
 Halal Logistics Market | 2026-2036
Halal Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Halal Logistics Market Intelligence
Asset-light leasing models for temperature-controlled halal-certified warehouses is rewriting competitive entry barriers for mid-sized logistics providers. TASCO Berhad leverages its Malaysian port-linked cold storage network to anchor Southeast Asian halal distribution. Nippon Express Holdings sustains integrated rail-sea corridors across Central Asia and the Middle East. DB Schenker differentiates through proprietary digital halal chain-of-custody tracking systems.
Halal logistics encompasses the end-to-end movement, storage, and handling of goods compliant with Islamic dietary and ethical standards, requiring segregation from non-halal products, temperature integrity for perishables, and auditable chain-of-custody documentation. Its primary commercial purpose is to guarantee religious compliance for Muslim consumers while enabling manufacturers to access Organization of Islamic Cooperation markets exceeding one billion people. Transportation services dominate value capture due to fuel, fleet certification, and route optimization costs, while warehousing exhibits the fastest structural expansion as e-commerce platforms demand last-mile halal-compliant fulfillment nodes. Certification level segmentation reveals margin concentration at the fully certified tier, where audit costs and facility segregation create defensible supplier positions.
Malaysia's Department of Islamic Development (JAKIM) and Indonesia's Halal Product Assurance Agency (BPJPH) now mandate domestic halal certification for imported food and cosmetics, directly shaping cross-border logistics infrastructure investment. The Gulf Standards Organization and Saudi Food and Drug Authority enforce parallel but non-identical requirements, fragmenting compliance architecture across Middle Eastern entry points. Stakeholders must monitor whether emerging African Muslim markets adopt GCC-aligned or ASEAN-aligned certification frameworks to determine hub-and-spoke network configuration.
Market Dynamics
Certification fragmentation between Malaysia's JAKIM and Indonesia's BPJPH is forcing logistics operators to maintain parallel compliance architectures, inflating facility costs and reshaping network design across Southeast Asia's halal trade corridors.
Growth Catalysts
- Pharmaceutical cold-chain mandates:Muslim-majority markets now require temperature-verified halal handling for vaccines and biologics, creating specialized demand for certified 2-8°C distribution infrastructure.
- E-commerce fulfillment node expansion:Indonesia's Java corridor is attracting warehousing investment as platforms build last-mile halal-compliant inventory positioning.
- BPJPH import certification requirements:Indonesia's 2024 mandate for domestic halal certification on inbound food and cosmetics is accelerating cross-border logistics restructuring.
Market Restraints
- Dual certification cost burden:Operators serving both ASEAN and GCC markets must maintain separate audit trails for JAKIM and Saudi Food and Drug Authority standards, duplicating facility segregation investments.
- Refrigerant price volatility:Cold-chain halal warehouses face input cost pressure from hydrofluorocarbon phase-down schedules under the Kigali Amendment.
- Port infrastructure concentration:Indonesia's reliance on Tanjung Priok and Surabaya for halal-certified container handling creates single-point vulnerability in the Java corridor.
Strategic Opportunities
- Central Asian rail-sea corridors:Landbridge routes connecting China to Turkey via Kazakhstan and Azerbaijan offer halal-certified alternatives to congested maritime chokepoints.
- African market framework adoption:Nigeria and Egypt's pending alignment with either GCC or ASEAN certification standards will determine hub location for continental distribution.
- Blockchain-IoT convergence:Immutable temperature and custody records from sensor networks integrated with distributed ledgers can automate compliance documentation for multi-jurisdiction shipments.
Industry Challenges
- Halal auditor scarcity:JAKIM and BPJPH-certified inspectors remain insufficient relative to facility expansion timelines, creating certification backlogs.
- Legacy warehouse retrofit costs:Converting ambient facilities to halal-segregated cold storage requires physical barriers, separate HVAC systems, and prayer facility installations that compress project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halal Logistics Market |
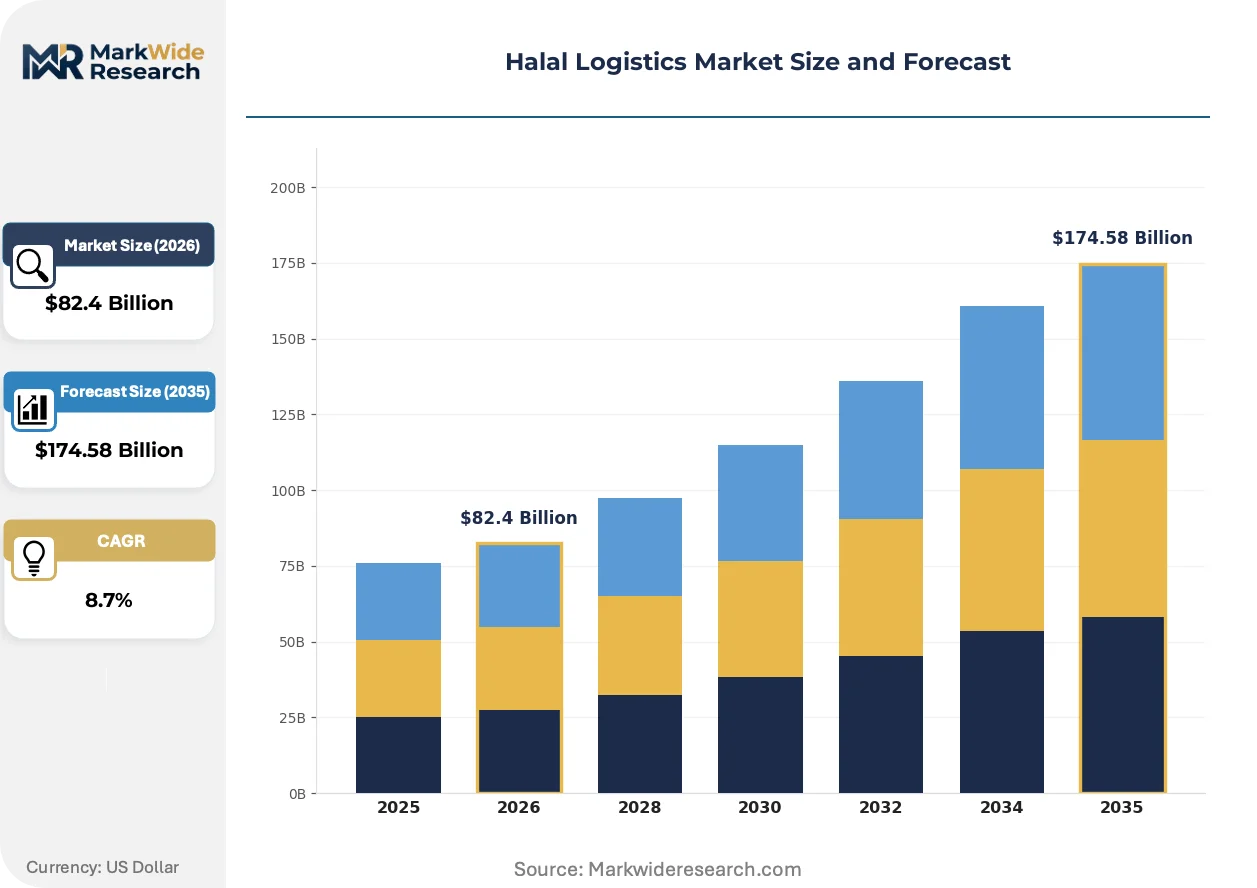
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $174.58 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Distribution End User: Food Manufacturers, Retail Chains, E-commerce Platforms, Wholesalers Certification Level: Certified, Partially Certified, Non-Certified, Proprietary Product Type: Frozen Foods, Packaged Goods, Fresh Produce, Beverages |
| Companies Covered | TASCO Berhad, Northport (Malaysia) BHD, Nippon Express Holdings, Sejung Shipping CO Ltd, HAVI Logistics, DB Schenker, Al Furqan Shipping & Logistics LLC, Kontena Nasional BHD (KNB), Yusen Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halal Logistics Market Strategic Shifts & Innovations
Digital chain-of-custody systems are displacing paper-based halal documentation, while certification bodies accelerate mutual recognition negotiations to reduce compliance duplication costs.
Blockchain-based halal traceability platforms are virtualizing the audit function by creating immutable records of product segregation, temperature exposure, and handler identity. Major Indonesian poultry processors and Malaysian palm oil exporters are piloting these systems to preempt BPJPH and JAKIM documentation requests. This virtualization is compressing certification verification timelines from weeks to hours.
Indonesia's BPJPH has accelerated mandatory halal certification timelines for food imports, with full enforcement now applying to categories previously under voluntary compliance. The regulation is forcing foreign manufacturers to pre-certify production facilities or face port detention. European dairy and cosmetic exporters are responding by establishing dedicated halal production lines ahead of shipment.
Buyer procurement patterns are fragmenting as mid-sized halal food brands bypass traditional distributors to contract directly with certified 3PL operators. This disintermediation is most visible in Malaysia's Klang Valley, where specialty halal logistics providers now handle end-to-end fulfillment for e-commerce-native brands that previously relied on conventional wholesale channels.
Halal Logistics Market Segmentation
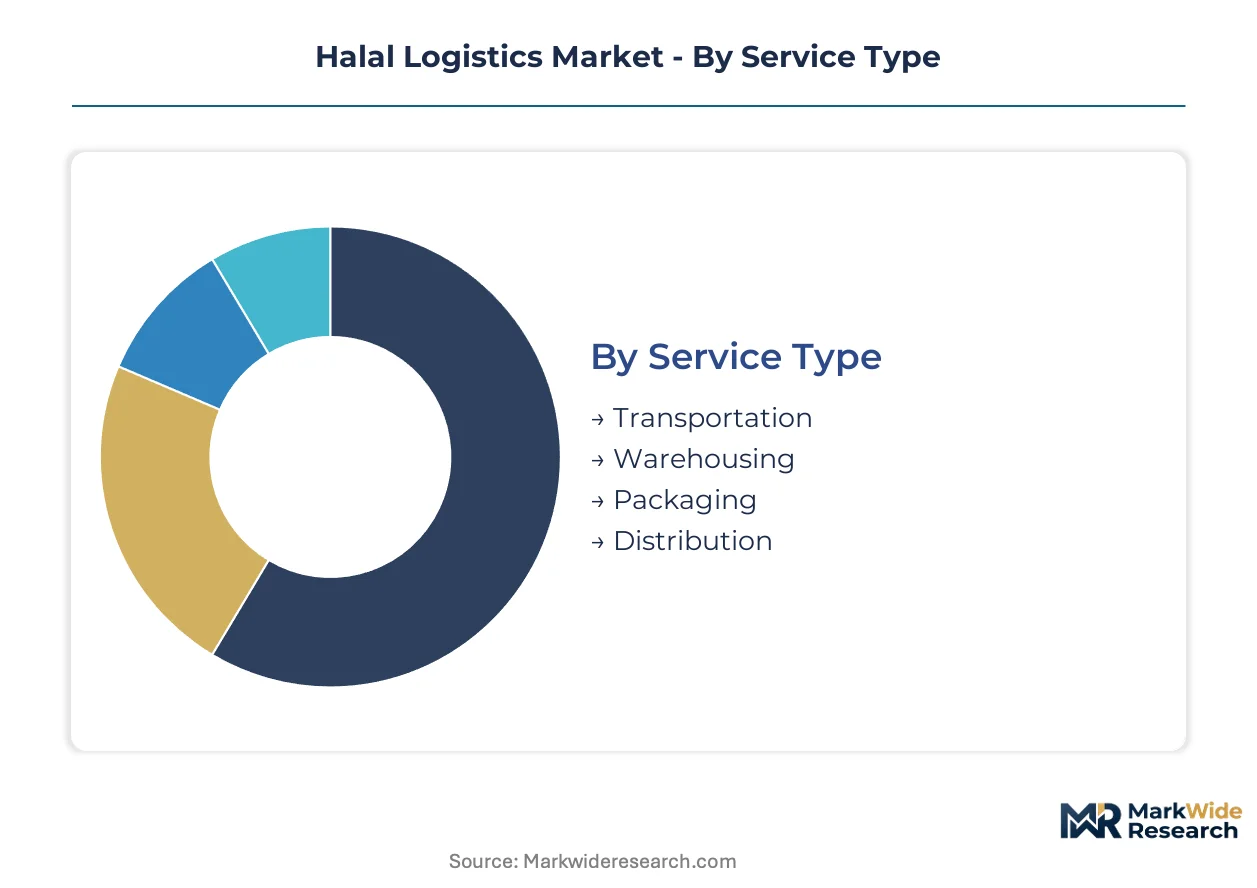
Halal logistics operators configure service portfolios around certification tier, product temperature sensitivity, and end-user fulfillment velocity. Segmentation discipline determines facility investment priority and margin capture across Southeast Asia's fragmented compliance landscape.
Service Type:
Cost tier differentiation separates asset-heavy cold storage from variable-cost transportation and value-added packaging services.
- Transportation:Fleet certification for halal-segregated cargo dominates capital deployment, with refrigerated trucks and container units requiring JAKIM or BPJPH handler training. Indonesian poultry processors and Malaysian palm oil exporters concentrate demand along the Java corridor and Klang Valley port links.
- Warehousing:Temperature-controlled facilities with physical segregation barriers and separate HVAC systems command premium lease rates. E-commerce platforms in Indonesia's urban clusters are driving fastest capacity absorption for last-mile fulfillment nodes.
- Packaging:Sharia-compliant material sourcing and contamination-proof sealing protocols serve pharmaceutical and cosmetic exporters facing Saudi Food and Drug Authority inspection.
- Distribution:Consolidated cross-dock operations merge halal-certified inbound flows with last-mile route optimization for retail chain replenishment.
Transportation holds installed capacity. Warehousing is rotating up the share rankings.
End User:
Application-based demand splits between bulk manufacturing supply chains and fragmented retail fulfillment networks.
- Food Manufacturers:Integrated production-to-port logistics for palm oil, processed meat, and dairy products require batch-level traceability documentation. Malaysian and Indonesian export-oriented processors anchor volume concentration.
- Retail Chains:Hypermarket and supermarket replenishment networks prioritize temperature integrity and rapid stock rotation over certification premium.
- E-commerce Platforms:Direct-to-consumer halal fulfillment demands micro-warehouse positioning within Indonesian urban corridors, with same-day delivery compressing inventory holding periods.
- Wholesalers:Traditional distribution intermediaries face margin compression as brands bypass tier-one logistics operators for certified 3PL contracts.
Food manufacturers retain volume leadership. E-commerce platforms are climbing the fastest.
Certification Level:
Margin concentration tracks audit stringency, with fully certified facilities capturing defensible positioning against compliance-lite competitors.
- Certified:Full JAKIM or BPJPH facility accreditation with segregated storage, dedicated handling protocols, and prayer facility provisions for Muslim staff. Pharmaceutical cold-chain mandates in Southeast Asia concentrate premium demand here.
- Partially Certified:Limited segregation zones or time-separated halal handling within shared facilities, serving lower-margin domestic distribution.
- Non-Certified:General logistics infrastructure without religious compliance protocols, excluded from Muslim-majority market access.
- Proprietary:Internal corporate standards maintained by integrated food manufacturers, bypassing third-party certification for captive supply chains.
Certified tier commands pricing power. Partially Certified is gaining share fastest among cost-constrained entrants.
Product Type:
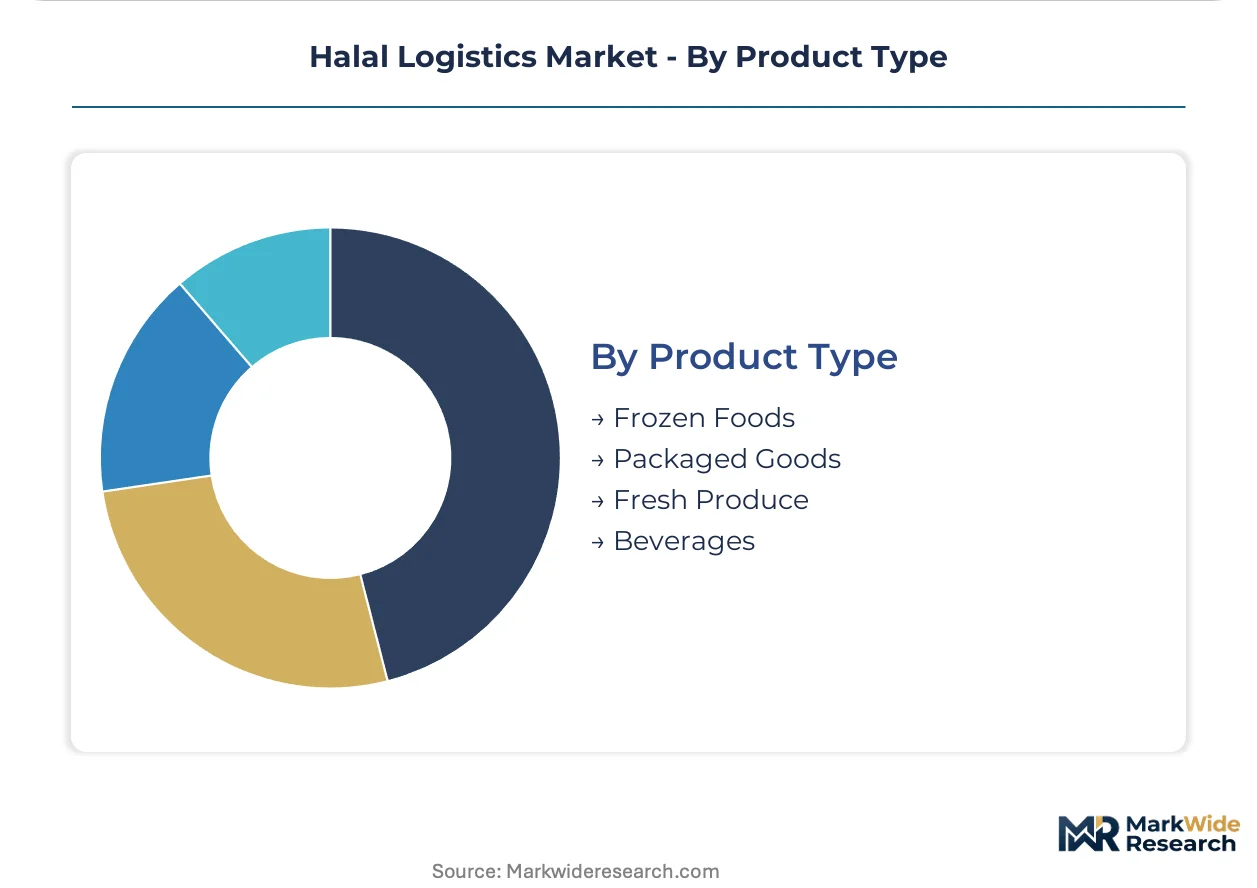
Temperature sensitivity and perishability windows determine infrastructure requirements across the product mix.
- Frozen Foods:Continuous cold-chain maintenance from production through retail display, with blast freezing and -18°C transport protocols. Indonesian processed poultry and Malaysian seafood exports drive corridor-specific capacity investment.
- Packaged Goods:Ambient-stable products requiring segregation integrity without temperature control, including confectionery and dry grocery items.
- Fresh Produce:Short shelf-life horticultural products demanding rapid throughput and controlled atmosphere handling, concentrated in Malaysia's vegetable export zones.
- Beverages:Liquid products with halal-certified ingredient verification and contamination-free bottling line logistics.
Frozen foods anchor refrigerated infrastructure deployment. Packaged goods are expanding most quickly on e-commerce velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances across Muslim-majority markets are restructuring logistics network investments, with inbound certification requirements now outpacing outbound infrastructure development in Southeast Asia.
Indonesia
BPJPH mandatory halal certification for food and cosmetics imports is accelerating cross-border restructuring. The agency's 2024 enforcement timeline forces European and Australian exporters to pre-certify facilities or face port detention. Tanjung Priok and Surabaya anchor Java corridor warehousing clusters serving domestic e-commerce fulfillment.
Malaysia
JAKIM facility accreditation standards command premium positioning for pharmaceutical cold-chain operators. The Department of Islamic Development mandates segregated storage, dedicated handling protocols, and prayer facilities for Muslim staff. Port-linked cold storage networks in Klang Valley concentrate distribution capacity for palm oil and processed meat exports.
Saudi Arabia
Saudi Food and Drug Authority parallel requirements fragment compliance architecture for operators serving both ASEAN and GCC markets. The Kingdom's pharmaceutical import growth drives demand for temperature-verified 2-8°C distribution infrastructure. Riyadh and Jeddah logistics zones handle increasing biologics and vaccine throughput.
United Arab Emirates
Dubai's position as re-export hub creates dual-certification cost pressures for logistics operators maintaining both JAKIM and GCC-aligned audit trails. Jebel Ali port infrastructure supports transshipment consolidation for African Muslim markets. Free zone warehousing clusters attract operators seeking compliance flexibility across certification frameworks.
Turkey
Central Asian rail-sea corridor development positions Turkish logistics operators as intermediaries between China and Middle Eastern markets. Landbridge routes via Kazakhstan and Azerbaijan offer halal-certified alternatives to congested maritime chokepoints. Istanbul logistics zones consolidate multi-jurisdiction shipments for European Muslim consumer markets.
Halal Logistics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in facility certification and fleet compliance. Market structure tilts toward consolidated port-linked operators with JAKIM and BPJPH dual accreditation, while mid-sized entrants pursue asset-light leasing models for temperature-controlled warehousing. Three archetypes dominate: integrated 3PL operators with proprietary digital tracking, port-authority-linked cold storage specialists, and rail-sea corridor integrators spanning Central Asia. Competitive moves concentrate on certification mutual recognition partnerships and micro-warehouse positioning in Indonesian urban corridors.
Within the integrated 3PL tier, TASCO Berhad and Nippon Express Holdings exemplify divergent geographic anchoring strategies. TASCO occupies a position tied to Malaysian port infrastructure, while Nippon Express represents rail-sea corridor integration across Central Asian and Middle Eastern routes. DB Schenker sits within the digital differentiation archetype, with proprietary chain-of-custody systems automating multi-jurisdiction compliance documentation. These three operators collectively illustrate how certification depth, geographic coverage, and technology investment define competitive positioning.
| Leading Market Players |
|---|
| TASCO Berhad |
| Northport (Malaysia) BHD |
| Nippon Express Holdings |
| Sejung Shipping CO Ltd |
| HAVI Logistics |
| DB Schenker |
| Al Furqan Shipping & Logistics LLC |
| Kontena Nasional BHD (KNB) |
| Yusen Logistics |
| Others |
Cost & Logistics Intelligence
Tanjung Priok's warehousing cluster concentration in North Jakarta anchors capacity premiums for halal-certified cold storage, translating port-linked facility scarcity into sustained pricing power for operators with dual JAKIM-BPJPH accreditation. Downstream buyers absorb cost pass-throughs unevenly across certification tiers, with pharmaceutical cold-chain mandates compressing price elasticity for temperature-verified handlers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with three-tier pricing stratification across fully certified, partially certified, and proprietary standard tiers. Price differentiation hinges on JAKIM/BPJPH audit depth and volume commitment scale, while pricing pressure stems from refrigerant cost volatility under Kigali Amendment phase-down schedules. Pharmaceutical manufacturers exhibit lowest price sensitivity; domestic food distributors face acute margin compression from certification surcharge stacking.
Supply Chain Analysis
Contract manufacturing concentration rests with integrated 3PL operators and port-authority-linked cold storage specialists, with facility ownership clustering in Malaysia, Indonesia, and the United Arab Emirates. Raw material dependencies span hydrofluorocarbon refrigerants, insulated paneling, and sensor hardware for temperature monitoring. Single-source vulnerability concentrates at Tanjung Priok and Surabaya container terminals. Distribution runs through hub-and-spoke networks anchored at Jebel Ali and Klang Valley for re-export consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Halal logistics incumbents face substitution pressure from blockchain-IoT traceability platforms that virtualize audit functions and compress third-party certification premiums into software margins.
For Market Incumbents: Pre-empt platform disintermediation by embedding proprietary digital chain-of-custody systems into customer contracts, locking in switching costs before sensor-network competitors achieve scale. Fortify position through backward integration into refrigerated fleet ownership, capturing fuel and handler certification margins that pure-play software entrants cannot replicate. Monitor BPJPH-JAKIM mutual recognition timelines as regulatory consolidation would obsolete dual-compliance infrastructure investments. For New Entrants and Emerging Players: Establish a beachhead in Indonesia's e-commerce micro-warehouse segment, where last-mile halal fulfillment nodes remain undersupplied relative to Java corridor demand velocity. Target asset-light leasing models for temperature-controlled facilities, bypassing capital-intensive port-linked cold storage dominated by incumbent scale. Lead with blockchain-IoT compliance documentation as a service differentiator to preempt traditional audit timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with installed JAKIM-BPJPH dual accreditation and proprietary digital tracking infrastructure, as certification backlogs create acquisition scarcity for audit-ready assets. Long-term viability hinges on exposure to pharmaceutical cold-chain mandates rather than commoditized food transport. Watch for African market framework alignment decisions as inflection signal for hub-location network value.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Mutual Recognition Partnership | BPJPH-JAKIM alignment would halve compliance duplication costs for cross-border operators. |
| Blockchain-IoT Platform Deployment | Immutable temperature records automate JAKIM documentation requests from Indonesian poultry processors. |
| Micro-Warehouse Network Expansion | Urban Indonesian fulfillment nodes capture e-commerce velocity away from traditional wholesale channels. |
| Central Asian Rail-Sea Corridor Investment | Kazakhstan-Azerbaijan routes offer halal-certified alternatives to congested maritime chokepoints. |
| Pharmaceutical Cold-Chain Certification | SFDA-mandated 2-8°C infrastructure commands premium positioning in Saudi biologics distribution. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs/trade data, BPJPH regulatory filings, JAKIM facility accreditation registries, and SEC disclosures from listed logistics operators. Interviews with cold storage facility managers, pharmaceutical supply chain directors, e-commerce fulfillment planners, and halal certification auditors informed demand-side validation. Bottom-up capacity modeling across Indonesian port zones and top-down trade flow analysis triangulate market sizing.
Forecast inputs incorporate certification tier penetration rates, temperature-controlled warehousing absorption velocity, and pharmaceutical cold-chain mandate expansion across Muslim-majority markets. Segmentation dimensions span service type, end-user application, certification level, and product temperature sensitivity. CAGRs derive from installed base growth adjusted for facility retrofit timelines and auditor scarcity constraints. Refrigerant phase-down schedules and BPJPH enforcement timelines feed scenario-weighted projections.
Macroeconomic conditions sit as an overlay; deviation in Indonesian rupiah volatility, GCC energy subsidy regimes, or Central Asian transit tariff structures would shift the trajectory. Forecasts reflect assumptions around certification mutual recognition progress and blockchain-IoT adoption curves. Quarterly review of BPJPH port detention rates and JAKIM auditor training pipeline indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific Container Drayage Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
South Africa Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Mexico Containerized Shipping Market
Logistics and Shipping
Czech Republic Third-Party Logistics Market
Logistics and Shipping
Morocco Freight and Logistics Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
China Cold Chain Logistics Market
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
Egypt Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
Express Delivery Market