
 Online Bus Ticketing Service Market | 2026-2036
Online Bus Ticketing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Online Bus Ticketing Service Market Analysis
India's aggregator ecosystem is restructuring how bus inventory reaches passengers. Redbus Online Private Limited dominates the subcontinent's fragmented operator base through proprietary seat-lock APIs. FlixMobility GmbH extends its European rail-bus multimodal stack into North American corridors. AbhiBus Marketing Private Limited anchors South India's tier-two city coverage with direct operator contracts.
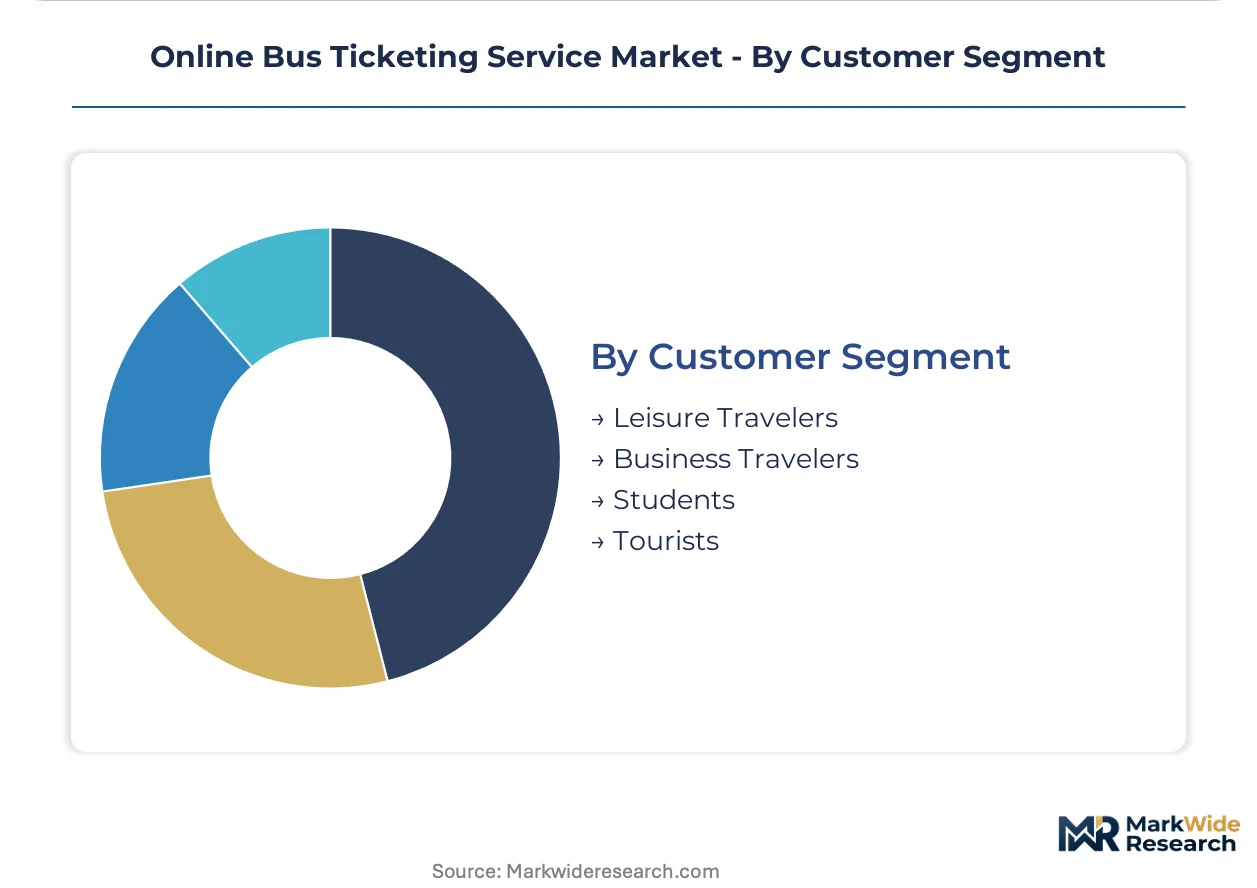
An online bus ticketing service is a digital intermediary platform that connects passengers with bus operators through real-time inventory APIs, dynamic seat maps, and automated confirmation protocols, primarily serving to eliminate counter queues and cash handling for scheduled intercity ground transport. The service type dimension shows one-way bookings sustaining volume leadership while multi-city itineraries capture rising margin pools from backpacker and corporate segments. Mobile wallet payment methods now outpace credit card flows across Southeast Asian and African corridors where banking infrastructure lags smartphone adoption. Leisure travelers occupy the largest customer segment, though business travelers generate superior per-trip yields through flexible ticket attachments.
India's Ministry of Electronics and Information Technology enforces bus API interoperability standards under its digital public infrastructure mandate, while the EU's GDPR frameworks shape how European platforms store cross-border passenger manifests. The US Department of Transportation's on-time performance disclosure rules indirectly pressure platforms to verify operator reliability data. Stakeholders must monitor whether India's BIS certification requirements for payment gateways fragment platform access across state-level transport corporations.
Market Dynamics
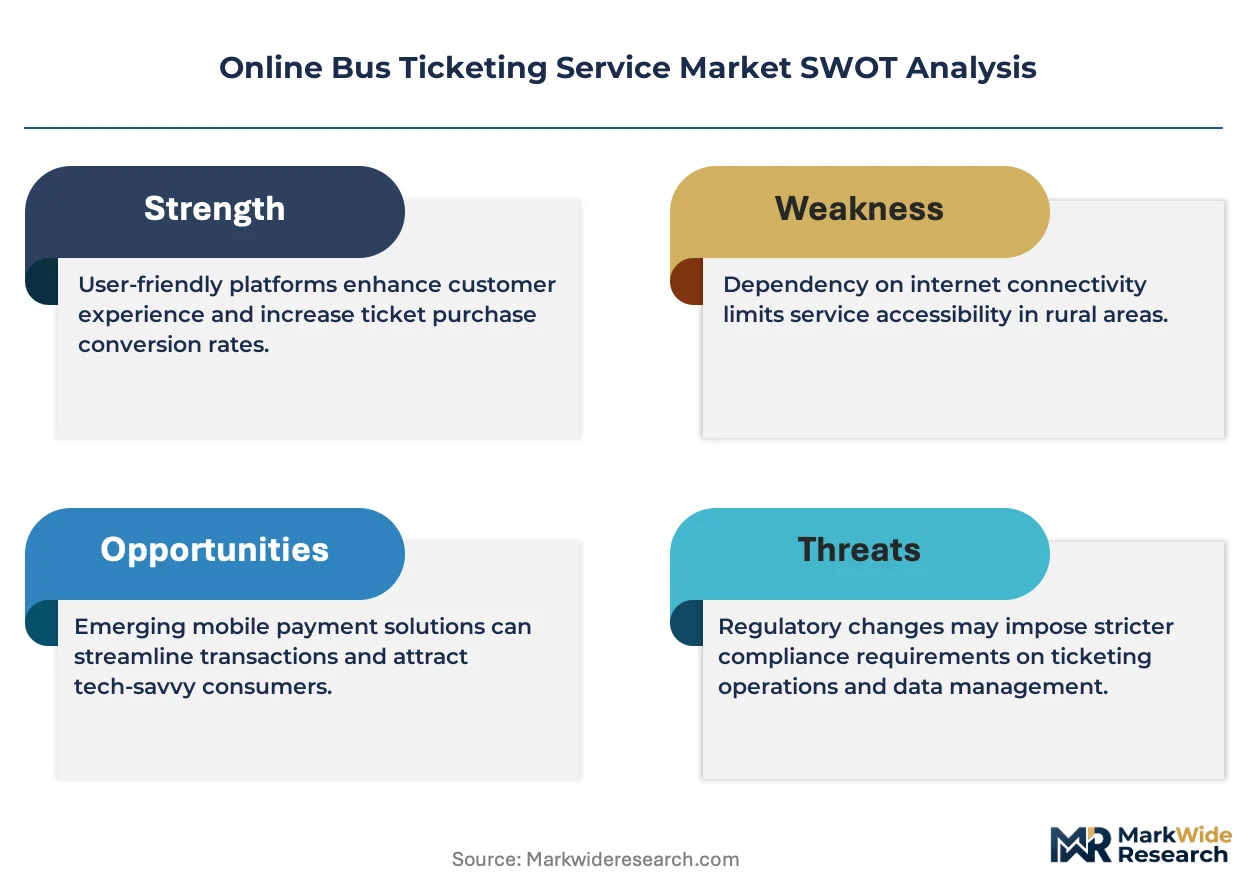
API standardization across India's state transport corporations is forcing platform consolidation, as operators abandon fragmented booking systems for unified digital infrastructure under the PLI scheme.
Growth Catalysts
- Mobile wallet penetration:Southeast Asian corridors with limited card infrastructure now process majority payments through GrabPay, Dana, and similar wallets, eliminating cash handling friction for intercity routes.
- India's PLI scheme for digital infrastructure:Production-linked incentives accelerate API interoperability mandates, compelling state bus corporations to adopt standardized booking protocols.
- Corporate travel manager adoption:Group booking tools with dynamic seat maps and consolidated invoicing draw enterprise travel spend away from offline agent networks.
Market Restraints
- Operator fragmentation in India:Thousands of private bus owners with non-standard fleet management systems resist platform integration, creating inventory visibility gaps.
- Payment gateway certification delays:India's BIS requirements for cybersecurity standards slow platform onboarding across state-level transport corporations.
- Rail substitution on premium corridors:High-speed rail expansion in Vietnam and Thailand absorbs price-insensitive business travelers from overnight bus routes.
Strategic Opportunities
- African mobile-first corridors:Kenya, Nigeria, and Ghana present white space where smartphone penetration exceeds formal banking access, favoring wallet-integrated bus platforms.
- Multimodal itinerary bundling:Convergence of bus APIs with ride-hailing and short-haul aviation systems enables end-to-end journey planning with single-checkout convenience.
- EU GDPR-aligned data trusts:Passenger manifest standardization creates exportable compliance frameworks for platforms entering European cross-border routes.
Industry Challenges
- Legacy reservation system integration:State-owned operators in India and Indonesia maintain decades-old mainframe infrastructure requiring costly middleware development for real-time seat locking.
- Driver verification and safety certification:Platform liability for operator compliance with commercial licensing and vehicle fitness standards demands expanded legal and audit functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Bus Ticketing Service Market |
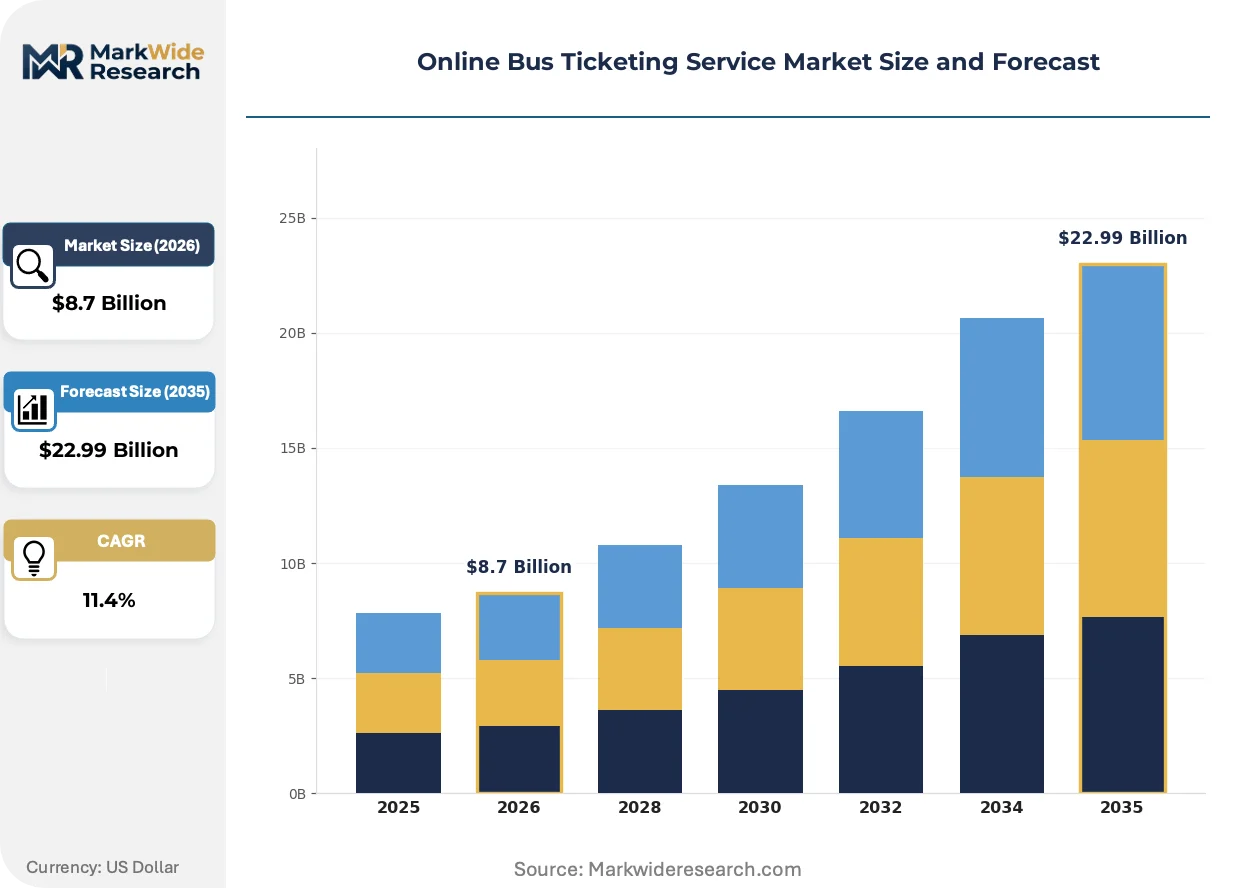
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: One-Way, Round Trip, Multi-City, Charter Ticket Type: Standard, Premium, Flexible, Non-Refundable Payment Method: Credit Card, Debit Card, Mobile Wallet, Bank Transfer Customer Segment: Leisure Travelers, Business Travelers, Students, Tourists |
| Companies Covered | Omio International GmbH, National Express Group PLC, FlixMobility GmbH, Easybook.com Pte. Ltd., Greyhound Lines, Inc., Redbus Online Private Limited, Wanderu Inc., AbhiBus Marketing Private Limited, Busbud Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Bus Ticketing Service Market Emerging Trajectories
Real-time inventory synchronization and dynamic pricing engines are compressing the gap between bus operator yield management and airline-style revenue optimization.
Dynamic seat map APIs with machine learning-based demand forecasting are automating price adjustments across India's intercity routes. Tier-two and tier-three operators adopting these tools now match revenue per kilometer previously reserved for premium fleet owners. The technology is automating yield management decisions that previously required manual intervention by dispatch managers.
India's Ministry of Electronics and Information Technology enforces bus API interoperability standards under its digital public infrastructure mandate. State transport corporations must expose real-time inventory through certified gateways or risk exclusion from aggregator platforms. Southern Indian states with earlier compliance deadlines now dominate platform inventory share.
Corporate procurement teams now mandate consolidated travel spend reporting with carbon footprint attribution. This behavioral shift compresses the addressable market for offline agents who cannot produce granular emissions data per journey. European corporate travel managers lead this requirement, extending the pattern into Southeast Asian supplier selection criteria.
Online Bus Ticketing Service Market Segmentation
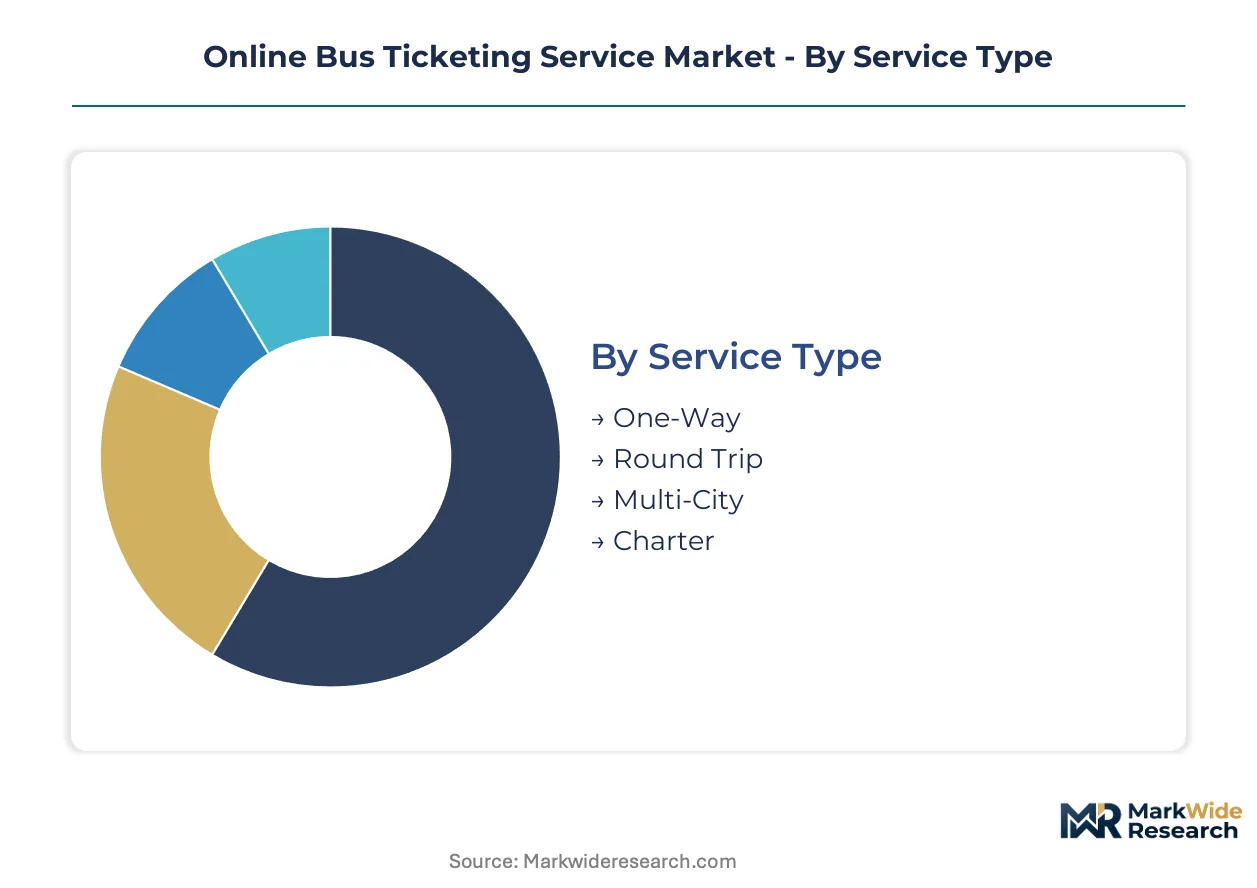
Online bus ticketing platforms segment their offerings across booking modalities, fare structures, payment rails, and traveler profiles to capture divergent willingness-to-pay and trip planning behaviors. Each dimension shapes platform technology investments and operator contract terms.
Service Type:
One-way bookings dominate transaction volumes while multi-city and charter services command premium positioning through itinerary complexity.
- One-Way:Single-leg bookings between origin-destination pairs constitute the core transaction engine for intercity aggregators. Indian state transport corporations and Indonesian private operators route the majority of their digital inventory through this format, driven by commuter and occasional traveler demand.
- Round Trip:Return-journey packaging reduces per-booking customer acquisition costs and locks in passenger commitment across both legs. Southeast Asian platforms leverage this format for weekend leisure corridors connecting Bangkok, Ho Chi Minh City, and Jakarta to surrounding provinces.
- Multi-City:Backpacker segments and corporate procurement teams utilize sequential leg booking for extended regional circuits. This format demands sophisticated API orchestration across multiple operators.
- Charter:Dedicated vehicle reservation for groups, events, and institutional transport. Direct operator contracts bypass standard inventory pools.
Mature deployment sits with One-Way. Newer deployment is concentrated in Charter as platforms build enterprise sales capabilities.
Ticket Type:
Fare flexibility tiers separate price-sensitive discretionary travelers from yield-generating business segments requiring cancellation rights.
- Standard:Fixed-fare inventory with limited modification rights anchors platform volume. Indian aggregators source this tier through bulk inventory agreements with state road transport undertakings.
- Premium:Enhanced seat selection, priority boarding, and bundled amenities capture superior yields on overnight routes. European platforms extend this tier through FlixMobility's sleeper bus configurations.
- Flexible:Full or partial refundability with change rights attracts corporate travel managers managing uncertain itineraries. This tier climbs fastest as procurement policies mandate cancellation protection.
- Non-Refundable:Deeply discounted inventory with absolute commitment terms fills marginal capacity. African corridors with high no-show rates utilize this tier to secure advance revenue.
Standard inventory commands platform attention through volume concentration. Flexible ticketing gains share fastest as enterprise procurement policies harden.
Payment Method:
Payment rail selection reflects banking infrastructure maturity and smartphone penetration across operating geographies.
- Credit Card:Revolving credit instruments dominate North American and European transactions where card acceptance infrastructure is universal. Corporate travel programs mandate card-based spend tracking.
- Debit Card:Direct bank account debiting prevails in markets with strong checking account penetration but limited credit card issuance. German and Dutch corridors show elevated debit preference.
- Mobile Wallet:Smartphone-based stored value systems including GrabPay, Dana, and M-Pesa process majority flows across Southeast Asia and East Africa where formal banking lags device ownership. This rail is expanding most quickly as platform integrations deepen.
- Bank Transfer:Real-time or batch account-to-account settlement serves B2B group bookings and institutional procurement with invoice reconciliation requirements.
Card rails anchor established markets. Mobile wallet deployment concentrates in African and Southeast Asian corridors with infrastructure gaps.
Customer Segment:
Traveler category determines booking frequency, price sensitivity, and ancillary attachment rates.
- Leisure Travelers:Discretionary vacation and family visit bookings generate the largest addressable population. Indian platforms capture this segment through festival-season inventory surges and pilgrimage route specialization.
- Business Travelers:Corporate-sponsored intercity movement commands superior per-trip yields through flexible fare attachment and last-minute booking patterns. European travel managers consolidate this spend through negotiated platform contracts.
- Students:Educational institution affiliations drive volume through semester-cycle predictability. Discounted fare programs with identity verification requirements lock in this cohort.
- Tourists:International visitors unfamiliar with local operator brands rely on aggregator platforms for route discovery and multilingual interface support.
Leisure concentration defines platform marketing investment. Business traveler deployment is concentrating as corporate sourcing policies mandate digital booking compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smartphone penetration rates across Southeast Asian corridors now exceed formal banking infrastructure, anchoring mobile wallet adoption for intercity ground transport bookings.
India
State transport corporations in Maharashtra and Karnataka drive digitization through API interoperability mandates under the PLI scheme. BIS certification requirements for payment gateways create compliance bottlenecks for platform onboarding. The Delhi-NCR cluster concentrates aggregator headquarters activity, with Redbus Online Private Limited and AbhiBus Marketing Private Limited operating national inventory networks from this base.
Indonesia
Island-hopping intercity routes across Java and Sumatra generate substantial booking volumes through mobile-first platforms. The national transport ministry enforces real-time seat inventory exposure for licensed operators. Jakarta and Surabaya anchor the archipelago's digital bus ticketing infrastructure, with private operators migrating from manual dispatch systems to API-connected platforms.
Vietnam
Ho Chi Minh City to Hanoi overnight corridors sustain demand despite high-speed rail competition on premium segments. The Ministry of Transport mandates electronic ticketing integration for all licensed intercity operators. The Mekong Delta region shows accelerating smartphone-based booking adoption among rural-origin passengers traveling to industrial zones.
Kenya
M-Pesa wallet penetration enables cashless intercity bus payments across Nairobi-Mombasa and Nairobi-Kisumu corridors. The national transport regulator requires digital manifest submission for all licensed operators. The Nairobi metropolitan area concentrates platform development activity, with matatu and intercity bus fleets adopting real-time inventory systems.
Germany
FlixMobility GmbH anchors European multimodal bus-rail integration from its Munich operational base. GDPR frameworks shape passenger data handling protocols for cross-border route manifests. The Rhine-Ruhr and Berlin-Brandenburg corridors demonstrate highest adoption of flexible fare tiers with carbon footprint attribution for corporate travel accounts.
Online Bus Ticketing Service Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue mobile-first wallet integration and multimodal itinerary bundling. The vendor base concentrates around three strategic archetypes: pan-regional aggregators with proprietary API infrastructure, operator-owned direct booking platforms, and multimodal travel super-apps expanding into ground transport. Competitive dynamics center on M&A activity targeting niche route coverage and strategic partnerships with state transport corporations for exclusive inventory access.
Within the European-origin tier, FlixMobility GmbH and Omio International GmbH exemplify multimodal platform expansion, while National Express Group PLC occupies a position in operator-controlled digital distribution. Redbus Online Private Limited anchors the India-focused aggregator archetype with direct state corporation API integrations.
| Leading Market Players |
|---|
| Omio International GmbH |
| National Express Group PLC |
| FlixMobility GmbH |
| Easybook.com Pte. Ltd. |
| Greyhound Lines, Inc. |
| Redbus Online Private Limited |
| Wanderu Inc. |
| AbhiBus Marketing Private Limited |
| Busbud Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up aggregator platforms in India and Southeast Asia enforce pricing discipline through exclusive API contracts with state transport corporations, while supply chain consolidation around certified payment gateways creates cost barriers for unlicensed entrants seeking market access.
Pricing Analysis
Warranty and service bundling separates flexible fare tiers from non-refundable inventory, with cancellation protection and change rights commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects seat selection granularity, operator brand tier, and dynamic yield management automation. Cost compression in standard inventory is intensifying because bulk procurement agreements with state road transport undertakings squeeze per-seat margins. Leisure travelers exhibit highest price sensitivity, while corporate procurement teams prioritize flexible fare attachment over absolute fare minimization.
Supply Chain Analysis
Certification gating through India's BIS cybersecurity standards and EU GDPR-aligned data trusts fragments platform onboarding velocity. Supply concentration rests on India, Indonesia, and Vietnam for operator inventory aggregation, with Germany anchoring European multimodal integration. Raw material dependencies include real-time seat map APIs, payment gateway middleware, and legacy mainframe bridging software. Single-source vulnerability around state transport corporation exclusivity agreements creates inventory access risk. Distribution runs through mobile-first super-apps in Southeast Asia and direct-to-operator platforms in European corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where India's PLI scheme for digital infrastructure and BIS payment gateway certification create regulatory moats favoring incumbent platforms with established state corporation relationships.
For Market Incumbents: Acquire exclusive API integration contracts with state road transport undertakings to lock out competing aggregators. Consolidate tier-two and tier-three operator networks through direct seat-lock API deployments before emerging wallet-first entrants achieve interoperability. Vertical integration into dynamic pricing engines insulates yield management capabilities from SaaS vendor consolidation. For New Entrants and Emerging Players: The premium-to-economy price-point gap in African mobile-first corridors offers white-space entry where M-Pesa penetration exceeds formal banking infrastructure. Target Kenya, Nigeria, and Ghana for wallet-integrated platform launches with minimal legacy reservation system competition. Pursue charter and group booking enterprise sales as the most penetrable segment with direct operator contracting requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor API-certified mid-cap specialists in Southern Indian states with early PLI compliance deadlines and dominant platform inventory share. Long-term viability hinges on regulatory certification durability rather than user acquisition scale. Watch for BIS certification backlog resolution as inflection signal for platform onboarding velocity normalization.| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Certification | India's PLI scheme mandates standardized booking protocols for state transport corporation inventory access. |
| Mobile Wallet Integration | GrabPay and M-Pesa partnerships eliminate cash handling friction in Southeast Asian and East African corridors. |
| Multimodal Itinerary Bundling | Convergence with ride-hailing and short-haul aviation APIs enables single-checkout journey planning. |
| Dynamic Pricing Engine Deployment | Machine learning-based demand forecasting automates yield management for tier-two operators. |
| Corporate Procurement Compliance | Carbon footprint attribution tools satisfy European travel manager consolidated spend reporting requirements. |
Methodological Framework
Document review covered SEC filings of listed transport operators, EU regulatory frameworks, and Indian government PLI scheme documentation, complemented by interviews with aggregator platform executives, state transport corporation IT directors, mobile wallet providers, and corporate travel procurement managers. Secondary validation drew from customs data on payment gateway equipment imports, API standardization committee minutes, and bus operator fleet registration databases. Bottom-up transaction volume estimates triangulated against top-down digital payment flow aggregates.
Market sizing outputs segmented across service type, ticket flexibility tier, payment rail, and customer category dimensions, with additional modeling of API certification status by state transport corporation. CAGRs derived from smartphone penetration trajectories, mobile wallet adoption curves, and corporate travel policy digitization rates. Forecast inputs incorporated PLI scheme incentive disbursement timelines and high-speed rail corridor completion schedules affecting modal substitution.
Inputs from state transport corporation annual reports and platform transaction disclosures were available through the study window; gaps in private operator fleet utilization data introduce uncertainty bands around yield management automation adoption curves. Forecasts reflect assumptions on regulatory certification velocity and mobile wallet interoperability standardization. A model refresh is warranted upon material change in India's BIS payment gateway certification processing timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Asia Pacific Tourism Vehicle Rental Market
Transportation Services
Drayage Services Market
Transportation Services
Global Moto Taxi Service Market
Transportation Services
Scooter Rental Market
Transportation Services
MUV Rental Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Australia Taxi Market
Transportation Services
Europe Light Commercial Vehicle Rental Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
North America International Express Service Market
Transportation Services
Compact Road Sweepers Market
Transportation Services
Multispace Parking Meter Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
North America Vehicle Rental Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Philippines Car Rental Market