
 ELISA POT Assay Kits Market | 2026-2036
ELISA POT Assay Kits Market Size, Share, and Industry Trends Forecast 2026-2036
ELISA POT Assay Kits Market Foresight
A shortage of trained bioanalytical technicians is reorganizing how ELISA POT Assay Kits suppliers structure their support services and kit complexity. Thermo Fisher Scientific Inc. leverages its global distribution network to sustain instrument-integrated kit sales across toxicology labs. Bio-Rad Laboratories, Inc. anchors its position through specialized calibration standards that reduce operator error in potency testing workflows.
ELISA POT Assay Kits are enzyme-linked immunosorbent assay systems designed to quantify peptide opioid toxicity through antibody-antigen binding detection, typically achieving picogram-per-milliliter sensitivity thresholds in serum or plasma matrices. Their primary commercial purpose centers on pharmaceutical bioequivalence studies and forensic toxicology screening where precise opioid potency measurement determines safety margins. Sandwich ELISA formats dominate current revenue owing to superior specificity for complex peptide matrices, while Competitive ELISA configurations are gaining fastest adoption in high-throughput drug testing environments where assay speed outweighs absolute sensitivity. Academic Institutions represent a mature end-user channel with stable but slower growth, whereas Diagnostic Laboratories concentrate margin pools through long-term service contracts tied to regulatory compliance testing.
FDA bioanalytical guidance and EMA ICH Q2(R1) validation standards jointly shape kit performance requirements, forcing manufacturers to demonstrate cross-laboratory reproducibility before commercial placement. ISO 13485 quality management certification has become a baseline market-access filter for suppliers serving European and North American diagnostic chains. Stakeholders must monitor evolving DEA scheduling decisions for synthetic opioids, as these classifications directly expand or contract the addressable testing panel breadth that kit portfolios must cover.
Market Dynamics
FDA bioanalytical method validation guidance revisions are compressing kit sensitivity thresholds and forcing manufacturers to revalidate entire product portfolios. This regulatory compression is reshaping R&D allocation across the competitive landscape.
Growth Catalysts
- EMA ICH Q2(R1) Validation Standards:European pharmaceutical manufacturers are accelerating kit replacement cycles to meet harmonized reproducibility requirements for cross-laboratory studies.
- Forensic Toxicology Screening:Contract research organizations in the United States are scaling high-throughput infrastructure for synthetic opioid detection panels.
- Peptide Matrix Complexity:Sandwich ELISA formats are capturing expanded application scope in bioequivalence studies where antibody specificity determines safety margin precision.
Market Restraints
- Monoclonal Antibody Supply Concentration:Critical capture antibody production clusters in Chinese bioreactor facilities expose kit manufacturers to geopolitical supply interruption risk.
- ISO 13485 Certification Timeline:European diagnostic chains now require quality management certification as a baseline market-access filter, extending commercialization cycles by 12-18 months.
- LC-MS/MS Substitution Threat:Liquid chromatography-tandem mass spectrometry systems are displacing ELISA in reference laboratories where absolute quantification outweighs throughput speed.
Strategic Opportunities
- India CDSCO Pathway Expansion:The country's national pharmaceutical regulator is streamlining import licensing for validated bioanalytical kits, opening access to generic drug manufacturers conducting bioequivalence studies.
- Automated Liquid Handler Convergence:Integration with Tecan and Hamilton robotic platforms is creating instrument-locked kit ecosystems that reduce operator variability in potency testing workflows.
- DEA Scheduling Tailwinds:Synthetic opioid classification decisions directly expand addressable testing panel breadth that kit portfolios must cover.
Industry Challenges
- Bioanalytical Technician Scarcity:The shortage of trained operators is forcing suppliers to simplify kit complexity and expand field application scientist deployment.
- Cross-Laboratory Reproducibility Burden:Demonstrating inter-site precision for FDA bioanalytical guidance compliance consumes disproportionate validation resources relative to kit revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ELISA POT Assay Kits Market |
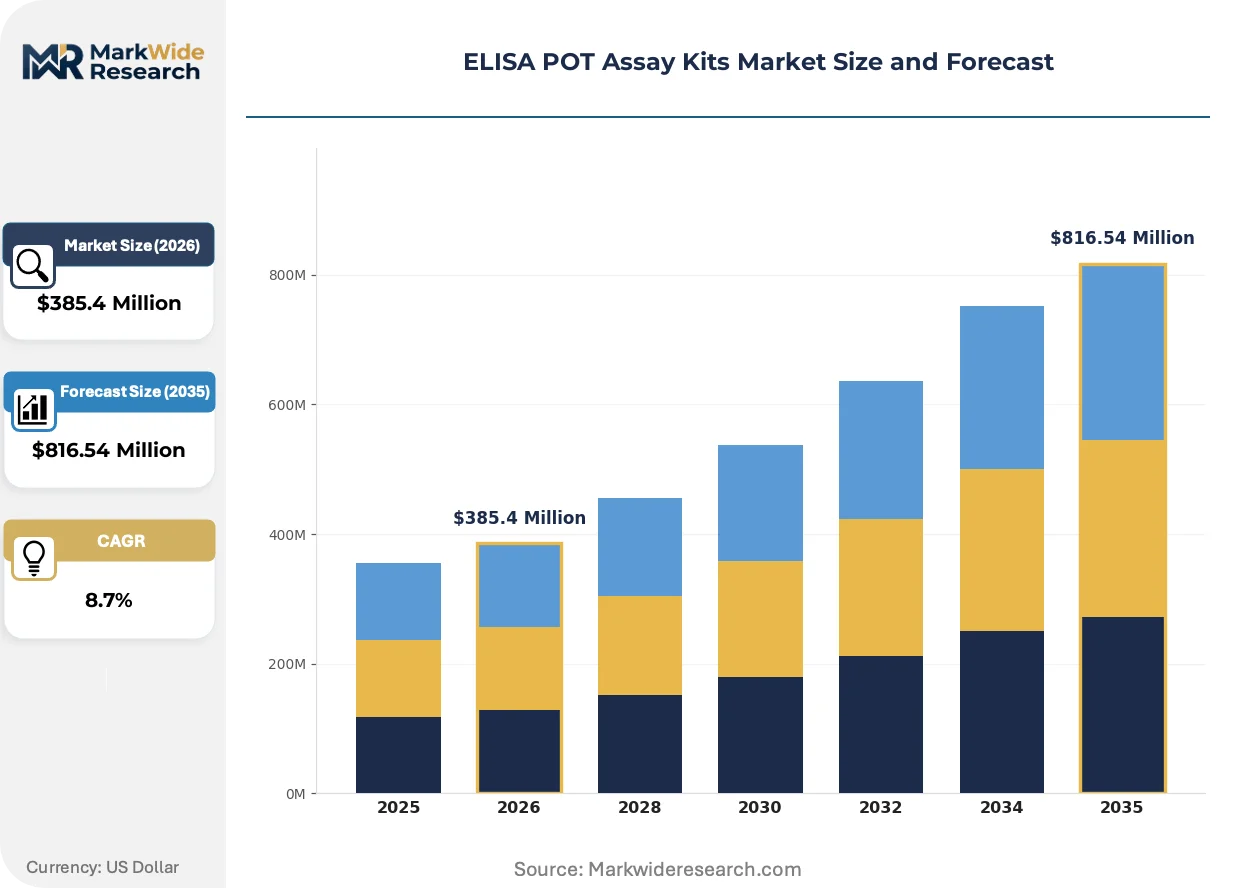
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sandwich ELISA, Competitive ELISA, Indirect ELISA, Direct ELISA Application: Clinical Diagnosis, Research, Quality Control, Drug Testing End User: Pharmaceutical Companies, Academic Institutions, Diagnostic Laboratories, Hospitals Packaging Type: Semi-Rigid Containers, Blister Packs, Multi-Pack Kits, Individual Vials |
| Companies Covered | Bio-Equip, antibodies-online GmbH, Genway Biotech, Inc., arigo Biolaboratories Corp, Elabscience, Inc., Thermo Fisher Scientific Inc., Bio-Rad Laboratories, Inc., Bio-Techne Corporation, Enzo Biochem, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ELISA POT Assay Kits Market Shifts & Advancements
Antibody engineering advances and detection chemistry improvements are fragmenting the traditional ELISA value proposition across multiple performance tiers. Kit manufacturers must now optimize for distinct use cases rather than universal platforms.
Multiplexed bead-based immunoassays are fragmenting the single-analyte ELISA market in pharmaceutical toxicology screening. Large CROs are adopting Luminex and Meso Scale Discovery platforms for simultaneous opioid panel quantification. This technology is fragmenting procurement decisions into specialized high-plex versus high-sensitivity workflow buckets.
REACH chemical registration requirements in Europe are forcing reformulation of horseradish peroxidase conjugate stabilizers and substrate buffers. Kit manufacturers are substituting synthetic enzyme stabilizers for traditional protein-based preservatives to maintain shelf-life claims. Diagnostic laboratories in Germany and France are prioritizing suppliers with completed substance registration dossiers.
Service contract unbundling is disrupting traditional reagent rental models in United States reference laboratories. Buyers are separating instrument maintenance from consumable supply agreements to optimize total cost of ownership. This pattern is most visible in regional hospital networks consolidating toxicology testing under centralized procurement committees.
ELISA POT Assay Kits Market Segmentation
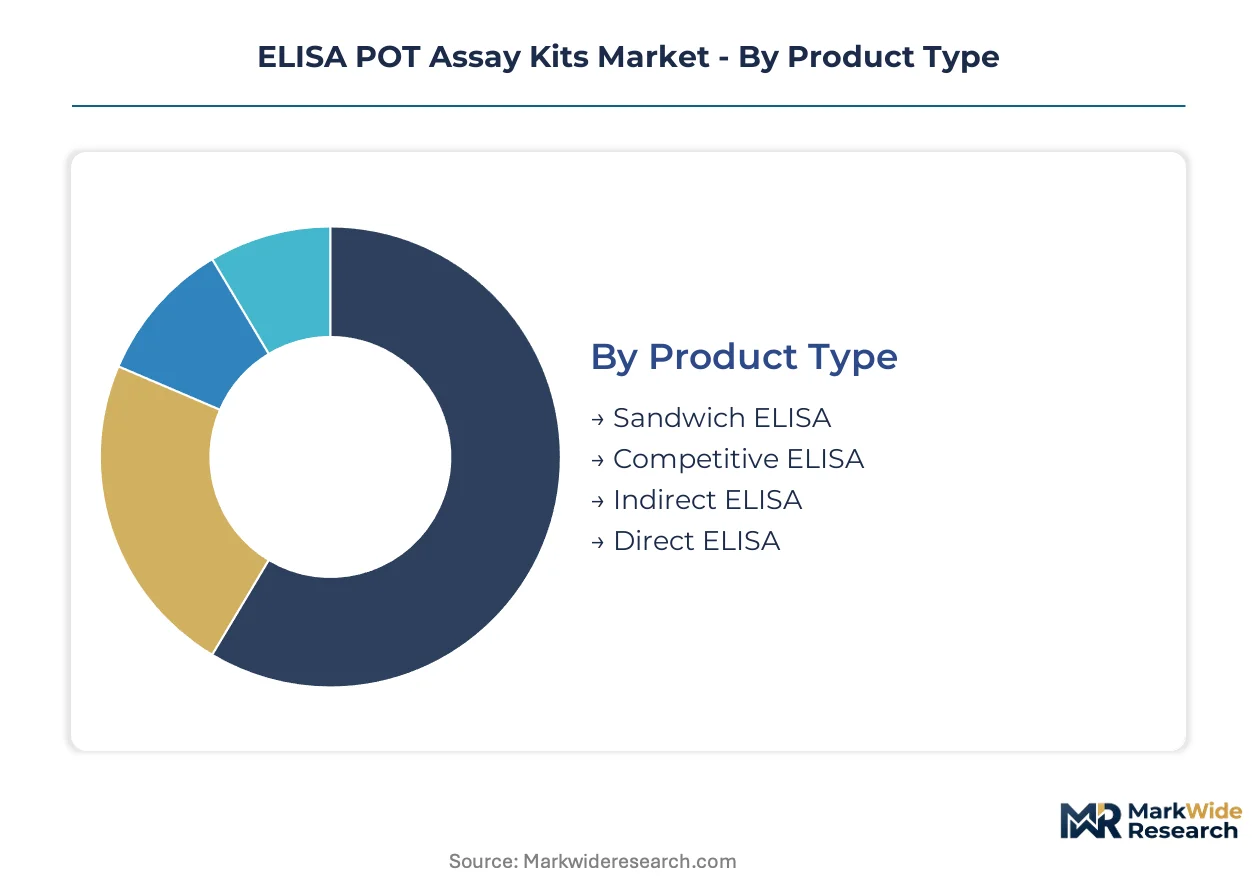
Segmentation in ELISA POT Assay Kits reveals divergent vulnerability profiles to LC-MS/MS substitution and automation-driven workflow consolidation. Manufacturers must calibrate portfolio depth against the technical specifications and procurement patterns of distinct user ecosystems.
Product Type:
Competitive ELISA formats face the most acute displacement pressure from liquid chromatography-tandem mass spectrometry systems in reference laboratories seeking absolute quantification precision.
- Sandwich ELISA:Dual-antibody capture architecture achieves picogram-per-milliliter sensitivity thresholds in complex peptide matrices. Pharmaceutical bioequivalence studies in the United States concentrate procurement around this format due to superior specificity for opioid potency determination.
- Competitive ELISA:Single-antibody competitive binding configuration prioritizes assay speed over absolute sensitivity. High-throughput drug testing environments favor this format where regulatory screening volume outweighs forensic-grade precision requirements.
- Indirect ELISA:Secondary antibody amplification step suits research applications with variable primary antibody sources.
- Direct ELISA:Simplified single-step detection reduces reagent costs for routine quality control workflows.
Sandwich ELISA anchors the volume base while Competitive ELISA gains share at the steepest rate.
Application:
Cost tier stratification separates premium-validated clinical applications from economy-grade research consumables.
- Clinical Diagnosis:FDA bioanalytical method validation guidance mandates cross-laboratory reproducibility documentation. Diagnostic chains in Germany prioritize suppliers with completed REACH substance registration dossiers for conjugate stabilizers.
- Drug Testing:Forensic toxicology panels require DEA-scheduled substance coverage breadth. Contract research organizations scale high-throughput infrastructure for synthetic opioid detection in the United States.
- Research:Academic laboratories tolerate higher inter-assay variability for experimental flexibility.
- Quality Control:Manufacturing release testing demands lot-to-lot consistency certification.
Clinical Diagnosis commands the margin pool while Drug Testing expands most quickly.
End User:
Customer type determines service intensity and kit complexity requirements.
- Diagnostic Laboratories:Long-term service contracts tied to regulatory compliance testing concentrate procurement decisions. Centralized hospital network committees in the United States unbundle instrument maintenance from consumable supply agreements.
- Pharmaceutical Companies:Toxicology screening program expansion drives instrument-integrated kit adoption. Bioequivalence study outsourcing creates demand for validated bioanalytical kits.
- Academic Institutions:Mature channel with stable but slower replacement cycles.
- Hospitals:Point-of-care constraints limit adoption to reference laboratory configurations.
Diagnostic Laboratories anchor the volume base while Pharmaceutical Companies climb the fastest.
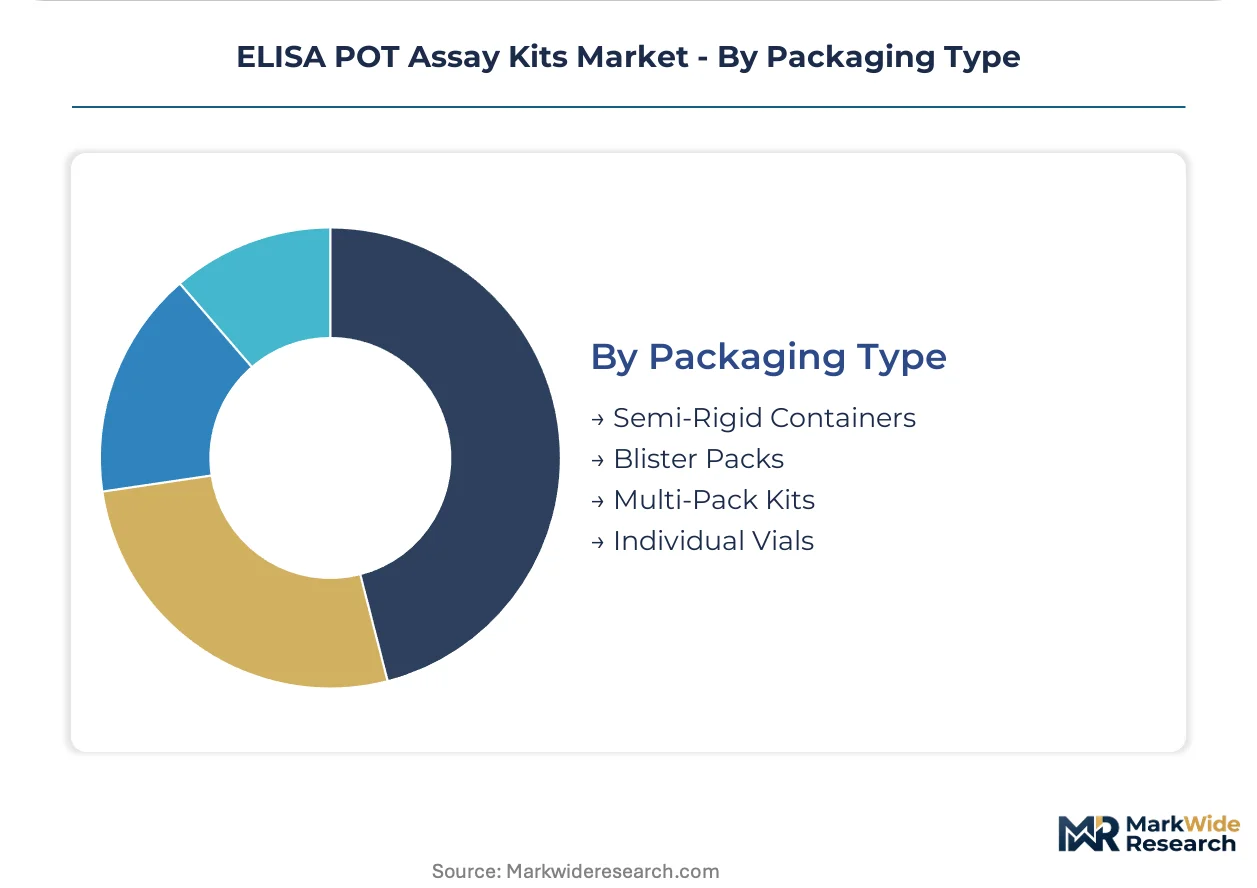
Packaging Type:
Supply chain configuration dictates packaging selection for shelf-life stability and cold-chain economics.
- Semi-Rigid Containers:Thermoformed polymer shells protect enzyme conjugate integrity through distribution. European diagnostic chains prioritize REACH-compliant stabilizer formulations.
- Multi-Pack Kits:Bulk configurations reduce per-assay cost for high-throughput screening operations.
- Blister Packs:Unit-dose presentation suits decentralized testing with variable demand patterns.
- Individual Vials:Lyophilized reagent format extends ambient stability for field deployment.
Semi-Rigid Containers anchor the volume base while Multi-Pack Kits gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. United States laboratories prioritize high-throughput automation for forensic toxicology screening, while European facilities emphasize REACH-compliant reagent formulations. Asian markets concentrate procurement around cost-efficient bioequivalence study kits for generic drug manufacturers.
United States
Contract research organizations in Massachusetts and North Carolina are scaling automated liquid handling infrastructure for synthetic opioid detection panels. FDA bioanalytical method validation guidance revisions are compressing kit sensitivity thresholds and forcing manufacturers to revalidate entire product portfolios. The Research Triangle Park cluster anchors high-throughput toxicology screening operations serving pharmaceutical clients nationwide.
Germany
Diagnostic chains in Bavaria and Baden-Württemberg prioritize suppliers with completed REACH substance registration dossiers for enzyme conjugate stabilizers. EMA ICH Q2(R1) validation standards are accelerating kit replacement cycles to meet harmonized reproducibility requirements for cross-laboratory studies. The Munich-Stuttgart corridor concentrates pharmaceutical bioequivalence study outsourcing demand.
China
Domestic bioreactor facilities in Shanghai and Suzhou supply critical monoclonal capture antibodies to international kit manufacturers. The country's national pharmaceutical regulator is streamlining import licensing pathways for validated bioanalytical kits serving generic drug manufacturers. Yangtze River Delta pharmaceutical clusters are expanding toxicology screening programs for export-oriented bioequivalence studies.
India
CDSCO is streamlining import licensing for validated bioanalytical kits, opening access to generic drug manufacturers conducting bioequivalence studies. Maharashtra and Gujarat-based pharmaceutical companies are expanding in-house toxicology screening capabilities to support ANDA submissions. The Hyderabad-Bangalore corridor anchors contract research organization growth for international bioequivalence study outsourcing.
United Kingdom
Academic institutions in Oxford and Cambridge tolerate higher inter-assay variability for experimental flexibility in peptide opioid toxicity research. MHRA alignment with EMA ICH Q2(R1) standards is shaping procurement criteria for diagnostic laboratories serving NHS reference networks. The Golden Triangle biotech cluster sustains stable but slower replacement cycles for research-grade assay kits.
ELISA POT Assay Kits Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the ELISA POT Assay Kits market. Thermo Fisher Scientific Inc. and Bio-Rad Laboratories, Inc. anchor the upper tier through instrument-integrated kit ecosystems and specialized calibration standards respectively. The middle tier fragments across antibody engineering specialists, detection chemistry innovators, and regional distribution-focused suppliers. Strategic moves concentrate on automated liquid handler convergence and geographic certification pathway expansion.
Within the integrated instrumentation tier, Thermo Fisher Scientific Inc. exemplifies scale-driven positioning through global distribution networks sustaining instrument-locked kit sales. Bio-Rad Laboratories, Inc. occupies a parallel position anchored through calibration standard specialization. Among antibody-focused specialists, antibodies-online GmbH represents the European distribution-centric archetype. These three companies illustrate the competitive structure: one American integrated leader, one American precision-focused incumbent, and one German specialist distributor.
| Leading Market Players |
|---|
| Bio-Equip |
| antibodies-online GmbH |
| Genway Biotech, Inc. |
| arigo Biolaboratories Corp |
| Elabscience, Inc. |
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories, Inc. |
| Bio-Techne Corporation |
| Enzo Biochem, Inc. |
| Others |
Supply & Pricing Matrix
Synthetic enzyme stabilizer substitution for traditional protein-based preservatives is simultaneously relocating formulation expertise toward REACH-compliant European suppliers and compressing margin structures for legacy preservative-dependent kit portfolios. This input transition redistributes pricing power toward manufacturers with completed substance registration dossiers while penalizing those dependent on unregistered Chinese bioreactor-sourced stabilizer intermediates.
Pricing Analysis
Long-term service contracts tied to regulatory compliance testing dominate procurement in diagnostic chains, with unbundling trends separating instrument maintenance from consumable supply agreements. Price differentiation separates ISO 13485-certified premium tiers from economy-grade research consumables, with certification timeline investments commanding 12-18 month commercialization premiums. Pricing pressure stems from LC-MS/MS substitution in reference laboratories where absolute quantification outweighs throughput economics. Academic institutions exhibit highest price sensitivity due to budget constraints, while pharmaceutical toxicology programs show lowest sensitivity given bioequivalence study regulatory imperatives.
Supply Chain Analysis
Port congestion on transpacific lanes elevates inbound logistics costs for lyophilized reagent shipments from Chinese bioreactor facilities to North American kit assembly plants. Monoclonal antibody production concentrates in China, Germany, and the United States, with critical capture antibody supply drawing from Shanghai and Suzhou manufacturing clusters. Single-source vulnerability in Chinese bioreactor capacity exposes kit manufacturers to geopolitical interruption risk. Distribution runs through Thermo Fisher's global logistics network and regional specialist distributors serving European diagnostic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as FDA bioanalytical guidance revisions force kit replacement cycles across pharmaceutical toxicology programs. Synthetic opioid scheduling decisions continue expanding addressable testing panel breadth faster than LC-MS/MS substitution can displace ELISA in high-throughput environments.
For Market Incumbents: Consolidate antibody engineering capabilities through captive supply arrangements with Chinese bioreactor facilities or backward integration into German specialist producers. Lock in diagnostic laboratory procurement through instrument-integrated kit ecosystems on Tecan and Hamilton robotic platforms. Priority lever rests on automated liquid handler convergence that reduces operator variability and raises switching costs. For New Entrants and Emerging Players: Lead with CDSCO-streamlined import licensing pathways serving Maharashtra and Gujarat generic drug manufacturers conducting bioequivalence studies. Target the India bioequivalence outsourcing corridor where validated kit demand outpaces domestic supply. Penetrate through antibody-specificity guarantees for complex peptide matrices that incumbent portfolios under-serve. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract research organizations scaling high-throughput toxicology infrastructure in the Research Triangle Park cluster. Five-to-ten year viability hinges on sustained pharmaceutical outsourcing of bioequivalence studies and forensic toxicology screening. Signal to watch: DEA scheduling velocity for novel synthetic opioids as direct panel expansion trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Liquid Handler Integration | Instrument-locked kit ecosystems on Tecan and Hamilton platforms reduce operator variability in potency testing workflows. |
| REACH Substance Registration Completion | Completed dossiers for enzyme conjugate stabilizers unlock Bavaria and Baden-Württemberg diagnostic chain procurement. |
| CDSCO Import Licensing Streamlining | Validated bioanalytical kit pathways open Maharashtra and Gujarat generic drug manufacturer bioequivalence study demand. |
| Monoclonal Antibody Supply Capturing | Backward integration into Shanghai and Suzhou bioreactor capacity mitigates geopolitical interruption risk for capture antibody inputs. |
| Multiplexed Bead-Based Immunoassay Development | Luminex and Meso Scale Discovery platform convergence addresses large CRO simultaneous opioid panel quantification requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA bioanalytical guidance documents, EMA ICH Q2(R1) validation standards, and CDSCO import licensing records. Interviews with bioanalytical laboratory directors, diagnostic procurement managers, pharmaceutical toxicology program leads, and contract research organization operations heads inform demand-side assumptions. Secondary validation draws from SEC 10-K filings of listed kit manufacturers, REACH substance registration databases, and DEA scheduling decision records. Bottom-up assay kit volume estimates triangulate against top-down pharmaceutical R&D spending allocation models.
Segmentation dimensions modeled include ELISA format architecture, application purpose, end-user category, and packaging configuration across the projection horizon. CAGRs derive from regression analysis of historical kit replacement cycles, regulatory compliance timeline impacts, and pharmaceutical toxicology program expansion rates. Forecast inputs incorporate synthetic opioid scheduling velocity, LC-MS/MS substitution penetration curves, and automation infrastructure deployment trajectories in United States contract research organizations.
Forecasts assume regulatory continuity in FDA bioanalytical method validation guidance, EMA ICH Q2(R1) standards, and CDSCO import licensing frameworks; material policy shifts would require re-modeling. Specific risk factors include DEA scheduling delays for novel synthetic opioids, REACH substance registration requirement expansions, and monoclonal antibody supply chain disruptions from Chinese bioreactor facility constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Global Photobiostimulation Devices Market
Biotechnology Equipment
Laboratory Andrology Equipment Market
Biotechnology Equipment
Global Lab Automation in Protein Engineering Market
Biotechnology Equipment
Global Large Molecule Bioanalytical Technologies Market
Biotechnology Equipment
Biosurgery Equipment Market
Biotechnology Equipment
Single Use Bioprocessing Market
Biotechnology Equipment
Airlift Bioreactors Market
Biotechnology Equipment
Separation Systems for Commercial Biotechnology Market
Biotechnology Equipment
Global Bioreactor Market
Biotechnology Equipment
Lab Scale Bioreactors Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
Lab Centrifuges Market
Biotechnology Equipment
Cell Disruption Market
Biotechnology Equipment
Low Endotoxin Gelatin Market