
 Biotechnology Instrumentation Market | 2026-2036
Biotechnology Instrumentation Market Size, Share, and Industry Trends Forecast 2026-2036
Biotechnology Instrumentation Market Outlook
Buyer concentration is shifting as pharmaceutical contract research organizations consolidate purchasing power while mid-sized biotechnology firms fragment demand across specialized vendors. Thermo Fisher Scientific leverages its chromatography and mass spectrometry breadth to anchor enterprise accounts. Danaher competes through integrated workflow automation that reduces manual sample handling. Illumina dominates next-generation sequencing instrumentation with proprietary consumable lock-in that extends customer lifetime value.
Biotechnology instrumentation comprises analytical and preparatory devices engineered to detect, quantify, separate, or cultivate biological molecules and cells, typically operating at detection thresholds of picograms per milliliter and temperature tolerances within 0.1 degrees Celsius for cell-based assays. These systems serve pharmaceutical development, clinical diagnostics, and academic research by converting biological signals into reproducible digital readouts. Spectrophotometers and chromatography systems lead product type revenue due to their ubiquity in quality control workflows across drug manufacturing facilities. Mass spectrometry technology commands premium positioning as proteomics and metabolomics applications expand in precision medicine pipelines. Drug discovery application demand outpaces genomics growth in absolute dollar terms, though genomics sustains higher instrument replacement frequency.
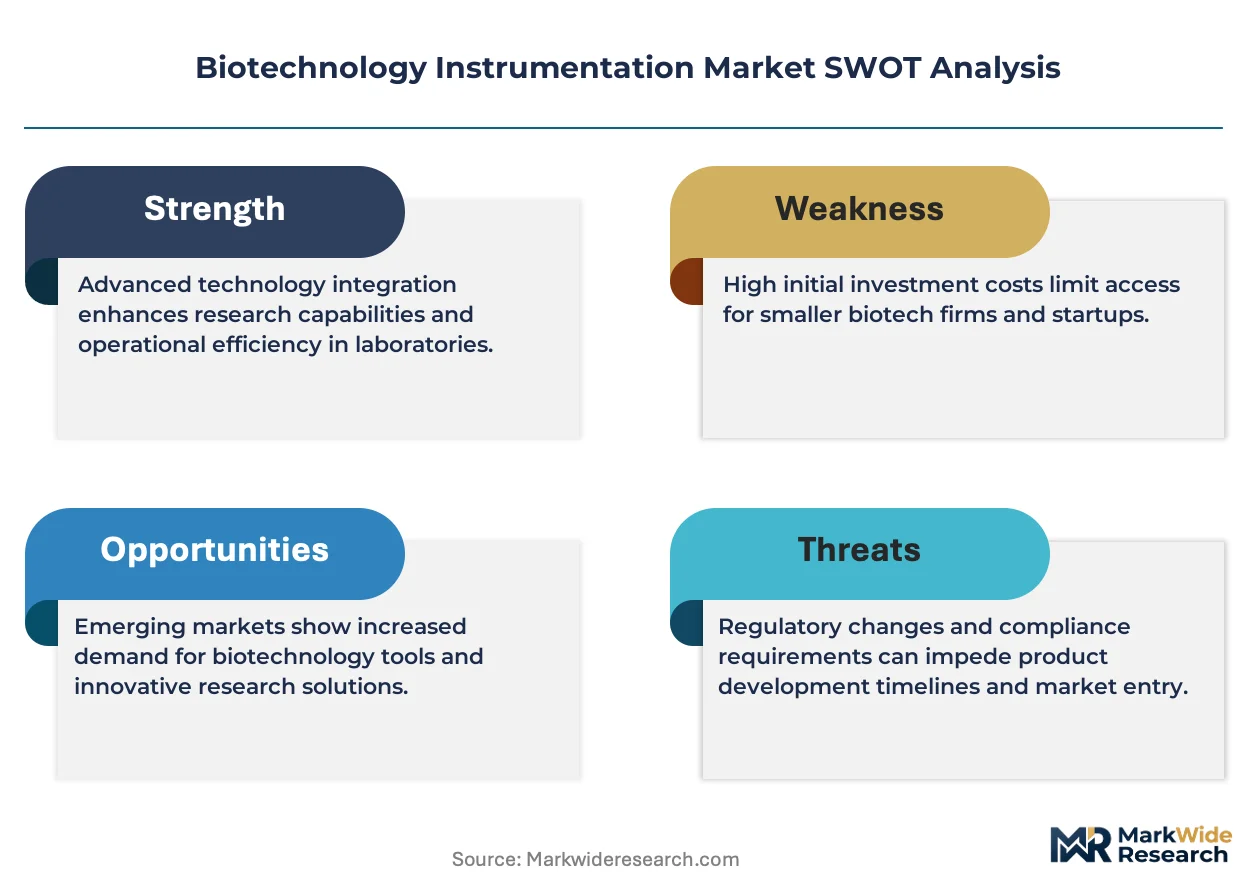
FDA 21 CFR Part 11 electronic records requirements and EMA GMP Annex 1 sterile manufacturing revisions compel instrument vendors to embed audit trails and environmental monitoring capabilities as standard features rather than optional modules. ISO 13485 quality management standards for in vitro diagnostic devices further constrain market access for manufacturers lacking certified production systems. Stakeholders must monitor how AI-enabled analytical software triggers new validation protocols from regulators before embedding machine learning into instrument control platforms.
Market Dynamics
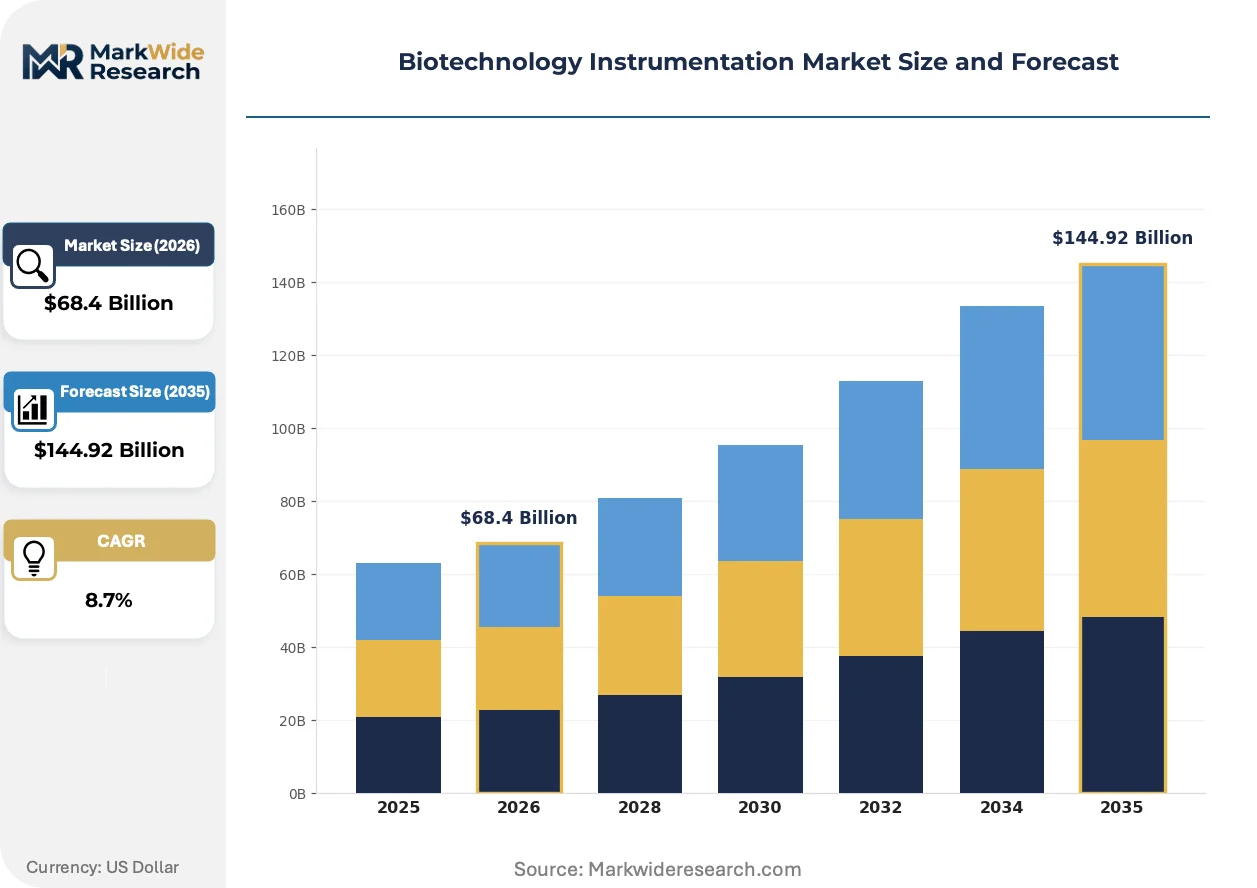
Pharmaceutical contract research organizations now consolidate purchasing power while FDA and EMA quality mandates for cell and gene therapy manufacturing compel facilities to upgrade analytical platforms, creating a bifurcated demand structure between enterprise-scale procurement and fragmented specialized needs.
Growth Catalysts
- EMA GMP Annex 1 revisions:Sterile manufacturing updates mandate environmental monitoring capabilities in analytical instruments, forcing facility upgrades across European biologics production sites.
- Biologics pipeline expansion:Contract research organizations scaling antibody and cell therapy programs drive chromatography and mass spectrometry procurement volumes.
- Precision medicine proteomics:Metabolomics applications in companion diagnostic development expand mass spectrometry deployment in clinical reference laboratories.
Market Restraints
- Helium supply volatility:Mass spectrometry systems depend on constrained noble gas supply chains concentrated in Qatar and the United States, creating input cost instability.
- ISO 13485 certification barriers:In vitro diagnostic instrument manufacturers face quality management system requirements that exclude uncertified production facilities from regulated markets.
- Consumable lock-in economics:Proprietary reagent and cartridge ecosystems create switching costs that fragment purchasing decisions across incompatible vendor platforms.
Strategic Opportunities
- AI-enabled analytical software:Machine learning integration into instrument control platforms creates validation protocol opportunities before regulators establish formal frameworks.
- India biologics manufacturing:CDSCO quality guidelines and PLI scheme incentives attract contract manufacturing investment, expanding instrument demand in Hyderabad and Bangalore clusters.
- Single-use chromatography systems:Pre-packed disposable columns reduce cross-contamination risk in multi-product biologics facilities, displacing traditional stainless-steel infrastructure.
Industry Challenges
- 21 CFR Part 11 validation timelines:Electronic records compliance requirements extend software deployment cycles, delaying instrument commissioning in FDA-regulated facilities.
- Multi-omics integration complexity:Combining genomics, proteomics, and metabolomics data streams requires specialized bioinformatics talent scarce in mid-sized biotechnology firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biotechnology Instrumentation Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spectrophotometers, Chromatography Systems, Incubators, Centrifuges Technology: ELISA, PCR, Mass Spectrometry, Cell Counters Application: Drug Discovery, Genomics, Proteomics, Quality Control End User: Pharmaceuticals, Academic Institutions, Research Labs, Biotechnology Firms |
| Companies Covered | Thermo Fisher Scientific, Danaher, Agilent Technologies, Waters Corporation, Shimadzu Corporation, Bio-Rad Laboratories, Illumina, PerkinElmer, Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biotechnology Instrumentation Market Strategic Shifts
Cloud-connected instrumentation and artificial intelligence integration are compressing analytical turnaround times while reshaping how biopharmaceutical facilities validate and deploy quality control systems across distributed manufacturing networks.
Benchtop mass spectrometry systems are decentralizing proteomics workflows from centralized core facilities into individual research laboratories and quality control stations. Mid-sized biotechnology firms in Boston and San Diego clusters now deploy these compact units for real-time batch release testing. This diffusion is compressing capital expenditure thresholds and fragmenting vendor account structures previously dominated by enterprise-scale installations.
EU AI Act risk classification frameworks are forcing instrument manufacturers to embed algorithmic transparency features into analytical software before European market entry. Automated decision-making systems in chromatography data processing now require documented training data provenance and human oversight protocols. Biologics manufacturers in Germany and Switzerland are prioritizing vendors with pre-validated compliance architectures to accelerate regulatory submissions.
Service unbundling is separating instrument hardware from validation, training, and maintenance contracts in pharmaceutical procurement. Contract research organizations now negotiate fractional field service agreements and remote diagnostic subscriptions rather than comprehensive coverage packages. This pattern concentrates in United States markets where specialized third-party service providers compete with original equipment manufacturer service networks.
Biotechnology Instrumentation Market Segmentation
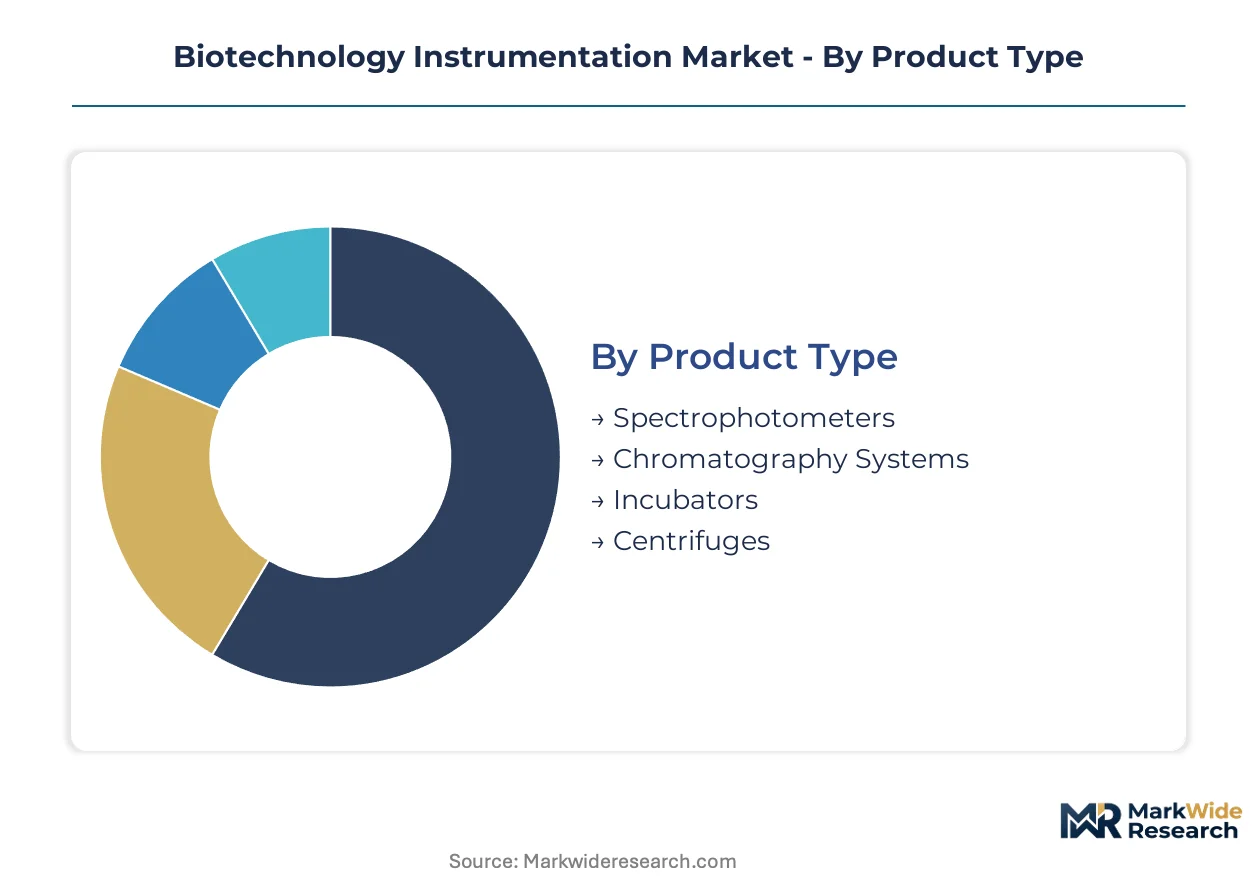
Segmentation in biotechnology instrumentation reveals how procurement patterns bifurcate between enterprise-scale standardization and specialized research requirements. Understanding these divisions exposes where vendor lock-in economics concentrate and where modular purchasing creates switching opportunities.
Product Type:
Standalone analytical systems dominate capital expenditure budgets while embedded preparatory modules integrate into automated workflow platforms.
- Spectrophotometers:These instruments measure light absorption across ultraviolet and visible wavelengths to quantify nucleic acid and protein concentrations. Pharmaceutical quality control laboratories in the United States deploy them for batch release testing, driven by FDA 21 CFR Part 11 electronic records mandates that require validated optical density measurements.
- Chromatography Systems:Separation platforms utilizing liquid or gas phases to isolate complex biological mixtures based on physicochemical properties. Boston and San Diego biotech clusters sustain heavy procurement of high-performance liquid chromatography units for biologics purity analysis, compelled by EMA GMP Annex 1 sterile manufacturing revisions that mandate environmental monitoring integration.
- Incubators:Temperature-controlled chambers maintaining precise thermal conditions for cell culture propagation, typically operating within 0.1 degrees Celsius tolerance.
- Centrifuges:Rotational separation devices isolating cellular components and biomolecules by density gradient differential.
Volume placements concentrate in chromatography systems; the faster expansion belongs to spectrophotometers.
Technology:
Detection methodologies span from antibody-based colorimetric assays to ionization-based molecular analysis, with cost tiers separating routine screening from precision quantification.
- Mass Spectrometry:Ionization-based detection platforms identifying molecules by mass-to-charge ratio with picogram-per-milliliter sensitivity. Proteomics applications in precision medicine pipelines command premium positioning, though helium supply volatility concentrated in Qatar and the United States creates input cost instability.
- PCR:Polymerase chain reaction thermal cyclers amplifying DNA sequences through repeated denaturation and extension cycles. Academic institutions maintain highest replacement frequency for these instruments as genomics research programs expand.
- ELISA:Enzyme-linked immunosorbent assay systems detecting antigens via antibody-antigen binding with colorimetric readout.
- Cell Counters:Automated enumeration devices quantifying viable cell density in bioprocess development workflows.
Mass spectrometry captures the steepest expansion trajectory; PCR maintains highest instrument turnover velocity.
Application:
Workflow positioning distinguishes discovery-phase exploratory tools from manufacturing-phase compliance systems.
- Drug Discovery:High-throughput screening and lead optimization activities consuming analytical capacity in early-phase pharmaceutical development. Contract research organizations scaling antibody and cell therapy programs drive absolute dollar demand, outpacing genomics in total procurement volume.
- Quality Control:Validated analytical procedures ensuring batch consistency and regulatory compliance in commercial manufacturing. FDA and EMA quality guidelines for cell and gene therapy manufacturing compel facilities to upgrade platforms, embedding audit trails as standard features.
- Genomics:DNA sequencing and genetic analysis workflows requiring next-generation sequencing infrastructure.
- Proteomics:Protein identification and quantification studies utilizing mass spectrometry and chromatography integration.
Quality control claims the largest installed base; drug discovery is gaining share fastest.
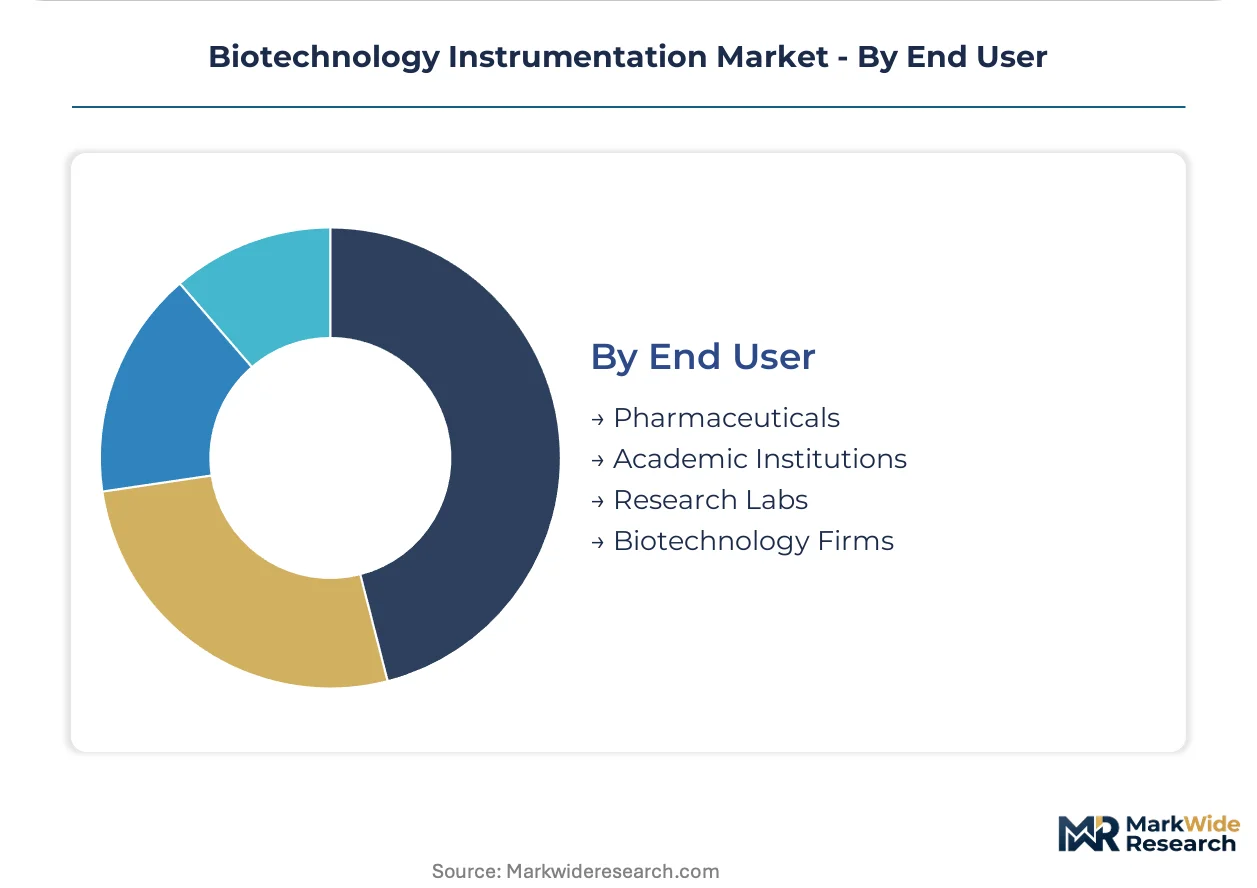
End User:
Customer scale determines purchasing centralization, with enterprise procurement teams negotiating differently than principal investigator-led acquisitions.
- Pharmaceuticals:Integrated drug developers and contract research organizations consolidating instrument procurement through enterprise agreements. Thermo Fisher Scientific anchors these accounts through chromatography and mass spectrometry breadth, while Danaher competes via integrated workflow automation.
- Biotechnology Firms:Mid-sized innovators fragmenting demand across specialized vendors. Boston and San Diego clusters sustain heavy capital investment, though multi-omics integration complexity creates talent scarcity constraints.
- Academic Institutions:University research departments procuring through grant-funded mechanisms with extended validation timelines.
- Research Labs:Government and independent research facilities operating outside pharmaceutical regulatory frameworks.
Pharmaceuticals dominate enterprise contract value; biotechnology firms show the most rapid account expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for biotechnology instrumentation concentrates in the United States, where Boston and San Diego biotech clusters sustain heavy capital investment in chromatography and mass spectrometry infrastructure. Pharmaceutical contract research organizations and mid-sized biotechnology firms drive procurement volumes across three continents. Regulatory mandates from FDA, EMA, and CDSCO compel facilities to upgrade analytical platforms with embedded audit trails and environmental monitoring capabilities.
United States
FDA 21 CFR Part 11 electronic records requirements and biologics pipeline expansion drive instrument procurement volumes. Contract research organizations consolidate purchasing power through enterprise agreements while mid-sized firms fragment demand. Boston and San Diego biotech clusters sustain heavy capital investment in chromatography and mass spectrometry infrastructure for real-time batch release testing.
Germany
EMA GMP Annex 1 sterile manufacturing revisions mandate environmental monitoring capabilities in analytical instruments. EU AI Act risk classification frameworks force manufacturers to embed algorithmic transparency features into chromatography data processing software. Biologics manufacturers in Germany and Switzerland prioritize vendors with pre-validated compliance architectures to accelerate regulatory submissions.
India
CDSCO quality guidelines and PLI scheme incentives attract contract manufacturing investment in biologics production. Hyderabad and Bangalore clusters expand instrument demand as pharmaceutical companies establish multi-product facilities. Single-use chromatography systems displace traditional stainless-steel infrastructure to reduce cross-contamination risk in these emerging manufacturing hubs.
China
NMPA regulatory harmonization with international standards compels domestic facilities to upgrade analytical platforms for cell and gene therapy manufacturing. Precision medicine proteomics applications expand mass spectrometry deployment in clinical reference laboratories. Yangtze River Delta and Pearl River Delta biopharmaceutical corridors concentrate capital investment in next-generation sequencing and automated workflow platforms.
Switzerland
Swissmedic quality guidelines for biologics manufacturing enforce stringent validation protocols for analytical instruments. Precision medicine pipelines in Basel and Zurich drive proteomics and metabolomics applications requiring mass spectrometry integration. Biologics manufacturers prioritize vendors with embedded audit trails and environmental monitoring as standard features rather than optional modules.
Biotechnology Instrumentation Market Competitive Environment
United States producers anchor one tier; Japanese and European specialists hold differentiated positions in precision detection technologies. Market structure tilts toward consolidation at the enterprise scale while mid-sized biotechnology firms fragment demand across specialized vendors. Three archetypes dominate: diversified life science conglomerates with chromatography breadth, integrated workflow automation specialists, and next-generation sequencing platforms with proprietary consumable ecosystems. Competitive moves concentrate on strategic partnerships for AI-enabled analytical software and geographic expansion into India biologics manufacturing corridors.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher represent contrasting strategic positions. Thermo Fisher anchors enterprise accounts through analytical breadth spanning chromatography and mass spectrometry portfolios. Danaher exemplifies integrated workflow automation approaches that reduce manual sample handling in pharmaceutical quality control environments. Illumina occupies a distinct position in next-generation sequencing instrumentation, where proprietary consumable lock-in extends customer lifetime value and fragments purchasing decisions across incompatible vendor platforms.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher |
| Agilent Technologies |
| Waters Corporation |
| Shimadzu Corporation |
| Bio-Rad Laboratories |
| Illumina |
| PerkinElmer |
| Bruker Corporation |
| Others |
Value Chain & Pricing Dynamics
Mass spectrometry specialists concentrated in Boston and San Diego biotech clusters command wage premiums that widen pricing spreads between premium analytical platforms and benchtop alternatives. Labor-cost differentials between these talent-dense metros and emerging manufacturing hubs in India compress margins for vendors competing on service-intensive installations.
Pricing Analysis
Volume placements concentrate in chromatography systems while mass spectrometry captures premium margins. Pricing stratifies across enterprise-grade, mid-tier, and entry-level instrument tiers, with FDA 21 CFR Part 11 compliance certification and embedded audit trail capabilities as primary differentiation drivers. Cost compression in mid-tier segments intensifies because contract research organizations negotiate unbundled service contracts. Academic institutions exhibit highest price sensitivity; pharmaceutical enterprise buyers prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Domestic-content mandates in China's NMPA regulatory framework and India's PLI scheme are reshaping sourcing patterns for analytical instrument components. Manufacturing concentration centers on the United States, Germany, and Japan for precision optical and ionization subassemblies. Helium supply chains draw from Qatar and the United States; rare earth magnet sourcing rests on Chinese processing capabilities. Single-source vulnerability in noble gas supply creates input cost instability. Distribution runs through original equipment manufacturer direct sales teams and specialized life science distributors with field service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into consumable production and captive software development is accelerating as vendors seek to extend customer lifetime value and defend margin structures against unbundling pressures.
For Market Incumbents: Lock in enterprise accounts through chromatography and mass spectrometry portfolio breadth while embedding AI-enabled analytical software ahead of formal EU AI Act validation protocols. Thermo Fisher Scientific's enterprise anchoring strategy and Danaher's workflow automation integration provide defensive templates against emerging modular competitors. Prioritize certification investment in ISO 13485 quality management systems to exclude uncertified rivals from regulated markets. For New Entrants and Emerging Players: Contract research organization procurement teams represent the most accessible channel for penetrating pharmaceutical quality control workflows. White-space opportunities concentrate in single-use chromatography systems for multi-product biologics facilities and benchtop mass spectrometry for decentralized proteomics workflows. Target India's Hyderabad and Bangalore clusters where CDSCO quality guidelines and PLI incentives are attracting contract manufacturing investment with limited incumbent service infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with AI-enabled analytical software specialists given pending regulatory validation frameworks that will favor pre-compliant architectures. Long-term viability favors platforms with proprietary consumable ecosystems that generate recurring revenue streams and create switching costs. Monitor FDA and EMA guidance on machine learning in instrument control as the inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Analytical Software Integration | EU AI Act compliance requirements in Germany and Switzerland favor vendors with pre-validated algorithmic transparency features. |
| Single-Use Chromatography System Development | Pre-packed disposable columns reduce cross-contamination risk in India's emerging multi-product biologics facilities. |
| Consumable Production Backward Integration | Proprietary reagent lock-in extends customer lifetime value and fragments purchasing decisions across incompatible platforms. |
| India Biologics Manufacturing Expansion | CDSCO quality guidelines and PLI scheme incentives in Hyderabad and Bangalore clusters attract contract manufacturing investment. |
| Cloud-Connected Instrument Validation | FDA 21 CFR Part 11 electronic records requirements compress analytical turnaround times across distributed manufacturing networks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this biotechnology instrumentation analysis. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and GPO contracts managers complemented secondary validation. Bottom-up triangulation across instrument shipment databases and top-down reconciliation against pharmaceutical capital expenditure disclosures ensured cross-verification. FDA 510(k) filings, EMA GMP inspection reports, CDSCO manufacturing licenses, and SEC 10-K instrument revenue disclosures provided foundational secondary sources.
Segment-level modeling operated at product type, technology, application, and end user dimensions across the projection horizon. CAGRs were derived from instrument replacement cycle analysis, biologics pipeline expansion trajectories, and regulatory compliance upgrade mandates. Treatment line positioning for cell and gene therapy manufacturing, regional regulatory cluster heterogeneity, and consumable attach rate assumptions informed analytical framework construction.
Caveats apply where helium supply volatility, AI regulatory validation timeline shifts, or biologics manufacturing geographic redistribution could materially shift the outlook. Forecasts reflect assumptions about contract research organization procurement consolidation and mid-sized biotechnology firm fragmentation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Cell and Tissue Culture Supplies Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Global Large Molecule Bioanalytical Technologies Market
Biotechnology Equipment
In-Vitro Fertilization (IVF) Microscopes Market
Biotechnology Equipment
Ultracentrifuges Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Balanced Salt Solution for Cell Culture Market
Biotechnology Equipment
Biotherapeutics Virus Removal Filters Market
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Cell Disruption Market
Biotechnology Equipment
DNA/RNA Extraction Market