
 Middle East and Africa Transfection Reagent and Equipment Market | 2026-2036
Middle East and Africa Transfection Reagent and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Transfection Reagent and Equipment Market Foresight
After-sales instrument maintenance and reagent subscription bundles are recalibrating how vendors capture lifetime value in the Middle East and Africa Transfection Reagent and Equipment Market. Lonza leverages its regional distribution partnerships to sustain premium positioning across Gulf State laboratories. Promega Corporation anchors its competitive stance through localized technical support networks in South Africa and Nigeria. Bio-Rad Laboratories, Inc. differentiates by specializing in electroporation system servicing capabilities that reduce instrument downtime for academic clients.
Transfection reagents and equipment comprise formulated chemical or physical delivery systems designed to introduce nucleic acids, proteins, or other macromolecules into eukaryotic cells, typically achieving transfection efficiencies between 70-90% in optimized mammalian systems depending on cell type and payload chemistry. These tools serve as foundational infrastructure for gene therapy manufacturing, vaccine vector development, and stable cell line engineering across biopharmaceutical workflows. DNA Reagents occupy the dominant revenue position due to persistent demand for plasmid-based gene therapy protocols, while RNA Reagents represent the fastest-expanding category as mRNA vaccine platforms gain traction among regional manufacturers. Electroporation devices command premium pricing relative to lipofection consumables because capital equipment purchases involve extended procurement cycles and tighter facility infrastructure requirements.
Saudi Arabia's SFDA and South Africa's national pharmaceutical regulator enforce progressively stringent biosafety and quality standards for nucleic acid delivery systems entering clinical applications. Egypt's drug authority applies import inspection protocols that align with international ISO certification benchmarks for transfection device electrical safety and reagent sterility assurance. Stakeholders must monitor how regulatory harmonization between Gulf Cooperation Council states and broader African economic communities reshapes product registration pathways and local manufacturing incentives.
Market Dynamics
Saudi Arabia's SFDA is tightening nucleic acid delivery system standards for clinical applications, forcing vendors to recalibrate quality assurance protocols and local manufacturing partnerships across Gulf State biotech clusters.
Growth Catalysts
- mRNA vaccine platforms:Regional manufacturers in Egypt and South Africa are expanding RNA transfection reagent procurement for infectious disease and oncology pipelines, creating sustained demand pull from academic research hubs and contract development organizations.
- CDSCO-aligned import protocols:Egypt's drug authority applies ISO certification benchmarks for reagent sterility assurance and device electrical safety, elevating quality thresholds that filter out low-grade suppliers and consolidate procurement toward certified vendors.
- Gene therapy manufacturing:Biopharmaceutical producers in the Gulf States are building plasmid-based production capacity, requiring high-efficiency DNA transfection systems for stable cell line engineering and viral vector generation.
Market Restraints
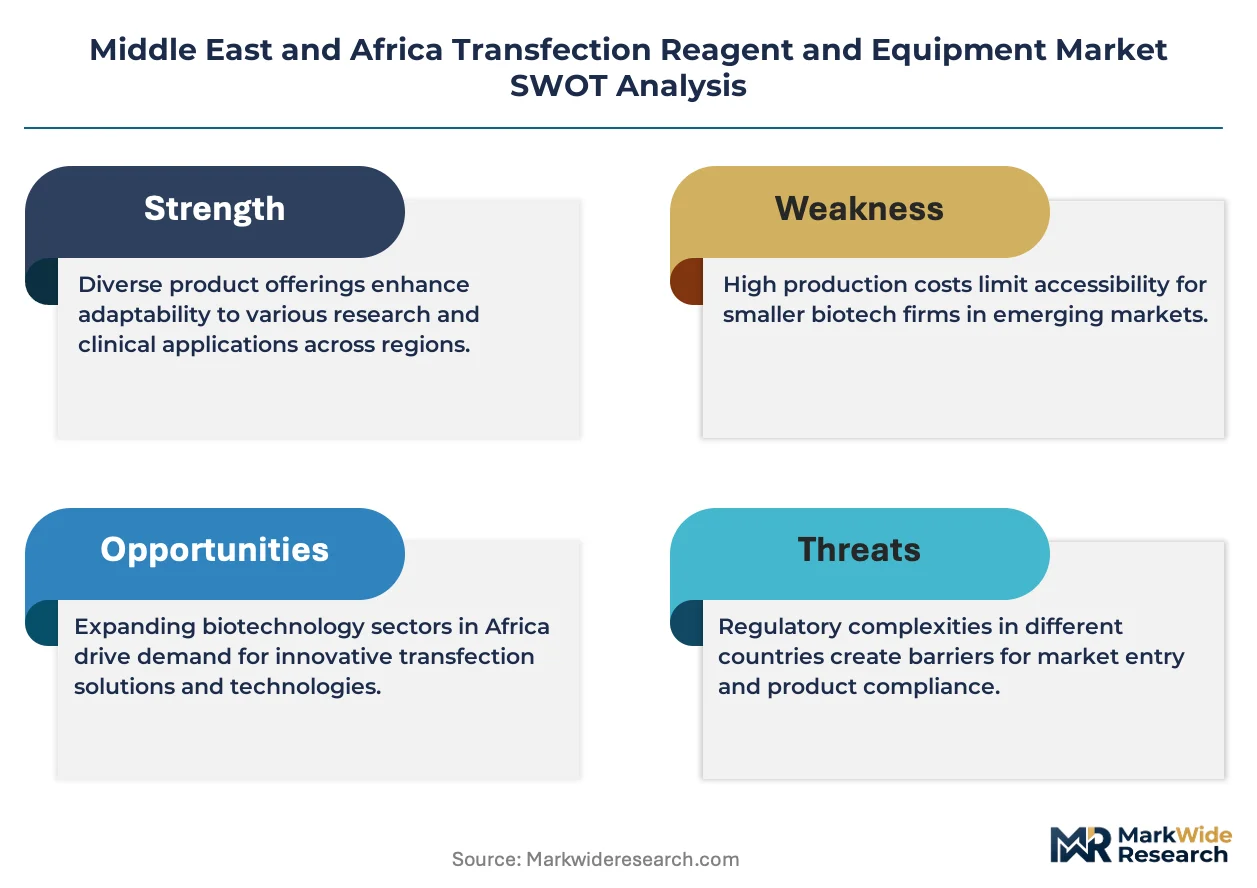
- Capital equipment intensity:Electroporation devices require extended procurement cycles and specialized facility infrastructure, compressing adoption rates among underfunded academic laboratories in Nigeria and Kenya.
- Reagent import dependency:Supply concentration in European and North American manufacturers exposes regional buyers to currency volatility and extended lead times for temperature-sensitive formulations.
- Technical performance variance:Primary cell transfection efficiencies below 50% in non-optimized African cell lines limit protocol standardization and reproducibility across distributed research networks.
Strategic Opportunities
- Nigeria's emerging biotech corridor:Lagos-based research institutions and vaccine developers represent underpenetrated demand for lipofection consumables and entry-level electroporation systems.
- Reagent subscription bundling:Instrument vendors are capturing lifetime value through after-sales maintenance contracts paired with recurring consumable supply agreements, displacing transactional procurement models.
- GCC regulatory harmonization:Convergence of biosafety frameworks between Saudi Arabia, UAE, and Qatar is streamlining product registration pathways and reducing redundant compliance costs for multi-country market entry.
Industry Challenges
- Specialized technical workforce scarcity:Electroporation protocol optimization and cell culture transfection troubleshooting require trained molecular biologists, a skill set concentrated in Johannesburg, Cape Town, and Riyadh research hubs.
- Legacy instrument integration:Academic laboratories in Egypt and Morocco operate aging electrophoresis and cell culture infrastructure that lacks compatibility with modern high-throughput transfection workstations, forcing costly facility upgrades or workflow fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Transfection Reagent and Equipment Market |
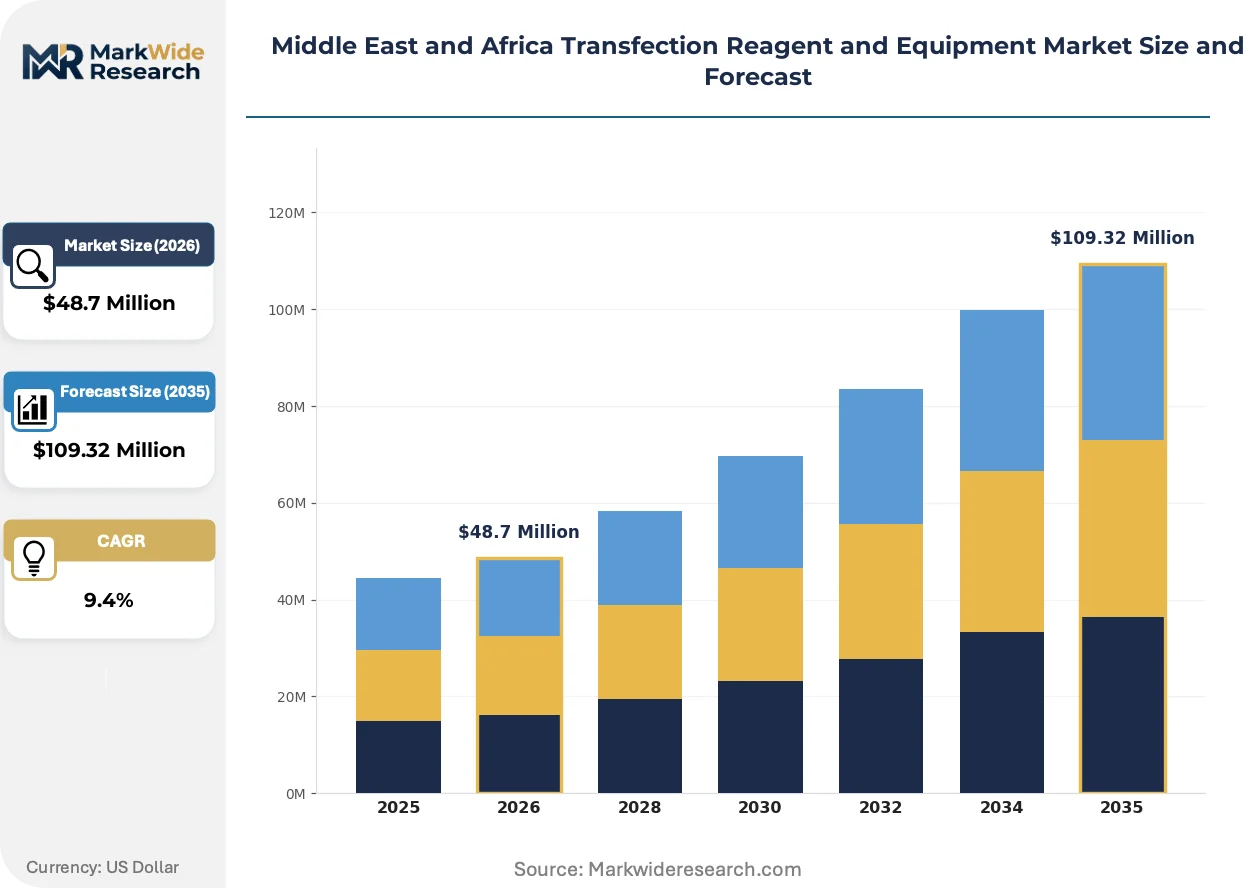
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $109.32 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Reagents, RNA Reagents, Protein Reagents, Transfection Devices Application: Gene Therapy, Vaccine Development, Cell Line Production, Basic Research End User: Pharmaceutical Companies, Academic Research Institutes, Contract Research Organizations, Biotechnology Firms Delivery Mode: Electroporation, Lipofection, Microinjection, Viral Vectors |
| Companies Covered | Mirus Bio LLC, Promega Corporation, Polyplus Transfection, Bio-Rad Laboratories, Inc., Merck KGaA, Lonza, MaxCyte, Inc., Altogen Biosystems, SBS Genetech, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Transfection Reagent and Equipment Market Shifts & Advancements
Physical delivery methods are gaining preference over chemical alternatives as biopharmaceutical manufacturers prioritize payload flexibility and cell-type universality in gene therapy workflows.
Electroporation-based nucleic acid delivery is overtaking lipofection in regional gene therapy manufacturing facilities. This physical method achieves transfection efficiencies exceeding 85% across difficult-to-transfect primary cells and stem cell lines. Saudi Arabian and South African contract manufacturers are adopting scalable electroporation platforms for plasmid and mRNA production. The technology is overtaking chemical reagent dependence in clinical-grade applications where lot-to-lot consistency and regulatory documentation requirements are compressing tolerance for formulation variability.
SFDA's progressive enforcement of biosafety standards for nucleic acid delivery systems entering clinical trials is reshaping vendor qualification requirements. The regulation mandates traceable supply chains and validated sterility assurance for reagents used in human therapeutic applications. Electroporation device manufacturers face tightened electrical safety certification protocols. Gulf State biotech clusters are responding by consolidating procurement toward vendors with established regional technical support infrastructure and documented compliance histories.
Service unbundling is fragmenting traditional instrument-reagent bundled sales models in South African academic markets. Research institutions are separating capital equipment purchases from consumable supply agreements, enabling competitive tendering for reagent contracts and squeezing margins on standalone instrument sales. Local distributors are responding with flexible financing structures and extended warranty packages. This behavioral shift is most visible in Cape Town and Johannesburg university consortia where centralized procurement offices are aggregating demand across multiple departments.
Middle East and Africa Transfection Reagent and Equipment Market Segmentation
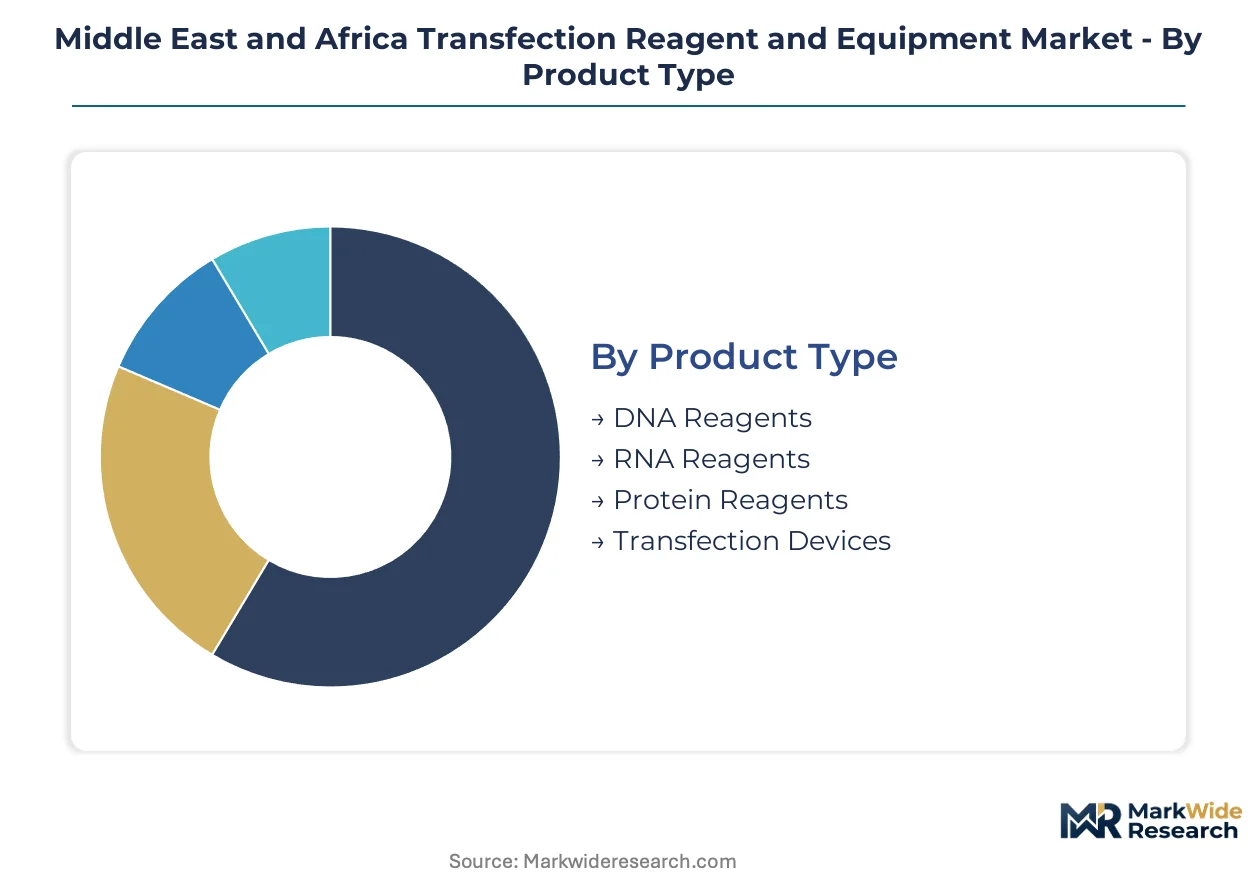
Transfection reagents and equipment serve distinct workflow requirements across gene therapy manufacturing, vaccine development, and academic research. Segmentation reveals how certification burdens, application complexity, and end-user procurement power reshape competitive positioning across Middle East and Africa markets.
Product Type:
SFDA and Egypt's drug authority apply differentiated certification protocols across reagent categories, with DNA and RNA reagents facing sterility assurance mandates that protein reagents and devices escape.
- DNA Reagents:Formulated chemical systems designed for plasmid delivery into eukaryotic cells, typically lipid-based or calcium phosphate formulations. Demand concentrates in Saudi Arabian biotech clusters where gene therapy manufacturers require high-efficiency stable cell line engineering for viral vector production.
- RNA Reagents:Specialized formulations optimized for mRNA and siRNA delivery with enhanced stability against nuclease degradation. South African contract manufacturers and Egyptian academic hubs are expanding procurement for infectious disease and oncology vaccine pipelines, creating supply tightness for GMP-grade formulations.
- Protein Reagents:Peptide-based and protein-conjugated delivery systems enabling direct macromolecule translocation across membranes. Limited adoption in regional markets due to higher per-transfection costs and complex cold-chain requirements.
- Transfection Devices:Capital equipment spanning electroporation systems, microinjection workstations, and automated liquid handlers. Extended procurement cycles in Gulf States favor vendors offering localized maintenance infrastructure and ISO-certified electrical safety documentation.
DNA Reagents sits at the top of the volume ranking, with RNA Reagents climbing the fastest.
Application:
Application segmentation tracks how end-use complexity determines margin structures, with clinical-grade workflows commanding premium pricing over research-only applications.
- Gene Therapy:Clinical and preclinical nucleic acid delivery for therapeutic gene modulation, requiring validated protocols and extensive regulatory documentation. Saudi Arabian manufacturers building plasmid production capacity drive demand for high-efficiency systems with traceable supply chains.
- Vaccine Development:mRNA and viral vector platform manufacturing for infectious disease and oncology indications. South African producers and Egyptian research consortia are scaling RNA transfection infrastructure for regional vaccine autonomy initiatives.
- Cell Line Production:Stable and transient transfection for biopharmaceutical manufacturing cell banks. Contract manufacturers in the Gulf States prioritize lot-to-lot consistency over absolute efficiency metrics.
- Basic Research:Academic and exploratory applications with lower regulatory documentation requirements. Nigerian and Kenyan laboratories face capital constraints that favor lipofection consumables over electroporation devices.
Gene Therapy commands the highest revenue per transaction, with Vaccine Development expanding most quickly.
End User:
Procurement sophistication varies sharply across end-user categories, with pharmaceutical companies leveraging centralized tendering that academic institutes cannot replicate.
- Pharmaceutical Companies:Integrated biopharmaceutical manufacturers with dedicated gene therapy and vaccine divisions. Saudi Arabian and UAE-based firms are consolidating supplier relationships to reduce qualification overhead for multi-site operations.
- Academic Research Institutes:University laboratories and national research centers with fragmented procurement authority. Cape Town and Johannesburg consortia are unbundling instrument and reagent purchases to enable competitive tendering.
- Contract Research Organizations:External service providers offering transfection-as-a-service for client molecule development. Emerging presence in Lagos and Nairobi serving regional biotech startups without in-house capabilities.
- Biotechnology Firms:Venture-backed and publicly traded companies focused on platform technologies. Concentrated in Riyadh and Dubai biotech clusters with preference for scalable electroporation platforms.
Pharmaceutical Companies anchor the revenue base, with Contract Research Organizations gaining share fastest.
Delivery Mode:
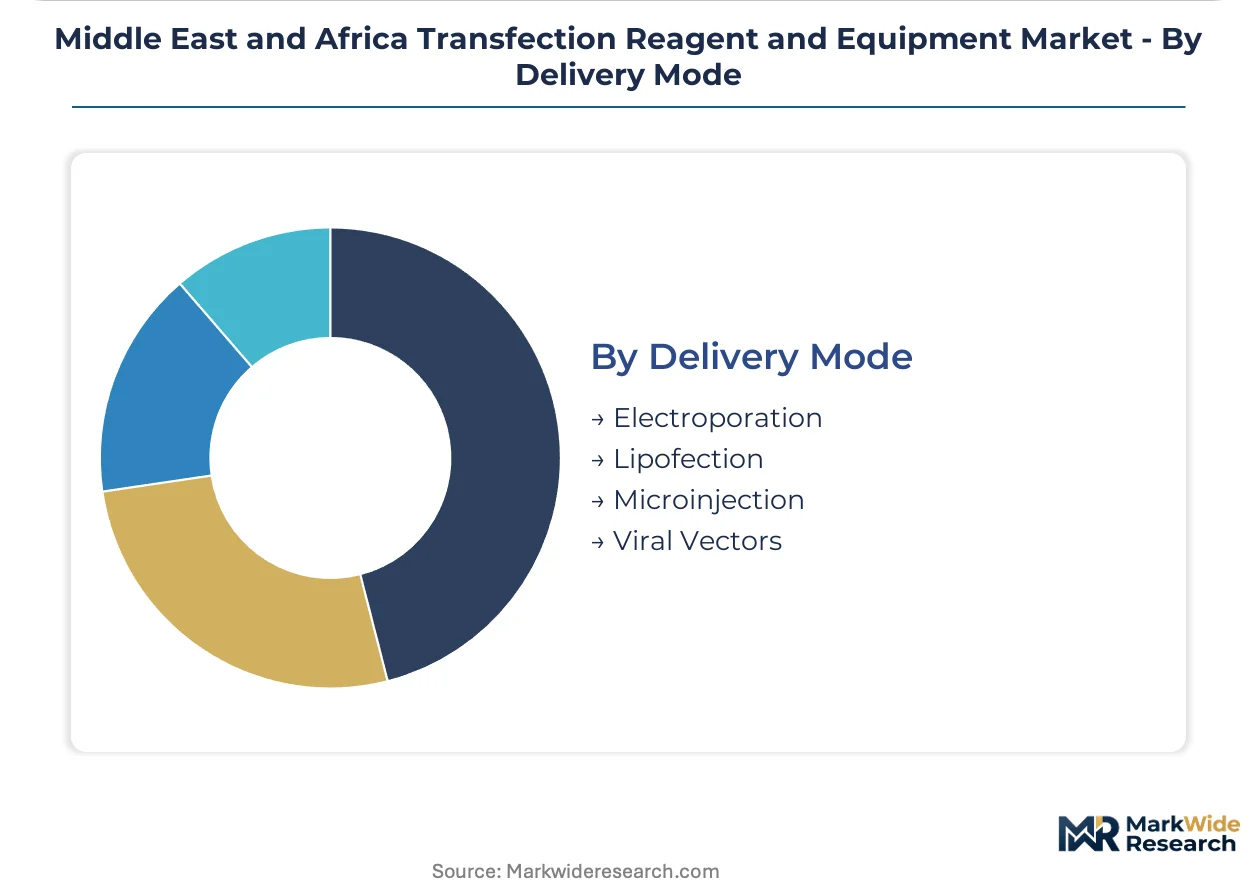
Physical versus chemical delivery methods split the market along payload flexibility and cell-type universality dimensions, with electroporation overtaking lipofection in clinical manufacturing settings.
- Electroporation:Physical membrane permeabilization using controlled electrical pulses, achieving efficiencies exceeding 85% across difficult-to-transfect primary cells. Saudi Arabian and South African contract manufacturers are adopting scalable platforms for plasmid and mRNA production.
- Lipofection:Lipid-based chemical delivery systems offering protocol simplicity and lower capital requirements. Dominates Nigerian and Kenyan academic markets where equipment procurement cycles are compressed.
- Microinjection:Direct physical delivery into individual cells using fine glass needles. Restricted to specialized applications in embryonic stem cell research and transgenic animal production with limited regional adoption.
- Viral Vectors:Engineered virus particles exploiting natural infection mechanisms for nucleic acid delivery. Requires separate biosafety containment infrastructure that few regional facilities have commissioned.
Electroporation leads the value ranking, with Lipofection maintaining volume dominance in price-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia and South Africa command divergent market trajectories despite comparable biopharmaceutical ambitions, with Riyadh's state-backed capital deployment contrasting Johannesburg's fragmented academic procurement patterns.
Saudi Arabia
Gene therapy manufacturers and mRNA vaccine developers drive reagent consumption in Riyadh and King Abdullah Economic City. SFDA enforces progressively stringent biosafety standards for nucleic acid delivery systems entering clinical trials, mandating traceable supply chains and validated sterility assurance. The Riyadh biotech cluster concentrates electroporation platform adoption for plasmid production.
South Africa
Contract development organizations and academic research hubs in Cape Town and Johannesburg sustain demand for DNA and RNA transfection reagents. The national pharmaceutical regulator applies CDSCO-aligned import protocols that elevate quality thresholds for reagent sterility assurance. Cape Town university consortia are unbundling instrument and reagent purchases to enable competitive tendering.
United Arab Emirates
Dubai and Abu Dhabi biotech clusters prioritize scalable electroporation systems for viral vector manufacturing. MOHAP coordinates with Gulf Cooperation Council states on regulatory harmonization for medical device electrical safety certification. Dubai Science Park hosts emerging contract manufacturers consolidating procurement toward vendors with regional technical support infrastructure.
Egypt
Academic research hubs in Cairo and Alexandria expand RNA transfection reagent procurement for infectious disease vaccine pipelines. The national drug authority applies ISO certification benchmarks for device electrical safety and reagent sterility assurance. Cairo's centralized procurement offices are aggregating demand across multiple university departments.
Nigeria
Lagos-based research institutions and vaccine developers represent emerging demand for lipofection consumables and entry-level electroporation systems. The national biosafety framework remains under development, creating qualification uncertainty for clinical-grade reagent imports. Lagos biotech corridor lacks specialized technical workforce density for protocol optimization.
Middle East and Africa Transfection Reagent and Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium reagent vendors capturing recurring revenue through subscription bundling while equipment OEMs compete on localized servicing capabilities. The vendor base concentrates around Swiss and German chemical suppliers, American electroporation specialists, and emerging Chinese reagent manufacturers. Three archetypes dominate: integrated life science conglomerates with broad portfolios, focused transfection technology specialists, and regional distribution partners leveraging technical support networks. Competitive intensity centers on strategic partnerships for local manufacturing qualification and geographic expansion through distributor exclusivity arrangements.
Within the integrated conglomerate tier, Merck KGaA and Lonza occupy positions anchored by established regional distribution partnerships and documented compliance histories with Gulf State regulators. Promega Corporation exemplifies the specialist archetype through its localized technical support infrastructure in South Africa and Nigeria. Bio-Rad Laboratories, Inc. represents the equipment-differentiated segment, with servicing capabilities that reduce instrument downtime for academic clients in Egypt and Morocco.
| Leading Market Players |
|---|
| Mirus Bio LLC |
| Promega Corporation |
| Polyplus Transfection |
| Bio-Rad Laboratories, Inc. |
| Merck KGaA |
| Lonza |
| MaxCyte, Inc. |
| Altogen Biosystems |
| SBS Genetech |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between GMP-compliant clinical reagents and research-grade consumables manifests in divergent pricing architectures and supply chain configurations across the Middle East and Africa Transfection Reagent and Equipment Market. Premium vendors command threefold price multiples for SFDA-validated DNA and RNA reagents while routing fulfillment through Dubai and Johannesburg regional distribution centers, whereas academic buyers in Nigeria and Kenya source economy-grade lipofection kits through direct import channels with extended lead times and currency-hedged payment terms.
Pricing Analysis
Capacity additions in South Africa's contract manufacturing sector are reshaping price floors for RNA transfection reagents as local formulators compete with established European suppliers. The dominant pricing structure separates premium GMP-grade from standard research-grade and economy unvalidated tiers, with price differentiation driven by ISO 13485 certification status and after-sales technical support bundling. Pricing pressure stems from Egyptian academic consortia unbundling instrument and consumable purchases to enable competitive tendering. Pharmaceutical companies in Saudi Arabia exhibit lowest price sensitivity due to state-backed capital deployment, while Nigerian research institutes face acute budget constraints favoring spot procurement of unbranded alternatives.
Supply Chain Analysis
Regional distribution centers in Dubai and Johannesburg operate as hub-and-spoke nodes for temperature-sensitive reagent fulfillment across the Middle East and Africa Transfection Reagent and Equipment Market. Manufacturing concentrates in Switzerland, Germany, and the United States for premium electroporation devices and formulated reagents, with emerging Chinese suppliers penetrating economy segments. Critical dependencies include lipid nanoparticle precursors, sterile filtration membranes, and precision electrical components for pulse generators. Single-source vulnerability runs through European cold-chain logistics providers serving GCC markets. Distribution runs through authorized distributor networks with localized technical support capabilities rather than direct vendor-to-end-user models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Transfection Reagent and Equipment Market functions as a geographic-arbitrage play where regulatory compliance costs in Saudi Arabia diverge sharply from qualification uncertainty in Nigeria, creating tiered entry barriers that favor capitalized incumbents in Riyadh while leaving price-sensitive segments exposed to unvalidated supply.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Accelerate SFDA and CDSCO-aligned quality documentation for RNA reagent portfolios to preempt emerging Chinese suppliers gaining traction in Egyptian academic markets. Consolidate distributor exclusivity arrangements in Lagos and Nairobi before regional contract manufacturers establish captive supply relationships. Capacity additions in South Africa threaten margin compression for premium DNA reagents unless incumbents anchor long-term service contracts with after-sales maintenance bundling. For New Entrants and Emerging Players: Capture Nigeria's vaccine development corridor as the most penetrable white-space target, where lagging biosafety framework development creates temporary qualification tolerance for research-grade electroporation systems. Prioritize lipofection consumables over capital equipment to bypass extended procurement cycles and facility infrastructure requirements. Establish technical training partnerships with Lagos-based research institutions to compensate for specialized workforce scarcity and differentiate against established vendors lacking localized protocol optimization support. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented distributor networks in North Africa and East Africa struggle to achieve scale economies against integrated life science conglomerates with Gulf State regulatory track records. Long-term viability favors acquisition targets with documented SFDA compliance histories and established cold-chain logistics capabilities spanning multiple jurisdictions. The signal to watch is MOHAP-led GCC regulatory harmonization progress, which would compress redundant compliance costs and trigger accelerated vendor consolidation toward multi-country qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Local Manufacturing Qualification | SFDA sterility assurance mandates drive regional production partnerships to reduce import dependency and currency exposure. |
| Reagent Subscription Bundling | After-sales maintenance contracts paired with consumable supply agreements displace transactional procurement in South African academic markets. |
| Technical Support Network Expansion | Localized troubleshooting capabilities in Lagos and Nairobi address workforce scarcity limiting protocol standardization. |
| Regulatory Harmonization Alignment | GCC convergence on biosafety frameworks streamlines multi-country product registration and reduces compliance overhead. |
| Electroporation Platform Scaling | Saudi Arabian contract manufacturers adopt scalable systems for mRNA and plasmid production to serve gene therapy pipelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand estimates for the Middle East and Africa Transfection Reagent and Equipment Market. Primary engagement captured perspectives from biopharmaceutical manufacturing executives, regulatory affairs specialists at SFDA and Egypt's drug authority, academic procurement officers in Cape Town and Johannesburg consortia, and distribution channel partners managing cold-chain logistics. Secondary validation drew from customs import records, ISO certification databases, clinical trial registration filings, and GMP facility inspection reports. Bottom-up segmentation modeling triangulated against top-down market sizing from regional biopharmaceutical capital expenditure disclosures.
Historical reference periods anchored demand trajectories across gene therapy manufacturing expansion, mRNA vaccine platform adoption curves, and academic research funding cycles to inform projection parameters. The analytical framework segmented by product type, application complexity, end-user procurement sophistication, and delivery mode technology across the modeling period. CAGRs derived from fitted growth curves incorporating country-specific regulatory enforcement timelines and biotech cluster development stages. Forecast inputs included SFDA biosafety standard progression, GCC harmonization implementation pace, and regional contract manufacturing capacity buildout announcements.
Regulatory enforcement delays, currency volatility in import-dependent markets, and technical workforce development shortfalls are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumption sets regarding certification timeline adherence and infrastructure investment continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Biosurgery Equipment Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Global Photobiostimulation Devices Market
Biotechnology Equipment
Global Latex Agglutination Test Kits Market
Biotechnology Equipment
United States Transfection Technologies Market
Biotechnology Equipment
Global DNA/RNA Extraction Kit Market
Biotechnology Equipment
Global Bioprocess Analyzers Market
Biotechnology Equipment
Global Biological Safety Cabinets Market
Biotechnology Equipment
Global Competent Cells Market
Biotechnology Equipment
Qpcr Instruments Market
Biotechnology Equipment
Global Biological Microscope Objectives Market
Biotechnology Equipment
Cell Harvesting Systems Market
Biotechnology Equipment
Global Automated Biochemical Analyzer Market
Biotechnology Equipment
Bioprocessing Analytics Equipment Market
Biotechnology Equipment
Biochemistry Analyzers Market