
 Germany Travel Insurance Market | 2026-2036
Germany Travel Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Travel Insurance Market Foresight
Digital claims processing revenue is reconfiguring margin pools away from traditional agent-mediated distribution. Allianz Partners leverages proprietary mobile claims platforms to sustain direct customer relationships. HanseMerkur Reiseversicherung anchors its position through specialized cruise and adventure travel products. ERGO Reiseversicherung competes via integrated banking-insurance cross-selling through its parent network.
Germany travel insurance constitutes short-term risk transfer instruments underwritten against trip-specific contingencies, typically incorporating medical expense ceilings, cancellation fee indemnification, and baggage valuation clauses. These products serve primarily to shield German travelers from liquidity shocks arising from health emergencies abroad or non-recoverable prepaid travel expenditures. Single Trip policies dominate transaction volume among occasional German holidaymakers, while Annual Multi-Trip coverage captures disproportionate value from frequent business travelers. Medical Expenses coverage commands premium priority given Germany's statutory health insurance limitations outside the EU, whereas Trip Cancellation protection faces margin compression from standardized online comparison tools.
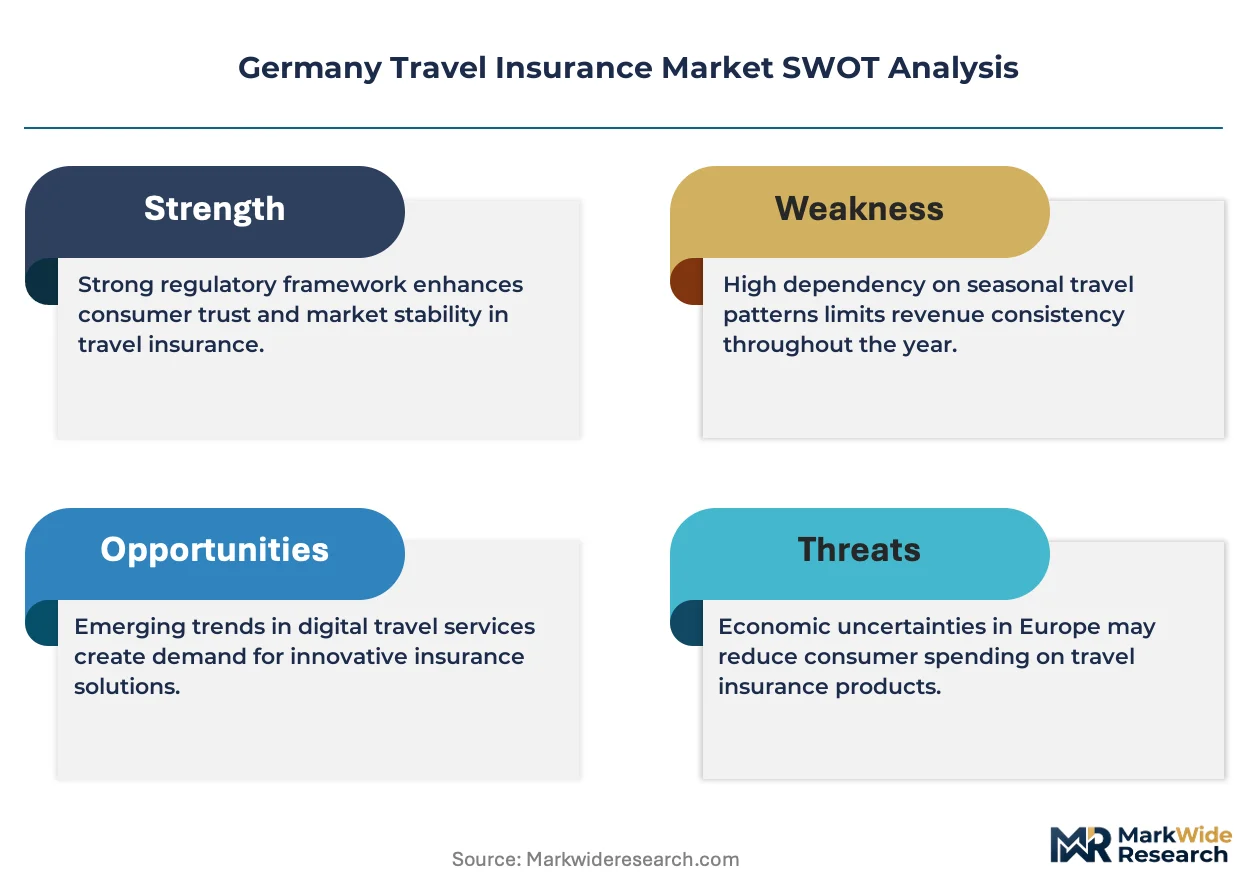
BaFin supervises solvency requirements and policy term transparency, while EU-wide Insurance Distribution Directive (IDD) rules govern commission disclosure and suitability assessments for German distributors. The country's national data regulator enforces GDPR-compliant handling of health declarations in digital underwriting workflows. Stakeholders must monitor whether embedded insurance partnerships with airline booking platforms will trigger fresh BaFin scrutiny over unadvised sales practices.
Market Dynamics
BaFin's consumer protection mandates for insurance transparency are forcing incumbent insurers to restructure policy disclosure workflows and accelerate digital underwriting investments. This regulatory pressure compounds with embedded insurance partnerships reshaping distribution economics.
Growth Catalysts
- IDD Commission Disclosure Rules:EU-wide Insurance Distribution Directive mandates force distributors toward fee-based advisory models, elevating demand for transparent standalone travel products.
- Senior Citizen Extended Coverage:German retirees seeking multi-month European stays drive specialized annual policies with elevated medical ceilings and pre-existing condition waivers.
- Mobile Claims Platforms:Proprietary smartphone-based first-notice-of-loss systems compress settlement cycles from weeks to hours, improving retention among digitally native travelers.
Market Restraints
- Statutory Health Insurance Limitations:Germany's GKV system provides partial EU coverage, creating consumer confusion about supplemental travel medical necessity and suppressing premium willingness.
- Comparison Engine Margin Compression:Aggregator platforms standardize cancellation coverage pricing, stripping differentiation from mid-tier underwriters.
- GDPR Health Data Friction:Germany's national data regulator enforces strict handling of medical declarations in digital workflows, lengthening quote-to-bind intervals.
Strategic Opportunities
- Bavaria Outbound Concentration:Germany's southern federal state exhibits outbound tourism rates exceeding national averages, warranting localized agent networks and alpine-specific adventure rider products.
- Airline Embedded Partnerships:Booking-platform integration at point-of-sale captures impulse purchasers bypassing traditional broker channels, though BaFin scrutiny over unadvised sales looms.
- Baden-Württemberg Business Travel Density:Stuttgart's manufacturing base sustains disproportionate annual multi-trip volume, supporting B2B direct enrollment programs.
Industry Challenges
- Legacy Core System Integration:Incumbent insurers struggle to connect decades-old policy administration platforms with real-time mobile claims APIs, delaying product iteration.
- Actuarial Talent Scarcity:Shortage of underwriters experienced in pandemic-era frequency modeling complicates pricing for cancellation and curtailment coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Travel Insurance Market |
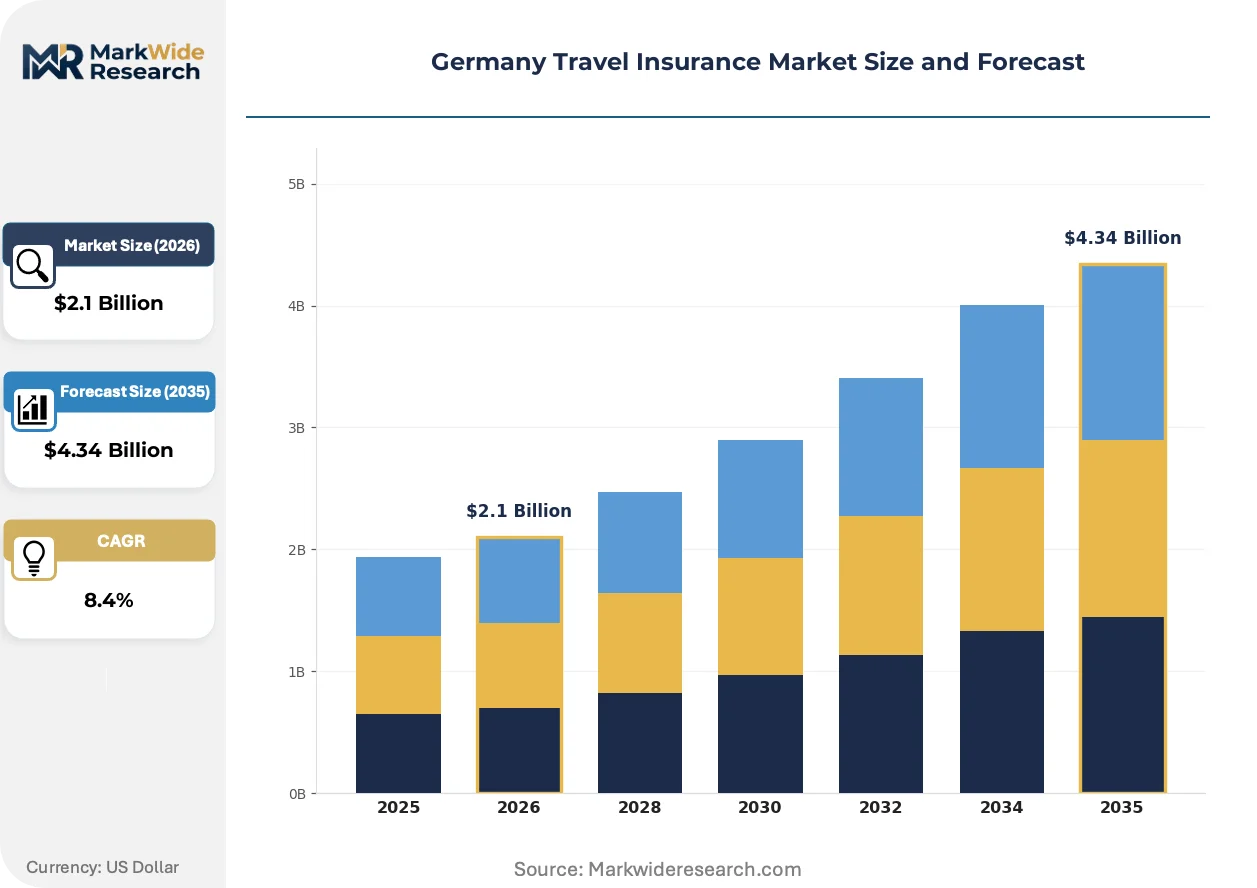
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Single Trip, Annual Multi-Trip, Long-Stay, Group Coverage Type: Medical Expenses, Trip Cancellation, Baggage Loss, Personal Liability Customer Segment: Leisure Travelers, Business Travelers, Students, Senior Citizens Distribution Channel: Insurance Agents, Online Platforms, Travel Agencies, Direct Sales |
| Companies Covered | Allianz Partners, HanseMerkur Reiseversicherung, ERGO Reiseversicherung, AXA Partners, Europ Assistance, Zurich Cover-More, Union Reiseversicherung, Würzburger TravelSecure, Berlin Direkt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Travel Insurance Market Shifts & Advancements
Digital claims processing is collapsing traditional service hierarchies while regulatory transparency mandates and demographic specialization reshape product architecture. Three developments dominate competitive positioning.
AI-powered claims triage is collapsing manual assessment queues into automated decision streams. German insurers deploy computer vision for baggage damage verification and natural language processing for medical expense validation. Frequent business travelers in Baden-Württemberg now expect same-day reimbursement, compressing legacy batch-processing economics.
BaFin's solvency and disclosure supervision tightens alongside EU-wide IDD implementation. German distributors must document suitability assessments and commission structures with granular audit trails. Smaller regional brokers face compliance cost burdens that favor consolidated direct-to-consumer platforms with embedded regulatory technology.
Retiree demand patterns are fragmenting standardized product templates. Extended-stay European coverage with pre-existing condition accommodations now commands premium positioning. Bavarian seniors increasingly bypass annual policies for modular subscription models covering variable trip durations, forcing actuarial repricing of traditional fixed-term structures.
Germany Travel Insurance Market Segmentation
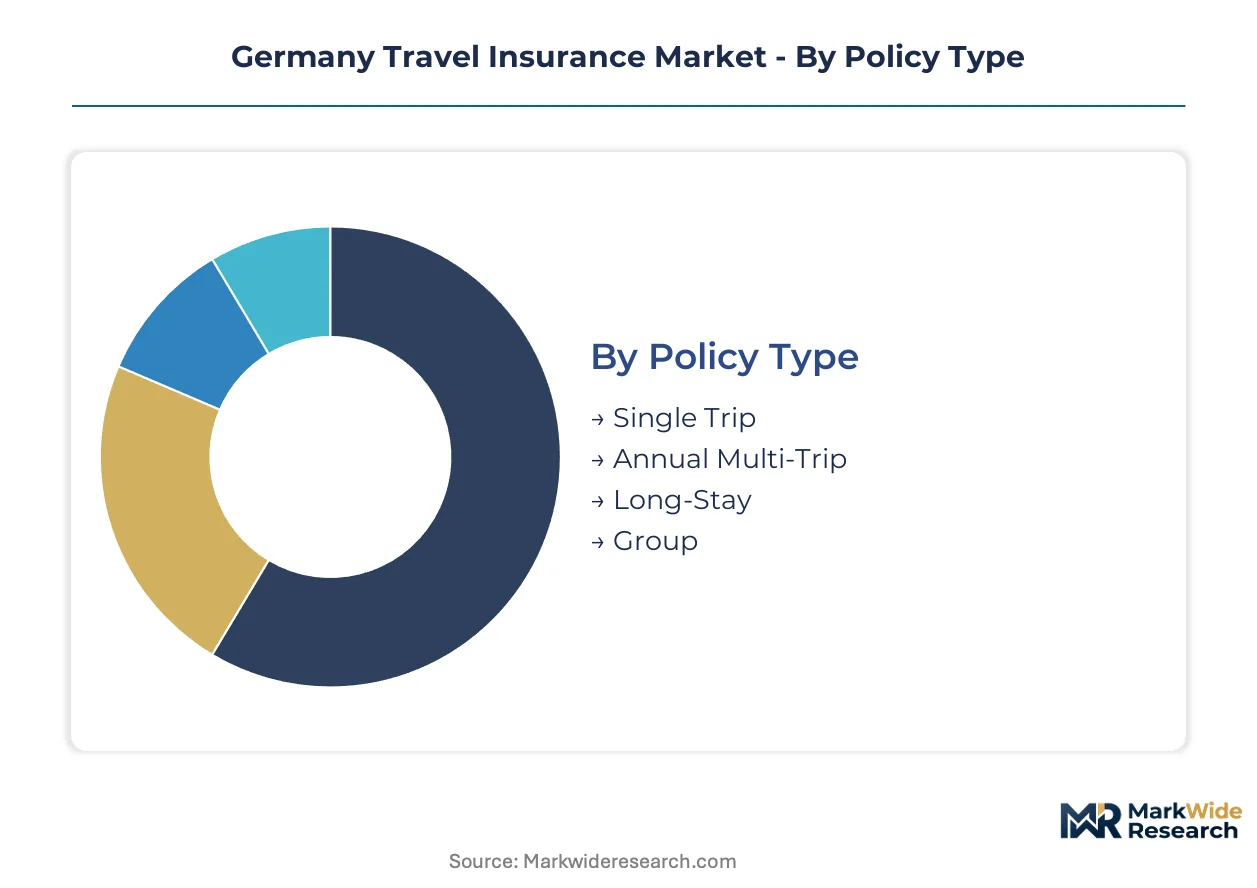
Travel insurance segmentation in Germany reflects divergent risk profiles across trip frequency, customer demographics, and distribution economics. Policy architecture varies sharply between occasional holidaymakers and frequent business travelers, while regulatory pressure from BaFin and the IDD reshapes channel economics. Understanding these fault lines clarifies where premium pools concentrate and which segments face margin compression.
Policy Type:
Cost tier differentiation separates occasional purchasers from high-frequency travelers with divergent price sensitivity and loyalty profiles.
- Single Trip:Short-duration coverage underwritten for discrete journeys with fixed departure and return dates. Bavarian leisure travelers dominate transaction volume, though aggregator-driven price transparency compresses per-policy margins.
- Annual Multi-Trip:Recurring coverage binding multiple journeys under one contract with territorial and duration caps. Baden-Württemberg business travelers sustain disproportionate value concentration given Stuttgart's manufacturing density and cross-border supplier visits.
- Long-Stay:Extended-duration policies accommodating sabbaticals, retirement travel, or seasonal residence abroad. German retirees seeking multi-month European stays drive specialized underwriting with elevated medical ceilings and pre-existing condition accommodations.
- Group:Collective coverage for organized travel parties with standardized terms and simplified enrollment. Corporate incentive trips and educational exchanges in North Rhine-Westphalia sustain modest volume.
Single Trip commands the established base. The steepest expansion runs through Annual Multi-Trip.
Coverage Type:
Application-specific protection modules align with distinct loss event probabilities and customer willingness-to-pay thresholds.
- Medical Expenses:Reimbursement for emergency treatment, hospitalization, and medical evacuation abroad. German statutory health insurance gaps outside the EU elevate this to premium priority, particularly among senior travelers in Bavaria confronting elevated health event probabilities.
- Trip Cancellation:Indemnification for non-recoverable prepaid expenditures when insured events prevent departure. Online comparison engines standardize pricing here, stripping differentiation from mid-tier underwriters and compressing attachment rates.
- Baggage Loss:Valuation-based recovery for stolen, damaged, or delayed luggage. Mobile claims platforms now deploy computer vision for damage verification, collapsing settlement cycles.
- Personal Liability:Third-party injury or property damage protection during travel activities. Adventure travel riders in alpine regions of southern Germany attach this coverage with elevated frequency.
Medical Expenses commands the established base. The steepest expansion runs through Trip Cancellation.
Customer Segment:
Volume concentration tracks demographic-specific travel patterns, risk appetites, and policy sophistication levels.
- Leisure Travelers:Occasional holidaymakers purchasing coverage episodically around vacation planning cycles. This segment concentrates in Bavaria and Baden-Württemberg where outbound tourism rates exceed national benchmarks.
- Business Travelers:Frequent journeyers requiring streamlined enrollment and rapid claims resolution. Stuttgart's automotive and engineering headquarters sustain disproportionate annual multi-trip enrollment through B2B direct programs.
- Students:Young travelers seeking budget-compliant coverage for educational exchanges and gap-year travel. University partnerships in Berlin and Munich drive seasonal enrollment spikes.
- Senior Citizens:Retirees with extended-stay patterns and elevated medical service utilization. Pre-existing condition waivers and modular subscription models are gaining traction among this cohort.
Leisure Travelers commands the established base. Senior Citizens is expanding most quickly.
Distribution Channel:
Margin architecture diverges sharply between advised sales with commission disclosure obligations and embedded digital capture at point-of-sale.
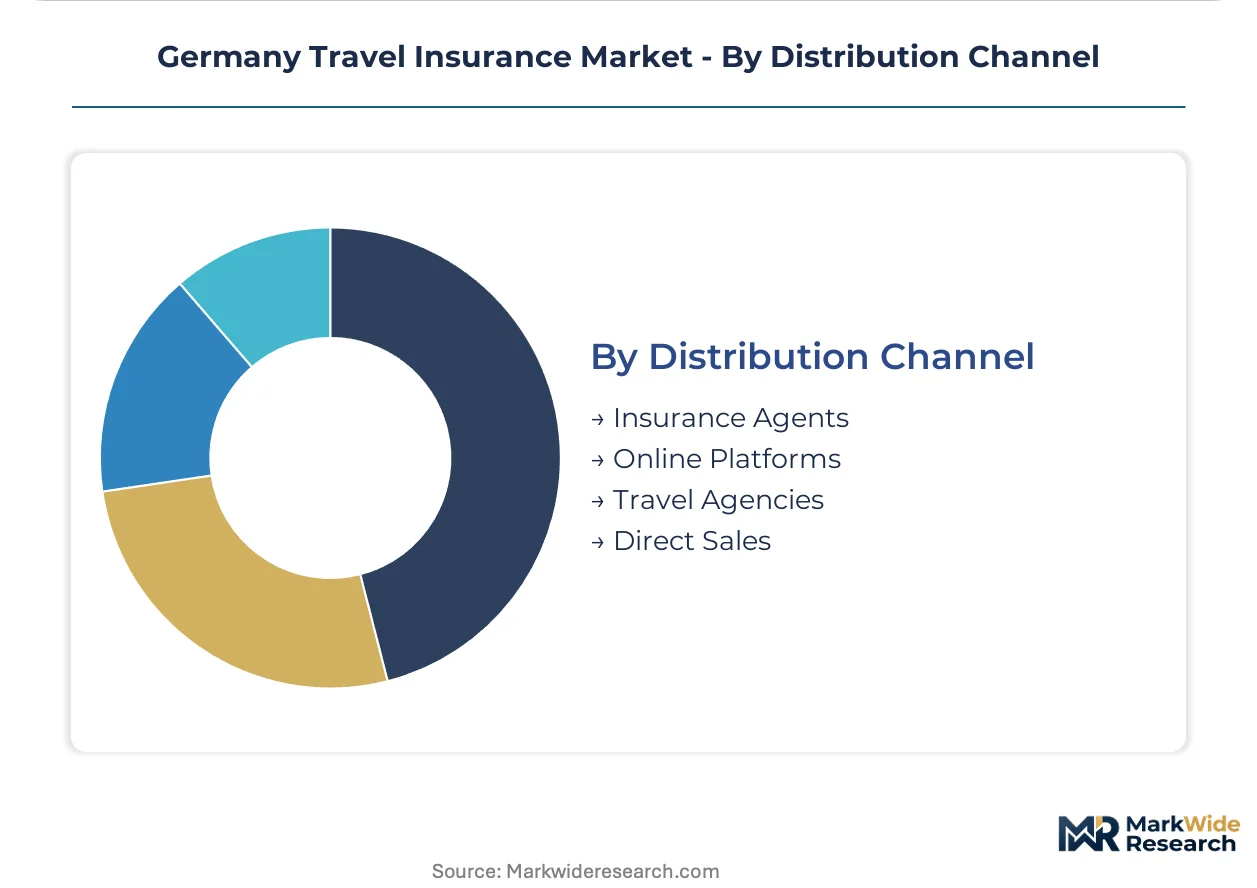
- Insurance Agents:Face-to-face advisory with documented suitability assessments under IDD requirements. Compliance cost burdens favor consolidated networks over smaller regional brokers.
- Online Platforms:Aggregator and direct-to-consumer digital channels with standardized comparison interfaces. Price transparency here strips differentiation from mid-tier underwriters.
- Travel Agencies:Bundled policy attachment at booking completion, though BaFin scrutiny over unadvised sales practices looms for embedded partnerships.
- Direct Sales:Insurer-owned channels leveraging proprietary mobile claims platforms to sustain customer relationships. Allianz Partners anchors positioning here.
Insurance Agents commands the established base. Online Platforms is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across German federal states diverge sharply, with southern regions prioritizing extended European coverage while western industrial belts favor streamlined annual business policies. This geographic fragmentation shapes localized product development and distribution investments.
Bavaria
Alpine leisure travelers and affluent retirees in Munich and Garmisch-Partenkirchen drive demand for adventure riders and multi-month European coverage. BaFin's transparency mandates compel Munich-based insurers to restructure policy disclosure workflows. The Munich-Upper Bavaria corridor sustains disproportionate single-trip transaction volume through specialized agent networks.
Baden-Württemberg
Stuttgart's automotive headquarters and engineering clusters generate concentrated annual multi-trip enrollment from cross-border supplier visits. The EU Insurance Distribution Directive forces B2B distributors toward documented suitability assessments. The Stuttgart-Mannheim industrial belt anchors direct enrollment programs targeting manufacturing sector procurement departments.
North Rhine-Westphalia
Corporate incentive travel and educational exchanges in Cologne and Düsseldorf sustain modest group policy volume. GDPR health data friction lengthens quote-to-bind intervals for digital underwriting platforms based in the Ruhr metropolitan region. Düsseldorf's financial services density supports embedded insurance partnerships with airline booking platforms.
Hesse
Frankfurt's banking and logistics workforce generates steady business travel demand with premium expectations for rapid claims resolution. BaFin scrutiny over unadvised sales practices looms for embedded partnerships targeting impulse purchasers at point-of-sale. The Frankfurt-Rhine-Main metro anchors insurer technology centers developing mobile claims APIs.
Berlin-Brandenburg
University partnerships and startup ecosystem mobility drive seasonal enrollment spikes among students and young professionals. Comparison engine margin compression strips differentiation from mid-tier underwriters competing for price-sensitive digital natives. Berlin's tech startup density incubates direct-to-consumer platforms with embedded regulatory technology.
Germany Travel Insurance Market Competitive Landscape
Capability concentration sits with specialized underwriters commanding niche actuarial expertise; scale advantage sits with diversified financial groups leveraging cross-selling infrastructure. The market structures around three tiers: integrated banking-insurance conglomerates, standalone travel specialists, and digital-native direct platforms. Strategic moves center on embedded airline partnerships and proprietary mobile claims platform deployment.
Among Germany-based specialists, HanseMerkur Reiseversicherung and Union Reiseversicherung exemplify the focused underwriter archetype, while Allianz Partners occupies a position representing the scale-driven diversified tier. These three entities anchor the competitive spectrum from niche cruise and adventure products to integrated direct-to-consumer mobile ecosystems.
| Leading Market Players |
|---|
| Allianz Partners |
| HanseMerkur Reiseversicherung |
| ERGO Reiseversicherung |
| AXA Partners |
| Europ Assistance |
| Zurich Cover-More |
| Union Reiseversicherung |
| Würzburger TravelSecure |
| Berlin Direkt |
| Others |
Supply & Pricing Matrix
Undercapacity in actuarial talent pools across German insurance hubs is compressing product development cycles and elevating pricing power for specialized underwriters who can field experienced pandemic-era risk modelers. This scarcity dynamic concentrates margin capture with incumbents possessing captive analytical capabilities while forcing price-sensitive tiers toward standardized comparison-engine offerings.
Pricing Analysis
Subscription-based annual policies dominate contract structures for frequent travelers, while single-trip coverage retains spot-market characteristics with binding at point-of-sale. Three-tier pricing structure across premium, standard, and economy levels separates Allianz Partners' integrated mobile ecosystem from HanseMerkur's specialized adventure riders and aggregator-driven generic products. Cost compression in the standard tier is intensifying because BaFin's IDD disclosure requirements elevate compliance burdens for mid-tier distributors. Students and young professionals in Berlin-Brandenburg exhibit highest price sensitivity, whereas Baden-Württemberg manufacturing executives purchasing B2B annual enrollment show lowest elasticity.
Supply Chain Analysis
Tariff exposure between German insurers and offshore IT service providers in India and Poland dominates supply chain risk planning for digital claims platform development. Proprietary mobile infrastructure draws from software engineering clusters in Berlin and Munich, cloud computing capacity in Frankfurt data centers, and legacy system integration expertise concentrated in Stuttgart and Hamburg. Single-source vulnerability in pandemic-era frequency modeling talent complicates pricing for cancellation coverage. Distribution runs through direct-to-consumer platforms, embedded airline partnerships, and residual agent networks with IDD-mandated suitability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Actuarial talent capable of modeling post-pandemic cancellation frequency and curtailment risk sits in critically short supply across German insurance labor markets, constraining product innovation velocity and compressing competitive differentiation to distribution technology and regulatory compliance infrastructure.
For Market Incumbents: Harden core system architecture against API integration failures that delay mobile claims deployment, while consolidating regional agent networks to amortize BaFin-mandated compliance costs across larger enrollment bases. Legacy platform obsolescence poses the primary existential threat; vertical integration into proprietary cloud infrastructure offers the most durable defensive lever. For New Entrants and Emerging Players: Build out modular subscription products targeting Bavarian and Baden-Württemberg retirees seeking variable-duration European coverage with pre-existing condition accommodations. Senior citizen segments remain underpenetrated by agile digital platforms. A direct-to-consumer mobile-first go-to-market angle, paired with embedded regulatory technology for GDPR-compliant health data handling, bypasses incumbent legacy constraints. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists commanding niche actuarial expertise in long-stay and adventure travel verticals, where pricing power persists outside comparison-engine commoditization. Five-to-ten year viability hinges on successful technology modernization rather than scale economics alone. The signal to watch is embedded insurance partnership regulatory clearance from BaFin, which would validate alternative distribution economics at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Mobile Claims Platform Deployment | Allianz Partners' same-day reimbursement capability compresses legacy batch-processing economics and elevates retention. |
| Embedded Airline Partnership Expansion | Point-of-sale integration at booking platforms captures impulse purchasers bypassing traditional broker channels. |
| Actuarial Talent Acquisition Program | Pandemic-era frequency modeling expertise enables sustainable pricing for cancellation and curtailment coverage. |
| Legacy Core System Modernization | API connectivity with real-time mobile claims infrastructure accelerates product iteration cycles. |
| GDPR-Compliant Health Data Infrastructure | Embedded regulatory technology shortens quote-to-bind intervals and defends against national data regulator enforcement. |
Research Methodology
A standing panel of travel insurance product managers, BaFin supervisory specialists, airline partnership directors, and claims technology architects provided ongoing calibration against market developments throughout the study period. Primary interviews with underwriting executives at Munich and Stuttgart headquarters combined with secondary validation from BaFin disclosure filings, EU Insurance Distribution Directive implementation reports, and German outbound tourism statistics from federal state tourism boards. Bottom-up enrollment data triangulated against top-down premium pool estimates derived from statutory health insurance coverage gap analysis.
Scenario-bracketing around regulatory enforcement intensity, embedded partnership adoption curves, and actuarial talent availability shaped the analytical framework across the analysis window. Segmentation dimensions modeled include policy type, coverage module, customer demographic, and distribution channel, with regional federal state variation as an additional cross-cutting dimension. CAGRs were derived from trend extrapolation adjusted for structural breakpoints in pandemic-era claims frequency. Forecast inputs incorporated mobile claims platform penetration rates and IDD compliance cost trajectories.
Stress conditions across BaFin enforcement stringency, airline partnership regulatory clearance timing, and senior citizen subscription model adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about sustained outbound tourism recovery and stable EU health coverage coordination frameworks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
GCC Health Insurance Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
Cyber Insurance Market
Insurance
Germany Property and Casualty Insurance Market
Insurance
Asia-Pacific EV Insurance Market
Insurance
Cloud Computing in Insurance Market
Insurance
Marine Crew Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Europe Car Insurance Market
Insurance
Aircraft Insurance Market
Insurance
Commercial Earthquake Insurance Market
Insurance
Switzerland Reinsurance Market
Insurance
Cannabis Crop Insurance Market
Insurance
Online Insurance Market
Insurance
Europe EV Insurance Market
Insurance
Singapore Property and Casualty Insurance Market