
 Solar Panel Warranty Insurance Market | 2026-2036
Solar Panel Warranty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Panel Warranty Insurance Market Analysis
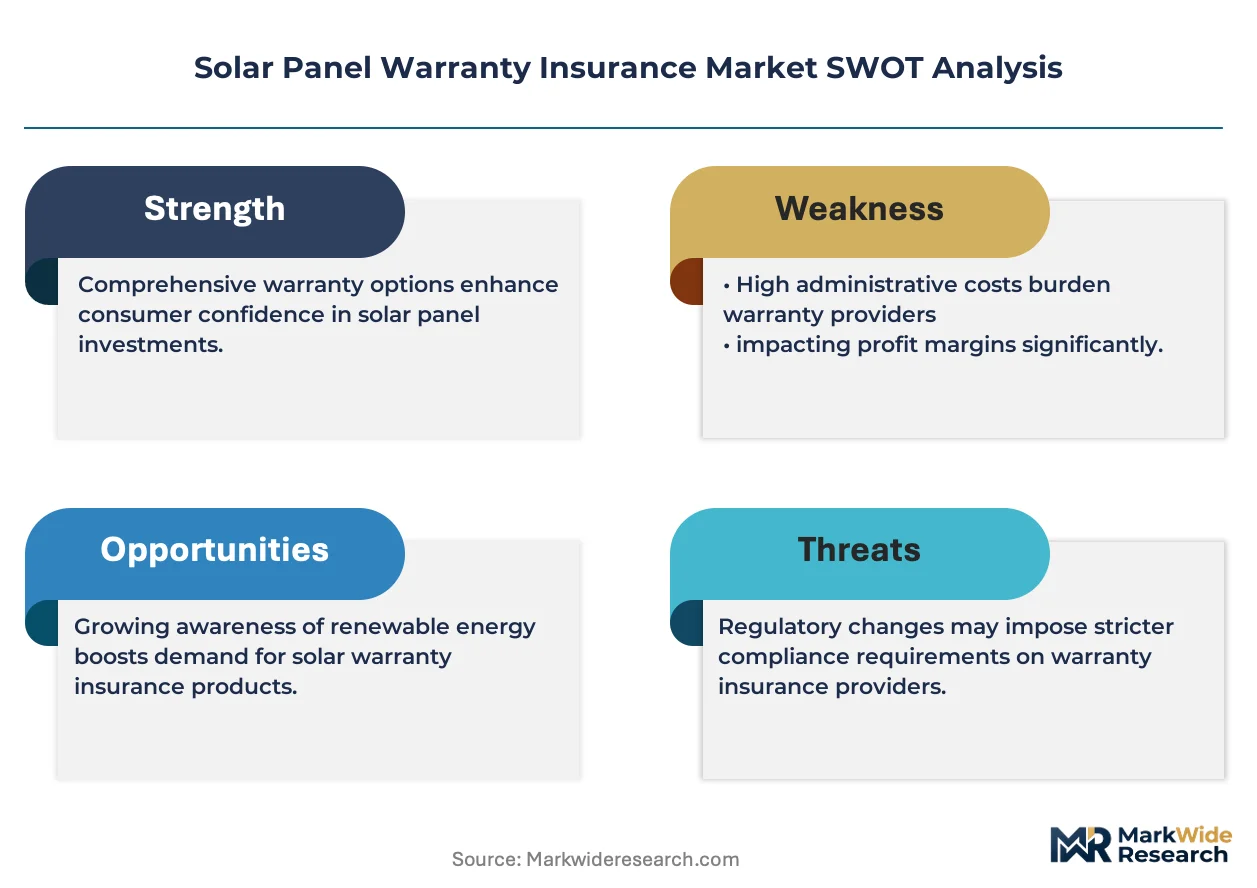
Broker-sourced warranty coverage is reconfiguring how residential and commercial solar projects secure long-term protection. Solar Insure leverages its installer network to control policy distribution across high-volume state markets. Qcells sustains competitive positioning through captive warranty programs tied to its module manufacturing base. NRG Clean Power anchors its growth in California's retrofit-heavy residential segment where legacy system coverage gaps persist.
Solar panel warranty insurance constitutes a risk-transfer instrument covering photovoltaic module defects, performance degradation, and installation workmanship failures over contractually defined periods, typically spanning 10 to 25 years depending on coverage tier. The product serves to protect capital deployed in solar generation assets against revenue loss from underperformance or premature equipment replacement. Comprehensive policies command premium positioning as they bundle module, inverter, and labor coverage into single instruments, while performance guarantee products attract utility-scale buyers seeking production-linked protection. Third-party administrators occupy a growing structural role by adjudicating claims and managing installer credentialing programs that determine policy eligibility.
The US Inflation Reduction Act and state-level contractor licensing boards shape warranty insurance demand through domestic content incentives and installation quality mandates. NABCEP certification requirements in multiple states restrict market access to installers carrying approved coverage, directly expanding addressable premium pools. Stakeholders must monitor evolving state net metering successor tariffs and their impact on residential system payback periods, as these determine homeowner willingness to purchase extended warranty protection beyond standard manufacturer terms.
Market Dynamics
The IRA's domestic content bonus credits are forcing warranty insurers to restructure coverage terms for US-manufactured modules, creating divergent policy frameworks that segment the market by module origin and installer certification tier.
Growth Catalysts
- NABCEP Certification Mandates:State-level contractor licensing boards in California, Texas, and Florida now require approved warranty coverage for installer credentialing, directly expanding premium pools as uncertified operators exit these markets.
- Net Metering Successor Tariffs:California's NEM 3.0 and similar successor policies in high-irradiance states compress residential payback periods, prompting homeowners to purchase extended warranty protection beyond standard manufacturer terms.
- Performance Guarantee Products:Utility-scale buyers seeking production-linked protection drive demand for instruments that bundle module, inverter, and labor coverage into single comprehensive policies with 20-25 year terms.
Market Restraints
- Actuarial Data Scarcity:Limited historical claims data for newer module technologies—particularly heterojunction and perovskite tandem cells—constrains underwriters' ability to price long-tail degradation risk accurately.
- Installer Network Concentration:Broker-sourced coverage depends on credentialed installer density, creating coverage gaps in rural markets where NABCEP-certified contractors remain sparse and policy distribution costs escalate.
- Module Manufacturer Captive Programs:Vertically integrated manufacturers offering bundled warranty protection limit addressable market for third-party insurers, compressing premium growth in segments dominated by Qcells and similar suppliers.
Strategic Opportunities
- Retrofit System Coverage:California's legacy residential installations—many with expired manufacturer warranties—present underserved demand for third-party protection as homeowners seek to preserve asset value ahead of inverter replacement cycles.
- Third-Party Administrator Expansion:Claims adjudication and installer credentialing services represent adjacent revenue streams as insurers outsource policy management to specialized administrators with field inspection capabilities.
- Commercial Installer Segment:Distributed solar deployment acceleration across Texas and Florida creates concentrated demand from commercial installers requiring workmanship coverage for multi-site portfolios with standardized risk profiles.
Industry Challenges
- Claims Verification Complexity:Distinguishing between module defects, installation workmanship failures, and environmental degradation requires specialized field engineering capacity that strains insurer technical resources.
- Credentialing Program Management:Maintaining installer eligibility databases across evolving state requirements demands continuous operational investment as NABCEP standards and state reciprocity agreements shift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Panel Warranty Insurance Market |
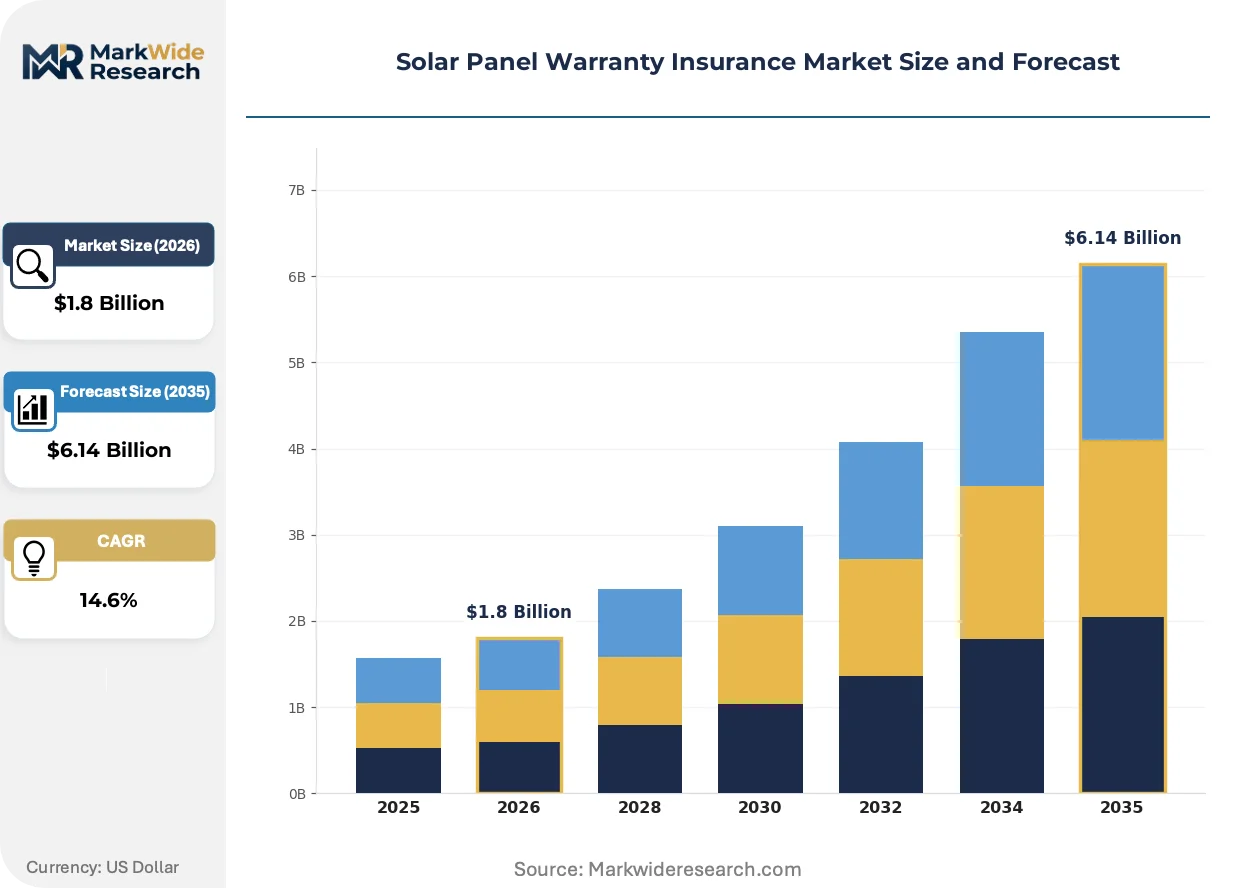
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Comprehensive, Partial Coverage, Limited, Performance Guarantee Provider Type: Insurance Companies, Third-party Administrators, Industry Associations, Brokers End User: Residential Clients, Commercial Installers, Utilities, Contractors Policy Terms: Short-term, Medium-term, Long-term, Multi-year |
| Companies Covered | NRG Clean Power, Semper Solaris, Solar Insure, REC, Silfab, Solar Energy World, SunPower by Sun Solar, Qcells, Ameco Solar & Roofing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Panel Warranty Insurance Market Emerging Trajectories
Digital telemetry integration and automated performance monitoring are compressing claims cycles and enabling predictive underwriting models that shift warranty insurance from reactive indemnification toward proactive risk management.
Embedded module-level power electronics with granular production data streams are rendering obsolete traditional warranty structures that rely on periodic manual inspection and estimated degradation curves. Commercial and utility-scale asset managers now demand real-time performance verification as a condition of coverage, compressing settlement timelines from quarters to weeks. This telemetry dependency is creating tiered insurer capabilities split between data-integrated underwriters and legacy operators dependent on physical site assessments.
The Inflation Reduction Act's domestic content bonus credits are bifurcating warranty requirements between US-manufactured and imported modules, with coverage terms now explicitly tied to supply chain documentation. Insurers must verify module origin through bill-of-materials tracing to qualify policies for bonus credit eligibility, adding compliance layers that favor established underwriters with supplier audit relationships. Texas and California installers report this documentation burden as a primary friction point in policy placement.
After-sales service unbundling is disrupting traditional manufacturer-captive warranty models as independent service providers seek third-party coverage to compete on retrofit and O&M contracts. Commercial asset owners in Florida now separate warranty procurement from module purchase, creating channel openings for broker-sourced instruments with flexible term structures. This disaggregation is most visible in the commercial retrofit segment where legacy system owners prioritize coverage portability over manufacturer affiliation.
Solar Panel Warranty Insurance Market Segmentation
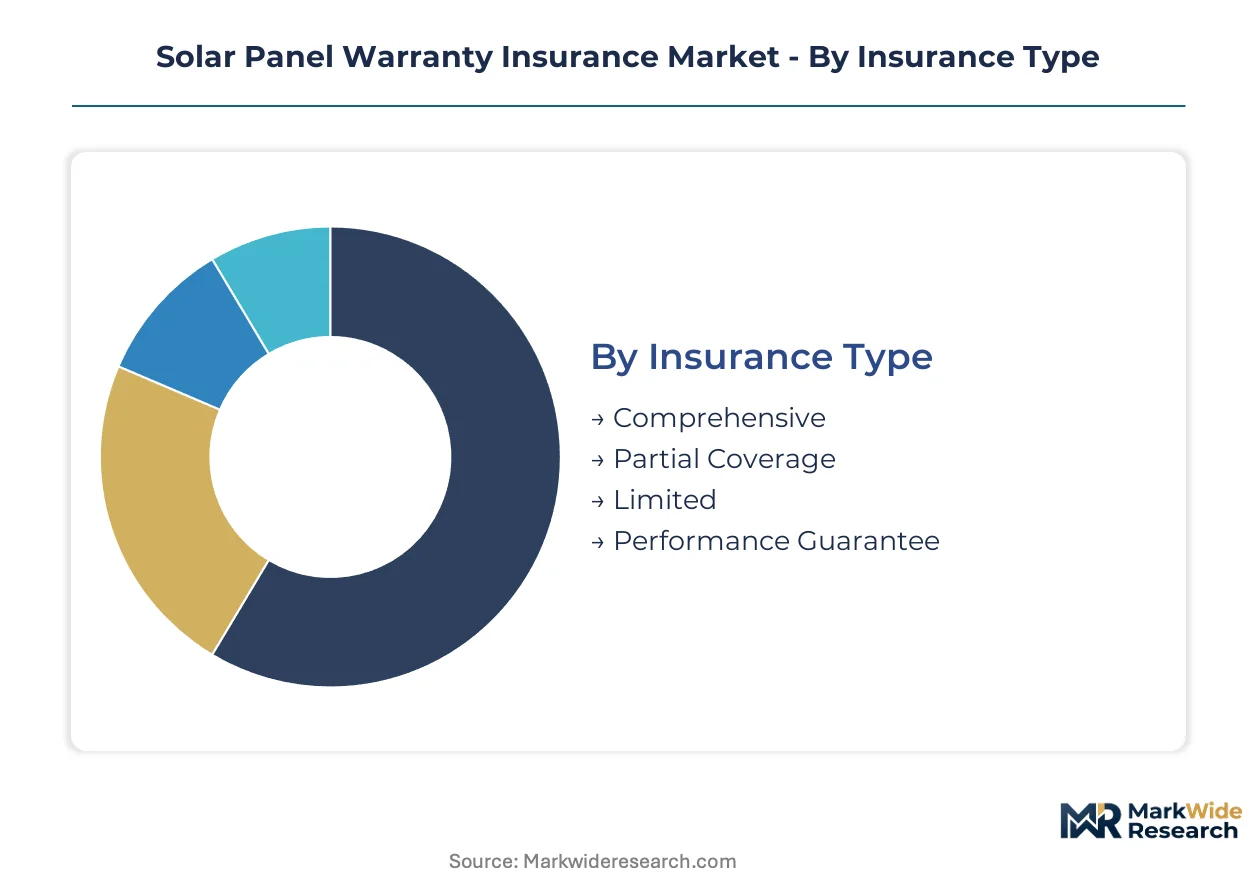
Warranty insurance segmentation determines which risk-transfer instruments match specific asset classes and buyer sophistication levels. Coverage depth, provider structure, and contract duration create distinct commercial zones with divergent margin profiles and underwriting complexity.
Insurance Type:
After-sales-service intensity varies dramatically across coverage tiers, with comprehensive policies demanding continuous claims adjudication and field engineering capacity while limited products operate on automated renewal cycles.
- Comprehensive:Bundles module defect, inverter failure, and labor coverage into single instruments with 20-25 year terms. Commercial installers in Texas and Florida concentrate demand here as distributed solar portfolios require standardized protection across multi-site deployments.
- Partial Coverage:Excludes specific failure modes—typically workmanship or inverter replacement—to achieve lower premium positioning. Residential clients in California's NEM 3.0 environment select this tier to manage payback-period compression without sacrificing core module protection.
- Limited:Restricts protection to named perils with capped liability schedules. Compact option for legacy system owners seeking basic asset preservation ahead of equipment replacement cycles.
- Performance Guarantee:Production-linked instruments tied to verified telemetry data rather than equipment replacement. Utility-scale buyers favor this structure for revenue certainty in power purchase agreements.
By volume, Comprehensive leads. By growth pace, Performance Guarantee is ahead.
Provider Type:
Cost tier stratification separates established underwriters with captive actuarial departments from lean administrators outsourcing risk-bearing to reinsurance markets.
- Insurance Companies:Balance sheet underwriters pricing long-tail degradation risk through proprietary actuarial models. Limited historical claims data for heterojunction and perovskite technologies constrains their expansion into next-generation module coverage.
- Third-party Administrators:Manage claims adjudication and installer credentialing without bearing underwriting risk. Fastest-climbing segment as insurers outsource operational complexity to specialists with field inspection networks.
- Industry Associations:Facilitate group purchasing arrangements leveraging collective bargaining power. Concentrated in state markets with mandatory NABCEP certification requirements.
- Brokers:Control policy distribution through credentialed installer networks. Solar Insure exemplifies this model's geographic concentration in high-volume state markets.
Third-party Administrators dominate transaction volume. Insurance Companies capture premium value.
End User:
Application-specific requirements fragment the buyer base across residential sophistication levels, commercial scale economies, and utility procurement protocols.
- Residential Clients:Homeowners purchasing extended protection beyond manufacturer terms. California's retrofit-heavy segment shows persistent demand for legacy system coverage as original warranties expire.
- Commercial Installers:Require workmanship coverage for multi-site portfolios with standardized risk profiles. This segment expands most quickly as distributed solar deployment accelerates across Texas and Florida.
- Utilities:Demand production-linked instruments with real-time performance verification. Procurement specifications now mandate telemetry integration as a coverage condition.
- Contractors:Seek credentialing-compliant policies to maintain NABCEP eligibility in regulated state markets. Coverage portability matters more than manufacturer affiliation for this group.
Commercial Installers lead absolute premium generation. Residential Clients show steepest expansion trajectory.
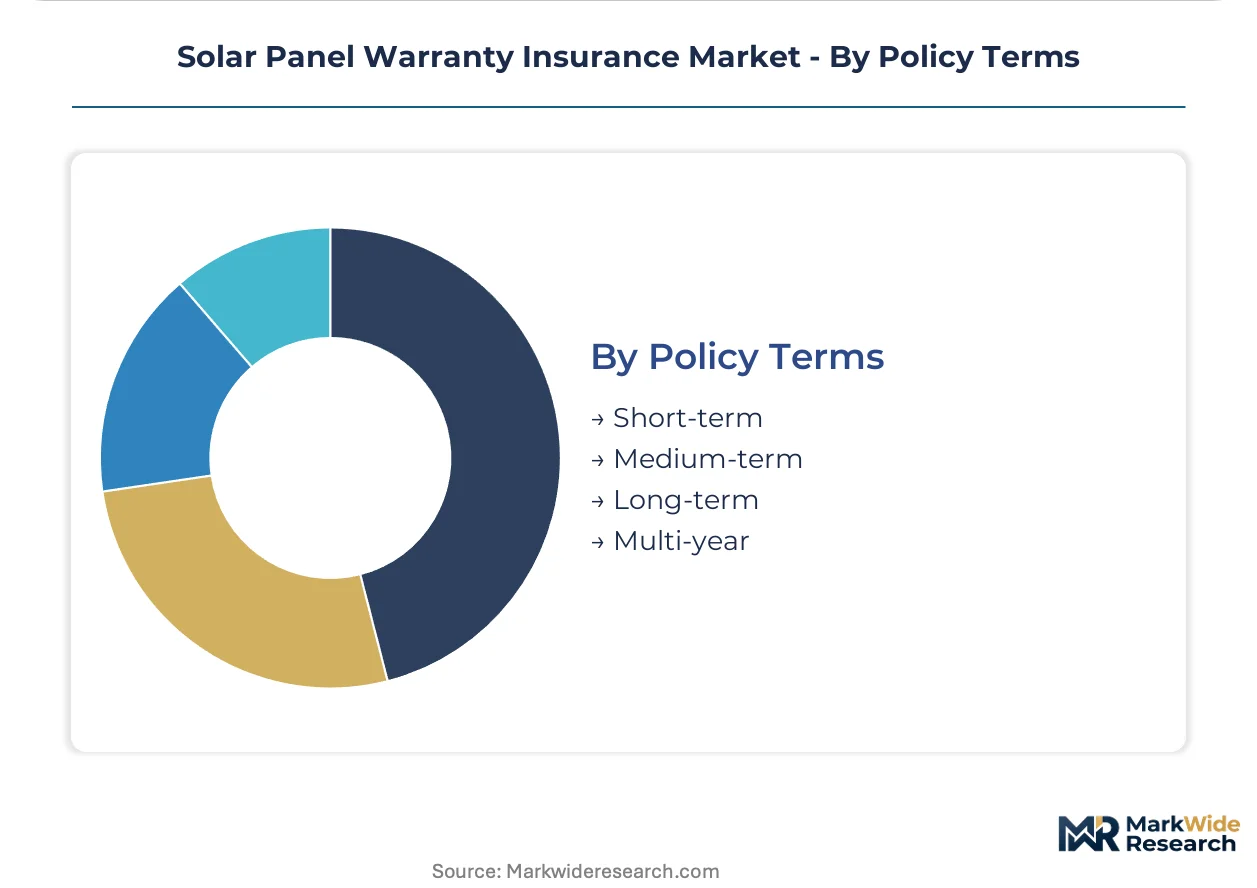
Policy Terms:
Maturity-based pricing separates short-cycle administrative products from capital-intensive long-tail instruments requiring dedicated reserves.
- Short-term:Annual renewable contracts for transitional coverage during ownership changes or equipment upgrades. Thin margins reflect minimal claims exposure.
- Medium-term:5-10 year structures bridging manufacturer warranty gaps. Popular among commercial asset owners seeking coverage alignment with financing tenors.
- Long-term:15-25 year instruments matching asset economic life. Concentrated actuarial risk as degradation curves extend beyond available historical data.
- Multi-year:Pre-paid policies with locked premium rates. Favored by utilities hedging against future pricing volatility in long-dated power purchase agreements.
Long-term policies anchor premium value. Multi-year structures gain share fastest in utility procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US interstate transmission grid expansion through Texas's Competitive Renewable Energy Zones underwrites North America's warranty insurance concentration. Germany's HVDC corridor links to Nordic hydro capacity anchor European demand. China's ultra-high voltage backbone shapes Asia-Pacific market structure.
United States
California's NEM 3.0 successor tariff compresses residential payback periods and prompts extended warranty purchases beyond manufacturer terms. The IRA's domestic content bonus credits force insurers to verify module origin through bill-of-materials tracing. Installer density concentrates in Los Angeles Basin and Central Valley markets where NABCEP-certified contractors control policy distribution.
Germany
Commercial rooftop deployment across Bavaria and North Rhine-Westphalia drives demand for multi-site portfolio coverage with standardized risk profiles. The EU Green Deal's accelerated solar targets interact with Germany's EEG feed-in tariff revisions to reshape warranty term structures. Munich and Frankfurt host the densest installer networks for third-party administrator partnerships.
China
Utility-scale project pipelines in Xinjiang and Inner Mongolia require production-linked instruments with real-time telemetry verification. MIIT's module quality certification standards create tiered eligibility for warranty coverage based on manufacturer testing protocols. Yangtze River Delta provinces concentrate third-party administrator capacity for claims adjudication.
India
Gujarat and Rajasthan's solar parks generate concentrated demand from commercial asset owners seeking coverage portability separate from module purchase. The PLI scheme's domestic manufacturing incentives intersect with CEA grid connectivity standards to determine warranty eligibility tiers. Mumbai and Ahmedabad anchor broker-sourced distribution networks.
Australia
Queensland and New South Wales residential markets show persistent retrofit demand as legacy system warranties expire ahead of inverter replacement cycles. The Clean Energy Council's installer accreditation requirements restrict policy placement to credentialed contractors. Sydney and Melbourne concentrate third-party administrator field inspection capacity.
Solar Panel Warranty Insurance Market Vendor Landscape
On the supply side, the industry is bifurcated between balance-sheet underwriters pricing long-tail degradation risk and lean administrators outsourcing risk-bearing to reinsurance markets. Strategic archetypes include broker-sourced distributors controlling installer networks, captive warranty programs tied to module manufacturing bases, and third-party administrators managing claims adjudication. Dominant competitive moves center on geographic expansion into high-irradiance state markets and portfolio diversification into retrofit system coverage.
Within the broker-sourced distribution tier, Solar Insure and NRG Clean Power exemplify network-dependent models concentrated in California and Texas high-volume markets. Qcells occupies a position representing captive warranty programs that bundle module protection with manufacturing origin, constraining addressable market for third-party instruments in segments dominated by vertically integrated suppliers. These three anchors illustrate how provider structure determines competitive zone—network control, manufacturing affiliation, or administrative specialization.
| Leading Market Players |
|---|
| NRG Clean Power |
| Semper Solaris |
| Solar Insure |
| REC |
| Silfab |
| Solar Energy World |
| SunPower by Sun Solar |
| Qcells |
| Ameco Solar & Roofing |
| Others |
Supply Flow & Price Mechanics
Undercapacity in NABCEP-certified installer networks across California's Central Valley and Texas's Permian Basin corridors drives premium pricing for broker-sourced coverage while forcing insurers to absorb elevated policy distribution costs. This utilization squeeze concentrates pricing power with credentialed installer networks and compels third-party administrators to extend supplier financing terms to maintain field inspection capacity.
Pricing Analysis
Volume-discount tiering structures stratify across premium comprehensive policies, standard partial coverage, and economy limited protection tiers. Premium differentiation hinges on NABCEP certification grade and telemetry integration depth, with real-time performance verification commanding substantial markups over inspection-dependent alternatives. Price erosion runs through the limited coverage tier as legacy system owners prioritize basic asset preservation over bundled protection. Commercial installers in multi-site portfolios exhibit lowest price sensitivity due to standardized risk profile efficiencies, while residential retrofit clients in California's NEM 3.0 environment demonstrate acute cost consciousness.
Supply Chain Analysis
Extended payment terms from reinsurance markets to third-party administrators anchor supplier financing flows, with 90-120 day cycles now standard for claims adjudication services. Module manufacturing concentrates in China, South Korea, and Vietnam, while installer credentialing capacity clusters in California, Texas, and Florida. Polysilicon supply, encapsulant materials, and aluminum framing constitute critical input dependencies. Tariff exposure on imported modules creates documentation compliance burdens that favor established underwriters with supplier audit relationships. Distribution runs through broker-sourced installer networks rather than direct carrier channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among commercial installers operating multi-site portfolios, fragmenting the historically dispersed residential segment and reshaping procurement leverage across the warranty insurance value chain.
For Market Incumbents: Pre-empt captive warranty program expansion by Qcells and vertically integrated manufacturers through exclusive NABCEP-certified installer network lockups in California and Texas. Invest in telemetry-integrated underwriting capabilities before real-time performance verification becomes a mandatory coverage condition for utility-scale procurement. Certification tier differentiation serves as the priority defensive lever against margin compression. For New Entrants and Emerging Players: Build out third-party administrator capabilities in Florida's commercial retrofit segment, where legacy system owners seek coverage portability separate from module purchase. Target Australia's Queensland and New South Wales residential markets, where Clean Energy Council accreditation requirements create barrier-protected demand pools. Lead with automated claims adjudication technology to compress settlement timelines from quarters to weeks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across third-party administrator segments as operational scale economies in claims processing compress unit costs. Long-term viability favors acquisition targets with established field inspection networks and installer credentialing databases rather than balance-sheet underwriters exposed to heterojunction technology actuarial uncertainty. Monitor domestic content bonus credit compliance rates as the inflection signal for policy placement momentum shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Integration Investment | Real-time performance verification compresses claims cycles from quarters to weeks for utility buyers. |
| NABCEP Certification Expansion | Credentialing density in California and Texas directly expands addressable premium pools. |
| Retrofit System Coverage Launch | Legacy residential installations with expired warranties present underserved demand in California. |
| Domestic Content Compliance Program | Bill-of-materials tracing capability qualifies policies for IRA bonus credit eligibility. |
| Third-Party Administrator Acquisition | Claims adjudication specialization captures operational outsourcing trends from balance-sheet underwriters. |
Methodological Framework
The analysis maps comprehensive, partial, limited, and performance guarantee coverage tiers, each validated through installer network heads, claims adjudication officers, and reinsurance placement specialists. Primary interviews with NABCEP-certified contractors, third-party administrator operations directors, and utility procurement managers combined with secondary validation against FERC filings, EIA project databases, state contractor licensing board records, and IRA domestic content guidance. Bottom-up policy volume estimates triangulated against top-down premium pool calculations.
Assumptions held fixed include NABCEP certification reciprocity agreements across state markets and continued IRA domestic content bonus credit availability, while module technology substitution rates and net metering successor tariff structures were varied across sensitivity scenarios. Segmentation dimensions modeled span insurance type, provider structure, end-user archetype, and policy term maturity. CAGRs derived from installer deployment trajectories and warranty penetration curves. Forecast inputs incorporated heterojunction and perovskite technology degradation uncertainty and commercial distributed solar acceleration patterns.
Stress conditions across installer certification density, module origin documentation compliance, and claims frequency volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions; macroeconomic contraction, federal incentive modification, or breakthrough module reliability improvements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Marine Crew Insurance Market
Insurance
Global Flood Insurance Market
Insurance
Asia-Pacific Surety Market
Insurance
Canada House Insurance Market
Insurance
Cancer Insurance Market
Insurance
USA Travelers Insurance Market
Insurance
France Liability Insurance Market
Insurance
B2B2C Insurance Market
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
AI in Insurance Market
Insurance
Europe Bancassurance Market
Insurance
Europe Travel Insurance Market
Insurance
Bancassurance in ASEAN Market
Insurance
United States Insurance Brokerage Market
Insurance
India Parametric Insurance Market
Insurance
Digital Innovation in Insurance Market