
 Global Property and Casualty Reinsurance Market | 2026-2036
Global Property and Casualty Reinsurance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Property and Casualty Reinsurance Market Outlook
The EU Green Deal is consolidating demand for climate-resilient reinsurance structures across European cedents. Munich Re leverages its proprietary catastrophe modeling to sustain pricing power in natural peril lines. Swiss Re anchors global capacity for parametric solutions, while Hannover Re competes aggressively in specialty casualty treaties across Lloyd's syndicates and international markets.
Property and Casualty Reinsurance involves the transfer of insurance risk from primary insurers to specialized capital providers, utilizing treaty structures with defined attachment points, limits, and reinstatement provisions to stabilize cedent balance sheets against correlated losses. Catastrophe Reinsurance commands the deepest margin pools due to peak peril concentration in Florida and Japan, while Specialty Reinsurance extends fastest through cyber and intellectual property liability emergence. Proportional Reinsurance dominates premium volume through Quota Share arrangements, though Non-Proportional Reinsurance captures disproportionate profit in hardening casualty cycles.
Solvency II in Europe, the Bermuda Monetary Authority's insurance code, and state-level surplus lines regulation in the US collectively shape capital adequacy thresholds and cross-border market access for reinsurance placements. The National Association of Insurance Commissioners coordinates US credit-for-reinsurance standards that determine collateral requirements for offshore carriers. Stakeholders must monitor evolving climate scenario testing mandates and their compression of retrocession capacity.
Market Dynamics
Climate volatility is compressing retrocession capacity and forcing cedents to restructure catastrophe tower placements across peak peril zones. Solvency II capital charges and Bermuda Monetary Authority solvency frameworks are simultaneously reshaping where carriers domicile their specialty books.
Growth Catalysts
- EU Green Deal climate stress testing:European cedents must embed physical risk scenarios into Own Risk and Solvency Assessments, driving demand for parametric covers and model-based pricing.
- Florida wind market dislocation:Citizens Property Insurance cessions to private reinsurers are expanding treaty limits as state-backed capacity retreats from coastal exposure.
- Cyber peril modeling advances:RMS and AIR frameworks now capture systemic accumulation risk, enabling underwriters to price standalone cyber treaties with defined event triggers.
Market Restraints
- Retrocession capacity scarcity:Collateralized markets in Bermuda and London have contracted by half since peak peril years, forcing primary carriers to retain more net catastrophe exposure.
- Long-tail casualty reserving uncertainty:US asbestos and environmental liabilities continue developing adversely, compressing capacity for specialty casualty treaties at Lloyd's.
- Interest rate volatility:Duration mismatches in fixed-income portfolios are eroding investment income offsets for European life reinsurers with property-casualty hybrids.
Strategic Opportunities
- India regulatory opening:IRDAI's 2022 reinsurance liberalization permits foreign carriers to establish branches in Mumbai, GIFT City, and Chennai without mandatory cessions to GIC Re.
- Parametric agriculture expansion:Satellite-indexed drought and flood covers are penetrating Sub-Saharan African and Southeast Asian markets previously unserved by traditional indemnity structures.
- US Inflation Reduction Act risk transfer:Renewable energy project financiers require construction and operational all-risk covers with battery storage peril extensions.
Industry Challenges
- Catastrophe modeler talent scarcity:Demand for geospatial data scientists and climate physicists exceeds supply across Bermuda, Zurich, and Singapore underwriting hubs.
- Legacy system integration friction:Cedents with 1990s-era policy administration platforms face API incompatibility when placing facultative risks through digital placement platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Property and Casualty Reinsurance Market |
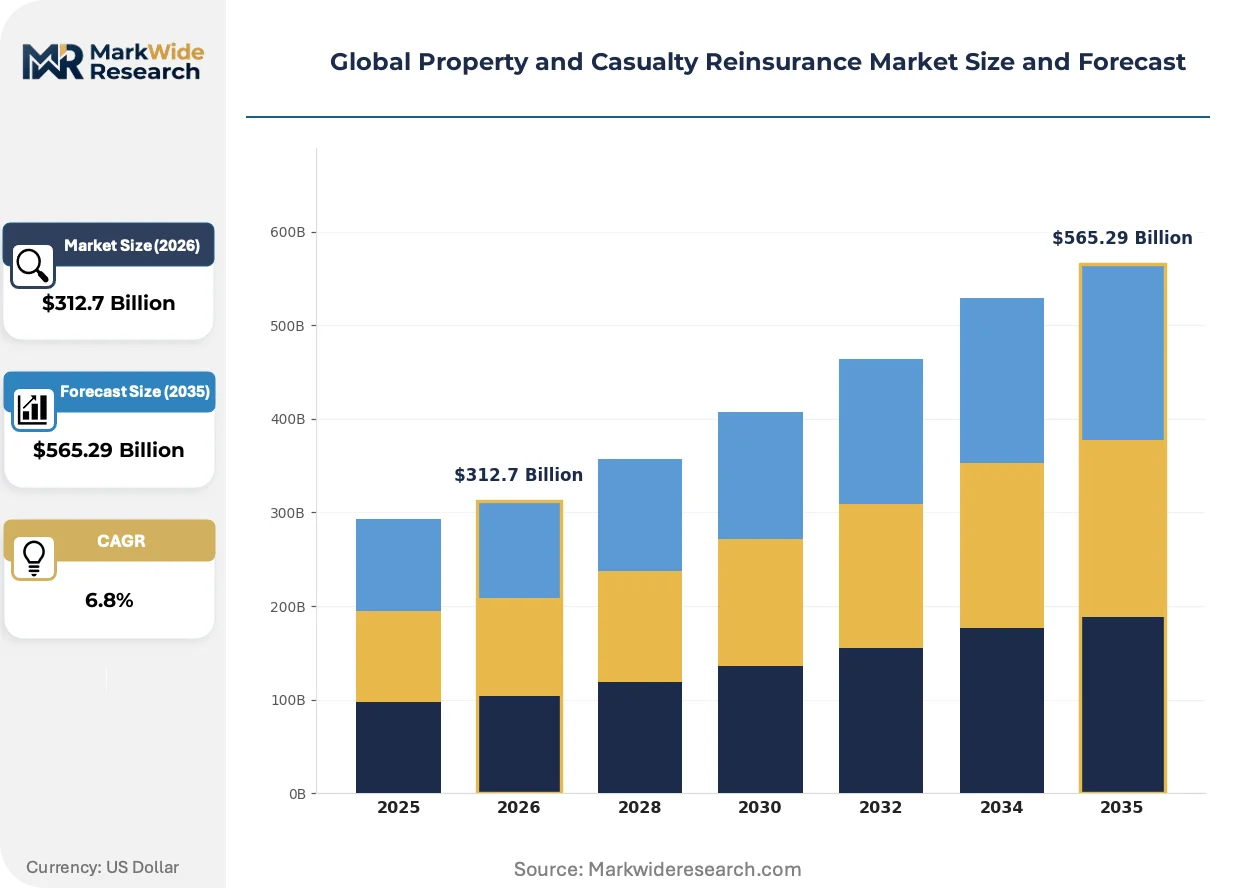
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Property Reinsurance, Casualty Reinsurance, Specialty Reinsurance, Catastrophe Reinsurance Distribution Channel: Brokers, Direct Sales, Online Platforms, Reinsurers Service Type: Proportional Reinsurance, Non-Proportional Reinsurance, Excess of Loss, Quota Share End User: Insurance Companies, Mutual Insurers, Captive Insurers, Self-Insured Entities |
| Companies Covered | Munich Re, Swiss Re, Berkshire Hathaway, Lloyd’s, Hannover Re, SCOR SE, Reinsurance Group of America, Everest Group, RenaissanceRe Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Property and Casualty Reinsurance Market Strategic Shifts
Digital placement infrastructure and alternative capital structures are compressing placement cycles from months to weeks. Machine learning is penetrating catastrophe modeling, while regulatory disclosure mandates are forcing transparency into previously opaque treaty terms.
Artificial intelligence-driven exposure analytics is expanding into property underwriting workflows. Swiss Re and Munich Re are deploying computer vision for real-time building vulnerability assessment. This compression of data acquisition timelines is expanding into pricing granularity for commercial property treaties.
EU CSRD sustainability disclosure requirements are mandating climate risk quantification in reinsurance cession decisions. European cedents must now report Scope 3 emissions from their insurance portfolios. This regulatory pressure is expanding into demand for certified green reinsurance structures with verified carbon offset mechanisms.
Cedents are unbundling traditional bundled treaty services and purchasing analytics, capital relief, and claims handling separately. Large commercial insurers in London and New York are direct-placing peak risks through broker-owned digital platforms. This disintermediation is concentrating in Florida wind and Japanese earthquake programs where standardization permits algorithmic pricing.
Global Property and Casualty Reinsurance Market Segmentation
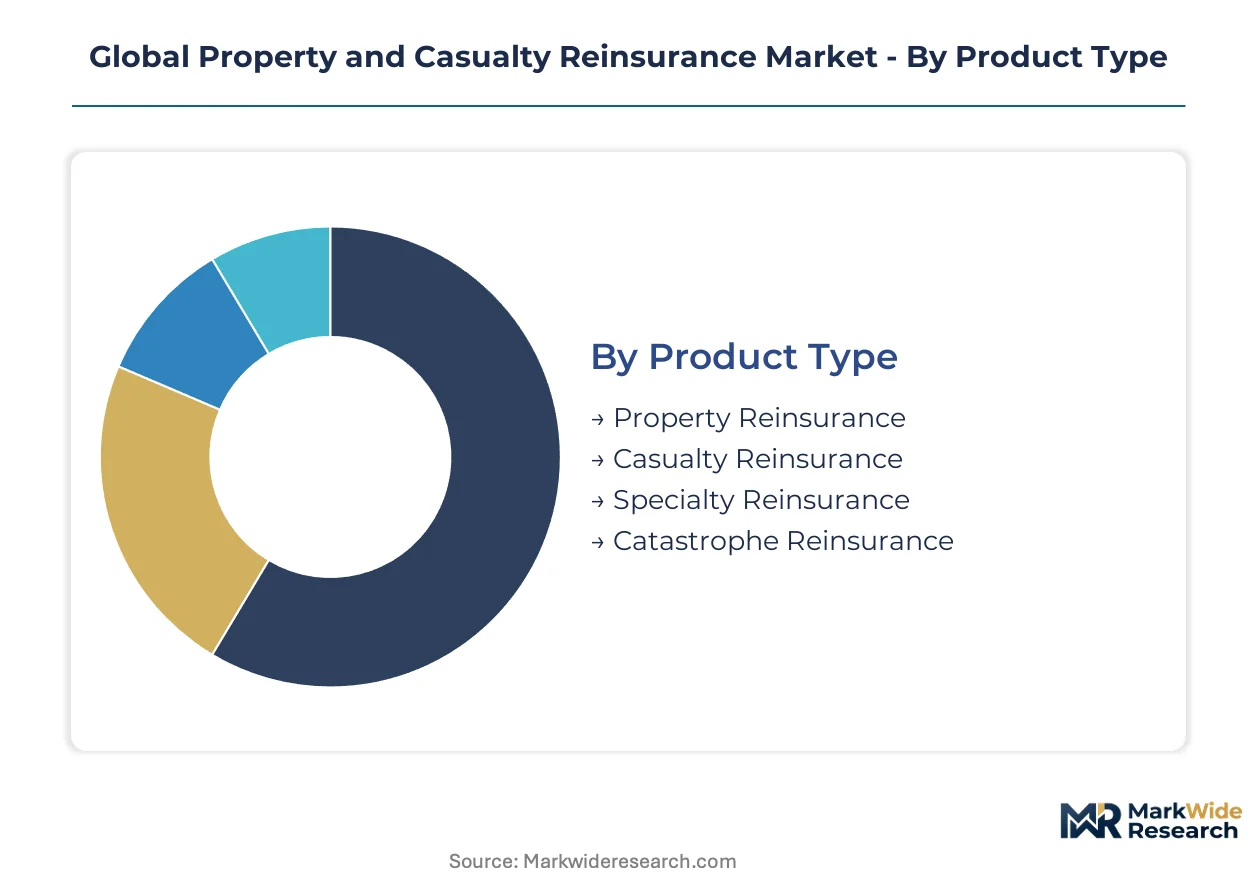
Reinsurance market segmentation reveals how capital flows differentially across risk transfer mechanisms. Treaty structures, distribution pathways, and cedent types each command distinct pricing dynamics and placement cycles that reshape competitive positioning.
Product Type:
Property Reinsurance captures the largest premium volume through catastrophe-exposed commercial portfolios, while Specialty Reinsurance climbs the fastest through emerging liability classes.
- Property Reinsurance:Covers physical damage to buildings, infrastructure, and business interruption from fire, windstorm, and flood perils. Demand concentrates in Florida coastal zones and Japanese earthquake corridors where primary carriers cede peak peril accumulation to stabilize balance sheets against correlated losses.
- Catastrophe Reinsurance:Provides aggregate protection against defined natural peril events with attachment points and reinstatement provisions. Bermuda-based carriers anchor global capacity for Florida wind and Tokyo earthquake programs where model-based pricing commands the deepest margin pools.
- Casualty Reinsurance:Transfers liability exposure from auto, general liability, and workers compensation lines through treaty structures.
- Specialty Reinsurance:Covers non-standard risks including cyber, intellectual property, and marine liability through customized manuscript wording.
Mature deployment sits with Property Reinsurance. Newer deployment is concentrated in Specialty Reinsurance.
Distribution Channel:
Broker intermediation dominates high-complexity treaty placements, while digital platforms compress cycles for standardized catastrophe covers.
- Brokers:Marsh, Aon, and Willis Towers Watson intermediate complex multi-layer catastrophe towers and specialty casualty treaties. London and Bermuda placements rely on broker analytics for pricing benchmarking and capacity aggregation across Lloyd's syndicates and international reinsurers.
- Direct Sales:Large commercial insurers in Germany and Switzerland bypass intermediaries for renewal business with established panel reinsurers. Munich Re and Swiss Re maintain dedicated client executives for direct treaty negotiations with European cedent leadership.
- Online Platforms:Digital placement infrastructure from broker-owned ventures enables algorithmic pricing for Florida wind and Japanese earthquake programs.
- Reinsurers:Direct facultative placements occur through reinsurer-produced capacity without intermediary involvement.
Broker channels retain pricing power in complex placements. Direct channels gain share fastest in renewal business with mature cedent relationships.
Service Type:
Proportional structures dominate premium flow, while Non-Proportional treaties capture disproportionate profit in hardening casualty cycles.
- Proportional Reinsurance:Cedents and reinsurers share premiums and losses in fixed percentage arrangements. Quota Share treaties dominate European motor and property portfolios where Solvency II capital relief drives cession strategy.
- Non-Proportional Reinsurance:Reinsurers respond only when losses exceed defined attachment points. Excess of Loss structures protect US commercial insurers against shock losses in general liability and umbrella lines where social inflation pressures reserving.
- Quota Share:Specific proportional arrangement with fixed percentage participation on all risks within a defined portfolio.
- Excess of Loss:Specific non-proportional structure with layered attachment points and limits.
Quota Share deployment is mature across European motor lines. Excess of Loss structures are expanding fastest in US casualty towers.
End User:
Insurance Companies cede the largest premium volume, while Captive Insurers represent the fastest-growing cedent category through alternative risk transfer expansion.
- Insurance Companies:Primary carriers cede catastrophe accumulation and peak peril exposure to protect regulatory capital positions. Florida domestic insurers and Japanese non-life carriers represent the most active cedent demand for international reinsurance capacity.
- Captive Insurers:Corporate-owned vehicles retain risk and access reinsurance markets directly without primary insurer intermediation. Bermuda and Vermont domiciles are expanding captive formations for Fortune 500 clients seeking balance sheet optimization and customized coverage structures.
- Mutual Insurers:Policyholder-owned carriers cede through treaty arrangements to diversify pooled risk.
- Self-Insured Entities:Large corporations retain risk directly and purchase reinsurance for catastrophic layers.
Traditional Insurance Companies anchor mature cedent relationships. Captive Insurers are gaining share fastest through corporate risk retention expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bermuda's Hamilton anchors global catastrophe reinsurance capacity, with Lloyd's of London and Zurich underwriting hubs competing for European and Asian treaty flows. Regional dynamics reflect divergent regulatory capital regimes and peril exposure concentrations.
United States
Florida domestic insurers cede wind exposure to international reinsurers as Citizens Property Insurance contracts state-backed capacity. The National Association of Insurance Commissioners coordinates credit-for-reinsurance standards determining collateral requirements for offshore carriers. Miami and Tampa underwriting clusters concentrate treaty placement activity for Gulf and Atlantic coastal risks.
Germany
Industrial commercial insurers embed climate scenarios into Own Risk and Solvency Assessments under Solvency II capital charges. The Federal Financial Supervisory Authority enforces risk-based capital adequacy thresholds for cession strategies. Munich anchors continental European reinsurance treaty negotiation with dedicated client executive relationships.
Japan
Non-life carriers cede Tokyo earthquake accumulation to Bermuda and London capacity providers. The Financial Services Agency mandates catastrophe reserve strengthening for domestic primary insurers. Osaka and Nagoya industrial corridors drive demand for commercial property treaty protection against typhoon and flood perils.
United Kingdom
Lloyd's syndicates and company market underwriters intermediate complex multi-layer catastrophe towers for international cedents. The Prudential Regulation Authority and Lloyd's Corporation jointly supervise solvency and market conduct standards. London's EC3 insurance district concentrates broker analytics and capacity aggregation functions.
India
IRDAI's 2022 reinsurance liberalization permits foreign carriers to establish branches in Mumbai, GIFT City, and Chennai without mandatory cessions to GIC Re. The Insurance Regulatory and Development Authority of India now licenses international reinsurers for direct treaty access. Mumbai's financial district anchors emerging South Asian reinsurance placement activity.
Global Property and Casualty Reinsurance Market Competitive Environment
Premium-margin players sit above commodity-margin players across catastrophe modeling sophistication and balance sheet scale. The market structures around a concentrated tier of global carriers with proprietary risk analytics, supported by specialized Bermuda and Lloyd's capacity providers. Three archetypes dominate: integrated multi-line reinsurers with captive primary relationships, catastrophe-focused specialists with collateralized vehicles, and Lloyd's syndicates with delegated underwriting authority. Competitive moves concentrate on portfolio diversification into cyber and specialty casualty lines, alongside geographic expansion through regulatory licensing in India and Southeast Asia.
Within the integrated multi-line tier, Munich Re and Swiss Re occupy positions as archetypal carriers combining proprietary catastrophe modeling with direct cedent relationships. Hannover Re represents the specialty-focused competitor competing across Lloyd's syndicates and international treaty markets. These three German and Swiss carriers anchor European reinsurance capacity while maintaining Bermuda and Asian branch operations for regional treaty access.
| Leading Market Players |
|---|
| Munich Re |
| Swiss Re |
| Berkshire Hathaway |
| Lloyd's |
| Hannover Re |
| SCOR SE |
| Reinsurance Group of America |
| Everest Group |
| RenaissanceRe Holdings |
| Others |
Value Chain & Pricing Dynamics
Collateralized reinsurance vehicles backed by alternative capital providers anchor Bermuda's catastrophe capacity, concentrating supply among a tight cohort of ILS fund managers and sidecar sponsors. This ownership pattern tightens pricing discipline through collateral posting requirements and investor redemption sensitivity, while cedents face step-function cost increases when renewing catastrophe towers in peak peril zones.
Pricing Analysis
Loss-cost-based pricing anchors treaty negotiations, with reinsurers pricing Florida wind and Japanese earthquake layers against modeled annual average loss and tail value-at-risk metrics. Rate differentiation tracks attachment point elevation and reinstatement terms, with lower layers commanding wider spreads due to frequency exposure. Pricing pressure intensifies in retrocession markets where collateralized capacity contraction forces cedents to retain more net exposure. Large commercial insurers with proprietary catastrophe modeling capabilities exhibit lowest price sensitivity, while small Florida domestic carriers face acute affordability constraints.
Supply Chain Analysis
Reinstatement premium flows and commutation settlements create reverse-logistics capital movements that complicate liquidity forecasting for cedents and reinsurers alike. Capacity concentrates in Bermuda, Switzerland, and Germany, with Lloyd's syndicates providing specialty line depth. Treaty placement draws from broker analytics, catastrophe model outputs, and collateralized ILS structures. Single-source vulnerability sits with RMS and AIR Worldwide for proprietary peril modeling, constraining cedent negotiation leverage. Distribution runs through Marsh, Aon, and Willis Towers Watson for complex multi-layer placements, while direct channels handle renewal business with established panel reinsurers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solvency II capital charges and Bermuda Monetary Authority solvency frameworks erect compliance moats that favor carriers with advanced internal models and diversified balance sheet scale. New entrants face steep capitalization hurdles and model accreditation timelines that entrench incumbent positioning.
For Market Incumbents: Acquire catastrophe modeling talent pools to defend pricing power against emerging MGAs with algorithmic underwriting capabilities. Expand collateralized vehicle offerings to capture alternative capital flows retreating from peak peril zones. Deepen proprietary risk analytics investment to differentiate treaty terms as broker-owned digital platforms compress placement margins.
For New Entrants and Emerging Players: IRDAI's 2022 reinsurance liberalization in India opens a window for branch establishment in Mumbai and GIFT City without mandatory GIC Re cessions. Target parametric agriculture and cyber liability treaties where traditional carriers lack specialized modeling infrastructure. Pursue fronting arrangements with established Bermuda carriers to access collateralized capacity without full balance sheet commitment.
For Investors and Strategic Acquirers: Retrocession market contraction is the leading indicator that capacity-scarce pricing environments will persist through hardening cycles. Focus acquisition screening on Lloyd's syndicates with delegated underwriting authority and specialty casualty expertise. Monitor Florida Citizens Property Insurance cession volumes as a demand inflection signal for private reinsurer market share expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Catastrophe Model Development | Proprietary peril analytics differentiate treaty pricing against commoditized broker platforms. |
| Collateralized Vehicle Launch | ILS sidecars access pension fund capital seeking uncorrelated insurance-linked returns. |
| Regulatory Licensing Expansion | IRDAI branch approvals unlock direct treaty access to Indian cedent portfolios. |
| Parametric Product Design | Index-based triggers bypass traditional loss adjustment friction in emerging markets. |
| Cyber Accumulation Modeling | RMS and AIR frameworks enable standalone treaty pricing for systemic risk exposure. |
Study Parameters
Document review covered regulatory filings from the Bermuda Monetary Authority, NAIC credit-for-reinsurance standards, and Solvency II technical specifications, complemented by interviews with treaty underwriters, broker analytics heads, and cedent risk management officers. Secondary validation drew from Lloyd's market reports, catastrophe model documentation, and ILS market databases. Bottom-up treaty placement tracking and top-down premium flow estimates were triangulated to reconcile segment-level demand with carrier capacity deployment.
Projected market value and premium volume outputs reflect econometric modeling across treaty structure, distribution channel, service type, and cedent category dimensions throughout the forecast period. CAGRs were derived from trend extrapolation of cession rates, regulatory capital charge evolution, and alternative capital flow patterns. Climate scenario stress testing mandates and cyber peril emergence curves served as primary demand-side forecast inputs.
Caveats apply where retrocession market liquidity, interest rate volatility, or climate model revision could materially shift the outlook. Practitioners should monitor Florida wind market dislocation and EU Green Deal implementation timelines for early signals of capacity repricing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Aerial Imaging in Insurance Service Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Digital Monetary Insurance Market
Insurance
Africa Microinsurance Market
Insurance
Europe Embedded Insurance Market
Insurance
Austria Property and Casualty Insurance Market
Insurance
Dental Insurance Market
Insurance
France Car Insurance Market
Insurance
Australia Parametric Insurance Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
Europe Travel Insurance Market
Insurance
Logistics Insurance Market
Insurance
Japan Bancassurance Market
Insurance
Asia-Pacific Mobile Phone Insurance Market
Insurance
Germany Car Insurance Market
Insurance
Saudi Arabia Travel Insurance Market