
 Business Insurance Market | 2026-2036
Business Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Business Insurance Market Analysis
Modular policy bundling is repositioning how enterprises evaluate carrier relationships. Chubb leverages its global underwriting platform to anchor complex multi-line accounts for large corporations. Travelers dominates commercial property coverage through advanced catastrophe modeling capabilities. Hiscox specializes in tailored professional liability for small enterprises and startups across digital service sectors.
Business insurance constitutes risk transfer instruments designed to indemnify organizations against operational, legal, and asset-related losses through contractual premium arrangements. Policies specify coverage limits, deductibles, and exclusions calibrated to industry-specific exposure profiles, with primary commercial purpose centered on balance sheet protection and operational continuity assurance. General liability coverage leads premium volume due to universal contractual requirements, while professional liability exhibits accelerated expansion driven by errors-and-omissions exposures in technology services. Workers' compensation maintains mature, regulated premium pools with margin compression in high-frequency jurisdictions.
The National Association of Insurance Commissioners coordinates state-level reserve and rate filings across US jurisdictions, while the EU's Solvency II framework mandates risk-based capital requirements for carriers operating in member states. The UK's Prudential Regulation Authority imposes stress-testing protocols that shape product availability and pricing granularity for London-market syndicates. Stakeholders must monitor evolving climate disclosure mandates from securities regulators and their cascading effects on property underwriting standards and coverage terms.
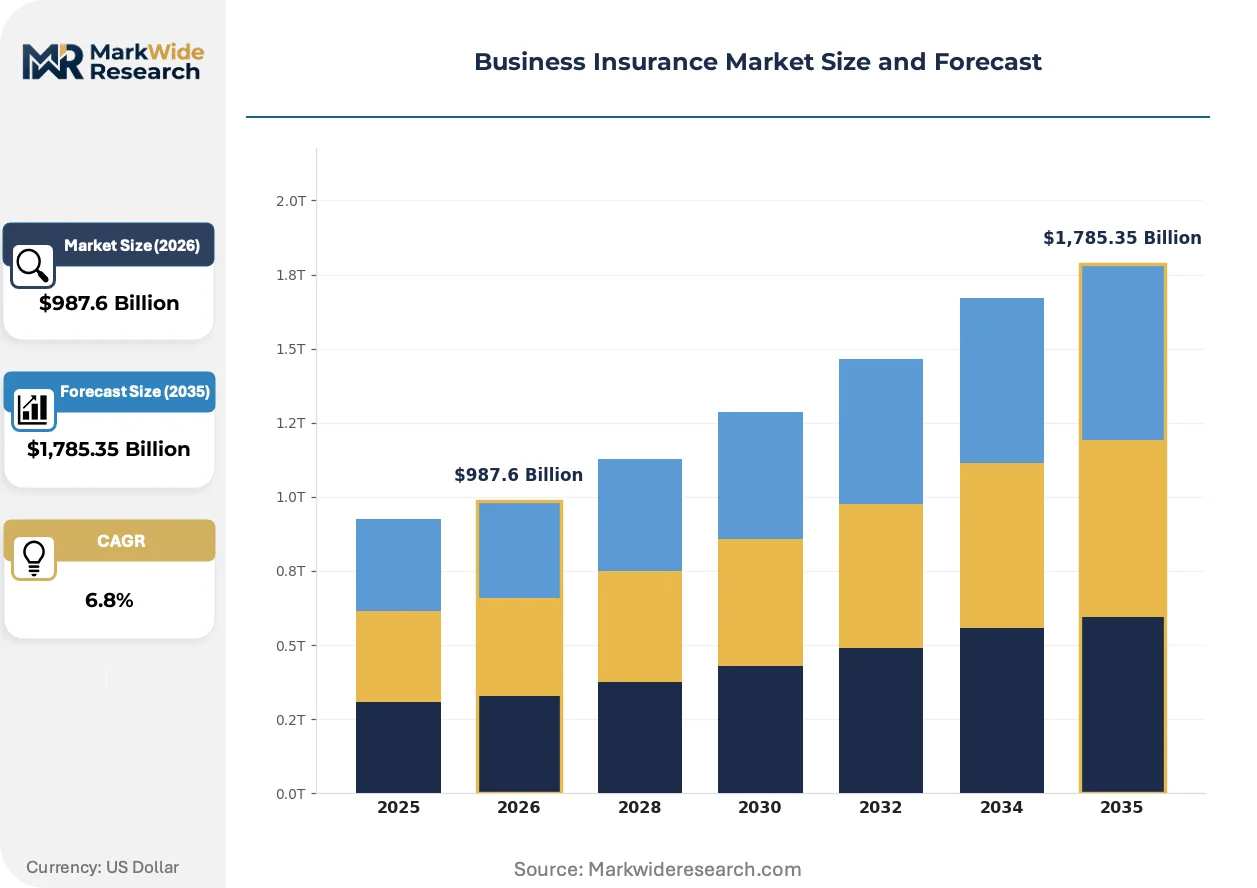
Market Dynamics
EU AI Act mandates are forcing carriers to restructure underwriting algorithms and reserve capital against algorithmic bias liabilities, compressing product development cycles across commercial lines.
Growth Catalysts
- EU AI Act compliance mandates:Germany's mid-market manufacturers now require modular cyber-physical coverage bundles, pulling premium volume into specialized commercial lines.
- Healthcare digitization:US hospital systems facing HIPAA breach exposure are expanding cyber liability adoption beyond traditional malpractice frameworks.
- Biometric privacy litigation:Illinois BIPA and Texas biometric statutes have activated errors-and-omissions demand among HR technology vendors.
Market Restraints
- Reinsurance capacity contraction:London-market syndicates face reduced retrocession availability for catastrophe-exposed property layers, hardening rates in Florida and California.
- Long-tailed liability uncertainty:Social inflation in US jury verdicts distorts loss development triangles for commercial auto and general liability reserves.
- Climate attribution science gaps:Property underwriters lack standardized peril models for secondary flood zones, constraining coverage expansion in coastal manufacturing corridors.
Strategic Opportunities
- Parametric coverage expansion:Indian agricultural cooperatives and Southeast Asian logistics operators represent underpenetrated demand for index-triggered business interruption products.
- Embedded distribution partnerships:Commercial banking platforms in Brazil and Mexico are integrating micro-enterprise policies into working capital facilities.
- CSRD disclosure alignment:EU corporate sustainability reporting requirements are creating advisory revenue streams for carriers offering climate risk quantification services.
Industry Challenges
- Actuarial talent scarcity:Specialty lines requiring cyber and intangible asset modeling face recruitment bottlenecks against technology sector compensation benchmarks.
- Legacy system integration friction:Mid-tier carriers struggle to embed telematics and IoT data streams into decades-old policy administration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Insurance Market |
| Market Size in 2026 | $987.6 Billion |
| Market Size in 2035 | $1,785.35 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: General Liability, Property Insurance, Professional Liability, Workers' Compensation Business Size: Small Enterprises, Medium Enterprises, Large Corporations, Startups Industry Type: Healthcare, Manufacturing, Retail, Hospitality Policy Type: Comprehensive, Modular, Customized, Package |
| Companies Covered | The Hartford, Chubb, Travelers, Liberty Mutual, Nationwide, Hiscox, Marsh & McLennan, Aon, Arthur J. Gallagher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Insurance Market Emerging Trajectories
Algorithmic underwriting and real-time exposure monitoring are compressing traditional annual policy cycles into continuous risk-adjustment frameworks across commercial insurance.
API-first policy administration software is modularizing how carriers assemble coverage components. Mid-market brokers in the Netherlands and Denmark are adopting white-label platforms that unbundle property, liability, and cyber modules into configurable stacks. This architecture enables quarterly coverage adjustments rather than annual renewals, reducing basis risk for clients with volatile revenue profiles.
CSRD climate disclosure mandates are reshaping property underwriting standards. EU carriers must now document physical risk exposure in investment portfolios and underwriting books, triggering granular geocoding requirements for industrial facilities. German manufacturing clusters and Benelux logistics hubs face heightened scrutiny on flood and windstorm resilience certifications.
Usage-based premium structures are displacing flat-rate conventions in commercial auto and equipment coverage. Fleet operators in Texas and Ontario now transmit telematics data directly to underwriting engines, with premiums adjusting monthly based on mileage, route risk profiles, and driver behavior scores. This shift compresses customer switching costs and intensifies price transparency.
Business Insurance Market Segmentation
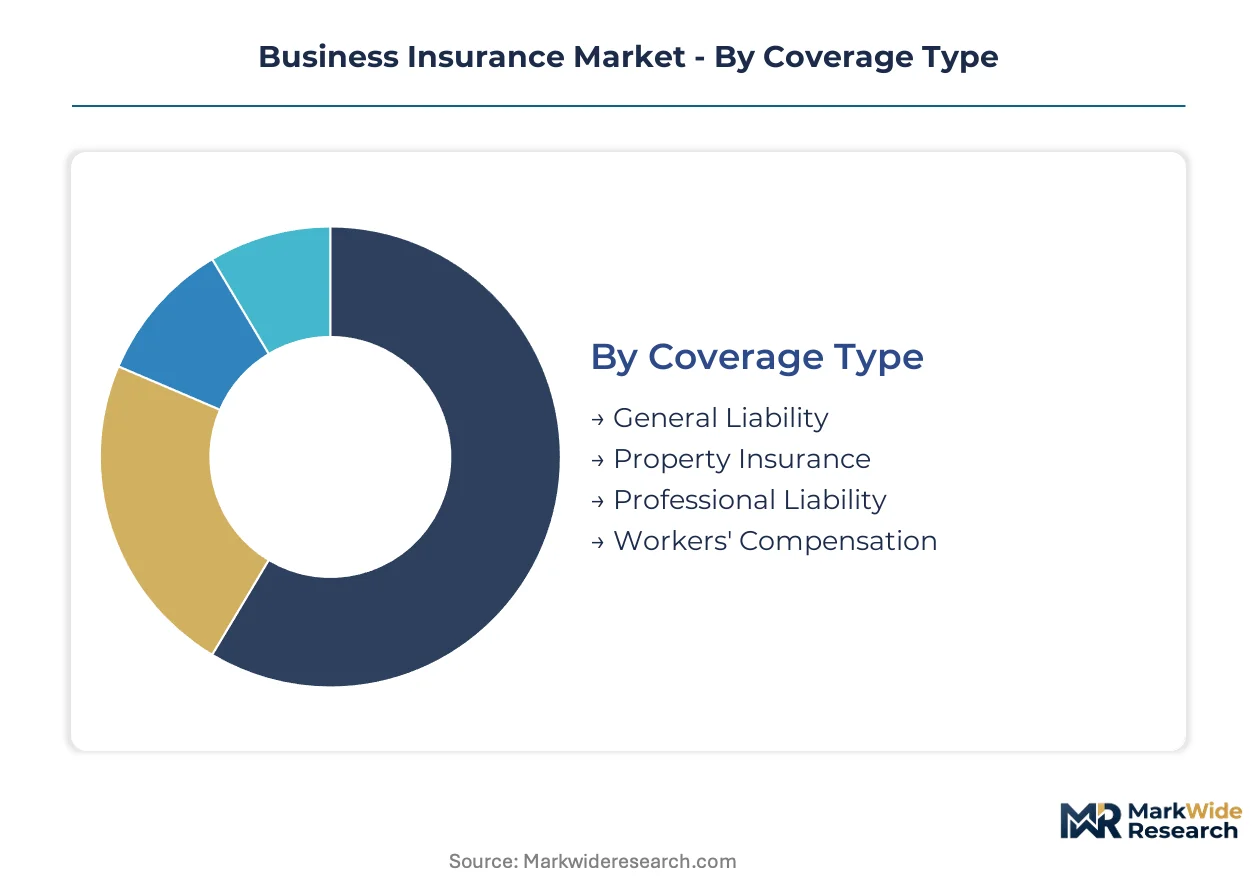
Business insurance segmentation reflects divergent risk profiles across organizational scale and operational complexity. Carriers calibrate underwriting precision through coverage granularity, balancing standardized products for volume efficiency against tailored structures for specialty exposures.
Coverage Type:
Standardization dominates commodity lines while specialty coverages demand bespoke underwriting architecture.
- General Liability:Broad-spectrum protection against third-party bodily injury and property damage claims. Universal contractual requirements across US commercial leasing and vendor agreements sustain premium leadership, though social inflation in jury verdicts compresses carrier margins in high-frequency jurisdictions.
- Professional Liability:Errors-and-omissions coverage for service-based enterprises including technology consultancies and financial advisors. HIPAA breach exposure among US hospital systems and Illinois BIPA litigation against HR technology vendors are accelerating policy adoption beyond traditional malpractice frameworks.
- Property Insurance:Physical asset protection against fire, theft, and natural catastrophe perils.
- Workers' Compensation:Statutory employer liability for occupational injury and illness claims.
Leading the category by volume: General Liability. Expanding most quickly: Professional Liability.
Business Size:
Premium economics shift dramatically across the scale spectrum, from transactional micro-policies to complex multi-line negotiations.
- Large Corporations:Complex risk profiles requiring coordinated global programs across multiple jurisdictions. German mid-market manufacturers seeking modular cyber-physical bundles illustrate how sophisticated buyers unbundle coverage components for quarterly adjustment flexibility.
- Small Enterprises:Standardized policy templates with minimal underwriting friction. Embedded distribution partnerships through Brazilian and Mexican commercial banking platforms demonstrate how micro-enterprise coverage integrates into working capital facilities.
- Medium Enterprises:Transitional buyers balancing customization needs against administrative efficiency constraints.
- Startups:Early-stage ventures with volatile revenue profiles and limited loss history.
Revenue concentration peaks with Large Corporations. Customer acquisition velocity runs highest among Startups.
Industry Type:
Sector-specific regulatory mandates and loss experience patterns drive coverage differentiation.
- Healthcare:Institutions face intersecting malpractice, cyber liability, and HIPAA breach exposures. Digitization of patient records and telemedicine expansion are restructuring traditional malpractice frameworks toward hybrid cyber-clinical coverage.
- Manufacturing:German industrial clusters exhibit concentrated demand for modular property and cyber-physical bundles under EU AI Act compliance pressure.
- Retail:High-frequency general liability exposure from customer foot traffic and product defect claims.
- Hospitality:Seasonal revenue volatility complicates business interruption coverage calibration.
Maturest underwriting infrastructure: Manufacturing. Steepest coverage expansion trajectory: Healthcare.
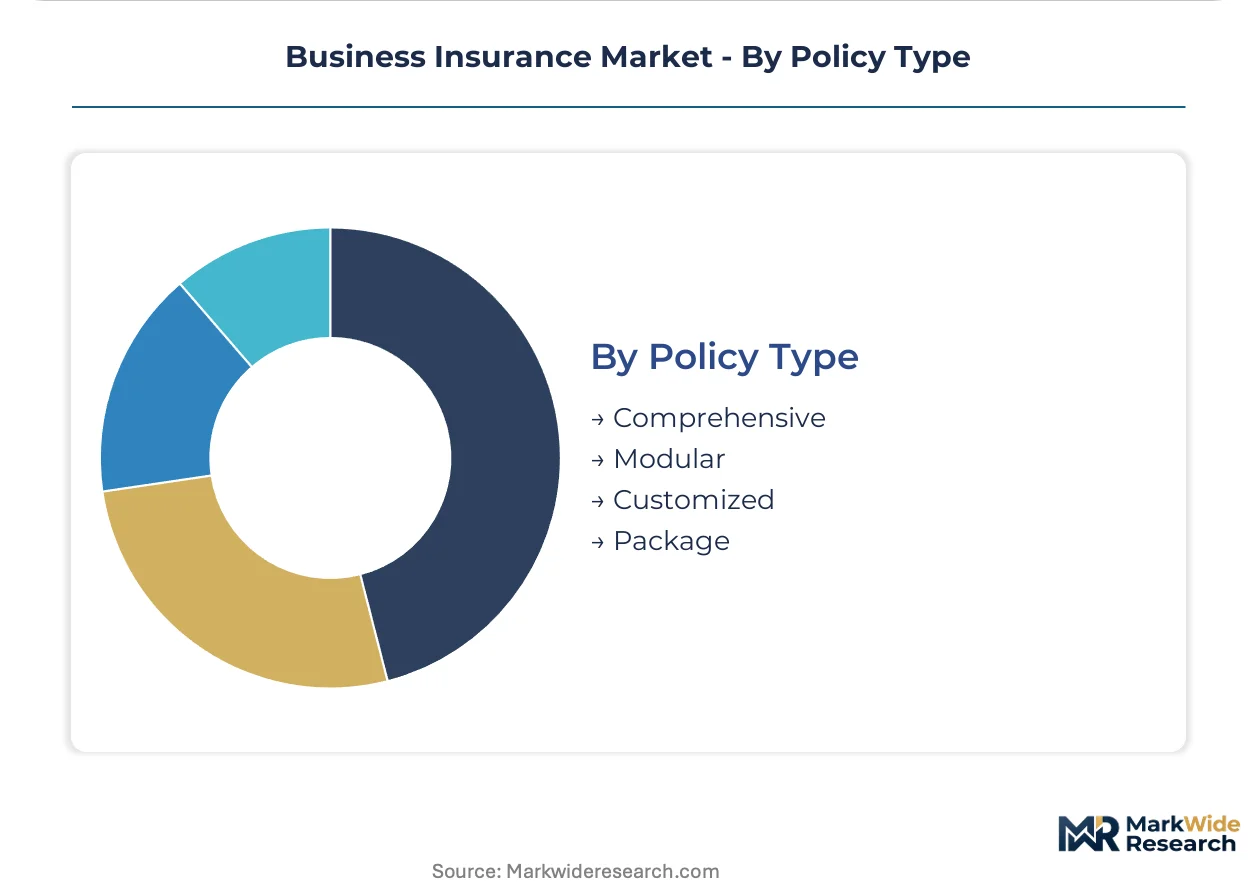
Policy Type:
Distribution architecture determines whether carriers capture value through assembly efficiency or advisory depth.
- Modular:Component-based structures enabling quarterly coverage adjustments rather than annual renewals. Netherlands and Denmark mid-market brokers deploy white-label API platforms to unbundle property, liability, and cyber modules into configurable stacks.
- Comprehensive:Integrated multi-line programs for buyers seeking administrative simplicity.
- Customized:Bespoke structures negotiated for unique or emerging risk categories.
- Package:Pre-assembled combinations targeting specific industry verticals.
Dominant transaction format: Package policies. Gaining share fastest: Modular architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates premium volume that exceeds domestic carrier capacity, drawing London-market syndicates and Bermuda reinsurers to absorb catastrophe layers. Germany concentrates sophisticated manufacturing demand that outpaces local specialty underwriting depth.
United States
Hospital systems in Texas and Illinois are expanding cyber liability coverage beyond traditional malpractice frameworks. HIPAA breach exposure and Illinois BIPA litigation against HR technology vendors are activating errors-and-omissions demand. The National Association of Insurance Commissioners coordinates state-level reserve filings that shape product availability across Florida and California catastrophe markets.
Germany
Mid-market manufacturers in Baden-Württemberg and Bavaria are unbundling coverage into modular cyber-physical bundles. The EU AI Act mandates algorithmic bias liability reserves that compress product development cycles. Industrial clusters around Stuttgart and Munich face heightened scrutiny on flood resilience certifications under CSRD climate disclosure requirements.
United Kingdom
London-market syndicates are restructuring catastrophe property layers as retrocession availability contracts. The Prudential Regulation Authority imposes stress-testing protocols that shape pricing granularity for commercial auto and general liability reserves. Lloyd's underwriting rooms anchor specialty lines for global energy and marine accounts.
India
Agricultural cooperatives in Maharashtra and Gujarat represent underpenetrated demand for parametric business interruption products. The Insurance Regulatory and Development Authority of India is expanding micro-enterprise policy distribution through commercial banking platforms. Mumbai-based brokers are white-labeling API-first administration software for quarterly coverage adjustments.
Brazil
São Paulo logistics operators are adopting usage-based premium structures for commercial auto and equipment coverage. Embedded distribution partnerships through Banco do Brasil and Itaú Unibanco integrate micro-enterprise policies into working capital facilities. The Superintendence of Private Insurance regulates solvency requirements that constrain mid-tier carrier expansion into cyber liability lines.
Business Insurance Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. Global carriers with multi-line platforms anchor complex corporate accounts through coordinated international programs. Boutique underwriters capture specialty exposures in cyber liability and professional lines with tailored underwriting precision. Dominant competitive moves include embedded distribution partnerships with commercial banking platforms and API-first policy administration acquisitions.
Among diversified global carriers, Chubb and Travelers exemplify scale-driven underwriting platforms that coordinate multi-jurisdictional programs for large corporations. Hiscox occupies a specialist position within the small enterprise and startup segment across digital service sectors. These three carriers represent contrasting archetypes: integrated global conglomerate, catastrophe-modeling property leader, and tailored professional liability boutique.
| Leading Market Players |
|---|
| The Hartford |
| Chubb |
| Travelers |
| Liberty Mutual |
| Nationwide |
| Hiscox |
| Marsh & McLennan |
| Aon |
| Arthur J. Gallagher |
| Others |
Supply Flow & Price Mechanics
German mid-market manufacturers demanding quarterly coverage adjustments force carriers to restructure policy administration systems, compressing development timelines and compressing margins across modular product lines.
Pricing Analysis
Margin tightening in commercial auto traces to telematics-enabled usage-based structures displacing flat-rate conventions. Pricing stratifies across premium catastrophe layers, standard admitted markets, and economy surplus lines based on retrocession availability and carrier surplus position. Cost-down pressure on cyber liability accelerates because HIPAA breach exposure activates errors-and-omissions demand beyond traditional malpractice frameworks. Small enterprises exhibit highest price sensitivity due to embedded distribution through banking platforms, while large corporations prioritize coverage flexibility over premium minimization.
Supply Chain Analysis
Actuarial talent shortages in London, Bermuda, and Zurich constrain specialty lines development against technology sector compensation benchmarks. Underwriting capacity draws from reinsurance retrocession markets, Lloyd's syndicate capital, and captive insurer formations. Single-source vulnerability concentrates in catastrophe modeling vendor relationships, where three firms dominate peril quantification for property layers. Distribution runs through wholesale brokers, managing general agents, and direct carrier platforms serving distinct buyer scale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first policy administration platforms are displacing decades-old legacy systems, compressing product development cycles from annual to quarterly renewal frameworks.
For Market Incumbents: Anticipate embedded distribution partnerships from commercial banking platforms in Brazil and Mexico eroding traditional broker relationships. Defend position by deepening API-first platform acquisitions that enable modular coverage unbundling. Prioritize certification investment in EU AI Act compliance capabilities to capture German manufacturing demand for cyber-physical bundles. For New Entrants and Emerging Players: Begin with parametric coverage expansion targeting Indian agricultural cooperatives and Southeast Asian logistics operators where traditional indemnity products show underpenetration. White-label distribution through Mumbai-based brokers offers lowest customer acquisition friction against established carrier direct channels. For Investors and Strategic Acquirers: The window for entry favors specialty cyber liability boutiques with EU AI Act compliance infrastructure already deployed. Long-term viability rests on algorithmic underwriting capabilities that compress traditional annual policy cycles. Watch reinsurance retrocession availability as the inflection signal for property layer pricing volatility.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Acquisition | Enables quarterly coverage adjustments for German manufacturing clients facing volatile revenue profiles. |
| Embedded Banking Partnership | Integrates micro-enterprise policies into Banco do Brasil working capital facilities for customer acquisition velocity. |
| EU AI Act Compliance Certification | Captures Baden-Württemberg manufacturer demand for algorithmic bias liability reserves. |
| Parametric Product Development | Addresses Maharashtra agricultural cooperative demand for index-triggered business interruption coverage. |
| Telematics Data Integration | Supports usage-based premium structures for Texas fleet operators transmitting route risk profiles monthly. |
Methodological Framework
Independent corroboration across carrier underwriting executives, commercial brokerage principals, and regulatory affairs leads underwrites the qualitative findings. Primary interviews with Lloyd's syndicate managers, Munich reinsurance specialists, and NAIC state filing coordinators combined with secondary validation from SEC 10-K insurance disclosures, NAIC statutory filings, and EIOPA Solvency II reports. Bottom-up premium volume triangulation against top-down macroeconomic exposure modeling ensures segmentation integrity.
Rate-of-change decomposition separates volume expansion from pricing hardening across the projection horizon. Segmentation dimensions modeled include coverage type, business size tier, industry vertical, policy architecture format, and regional regulatory cluster. CAGRs derive from premium growth trajectory analysis calibrated to exposure base expansion and rate level movement. Forecast inputs incorporate catastrophe model vendor peril updates and EU AI Act implementation timelines.
Underlying measurement precision varies by segment; general liability and workers' compensation carry tighter precision than emerging cyber-physical bundles. Forecasts reflect assumptions on reinsurance capacity availability and climate attribution science advancement. Material deviation in retrocession pricing or CSRD disclosure enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Canada House Insurance Market
Insurance
Car Insurance Market
Insurance
Europe Road Assistance Insurance Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
Commercial Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Europe EV Insurance Market
Insurance
IoT Insurance Market
Insurance
Event Insurance Market
Insurance
Auto Extended Warranty Market
Insurance
Intellectual Property Liability Insurance Market
Insurance
India Life and Non-Life Insurance Market
Insurance
Trade Credit Insurance Market
Insurance
Europe Travel Insurance Market
Insurance
Disability Insurance Market
Insurance
UK Electronic Gadgets Insurance Market