
 Japan Bancassurance Market | 2026-2036
Japan Bancassurance Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Bancassurance Market Intelligence
The capital-intensity divergence between integrated banking-insurance conglomerates and standalone insurers is redrawing competitive boundaries in Japan. Mitsubishi UFJ Financial Group leverages its megabank branch infrastructure to sustain premium flow through captive distribution. Nippon Life Insurance anchors its position through proprietary agency networks that compete directly with bank channels for household financial assets.
Bancassurance denotes the distribution of insurance products through banking channels, relying on integrated IT systems for customer data sharing, suitability screening, and premium collection within a single financial institution relationship. Its primary commercial purpose is to generate non-interest fee income for banks while expanding insurers' access to mass-market households. Life insurance dominates product flow through branch networks due to embedded savings features and tax-advantaged treatment, while non-life products through online platforms represent the fastest-growing channel-service intersection. Term policies occupy the highest volume tier among product types, though whole life and annuities concentrate margin pools through longer-duration liabilities.
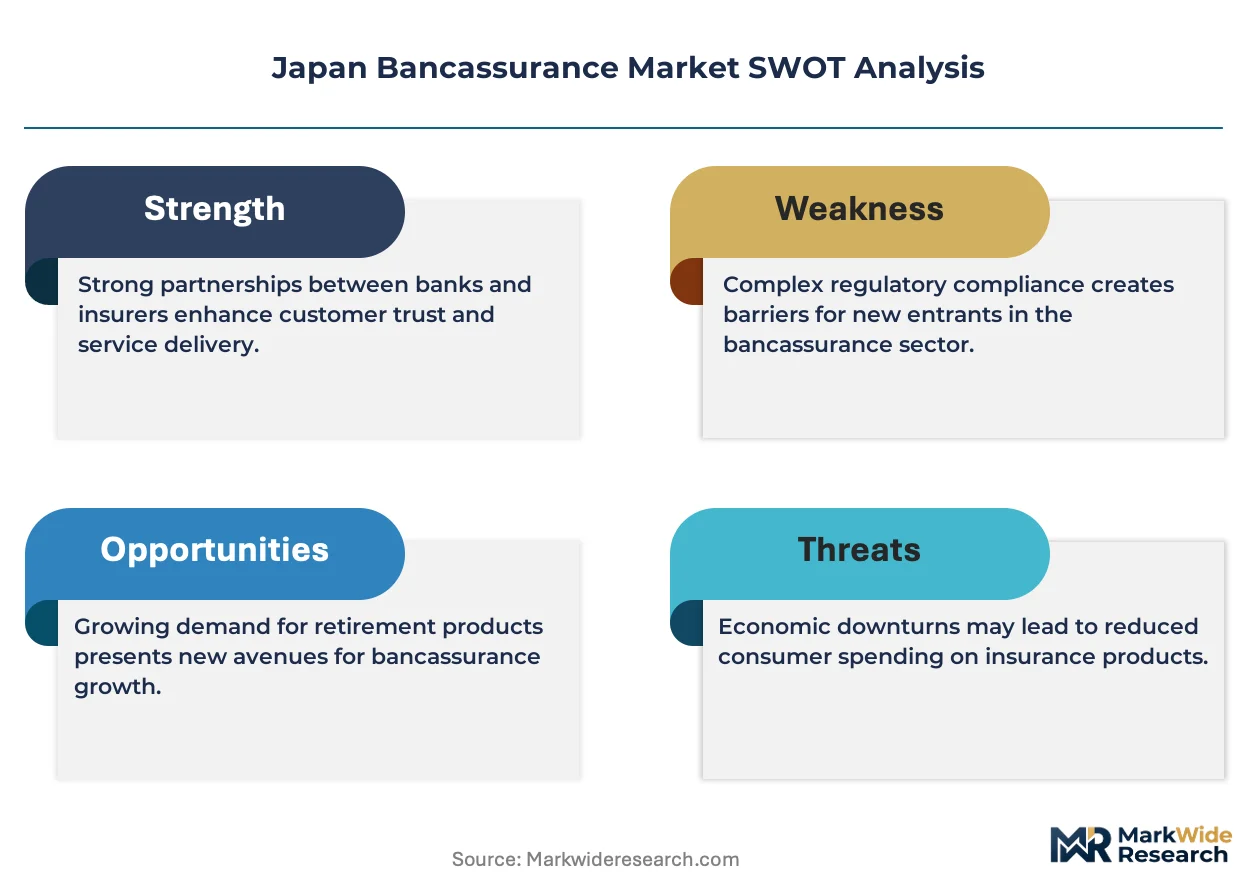
Japan's Financial Services Agency mandates strict suitability standards and cooling-off periods for bank-sold insurance, while METI guidelines shape digital sales channel expansion. The JFSA's conduct regime and consumer contract law frameworks constrain product complexity that can be offered through non-face-to-face channels. Stakeholders must monitor evolving interpretations of banking-insurance firewall rules as digital platform integration deepens.
Market Dynamics
METI's financial services modernization agenda and the JFSA's conduct regime are compressing distribution timelines while forcing banks and insurers to reconfigure IT architectures for real-time suitability screening. This regulatory pressure is accelerating capital deployment into digital identity frameworks and branch network rationalization.
Growth Catalysts
- Digital Identity Frameworks:METI's My Number integration enables seamless KYC verification across banking and insurance platforms, reducing onboarding friction for mass-market households.
- Tax-Advantaged Life Products:Embedded savings features in whole life and annuity policies attract household financial assets seeking shelter from Japan's progressive income tax structure.
- Branch Network Density:Metropolitan banking corridors in Tokyo and Osaka concentrate affluent retail customers within physical distribution reach, sustaining premium flow through face-to-face advisory.
Market Restraints
- JFSA Cooling-Off Mandates:Mandatory withdrawal periods for bank-sold insurance compress conversion rates and extend customer acquisition cost recovery timelines.
- IT Integration Complexity:Legacy core banking systems require substantial middleware investment to achieve real-time data sharing with insurer policy administration platforms.
- Agency Channel Competition:Nippon Life's proprietary agent networks retain stronger household trust relationships, limiting bank channel penetration in rural prefectures.
Strategic Opportunities
- Non-Face-to-Face Channel Expansion:JFSA interpretations of consumer contract law are gradually permitting simplified products through smartphone apps, opening digital-native customer segments.
- Non-Life Product Diversification:Online platform distribution of property and casualty coverage represents underdeveloped white space compared to saturated life insurance flows.
- Regional Bank Consolidation:Smaller prefectural banks seeking fee income diversification present partnership opportunities for insurers lacking captive distribution infrastructure.
Industry Challenges
- Actuarial-Technology Talent Scarcity:The intersection of traditional insurance pricing expertise and cloud-native system architecture remains thinly staffed across Japanese financial institutions.
- Firewall Compliance Architecture:Banking-insurance separation rules require costly legal and operational separation of customer data flows, complicating unified CRM platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Bancassurance Market |
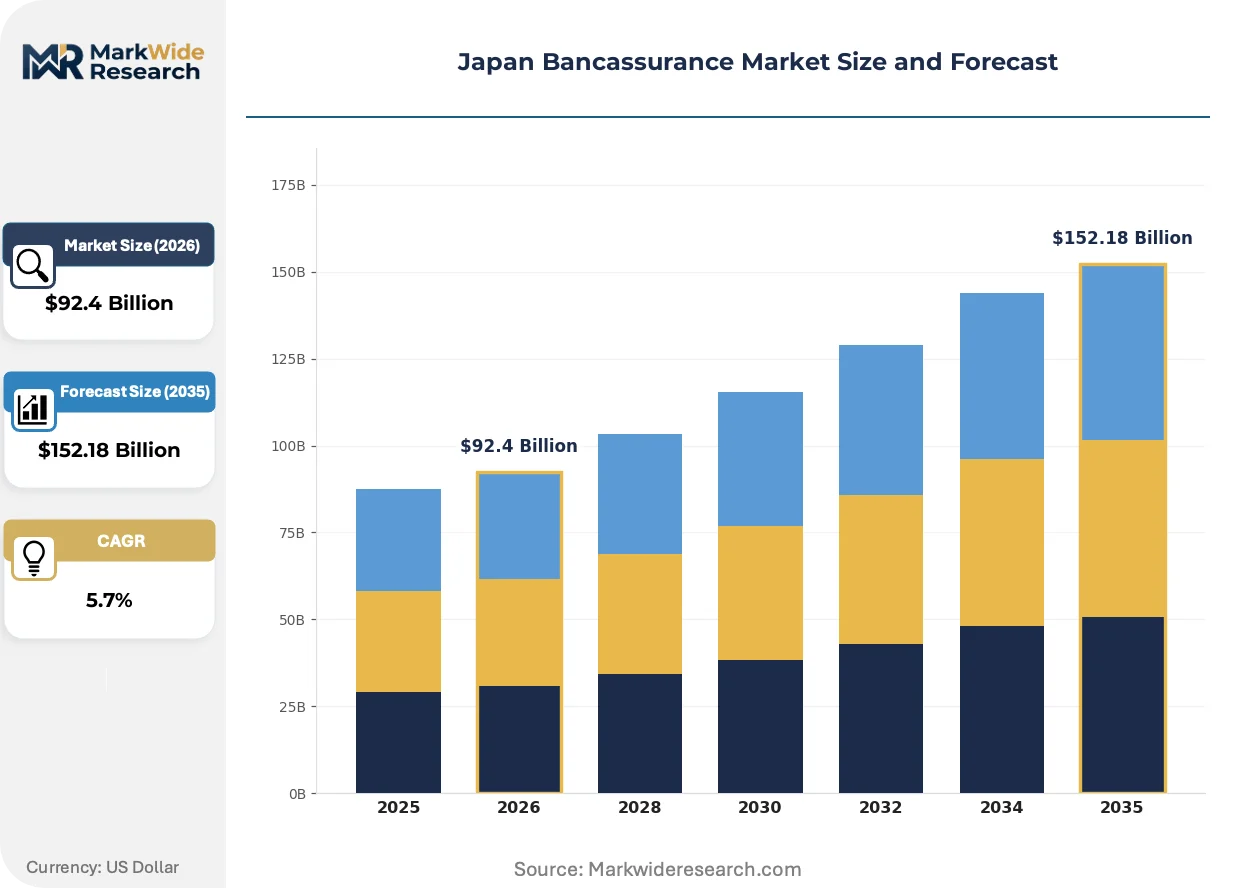
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $152.18 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Life Insurance, Non-Life Insurance, Investment Products, Health Insurance Channel: Direct Sales, Online Platforms, Branch Networks, Telemarketing Client Type: Individuals, Corporates, SMEs, High-Net-Worth Individuals Product Type: Term Policy, Whole Life, Universal Life, Annuities |
| Companies Covered | Tokio Marine Holdings, Sompo Holdings, Mitsubishi UFJ Financial Group (MUFG), Japan Post Insurance, Nippon Life Insurance Company, Sumitomo Mitsui Financial Group (SMFG), MS&AD Insurance Group Holdings, Dai-ichi Life Insurance, Mizuho Financial Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Bancassurance Market Strategic Shifts & Innovations
Digitization of suitability screening and policy issuance is redrawing the operational boundary between physical branches and remote channels. METI's interoperability standards and shifting household preferences are forcing synchronized investment across distribution infrastructure.
API-based core system integration is fragmenting the traditional monolithic IT stacks that previously dominated Japanese bancassurance operations. Regional banks in Fukuoka and Sapporo are adopting modular cloud architectures faster than Tokyo megabanks burdened by legacy mainframe dependencies. This technology shift is compressing vendor concentration among domestic system integrators and enabling direct insurer-to-bank data pipes that bypass traditional middleware layers.
METI's financial services modernization agenda is mandating open API frameworks for customer data portability across financial institutions. The regulation forces banks to expose standardized interfaces for insurance product quotation and policy servicing, eroding proprietary system advantages. Smaller insurers lacking internal IT development capacity are outsourcing platform compliance to fintech infrastructure providers, while major banking groups are building captive API gateways.
Household financial asset allocation is rotating from pure deposit products toward hybrid insurance-cum-savings vehicles, driven by negative real interest rates and demographic aging. Branch-based advisory is losing share to smartphone-enabled policy comparison tools among customers under age 45. This behavioral shift concentrates most acutely in Tokyo's 23 wards, where digital literacy and insurance product sophistication run highest among Japanese retail banking segments.
Japan Bancassurance Market Segmentation
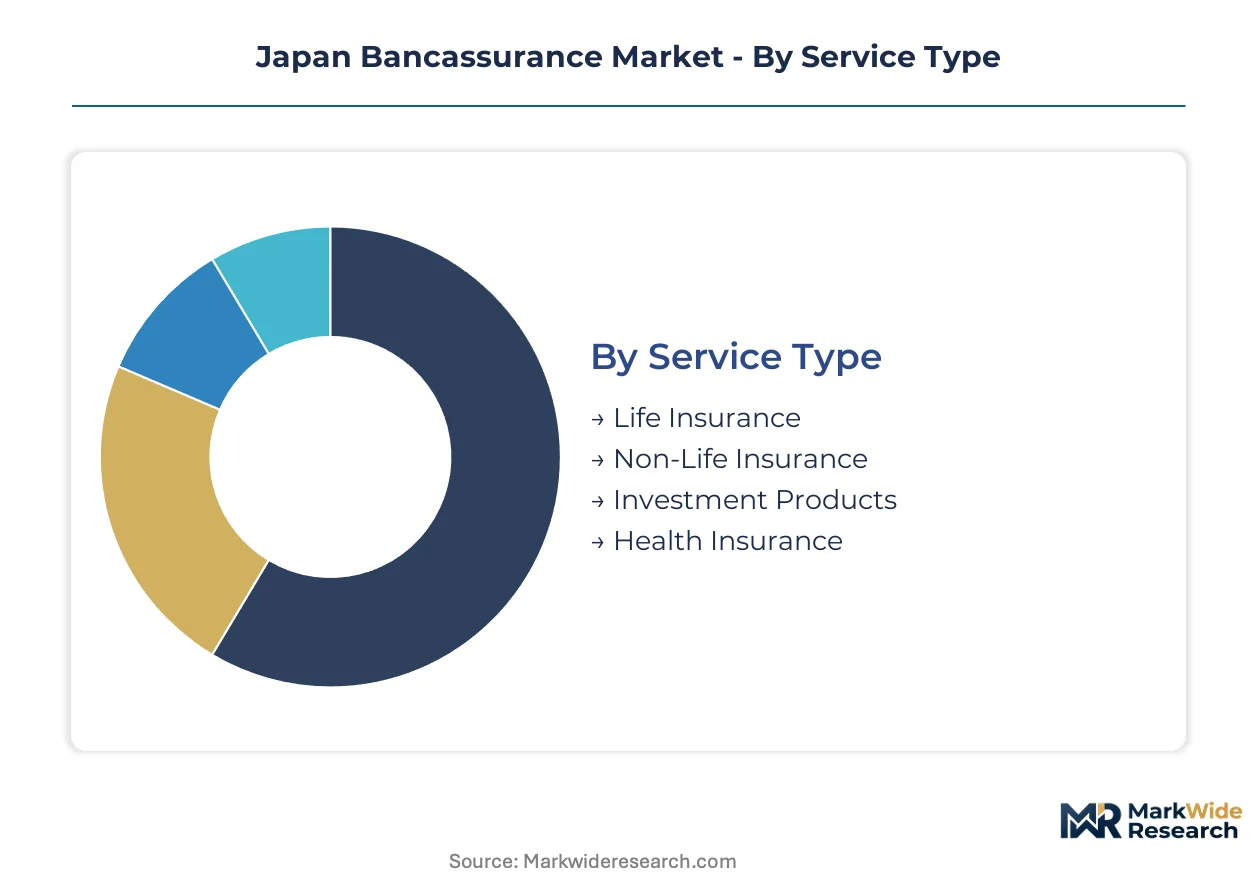
Segmentation in Japan's bancassurance market reflects regulatory boundaries set by JFSA suitability rules and METI digital framework mandates. Each dimension carries distinct compliance obligations that shape product design and channel deployment strategies.
Service Type:
JFSA cooling-off mandates apply differentially across insurance categories, with life products facing stricter face-to-face requirements than simplified non-life offerings.
- Life Insurance:Whole life and term policies with embedded savings features dominate branch-based distribution. Tokyo's metropolitan banking corridor concentrates demand from household asset reallocation away from negative-yield deposits.
- Non-Life Insurance:Property and casualty products through online platforms are climbing the fastest as JFSA interpretations gradually permit simplified digital issuance for standardized coverage.
- Investment Products:Unit-linked and variable annuity structures require enhanced suitability screening under JFSA conduct rules, limiting branch advisor discretion.
- Health Insurance:Medical expense riders and critical illness coverage attach to core life policies, with METI's My Number integration streamlining health data verification.
Established volume favors Life Insurance; emerging adoption favors Non-Life Insurance.
Channel:
Cost-to-serve economics vary dramatically, with legacy branch infrastructure carrying fixed cost burdens that digital channels avoid.
- Branch Networks:Face-to-face advisory sustains premium flow for complex whole life and annuity products. Osaka's commercial prefecture retains higher branch dependency than Tokyo's 23 wards.
- Online Platforms:Smartphone-enabled policy comparison and issuance are expanding most quickly among customers under age 45, particularly for standardized term coverage.
- Direct Sales:Insurer-operated channels bypass bank intermediation, competing for household financial assets through proprietary digital portals.
- Telemarketing:Regulatory constraints under Japan's consumer contract law limit outbound solicitation, relegating this channel to policy servicing and renewal prompts.
Margin concentration remains with Branch Networks; customer acquisition efficiency favors Online Platforms.
Client Type:
Wealth tier determines product complexity permissions and advisory intensity requirements under JFSA suitability frameworks.
- Individuals:Mass-market households seeking tax-advantaged savings vehicles drive term policy and annuity flows through Tokyo-Osaka branch corridors.
- High-Net-Worth Individuals:Sophisticated estate planning and wealth transfer structures demand customized universal life configurations with dedicated private banking interfaces.
- SMEs:Business succession and key-person coverage represent underdeveloped white space for regional bank partnerships outside major metropolitan centers.
- Corporates:Group life and health arrangements face competition from direct insurer relationships, limiting bancassurance penetration in this tier.
Current premium weight sits with Individuals; structural opportunity favors SMEs.
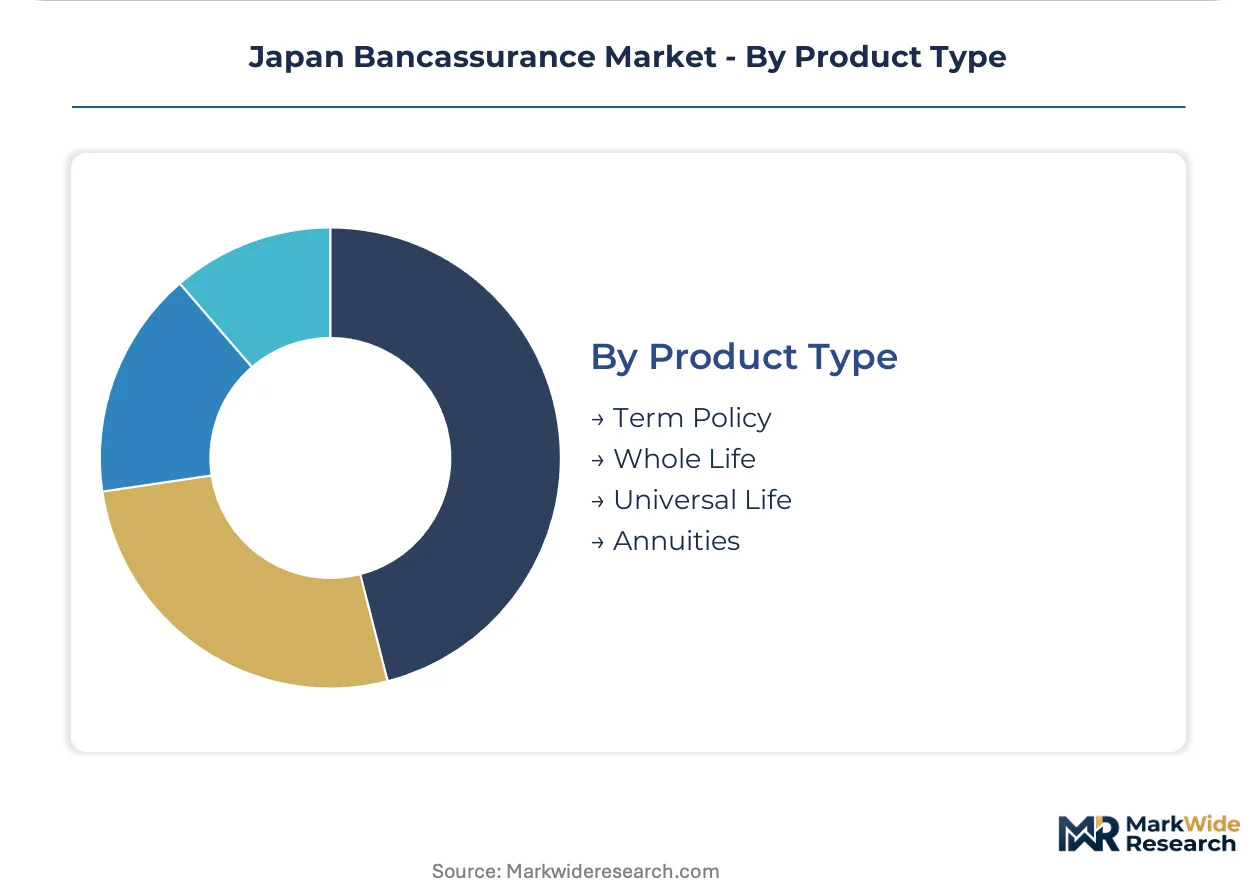
Product Type:
Liability duration and cash value mechanics differentiate regulatory treatment and capital requirements for insurers.
- Term Policy:Pure risk coverage without savings component permits simplified underwriting and digital distribution. Highest volume tier across all channels.
- Whole Life:Guaranteed cash accumulation and tax-deferred growth attract household asset reallocation, with longer-duration liabilities concentrating insurer margin pools.
- Universal Life:Flexible premium and adjustable death benefit structures require enhanced policy illustration standards under JFSA consumer protection rules.
- Annuities:Retirement income products face demographic tailwinds from Japan's aging population, though negative interest rates compress pricing flexibility.
Volume leadership belongs to Term Policy; value expansion favors Whole Life.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's bancassurance market exhibits pronounced regional asymmetry, with premium flows and distribution infrastructure concentrating in specific metropolitan corridors while rural prefectures lag in digital adoption and branch network density.
Kanto/Tokyo
Metropolitan banking corridors in Tokyo's 23 wards concentrate affluent retail customers seeking tax-advantaged life products. METI's My Number integration enables seamless KYC verification across integrated banking-insurance platforms. Mitsubishi UFJ Financial Group leverages its megabank branch infrastructure to sustain premium flow through captive distribution in this corridor.
Kansai/Osaka
Osaka's commercial prefecture retains higher branch dependency than Tokyo for complex whole life and annuity advisory. The JFSA's cooling-off mandates apply differentially here, with face-to-face requirements sustaining traditional distribution economics. Regional banks in this corridor present partnership opportunities for insurers lacking captive infrastructure.
Chubu/Nagoya
Manufacturing-affiliated households in Aichi Prefecture drive demand for SME succession coverage and key-person policies. METI's financial services modernization agenda shapes digital sales channel expansion among regional banks here. Nagoya's banking clusters are adopting modular cloud architectures faster than Tokyo megabanks burdened by legacy dependencies.
Kyushu
Fukuoka's regional banks are pioneering API-based core system integration that fragments traditional monolithic IT stacks. The JFSA's conduct regime and consumer contract law frameworks constrain product complexity offered through non-face-to-face channels. This sub-region represents underdeveloped white space for non-life product diversification compared to saturated life insurance flows elsewhere.
Hokkaido
Sapporo's banking institutions face actuarial-technology talent scarcity at the intersection of traditional pricing expertise and cloud-native architecture. METI's open API frameworks for customer data portability force operational reconfiguration. Rural prefecture demographics limit bank channel penetration where Nippon Life's proprietary agent networks retain stronger household trust relationships.
Japan Bancassurance Market Key Industry Players
Concentration sits with integrated banking-insurance conglomerates that leverage captive distribution infrastructure against standalone insurers dependent on proprietary agency networks. Three archetypes define competitive positioning: megabank groups with branch-dominant distribution, mutual insurers with agency network anchoring, and regional bank partnerships seeking fee income diversification. M&A activity concentrates on regional bank consolidation plays, while technology licensing partnerships address legacy IT integration complexity.
Among megabank-affiliated distributors, Mitsubishi UFJ Financial Group and Sumitomo Mitsui Financial Group exemplify the integrated conglomerate archetype, occupying positions that exploit branch network density for premium flow capture. Nippon Life Insurance Company anchors the mutual insurer tier, representing the proprietary agency model that competes directly with bank channels for household financial assets. These three entities illustrate the structural tension between banking-led and insurance-led distribution architectures reshaping competitive boundaries across Japan's metropolitan corridors.
| Leading Market Players |
|---|
| Tokio Marine Holdings |
| Sompo Holdings |
| Mitsubishi UFJ Financial Group (MUFG) |
| Japan Post Insurance |
| Nippon Life Insurance Company |
| Sumitomo Mitsui Financial Group (SMFG) |
| MS&AD Insurance Group Holdings |
| Dai-ichi Life Insurance |
| Mizuho Financial Group |
| Others |
Cost & Logistics Intelligence
JFSA's conduct regime and METI's open API mandates gate both insurer qualification for bank distribution and the price differentiation available across advisory versus digital channels. This regulatory scaffolding compresses margin pools for standardized products while preserving premium capture for complex whole life configurations requiring face-to-face suitability screening.
Pricing Analysis
The customization-premium spread between configured-to-order universal life policies and standardized term coverage defines pricing architecture across Japan's bancassurance corridors. Three-tier pricing structure across premium, standard, and economy levels reflects JFSA suitability tiering, certification-grade advisor qualifications, and embedded after-sales service bundling. Cost compression in term policy tiers is intensifying because regional banks compete aggressively for fee income share. Mass-market households under age 45 exhibit highest price sensitivity, while high-net-worth individuals accept premium positioning for estate planning complexity.
Supply Chain Analysis
Inventory and lead-time compression in policy issuance systems now separates competitive performers from legacy-dependent institutions across Tokyo-Osaka corridors. Core system integration draws from domestic system integrators in Japan, cloud-native fintech infrastructure providers in Singapore, and middleware specialists in India. Critical dependencies include real-time data pipes, API gateway architecture, and legacy mainframe emulation layers. Single-source vulnerability concentrates in captive IT development capacity at megabank groups. Distribution runs through branch networks for complex products and direct insurer-to-bank digital platforms for standardized coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's bancassurance market rewards institutions that command scarce actuarial-technology hybrid talent capable of bridging traditional pricing expertise with cloud-native system architecture. The gap between legacy-dependent incumbents and modular-platform adopters is widening faster than talent pipelines can fill.
For Market Incumbents: Secure proprietary agency network loyalty through enhanced digital tooling that preserves advisor autonomy against direct bank channel encroachment. Consolidate regional bank partnership pipelines before mutual insurers capture fee income diversification opportunities. Vertical integration into captive API gateway development protects against fintech infrastructure provider dependency. For New Entrants and Emerging Players: Differentiate on modular cloud architecture deployment speed to capture regional bank segments outside Tokyo-Osaka megabank dominance. Target SME succession coverage in Nagoya manufacturing corridors and Fukuoka commercial banking clusters where incumbent penetration remains thin. Lead with smartphone-enabled policy comparison tools calibrated to JFSA's gradually expanding non-face-to-face product permissions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital-native distribution sub-segments as API-based integration fragments traditional monolithic IT spending requirements. Long-term viability favors institutions with demonstrated My Number integration compliance and modular core system architecture. Acquisition target archetype: regional banks with captive customer bases seeking insurer partnerships but lacking internal IT development capacity. Watch JFSA interpretations of consumer contract law for non-face-to-face channel expansion as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| API Gateway Development | METI's open API mandates force standardized interface investment that erodes proprietary system advantages across megabank groups. |
| Regional Bank Partnership | Smaller prefectural banks seeking fee income diversification present captive distribution access outside Tokyo-Osaka corridor saturation. |
| Modular Cloud Migration | Legacy mainframe dependencies at Tokyo megabanks create competitive opening for nimbler regional institutions in Fukuoka and Sapporo. |
| Non-Life Product Diversification | Property and casualty coverage through online platforms represents underdeveloped white space compared to saturated life insurance flows. |
| Actuarial-Technology Talent Acquisition | Scarcity at the intersection of traditional pricing expertise and cloud-native architecture constrains platform modernization timelines. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with bank distribution heads, insurance product executives, regulatory compliance officers, and fintech platform engineers; and secondary validation against JFSA conduct guidelines, METI financial services modernization documentation, and insurer policy administration system disclosures. Bottom-up segmentation modeling triangulated against top-down macroeconomic projections across the analysis window.
Across the projection horizon, the analytical framework modeled service type, channel architecture, client wealth tier, and product liability duration dimensions. CAGRs derived from trend extrapolation of premium flow data, adjusted for regulatory intervention probability and technology adoption S-curves. Forecast inputs included My Number integration penetration rates and branch network rationalization trajectories specific to Japan's metropolitan banking corridors.
Forecasts assume regulatory continuity in JFSA conduct regimes and METI digital framework mandates; material policy shifts would require re-modeling. Specific risk factors include evolving interpretations of banking-insurance firewall rules and cooling-off mandate modifications. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Travel Insurance Market
Insurance
Earthquake Insurance Market
Insurance
Global Sports Insurance Market
Insurance
Financial Guarantee Market
Insurance
Cancer Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Europe EV Insurance Market
Insurance
Europe Travel Insurance Market
Insurance
US Property and Casualty (P&C) Insurance Market
Insurance
Business Insurance Market
Insurance
Dental Insurance Market
Insurance
Asia-Pacific Usage-Based Insurance Market
Insurance
Business Income Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
India Travel Insurance Market
Insurance
Middle East and Africa Travel Insurance Market