
 Specialty Insurance Market | 2026-2036
Specialty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Insurance Market Intelligence
Parametric trigger structures and embedded risk analytics is repositioning how carriers package and price catastrophic coverage. Chubb leverages its global underwriting platform to sustain leadership in high-net-worth personal lines and commercial specialty. Hiscox anchors its competitive edge in cyber and media liability through direct digital distribution and SME-focused product design. Tokio Marine HCC competes aggressively in accident and health specialty segments through delegated authority partnerships with managing general agents.
Specialty insurance encompasses non-standard, complex, or hard-to-place risks that fall outside conventional commercial lines due to unusual exposure characteristics, requiring bespoke underwriting expertise and tailored policy wording. Coverage typically incorporates layered limits, manuscript endorsements, and facultative reinsurance arrangements to address singular or catastrophic loss potentials. Professional Liability and Directors & Officers coverage command substantial premium pools given litigation severity trends and regulatory enforcement intensity across technology and healthcare verticals. Brokers dominate distribution for complex placements, while online platforms are gaining share in standardized specialty lines such as event insurance and small commercial specialty property.
The National Association of Insurance Commissioners (NAIC) in the United States shapes capital adequacy and market conduct standards, while the EU's Solvency II framework governs risk-based capital requirements for European carriers writing cross-border specialty business. Lloyd's of London operates under the UK Prudential Regulation Authority and Financial Conduct Authority dual regulatory structure, setting global benchmarks for syndicated specialty underwriting and claims performance transparency. Stakeholders must monitor evolving climate disclosure mandates and cyber incident reporting requirements that will redefine coverage triggers and retrocession structures.
Market Dynamics
Parametric trigger structures and embedded risk analytics are compressing policy development cycles while forcing carriers to rebuild actuarial infrastructure around real-time data ingestion rather than historical loss modeling.
Growth Catalysts
- EU Digital Operational Resilience Act (DORA):Mandates stringent cyber resilience protocols for financial services entities, expanding mandatory coverage minimums and creating compliance-driven demand spikes across Frankfurt, Paris, and Dublin banking corridors.
- Climate catastrophe modeling:Satellite-based exposure assessment tools enable parametric flood and windstorm products for agricultural cooperatives and municipal utilities previously excluded from traditional indemnity structures.
- Silicon Valley technology clusters:Concentrated venture capital deployment and IPO activity generate sustained demand for Directors & Officers liability and cyber breach coverage with manuscripted startup-specific exclusions.
Market Restraints
- Reinsurance capacity tightening:Retrocession markets in Bermuda and London have reduced aggregate catastrophe limits, forcing primary carriers to retain more peak peril exposure or cede at deteriorating terms.
- Long-tailed liability reserving:Asbestos and environmental impairment claims continue stressing legacy general liability portfolios, constraining capital deployment into emerging specialty lines.
- Alternative risk transfer mechanisms:Captive insurance formations and catastrophe bond issuances by large commercial buyers directly absorb risks that previously flowed to admitted specialty markets.
Strategic Opportunities
- India's manufacturing corridors:Semiconductor and pharmaceutical production incentives under the PLI scheme create underpenetrated demand for product recall and contingent business interruption coverage with localized policy wording.
- Embedded insurance distribution:API-based integration with commercial SaaS platforms enables point-of-sale micro-duration coverage for gig economy logistics and freelance professional services.
- Japan's METI carbon disclosure mandates:Supply chain emissions reporting requirements for listed corporations generate demand for climate litigation defense and greenwashing liability products.
Industry Challenges
- Actuarial talent scarcity:Specialty lines require hybrid expertise combining traditional reserving with data science and catastrophe modeling, yet graduate pipelines favor generic data analytics over insurance-specific training.
- Legacy system integration:Core policy administration platforms at established carriers resist API connectivity with external IoT sensor networks and blockchain-based smart contract triggers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Insurance Market |
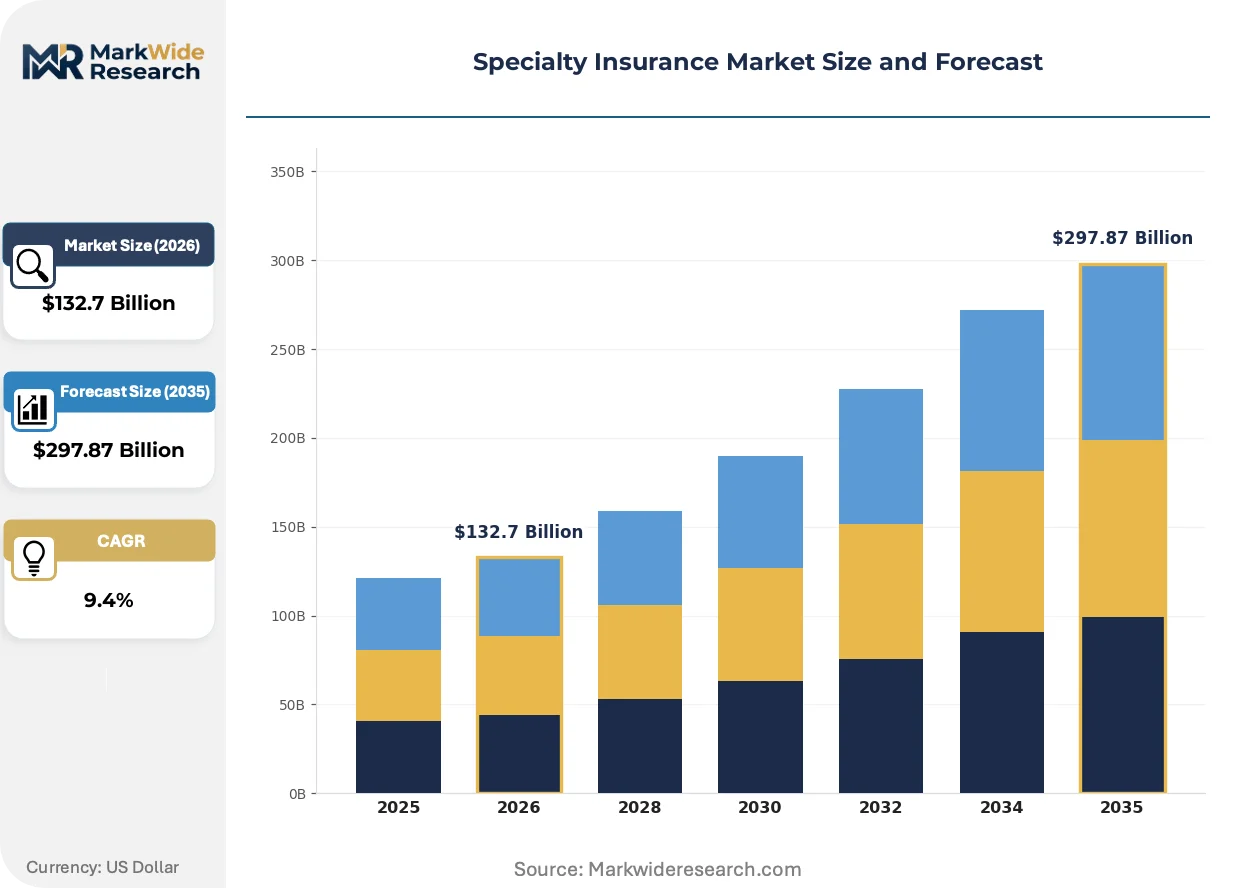
| Market Size in 2026 | $132.7 Billion |
| Market Size in 2035 | $297.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Professional Liability, Event Insurance, Specialty Property, Directors & Officers Client Type: Corporations, Nonprofits, Individuals, Government Entities Industry Vertical: Technology, Construction, Healthcare, Entertainment Distribution Channel: Brokers, Direct Sales, Online Platforms, Agents |
| Companies Covered | AXA, Chubb, Zurich Insurance Group, Allianz, American International Group, Assicurazioni Generali, AXA XL, Hiscox, Tokio Marine HCC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Insurance Market Strategic Shifts & Innovations
Distributed sensor networks and algorithmic underwriting engines are collapsing the distance between risk identification and capital deployment, enabling coverage structures that respond to verified events rather than assessed damages.
Blockchain-enabled smart contracts are unifying premium collection, claims verification, and settlement execution into single automated workflows. Parametric crop insurers in drought-prone agricultural regions now trigger disbursements within 48 hours of satellite-confirmed soil moisture thresholds. This compression is eliminating loss adjustment expense ratios and enabling capital-light market entry by technology-native underwriters.
The EU's Corporate Sustainability Reporting Directive (CSRD) mandates granular climate risk disclosures across supply chains. European carriers writing multinational programs must now embed transition risk assessments into underwriting submissions, with Lloyd's syndicates developing manuscripted exclusions for stranded asset exposure. German industrial manufacturing and Nordic renewable energy infrastructure represent the most immediately affected placement categories.
Buyers now unbundle risk advisory from placement execution, engaging independent analytics firms to structure coverage specifications before soliciting carrier quotes. Large commercial risk managers in London and New York retain specialty brokers for market access while commissioning separate catastrophe modeling studies from third-party vendors. This bifurcation compresses brokerage margins and rewards carriers with transparent, algorithmically defensible pricing methodologies.
Specialty Insurance Market Segmentation
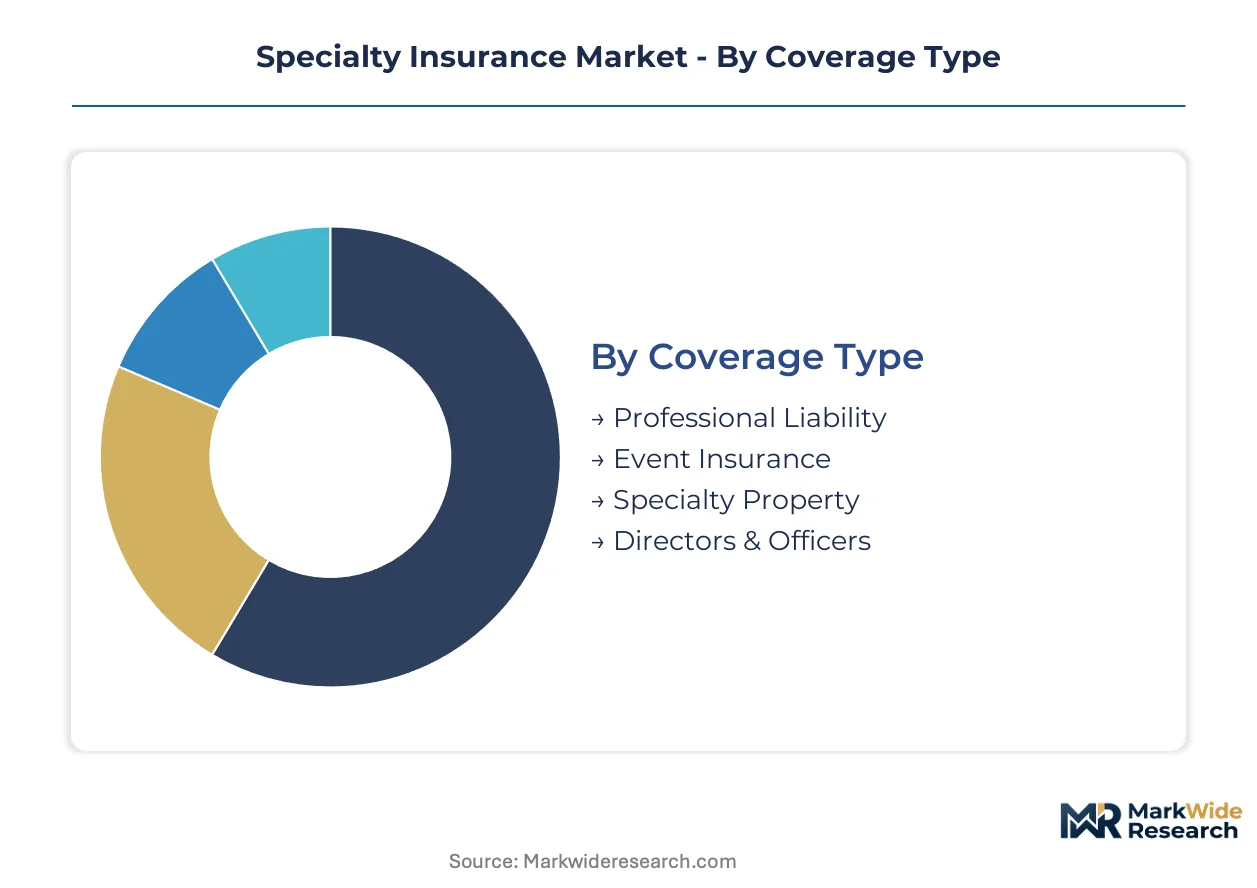
Specialty insurance segmentation reflects capital deployment patterns across risk-bearing capacity, client sophistication, and distribution economics. Underwriters allocate facultative reinsurance and manuscript capacity differentially across segments based on loss severity profiles and regulatory capital charges.
Coverage Type:
Capital intensity peaks where layered limits and facultative reinsurance stacking dominate underwriting infrastructure.
- Professional Liability:Manuscripted policies covering errors and omissions in professional services demand substantial actuarial reserves and claims litigation budgets. Demand concentrates among Silicon Valley technology firms and New York financial advisory practices facing SEC enforcement intensity and client arbitration frequency.
- Directors & Officers:Side-A, Side-B, and Side-C coverage structures require dedicated Side-A-only capacity and personal asset protection clauses for individual insureds. Litigation severity trends in Delaware corporate courts and derivative shareholder actions drive premium adequacy requirements.
- Specialty Property:Catastrophe-exposed commercial risks with manuscripted flood or earthquake sublimits.
- Event Insurance:Short-duration contingency coverage for cancellation and non-appearance risks.
Most installed capacity flows through Professional Liability. Expansion is steepest in Directors & Officers.
Client Type:
Pricing power and retention rates diverge sharply between sophisticated commercial buyers and fragmented individual purchasers.
- Corporations:Fortune 500 risk managers structure multi-line towers with manuscripted exclusions and captive participation. Demand clusters in Texas energy corridors and Illinois manufacturing belts where regulatory enforcement and shareholder litigation intersect.
- Nonprofits:Board liability and employment practices coverage with volunteer immunity provisions and limited asset bases. Endowment-dependent cultural institutions in Massachusetts and faith-based healthcare systems in Minnesota represent concentrated placement volumes.
- Individuals:High-net-worth personal lines with scheduled fine art and private collections.
- Government Entities:Municipal liability and public official bonds with sovereign immunity carveouts.
Corporations command the deepest facultative reinsurance participation. Nonprofits are gaining share fastest among emerging client categories.
Industry Vertical:
Vertical-specific regulatory intensity and loss history determine underwriting appetite and manuscript endorsement requirements.
- Technology:Cyber liability and media liability converge with technology errors and omissions in single integrated towers. EU DORA compliance deadlines and SEC cybersecurity disclosure rules generate mandatory coverage minimums across Frankfurt banking corridors and Dublin fund administration centers.
- Healthcare:Medical professional liability and managed care errors and omissions with regulatory exclusion clauses. Hospital systems in Florida and physician groups in California drive severity-adjusted pricing.
- Construction:Wrap-up liability and professional liability for design-build contractors.
- Entertainment:Cast insurance and production completion guarantees for film and live events.
Healthcare maintains the longest-tailed reserving requirements. Technology is expanding most quickly amid regulatory compliance mandates.
Distribution Channel:
Economics of placement complexity determine channel viability and compensation structures.
- Brokers:Wholesale and retail intermediaries dominate complex multi-carrier towers and manuscript policy negotiations. Lloyd's coverholders and London market brokers command premium shares on cross-border placements for multinational programs.
- Online Platforms:API-enabled direct distribution gains traction in standardized event insurance and small commercial specialty property. Hiscox and similar carriers deploy algorithmic underwriting for SME cyber and media liability with sub-24-hour quote turnaround.
- Direct Sales:Carrier-employed underwriters for large account relationships.
- Agents:Local producers for admitted market access and surplus lines licensing.
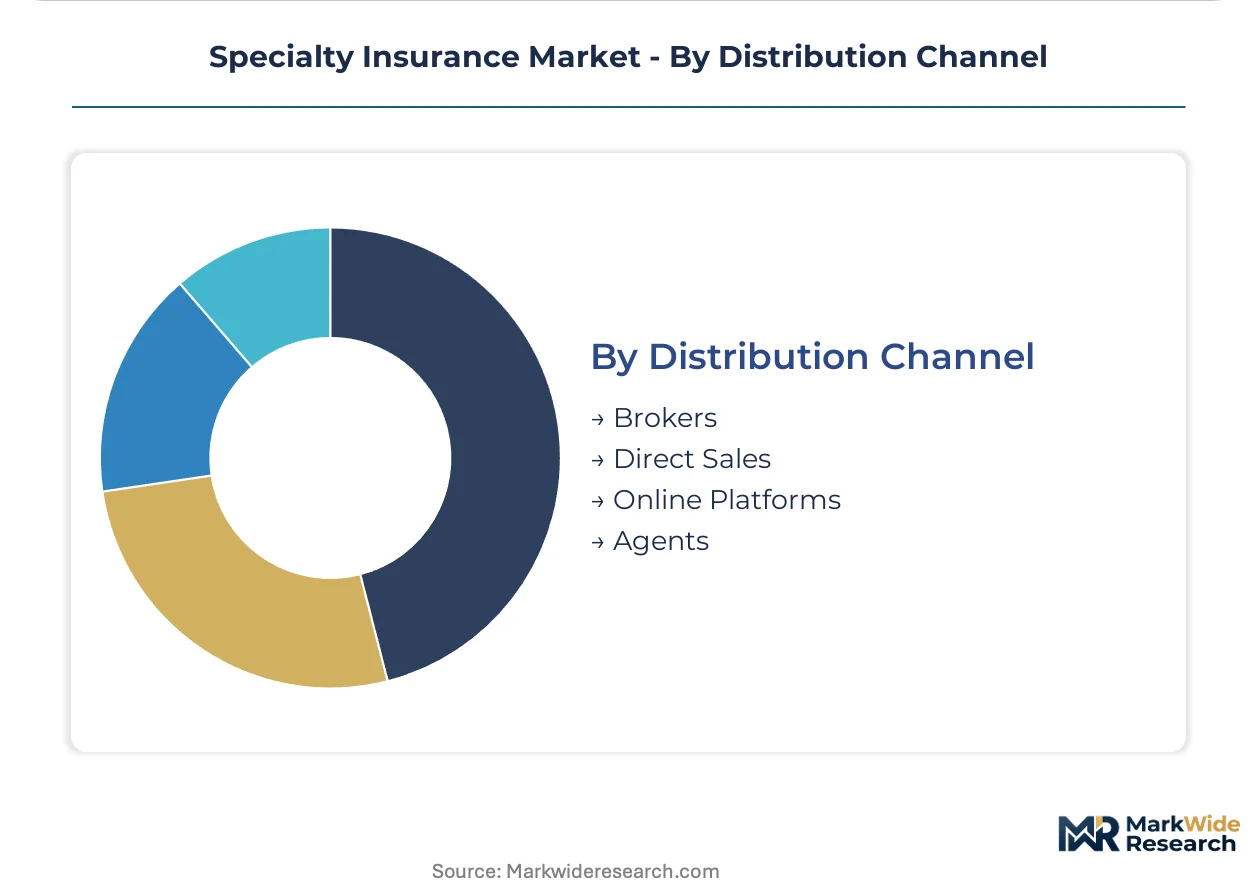
Brokers intermediate the majority of premium volume. Online platforms are climbing the fastest amid API integration with commercial SaaS ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium volume through Silicon Valley technology clusters and Texas energy corridors, while Germany anchors European specialty underwriting through industrial manufacturing demand and stringent regulatory frameworks.
United States
SEC cybersecurity disclosure rules and Delaware corporate litigation generate sustained demand for Directors & Officers coverage. The NAIC shapes capital adequacy standards that govern cross-state specialty placements. Silicon Valley venture capital deployment and New York financial advisory practices concentrate manuscripted technology errors and omissions demand.
Germany
Industrial manufacturing supply chains and renewable energy infrastructure drive climate litigation defense requirements. The EU's CSRD mandates granular climate risk disclosures across corporate supply chains. Frankfurt banking corridors and Bavarian automotive clusters generate compliance-driven demand for cyber resilience coverage.
United Kingdom
Lloyd's syndicates set global benchmarks for syndicated specialty underwriting through the PRA and FCA dual regulatory structure. The UK Prudential Regulation Authority governs risk-based capital for catastrophe-exposed commercial risks. London market brokers dominate cross-border multinational program placements.
Japan
METI carbon disclosure mandates for listed corporations generate greenwashing liability coverage demand. Supply chain emissions reporting requirements reshape underwriting submissions for climate litigation defense. Tokyo commercial risk managers and Osaka manufacturing belts concentrate captive insurance formation activity.
India
Semiconductor and pharmaceutical production incentives under the PLI scheme create underpenetrated demand for product recall coverage. The RBI governs financial services capital requirements that intersect with specialty cyber mandates. Gujarat manufacturing corridors and Karnataka technology parks concentrate contingent business interruption placement growth.
Specialty Insurance Market Key Industry Players
Top-tier vendors anchor global underwriting platforms, while regional specialists compete through delegated authority partnerships and direct digital distribution. The market structures around three tiers: integrated multinationals with facultative reinsurance capabilities, niche carriers with vertical-specific manuscript expertise, and technology-native entrants with API-enabled distribution. Consolidation pressures favor carriers with transparent pricing methodologies and algorithmic underwriting engines. Dominant competitive moves include strategic partnerships with managing general agents and portfolio diversification into parametric trigger products.
Within the integrated multinational tier, Chubb and Zurich Insurance Group exemplify carriers with global underwriting infrastructure and high-net-worth personal lines dominance. Hiscox occupies a position among digitally native specialists, leveraging direct distribution for SME-focused cyber and media liability. Tokio Marine HCC represents the delegated authority model, competing through managing general agent partnerships in accident and health specialty segments.
| Leading Market Players |
|---|
| AXA |
| Chubb |
| Zurich Insurance Group |
| Allianz |
| American International Group |
| Assicurazioni Generali |
| AXA XL |
| Hiscox |
| Tokio Marine HCC |
| Others |
Cost & Logistics Intelligence
Parametric trigger structures and algorithmic underwriting engines are compressing policy development cycles while simultaneously redistributing capital deployment toward technology-native carriers with lower fixed-cost infrastructure. This shift erodes traditional pricing power among established players while creating tiered cost advantages based on data ingestion capabilities and facultative reinsurance access.
Pricing Analysis
Capacity additions in Bermuda and London retrocession markets are reshaping price floors for catastrophe-exposed specialty lines. Three-tier pricing structure across manuscripted, semi-standardized, and commoditized coverage levels differentiates Lloyd's syndicate offerings from direct digital platforms. Pricing pressure stems from alternative risk transfer mechanisms absorbing previously ceded risks. Fortune 500 risk managers exhibit lowest price sensitivity given captive participation options, while SME buyers through online platforms drive hardest bargain on cyber and event coverage.
Supply Chain Analysis
Regional distribution centers in London, New York, and Bermuda anchor hub-and-spoke patterns for facultative reinsurance placement and claims settlement execution. Capital concentration flows through Lloyd's syndicates, Bermuda reinsurers, and European mutuals. Underwriting talent and catastrophe modeling expertise draw from UK, US, and Swiss labor pools. Single-source vulnerability sits with legacy core policy administration platforms resisting API connectivity. Distribution runs through wholesale brokers for complex towers and direct platforms for standardized lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty insurance functions as a stable compounder where regulatory compliance mandates generate recurring coverage demand across financial services and technology verticals.
For Market Incumbents: Lock in manuscript expertise advantages by deepening facultative reinsurance relationships with London and Bermuda markets. Acquire algorithmic underwriting capabilities to defend against technology-native entrants compressing quote turnaround times below 24 hours. Prioritize API integration investments over legacy system patchwork. For New Entrants and Emerging Players: EU DORA in Frankfurt and Dublin banking corridors opens a window for cyber resilience coverage specialists to capture compliance-driven demand spikes before incumbent platforms adapt. Target India's PLI manufacturing corridors for product recall and contingent business interruption white space. Deploy embedded insurance distribution through commercial SaaS platform partnerships as primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among delegated authority specialists with managing general agent networks in accident and health segments. Long-term viability hinges on transition risk assessment capabilities for climate litigation defense. Watch Lloyd's syndicate performance transparency metrics as inflection indicator for capital rotation into algorithmically defensible pricing methodologies.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Enables 48-hour satellite-triggered disbursements for agricultural and municipal utility risks. |
| Managing General Agent Partnership | Accelerates market entry in accident and health segments through delegated underwriting authority. |
| API Platform Integration | Captures SME cyber and media liability demand through sub-24-hour algorithmic quote generation. |
| Climate Risk Assessment Capability | Addresses EU CSRD supply chain disclosure mandates for German industrial and Nordic renewable placements. |
| Side-A Capacity Expansion | Meets Delaware litigation severity trends through dedicated personal asset protection clauses. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured perspectives from specialty underwriters, Lloyd's coverholders, catastrophe modelers, managing general agents, and commercial risk managers. Secondary validation drew from NAIC capital adequacy filings, Lloyd's performance data, SEC cybersecurity disclosure records, and EU regulatory implementation texts. Bottom-up premium volume estimates triangulated against top-down market sizing from reinsurance broker aggregates.
Historical reference periods anchored the projection horizon to observed loss development patterns and regulatory implementation timelines. Segmentation modeling spanned coverage type, client sophistication tier, industry vertical, and distribution channel complexity. CAGRs derived from loss cost trend analysis, rate change indices, and exposure growth assumptions across Silicon Valley technology clusters and Texas energy corridors.
Revisions become necessary when retrocession capacity contractions, climate catastrophe frequency shifts, or regulatory enforcement intensity changes materialize outside modeled assumptions. Forecasts reflect documented judgment calls on loss reserve adequacy and facultative reinsurance availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Canada Property and Casualty Insurance Market
Insurance
Directors and Officers (Dando) Insurance Market
Insurance
Insurance BPO Services Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
Telecommunication Insurance Market
Insurance
Engineering Insurance Market
Insurance
Medical Claims Processing Services Market
Insurance
Africa Microinsurance Market
Insurance
Europe Parametric Insurance Market
Insurance
India Dental Insurance Market
Insurance
Peru Insurance Market
Insurance
Marine Crew Insurance Market
Insurance
Austria Property and Casualty Insurance Market
Insurance
Cloud Computing in Insurance Market
Insurance
Takaful Insurance Market
Insurance
Digital Monetary Insurance Market