
 UK Dental Insurance Market | 2026-2036
UK Dental Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
UK Dental Insurance Market Outlook
Employer uptake of dental benefits is recalibrating the customer mix, with group and employer-sponsored plans displacing individual policies as the fastest-growing acquisition channel. Bupa leverages its integrated healthcare ecosystem to cross-sell dental coverage alongside private medical insurance. Simplyhealth anchors the SME segment through flexible capitation products designed for businesses with fewer than two hundred and fifty employees. Denplan specializes in practice-branded payment plans that extend dentist loyalty beyond traditional insurance frameworks.
Dental insurance constitutes a risk-transfer mechanism covering preventive, routine, and restorative oral health procedures against premium payments, typically underwritten with age-banded or community-rated pricing structures. The coverage type dimension splits between basic preventive-only policies and comprehensive plans incorporating orthodontics and implants, with the latter commanding premium multiples of three to five times. Employer-sponsored and group segments concentrate volume, while individual and family plans generate higher per-policy margins due to adverse selection dynamics. Capitation models dominate the payment model landscape for practice-affiliated schemes, whereas fee-for-service and reimbursement structures prevail in direct insurer-to-consumer distribution.
The Financial Conduct Authority's Consumer Duty mandates clear value assessments and fair treatment standards across all dental insurance product designs. The Competition and Markets Authority scrutinizes renewal pricing practices, pressuring insurers to justify premium escalations with documented claims experience. Stakeholders must monitor how the FCA's ongoing affordability framework consultations reshape distribution commission structures and product simplification requirements.
Market Dynamics
The Financial Conduct Authority's Consumer Duty is compressing product design cycles and forcing insurers to reprice legacy policies against documented claims experience. This regulatory pressure is reshaping distribution economics and accelerating the shift from individual to employer-sponsored acquisition channels.
Growth Catalysts
- Workplace wellness budget expansion:Mid-sized UK enterprises are redirecting occupational health spending toward preventive dental benefits. HR departments cite employee retention metrics as the primary justification for capitation plan adoption.
- FCA Consumer Duty transparency mandates:Clearer value assessments are reducing policyholder confusion and shortening sales cycles. Simplified product structures are lowering customer acquisition costs for direct-to-consumer distribution.
- Private dental practice density concentration:Greater London and the South East host disproportionate provider networks. Geographic clustering enables insurer-practice partnership models that reduce administrative friction.
Market Restraints
- Adverse selection in individual policy pools:Self-selecting enrollees with pre-existing conditions inflate claims ratios. Community-rated pricing structures struggle to absorb this risk concentration.
- Orthodontic and implant cost volatility:Material inputs and specialist labor rates fluctuate unpredictably. Comprehensive plan underwriters face margin compression when premium adjustments lag cost movements.
- Competition and Markets Authority renewal pricing scrutiny:Documented justification requirements for premium escalations constrain pricing flexibility. Insurers must invest in actuarial infrastructure to defend rate increases.
Strategic Opportunities
- Underpenetrated Northern England and Midlands corridors:Household disposable income gaps suppress individual policy uptake. Employer-sponsored group products offer lower per-capita acquisition costs in these postcodes.
- Tele-dental triage integration:Remote diagnostic platforms are converging with traditional insurance workflows. Early adopters are embedding virtual consultations into preventive coverage tiers.
- Capitation model standardization:Practice-branded payment plans outside traditional insurance frameworks capture patient loyalty. Insurers can white-label these structures for dental network exclusivity.
Industry Challenges
- Actuarial talent scarcity for dental-specific risk modeling:Generalist underwriters lack oral health procedure expertise. Specialist recruitment competes with broader health insurance verticals.
- Legacy policy administration system integration:Core platforms built for medical insurance require dental procedure code reconfiguration. Migration timelines stretch 18-24 months for established carriers.
- Commission structure recalibration under affordability consultations:The FCA's ongoing distribution review threatens intermediary remuneration models. Product simplification mandates may eliminate tiered advisor incentives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Dental Insurance Market |
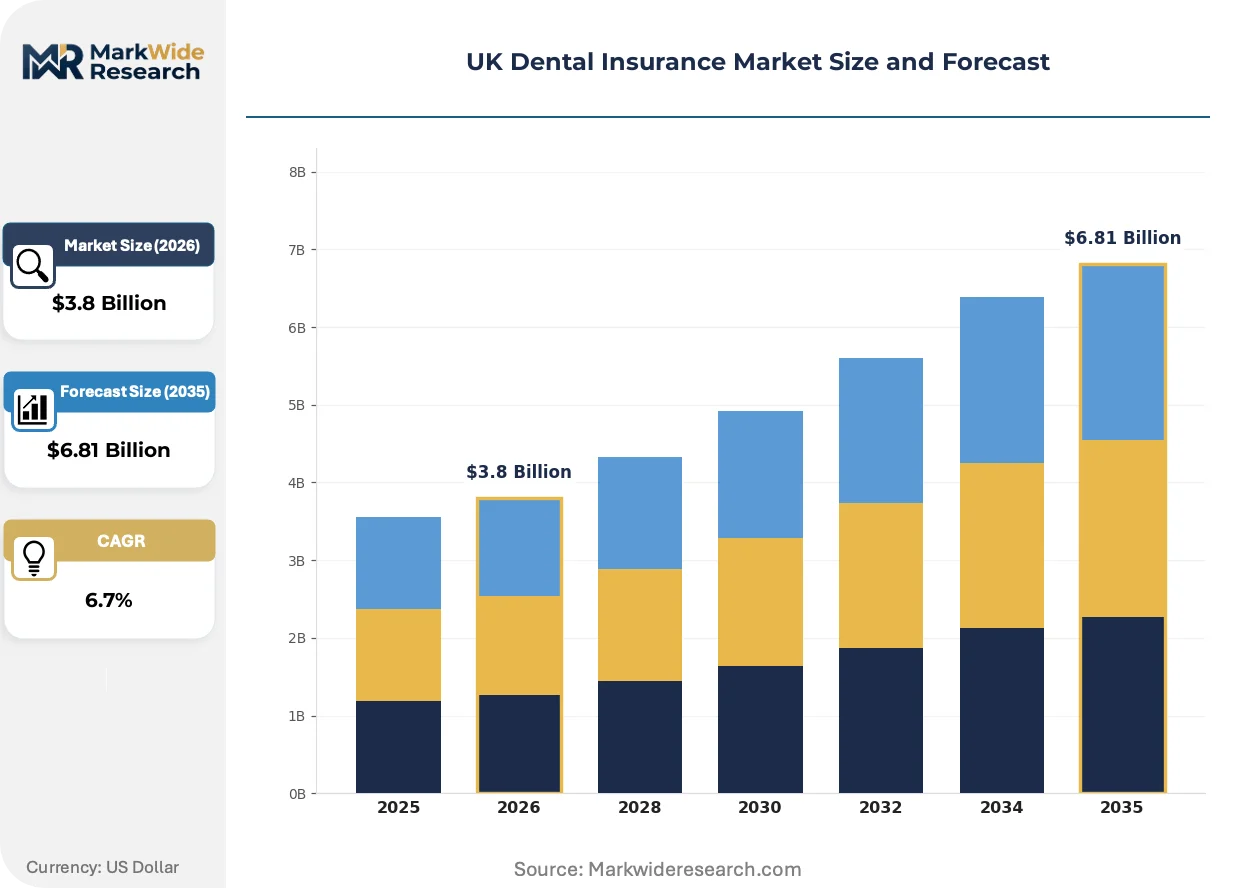
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Basic Coverage, Comprehensive Coverage, Major Services, Preventive Services Policy Duration: Annual Plan, Multi-Year Plan, Short-Term Plan, Lifetime Coverage Customer Type: Individual, Family, Group, Employer-Sponsored Payment Model: Per Visit, Capitation, Fee-for-Service, Reimbursement |
| Companies Covered | Simplyhealth, Cigna, Bupa, Unum, Dencover, AXA Health, Vitality Health, Denplan, Concordia Financial Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Dental Insurance Market Strategic Shifts
Digital distribution infrastructure and regulatory data requirements are converging to reshape how dental coverage reaches policyholders. Insurers are rebuilding core systems around transparency mandates and employer-centric acquisition flows.
Artificial intelligence claims adjudication is expanding into routine preventive and restorative procedure verification. Mid-sized UK insurers are deploying machine learning models to accelerate pre-authorization decisions. This compression of administrative overhead is enabling same-day coverage activation for employer group enrollments.
The Financial Conduct Authority's Consumer Duty rules are mandating annual value assessments with documented fair treatment evidence. Product teams must redesign policy documents and marketing materials to meet comprehension benchmarks. SME-focused distributors are investing in plain-language translation to avoid regulatory enforcement actions.
Employer-sponsored enrollment is displacing individual direct purchase as the dominant acquisition path. HR technology platforms are embedding dental benefit selection into annual benefits administration workflows. This channel shift concentrates volume in group underwriting pools while reducing adverse selection exposure for insurers.
UK Dental Insurance Market Segmentation
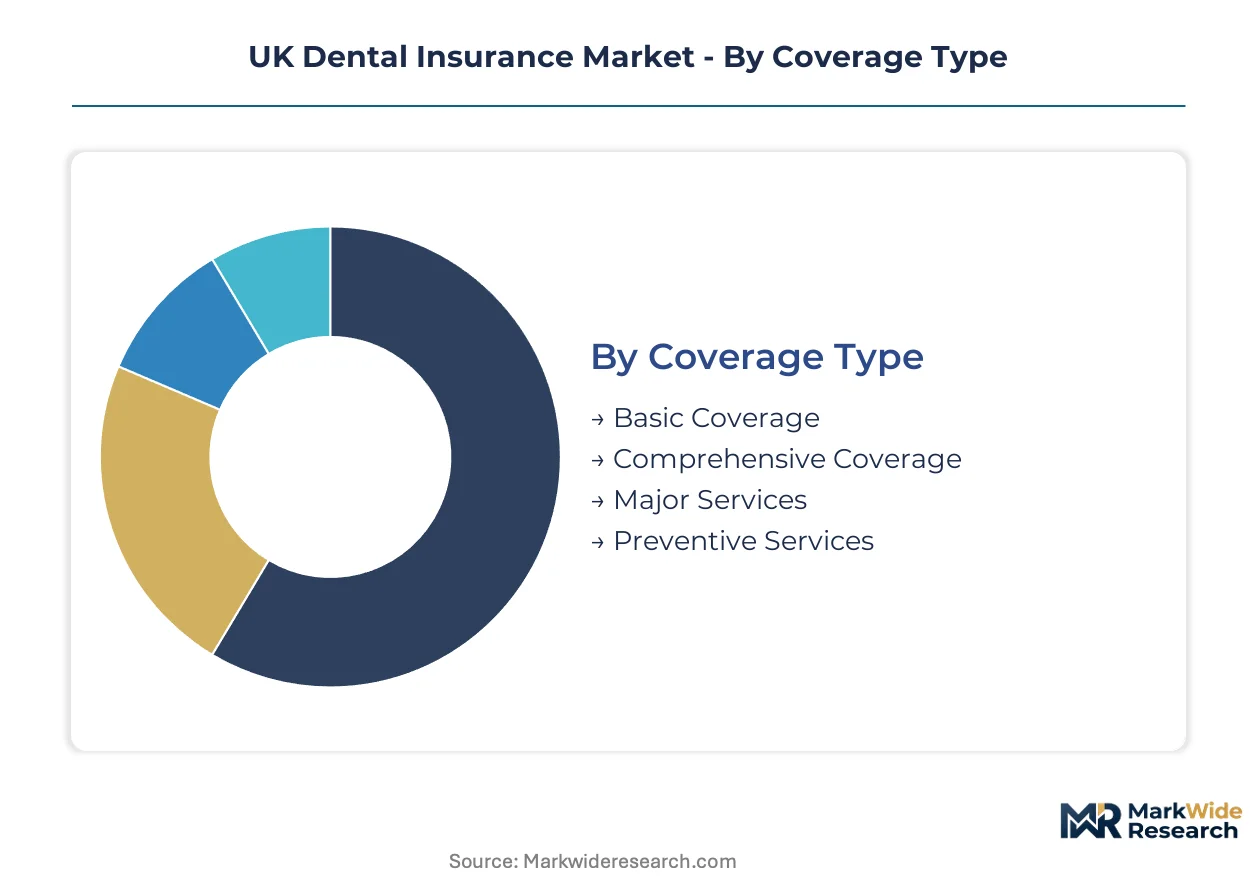
Dental insurance segmentation in the UK market reflects divergent risk appetites across consumer groups and payment structures. Each dimension carries distinct regulatory obligations and margin profiles that shape product development priorities for underwriters.
Coverage Type:
FCA Consumer Duty compliance requirements vary by coverage depth, with comprehensive plans facing heightened scrutiny on value assessment documentation.
- Basic Coverage:Policies covering preventive examinations, scale-and-polish procedures, and routine X-rays with limited annual claim ceilings. Demand concentrates among young professionals in Greater London seeking NHS top-up protection against treatment delays. These plans carry lower premium multiples but require simplified disclosure formats under FCA transparency mandates.
- Comprehensive Coverage:Full-spectrum protection incorporating restorative fillings, crowns, bridges, and selected periodontal therapies. Employer-sponsored pools in the South East drive volume concentration here, with HR departments citing recruitment competitiveness as the primary selection driver. Higher premium multiples necessitate detailed claims experience reporting for renewal pricing justification.
- Major Services:Extended protection for complex procedures including root canals, extractions, and denture work. These mid-tier products appeal to families in suburban corridors balancing premium costs against unpredictable treatment needs.
- Preventive Services:Examination-focused policies with minimal intervention coverage. Capitation models dominate this segment through practice-branded payment plans that extend patient loyalty beyond traditional insurance frameworks.
Leading the category by volume: Basic Coverage. Growing fastest: Comprehensive Coverage.
Policy Duration:
Duration selection correlates with customer acquisition channel, with employer-sponsored enrollments favoring annual alignment with benefits cycles.
- Annual Plan:Standard 12-month terms with guaranteed renewal rights. These contracts dominate the employer-sponsored channel, where HR platforms synchronize dental selections with April tax-year benefits administration. The FCA's affordability framework consultations are pressuring insurers to simplify annual renewal communications.
- Multi-Year Plan:Two-to-five year terms with locked premium rates. Individual purchasers in high-inflation postcodes favor these structures for cost predictability, though underwriters face margin compression when claims inflation exceeds pricing assumptions.
- Short-Term Plan:Temporary coverage bridging employment gaps or awaiting NHS treatment. Limited distribution through comparison sites with restricted benefit schedules.
- Lifetime Coverage:Continuous protection with no term expiration, rare in direct-to-consumer distribution but embedded in some legacy corporate trust arrangements.
Annual Plan holds the volume base. Multi-Year Plan shows steepest expansion trajectory as inflation-conscious consumers seek rate certainty.
Customer Type:
Channel economics diverge sharply between individual and group pools, with adverse selection dynamics determining underwriting approach.
- Individual:Direct-purchase policies selected by self-employed professionals and retirees. Claims ratios run elevated due to self-selection bias, compressing margins despite higher per-policy premiums. FCA Consumer Duty rules mandate enhanced suitability assessments for this channel.
- Family:Multi-member coverage with dependent child provisions including orthodontic benefits. Demand concentrates in affluent suburbs where private school catchments correlate with dental practice density.
- Group:Voluntary enrollment through membership organizations and affinity partnerships. These structures pool risk across heterogeneous populations, improving loss ratios compared to individual pools.
- Employer-Sponsored:Workplace benefits with mandatory or opt-out enrollment. Mid-sized enterprises with 50-250 employees represent the fastest-expanding segment, as occupational wellness budgets redirect toward preventive oral health.
Employer-Sponsored is gaining share fastest. Individual retains highest per-policy margin despite volume erosion.
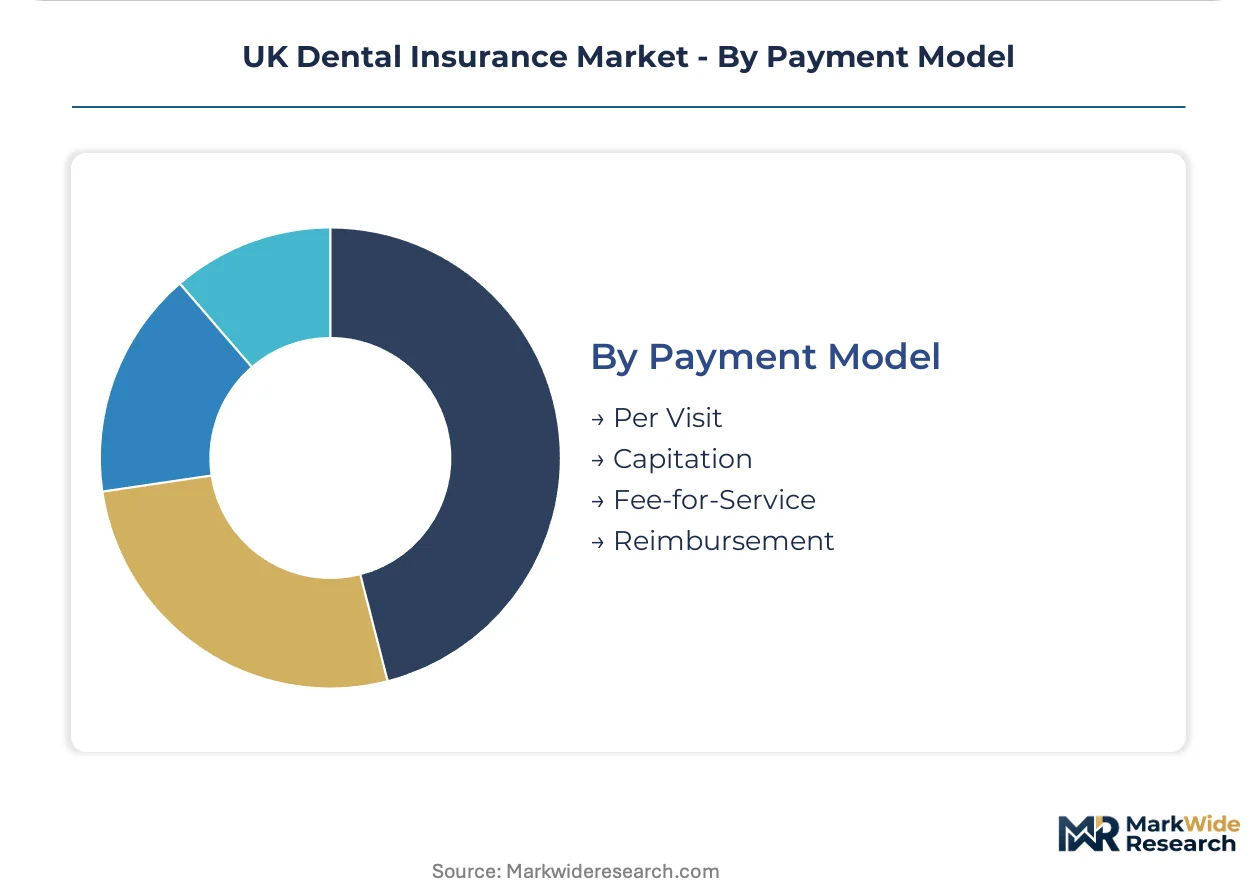
Payment Model:
Administrative infrastructure requirements vary by payment structure, with capitation models demanding practice network integration.
- Per Visit:Fixed copayments per appointment with balance billing for non-covered services. Simplified administration appeals to direct-to-consumer distributors seeking rapid policy activation.
- Capitation:Fixed monthly payments to dental practices covering contracted service bundles. Denplan's practice-branded structures dominate this segment, with insurers white-labeling these arrangements for network exclusivity. The model requires sophisticated practice quality monitoring and utilization management.
- Fee-for-Service:Itemized reimbursement based on submitted procedure codes. Legacy administration systems built for medical insurance require dental code reconfiguration, stretching migration timelines 18-24 months for established carriers.
- Reimbursement:Patient pays upfront with subsequent insurer repayment. Higher administrative friction limits scalability but appeals to policyholders prioritizing provider choice.
Capitation leads by policy count. Fee-for-Service retains dominance in comprehensive coverage tiers despite infrastructure burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise zones across Greater London and the South East concentrate dental insurance demand through elevated private practice density and occupational wellness budget expansion. The Financial Conduct Authority's Consumer Duty rules apply uniformly, yet regional income disparities reshape product penetration patterns.
Greater London
Financial services and professional services firms drive employer-sponsored enrollment through expanded occupational health budgets. The FCA's Consumer Duty mandates clear value assessments for all policies distributed within this jurisdiction. Canary Wharf and the City host dense concentrations of mid-sized enterprises adopting capitation plans for retention metrics.
South East England
Affluent suburban corridors generate family policy demand tied to private school catchments and orthodontic benefit utilization. NHS waiting list pressures push households toward comprehensive private coverage. Brighton, Oxford, and Guildford cluster high-net-worth individual purchasers seeking major services protection.
Midlands
Manufacturing and logistics employers represent underpenetrated group policy potential as workplace wellness budgets redirect toward preventive benefits. The Competition and Markets Authority's renewal pricing scrutiny applies equally here, constraining premium flexibility. Birmingham and Nottingham anchor emerging insurer-practice partnership models.
North England
Household disposable income gaps suppress individual policy uptake, yet employer-sponsored products offer lower per-capita acquisition costs. The FCA's affordability framework consultations threaten intermediary remuneration models across this postcode. Manchester and Leeds concentrate nascent tele-dental triage integration efforts.
Scotland
Devolved health policy creates distinct NHS dentistry access patterns that shape supplementary insurance design. Scottish Enterprise zones incentivize occupational benefit expansion among technology employers. Edinburgh and Glasgow host divergent private practice density profiles that fragment distribution economics.
UK Dental Insurance Market Competitive Environment
Top-tier vendors anchor integrated healthcare ecosystems, while specialized dental payment plan operators occupy distinct loyalty-driven niches. The market structure reflects tiered concentration around four to six dominant underwriters with meaningful scale, supplemented by regional specialists and affinity distributors. Strategic archetypes include ecosystem-integrated health insurers, practice-branded capitation specialists, and SME-focused flexible benefit providers. Competitive moves center on cross-selling dental coverage alongside private medical insurance and white-labeling capitation structures for network exclusivity.
Within the ecosystem-integrated tier, Bupa and Simplyhealth exemplify divergent scale approaches. Bupa leverages its healthcare infrastructure to cross-sell dental coverage through existing medical insurance relationships. Simplyhealth anchors the SME segment through capitation products designed for businesses with fewer than two hundred and fifty employees. Denplan occupies a distinct position as a practice-branded payment plan specialist extending dentist loyalty beyond traditional insurance frameworks.
| Leading Market Players |
|---|
| Simplyhealth |
| Cigna |
| Bupa |
| Unum |
| Dencover |
| AXA Health |
| Vitality Health |
| Denplan |
| Concordia Financial Group |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up dental practice networks anchor supply-side consolidation across Greater London and the South East, concentrating provider negotiating power and compressing capitation rate flexibility for insurers underwriting employer-sponsored group policies.
Pricing Analysis
Premium multiples for short lead-time enrollment in employer group cycles command three-to-five-fold rate advantages over individual policy spot purchases. Three-tier pricing structure across comprehensive, major services, and preventive levels stratifies by orthodontic inclusion and implant coverage depth. Pricing pressure stems from FCA Consumer Duty-mandated value assessment documentation raising administrative overhead. SME HR departments show lowest price sensitivity given retention-metric justification, while self-employed individual purchasers in Northern England exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Greater London, Birmingham, and Manchester anchor hub-and-spoke dental network deployment. Clinical labor supply concentrates in England's South East and Greater London, with equipment and consumable inputs drawing from German and Swiss manufacturers. Single-source vulnerability runs through specialized orthodontic material suppliers facing Swissmedic export certification delays. Distribution runs through practice-branded capitation partnerships dominating preventive service tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
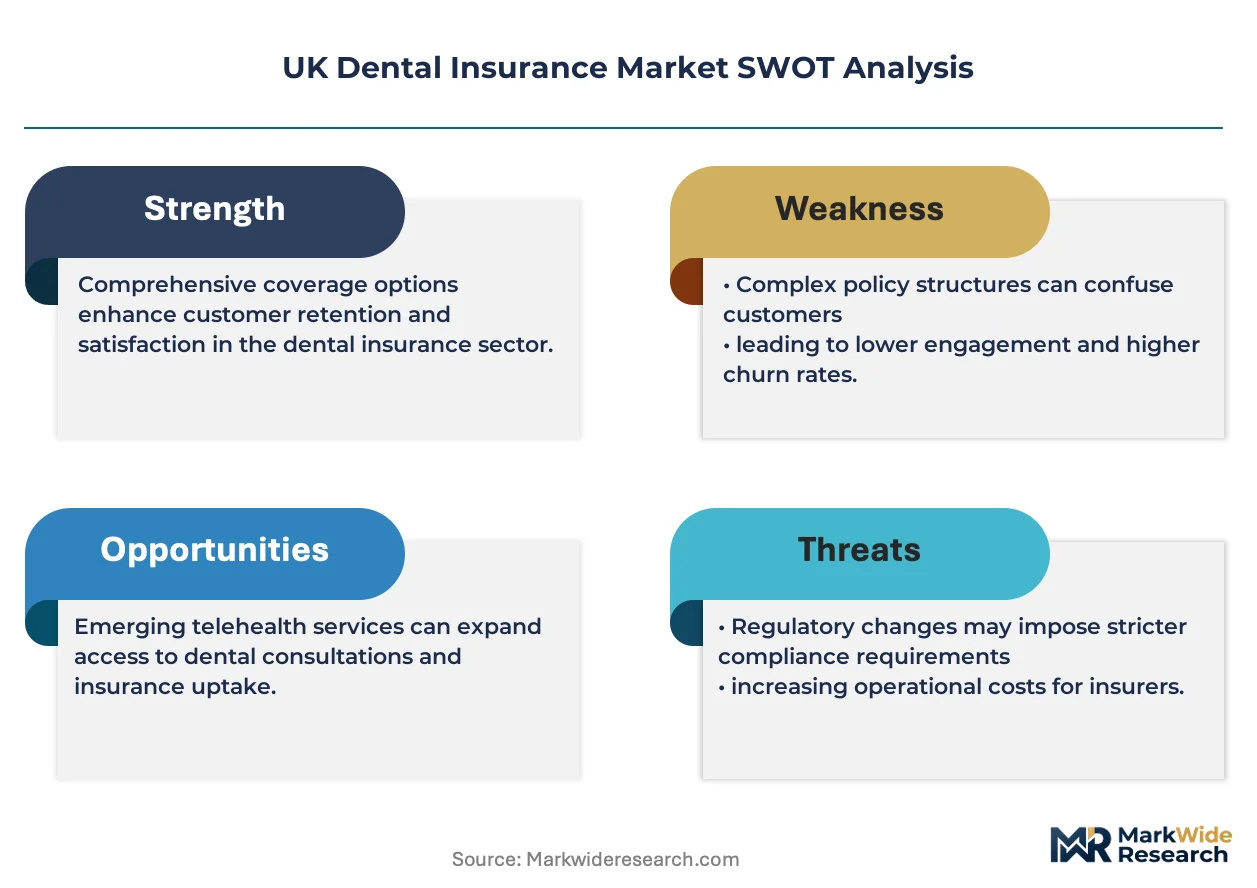
The UK Dental Insurance Market functions as a cost-of-compliance story where FCA Consumer Duty rules erect barrier-to-entry moats favoring established players with actuarial infrastructure to defend renewal pricing.
For Market Incumbents: Cement cross-selling integration between dental and private medical insurance lines through Bupa-style healthcare ecosystem leverage. Deepen practice network exclusivity via white-labeled capitation structures to preempt Simplyhealth's SME channel dominance. Counter adverse selection erosion by redirecting individual policy volume toward employer-sponsored group pools with mandatory enrollment mechanics.
For New Entrants and Emerging Players: The mid-market price-point gap between Denplan's practice-branded economy tiers and Bupa's premium comprehensive coverage offers white-space entry. Target underpenetrated Northern England employer-sponsored segments where per-capita acquisition costs run below national averages. Deploy tele-dental triage integration as differentiated go-to-market anchor for preventive service distribution.
For Investors and Strategic Acquirers: FCA affordability framework consultation finalization is the leading indicator that distribution commission restructuring will reshape intermediary economics. Long-term viability centers on platforms with direct employer enrollment technology bypassing advisor-dependent channels. Acquisition focus: SME-focused capitation specialists with proprietary practice network density in Midlands growth corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Capitation Model Standardization | Denplan's practice-branded structures enable insurer white-labeling for network exclusivity. |
| Tele-Dental Triage Integration | Remote diagnostic platforms embed into Simplyhealth's preventive coverage tiers. |
| Cross-Sell Infrastructure Buildout | Bupa leverages medical insurance relationships to capture dental policy attach rates. |
| SME Channel Technology Investment | HR platform embedding reduces acquisition friction for mid-sized enterprise enrollment. |
| Actuarial Talent Acquisition | Oral health procedure expertise defends against FCA renewal pricing scrutiny. |
Study Parameters
Multi-period observation of employer-sponsored enrollment velocity, capitation rate negotiations, and FCA enforcement patterns anchored the trend analysis, supplemented by interviews with dental practice owners, insurer product development directors, HR benefits administrators, and regulatory compliance officers. Secondary validation drew from Financial Conduct Authority consultation papers, Competition and Markets Authority market studies, NHS dentistry access statistics, and UK Office for National Statistics household income data. Bottom-up policy volume modeling and top-down market size triangulation converged on segment-level estimates.
Segment-weighting across coverage type, policy duration, customer type, and payment model dimensions structured the analytical framework. CAGRs were derived from fitted growth curves calibrated to documented enrollment shifts and premium rate trajectories across the projection horizon. Employer wellness budget expansion rates and private practice network density served as industry-specific forecast inputs.
Inputs from regulatory filings and dental practice association surveys were available through the study window; gaps in real-time claims experience data from closed-book legacy policies introduce uncertainty bands around renewal pricing projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
Asia-Pacific Liability Insurance Market
Insurance
Cyber Liability Insurance Market
Insurance
Microinsurance Market
Insurance
Identity Theft Insurance Market
Insurance
Gap Insurance Market
Insurance
Endowment Insurances Market
Insurance
Marine Crew Insurance Market
Insurance
Boiler Insurance Market
Insurance
USA Travelers Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
US Travel Insurance Market
Insurance
Horse Insurance Market
Insurance
Europe Parametric Insurance Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Djibouti Insurance Market