
 Austria Solar Energy Market | 2026-2036
Austria Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Solar Energy Market Outlook
Software-defined energy management is shifting how Austrian solar providers monetize installations beyond hardware sales. Wien Energie GmbH leverages its municipal utility scale to dominate Vienna's rooftop leasing programs. Fronius International GmbH anchors inverter and energy management technology leadership through Graz-based R&D operations. KPV Solar GmbH specializes in agricultural dual-use photovoltaics across Styria's wine-growing zones.
Austria solar energy encompasses photovoltaic systems converting sunlight into direct current electricity through silicon-based semiconductor junctions, typically operating at 15-22% conversion efficiency for crystalline modules and feeding into 230/400V distribution grids or centralized 110kV transmission networks. The technology serves residential self-consumption, commercial peak shaving, and utility-scale feed-in across Alpine and Danube basin geographies. Photovoltaic arrays lead installed capacity due to modular scalability and declining module costs, while building-integrated photovoltaics (BIPV) represent the fastest-growing product category as Austria's building codes tighten envelope energy standards. Crystalline silicon technology sustains manufacturing investment despite thin-film alternatives gaining traction in facade-integrated applications where weight constraints matter.
Austria's EAG framework and EU Green Deal compliance obligations shape project economics through feed-in tariff structures and accelerated permitting timelines. BIS-relevant standards for module durability and ÖNORM technical specifications govern product certification and grid interconnection protocols. Stakeholders must monitor grid congestion in western federal states and storage co-location requirements as photovoltaic penetration rises beyond distribution network hosting capacity.
Market Dynamics
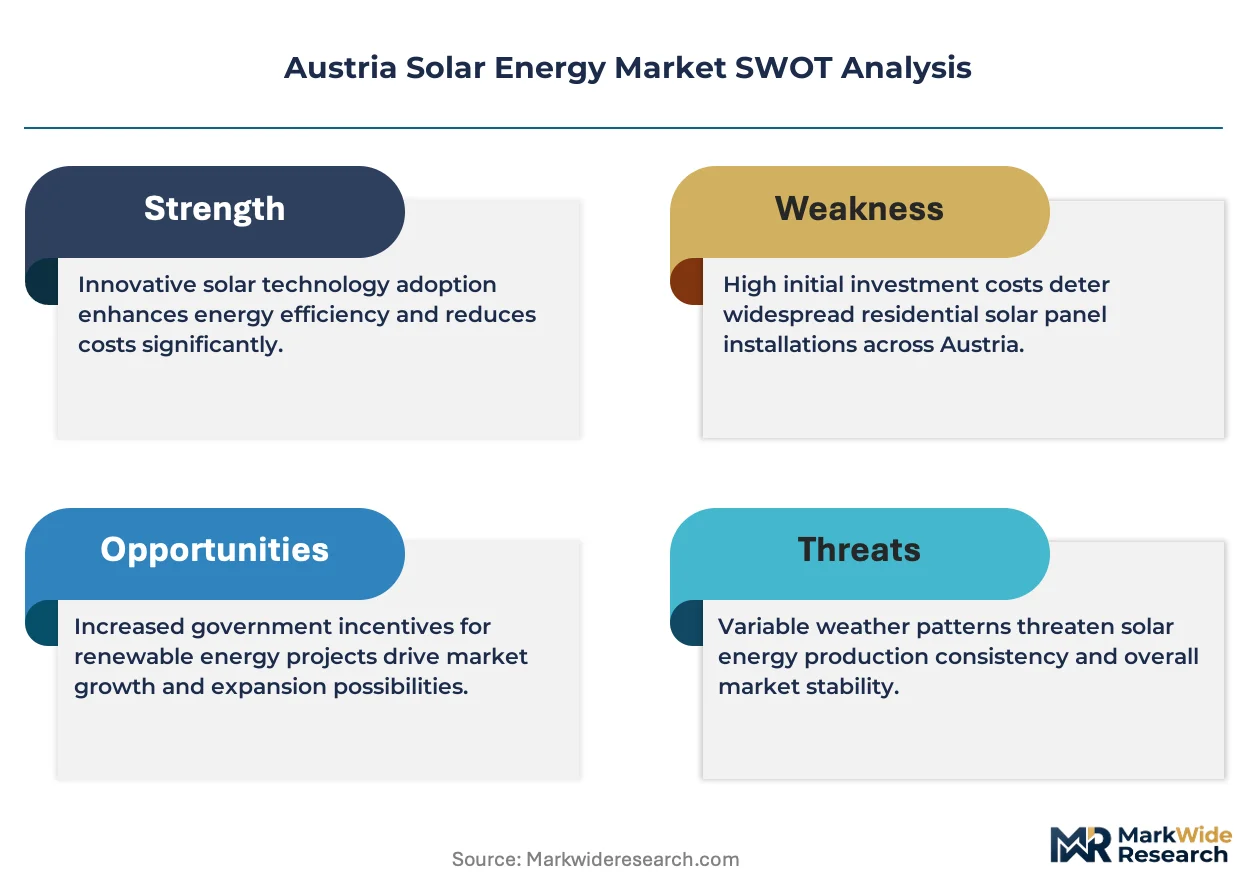
Austria's Renewable Expansion Act (EAG) has compressed permitting timelines for commercial solar installations, triggering a structural shift in how developers sequence land acquisition, grid interconnection applications, and module procurement contracts.
Growth Catalysts
- Feed-in tariff restructuring:The EAG's streamlined remuneration framework accelerates project returns for photovoltaic arrays above 25 kW, concentrating developer activity in Lower Austria's Weinviertel corridor.
- Building-integrated photovoltaics mandate:Tightening ÖNORM envelope energy standards force commercial construction to embed solar generation directly into facades and roofing systems.
- Agricultural dual-use expansion:Styria's wine-growing zones increasingly host elevated photovoltaic arrays that preserve grape cultivation underneath, unlocking land-constrained deployment.
Market Restraints
- Polysilicon supply concentration:Austria's photovoltaic module assemblers depend on Chinese polysilicon refiners, exposing project economics to input cost volatility and trade policy friction.
- Distribution grid hosting capacity:Western federal states face transformer saturation and voltage rise constraints that delay interconnection approvals for utility-scale solar parks.
- Seasonal generation mismatch:Alpine topography and winter cloud cover reduce capacity factors for fixed-tilt installations, limiting bankability without storage co-location.
Strategic Opportunities
- Grid-scale battery pairing:Co-located lithium-ion storage captures price arbitrage in Austria's wholesale electricity market and satisfies EAG flexibility requirements for large solar submissions.
- Municipal rooftop leasing:Vienna's dense urban fabric offers untapped commercial roof inventory where Wien Energie GmbH-style programs can scale behind-the-meter generation without land acquisition.
- Agrivoltaic standardization:Federal agricultural subsidies for dual-use systems could replicate Styria's wine-sector model across Burgenland's crop belts and pasturelands.
Industry Challenges
- Electrical engineering talent scarcity:Grid interconnection specialists and medium-voltage design engineers command premium wages as project pipelines expand beyond workforce training capacity.
- ÖNORM certification timelines:Module durability testing and inverter compliance verification create six-to-nine-month pre-construction delays that compress construction windows.
- Legacy building stock retrofit complexity:Vienna's historic preservation districts impose structural load and aesthetic constraints that fragment BIPV deployment economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Solar Energy Market |
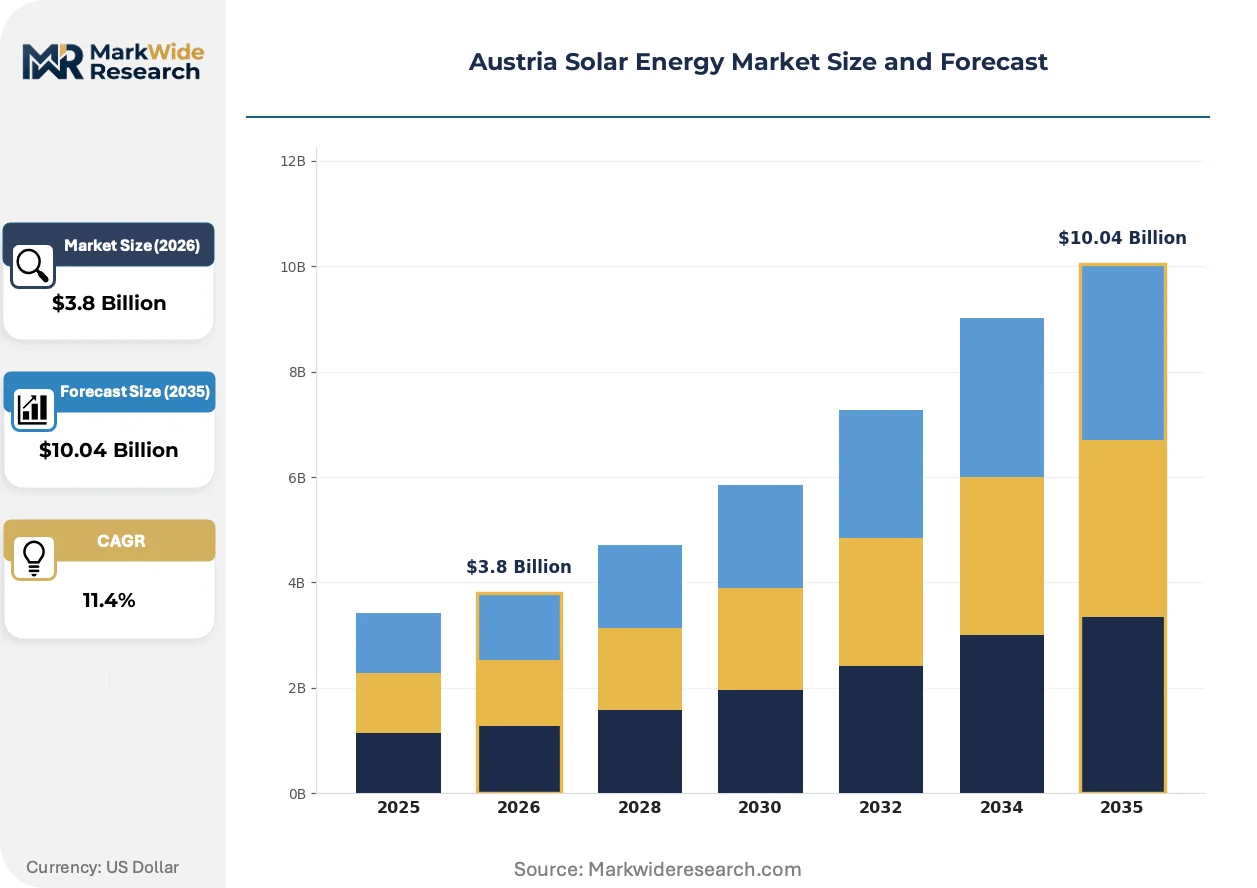
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic, Concentrated Solar Power, Solar Thermal, BIPV Application: Residential, Commercial, Industrial, Utility Scale Technology: Thin-Film, Crystalline Silicon, Multi-Junction, Organic Photovoltaics Installation Type: Ground-Mounted, Roof-Top, Floating Solar, Building-Integrated |
| Companies Covered | KPV Solar GmbH, Energie Steiermark AG, Wien Energie GmbH, Secundo Photovoltaik GmbH, Selina Photovoltaic GmbH, Verbund AG, Burgenland Energie, Ökovolt Solartechnik GmbH, Fronius International GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Solar Energy Market Strategic Shifts
Software-defined energy management is reconfiguring how Austrian solar assets generate revenue, shifting value capture from hardware margins toward dispatch optimization, grid services, and behind-the-meter energy arbitrage.
Bifacial photovoltaic modules are penetrating utility-scale installations in Lower Austria's flat agricultural zones. Large developers specify these double-sided collectors to harvest reflected irradiance from light-colored soil surfaces. This technology is converging with tracker mounting systems that adjust tilt angles throughout the day, squeezing additional yield from fixed land footprints without expanding acreage requirements.
The EU Green Deal's tightened carbon border adjustment mechanisms are reshaping module procurement strategies. Austrian project sponsors now prioritize European-manufactured crystalline silicon panels to avoid embedded emissions penalties, even at modest cost premiums. Commercial rooftop segments in Vienna and Graz respond fastest, as corporate offtakers face CSRD disclosure pressure to document supply chain carbon intensity.
Energy-as-a-service contracting is displacing direct equipment ownership among midsize commercial offtakers. Third-party operators install, maintain, and dispatch photovoltaic-plus-storage systems while customers pay fixed per-kWh rates. Styria's industrial manufacturing facilities and Tyrol's hospitality clusters exhibit the strongest uptake, as these sectors prioritize balance-sheet efficiency over asset control.
Austria Solar Energy Market Segmentation
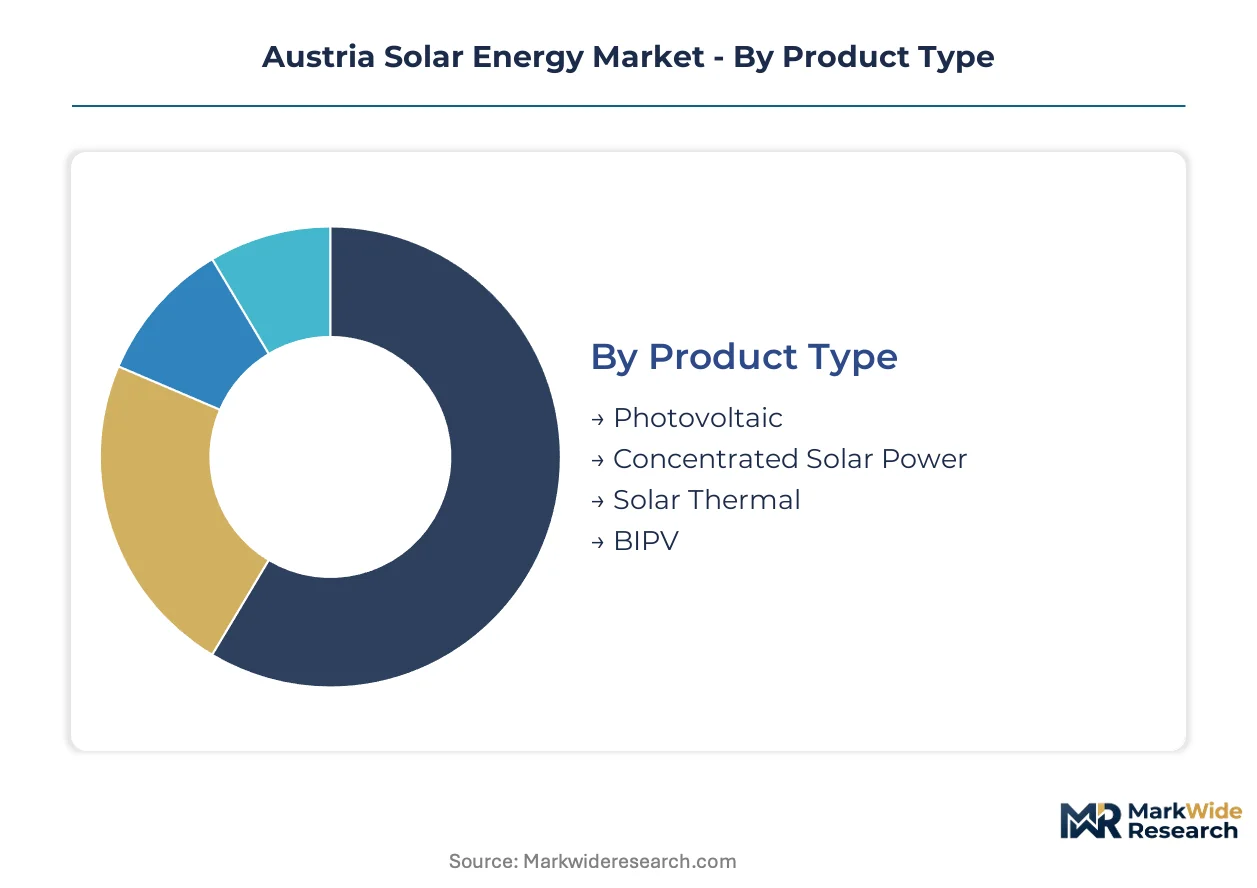
Segmentation in Austria's solar energy market reveals how technology choices, installation constraints, and end-use economics fragment procurement patterns across federal states. Understanding these divides helps suppliers calibrate product portfolios to Lower Austria's utility-scale corridors versus Vienna's rooftop-constrained density.
Product Type:
Standardization dominates photovoltaic arrays while customization intensifies for building-integrated and thermal applications.
- Photovoltaic:Crystalline silicon modules convert sunlight at 15-22% efficiency, feeding 230/400V distribution grids. Demand clusters in Lower Austria's Weinviertel corridor where grid-connected solar parks exploit flat agricultural terrain near substations.
- Building-Integrated Photovoltaics (BIPV):Custom-manufactured facade and roofing elements embed generation directly into building envelopes. Vienna's historic preservation districts and Graz's commercial construction drive specification as ÖNORM envelope standards tighten.
- Concentrated Solar Power:Mirror arrays focus thermal energy for industrial process heat in Alpine manufacturing zones.
- Solar Thermal:Evacuated tube collectors serve residential hot water demand in Tyrol's mountain municipalities.
Leading the category by volume: Photovoltaic. Growing fastest: BIPV.
Application:
Customer scale determines financing structures, with residential favoring self-consumption and utility-scale optimizing feed-in tariffs.
- Utility Scale:Ground-mounted arrays above 25 kW exploit EAG streamlined permitting and feed-in tariff restructuring. Developers concentrate procurement in Weinviertel's grid-accessible zones, pairing installations with lithium-ion storage to capture wholesale arbitrage.
- Commercial:Behind-the-meter generation serves peak shaving for Styria's industrial manufacturing and Tyrol's hospitality clusters. Energy-as-a-service contracting displaces direct ownership as midsize offtakers prioritize balance-sheet efficiency.
- Residential:Rooftop self-consumption systems dominate Vienna's dense urban fabric through municipal leasing programs.
- Industrial:Process heat integration and captive power supply anchor demand in Upper Austria's steel and chemical corridors.
Utility scale commands installed capacity. Commercial applications expand most quickly.
Technology:
Cost tiers separate mature crystalline silicon from emerging thin-film and multi-junction alternatives.
- Crystalline Silicon:Mature supply chains and module cost declines sustain manufacturing investment despite Chinese polysilicon concentration. European-manufactured panels gain preference as EU carbon border adjustments penalize embedded emissions.
- Thin-Film:Lightweight cadmium-telluride and CIGS alternatives penetrate facade-integrated applications where structural load constraints matter. Graz's commercial construction and Salzburg's heritage building retrofits drive specification.
- Multi-Junction:III-V semiconductor stacks deliver concentrated photovoltaic efficiency for research and specialized industrial deployment.
- Organic Photovoltaics:Polymer-based flexible films enable curved surface integration in experimental architectural projects.
Crystalline silicon leads by installed base. Thin-film gains share fastest.
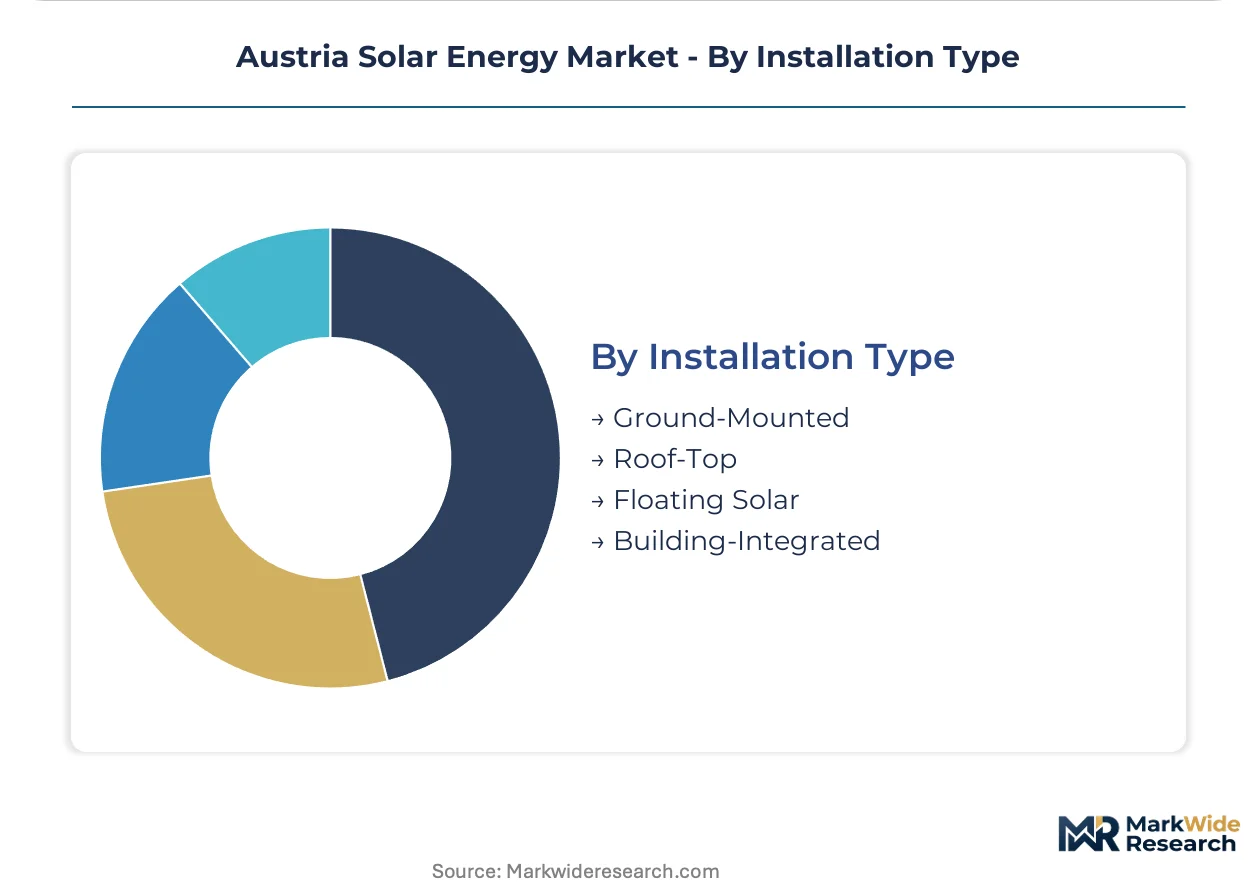
Installation Type:
Geography and land availability dictate mounting configuration, from flat-zone ground arrays to water-surface and building-integrated alternatives.
- Ground-Mounted:Fixed-tilt and tracker systems dominate Lower Austria's agricultural zones. Bifacial modules harvest reflected irradiance from light-colored soils, converging with single-axis trackers to maximize yield per hectare.
- Roof-Top:Distributed generation exploits Vienna's untapped commercial roof inventory and residential stock across federal states. Wien Energie GmbH's municipal leasing programs scale deployment without land acquisition friction.
- Floating Solar:Reservoir-mounted arrays address land constraints in Styria's lake districts and hydroelectric balancing ponds.
- Building-Integrated:Custom facade and roofing elements serve ÖNORM compliance in new construction and deep retrofits.
Ground-mounted installations lead by megawatt capacity. Building-integrated systems show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Weinviertel corridor in Lower Austria anchors the country's solar deployment, where flat agricultural terrain and substation proximity attract utility-scale developers clustering photovoltaic arrays near grid infrastructure.
Lower Austria
Weinviertel's agricultural zones host the densest concentration of ground-mounted solar parks, with developers exploiting EAG streamlined permitting for installations above 25 kW. The federal state's grid-connected corridors near substations reduce interconnection delays that plague western regions. Bifacial modules paired with single-axis trackers maximize yield per hectare across the corridor's light-colored soil surfaces.
Vienna
Municipal rooftop leasing programs unlock dense urban generation potential without land acquisition friction. Wien Energie GmbH dominates deployment through behind-the-meter commercial installations serving peak shaving demand. Historic preservation districts impose structural load and aesthetic constraints that fragment building-integrated photovoltaics economics in the inner city.
Styria
Wine-growing zones increasingly host elevated agrivoltaic arrays that preserve grape cultivation underneath, replicating a land-constrained deployment model across agricultural belts. Graz anchors inverter and energy management technology development through Fronius International GmbH's R&D operations. Federal agricultural subsidies for dual-use systems could extend this model into Burgenland's crop territories.
Tyrol
Mountain municipalities drive residential solar thermal demand for hot water applications in Alpine geographies where winter cloud cover reduces photovoltaic capacity factors. Hospitality clusters exhibit strong uptake of energy-as-a-service contracting, prioritizing balance-sheet efficiency over direct asset ownership. Seasonal generation mismatch limits bankability without storage co-location in this topography.
Upper Austria
Industrial manufacturing corridors anchor process heat integration and captive power supply for steel and chemical facilities. Grid congestion remains less severe than in western federal states, permitting faster interconnection approvals for commercial-scale installations. The region's manufacturing base creates concentrated demand for peak shaving behind-the-meter generation.
Austria Solar Energy Market Competitive Environment
Capital-heavy producers compete with asset-light designers across Austria's solar value chain. Module assemblers and project developers carry balance-sheet intensity from land acquisition and grid interconnection, while software-defined energy management specialists monetize installations through dispatch optimization without manufacturing exposure. Three archetypes dominate: municipal utilities leveraging ratepayer bases for rooftop leasing scale, technology manufacturers anchoring R&D through Graz-based operations, and agricultural dual-use specialists exploiting federal subsidy structures. Competitive moves concentrate on strategic partnerships for grid-scale battery pairing and portfolio diversification into energy-as-a-service contracting.
Among municipal utility operators, Wien Energie GmbH occupies a position representing ratepayer-backed deployment scale, while Energie Steiermark AG and Burgenland Energie exemplify regional energy company structures with integrated generation portfolios. Technology manufacturers include Fronius International GmbH, which anchors inverter and energy management leadership through its Graz-based GmbH structure, and KPV Solar GmbH, which represents the agricultural dual-use specialist archetype across Styria's wine-growing territories.
| Leading Market Players |
|---|
| KPV Solar GmbH |
| Energie Steiermark AG |
| Wien Energie GmbH |
| Secundo Photovoltaik GmbH |
| Selina Photovoltaic GmbH |
| Verbund AG |
| Burgenland Energie |
| Ökovolt Solartechnik GmbH |
| Fronius International GmbH |
| Others |
Value Chain & Pricing Dynamics
Electrical engineering talent scarcity in Vienna and Graz widens labor-cost spreads between premium EPC contractors and commoditized installation crews, compressing margins at the economy tier while specialized grid interconnection specialists capture rate premiums.
Pricing Analysis
Yield-per-watt guarantees anchor value-based pricing for utility-scale arrays in Lower Austria's Weinviertel corridor, with developers contracting output commitments rather than equipment markups. Price differentiation separates premium European-manufactured crystalline silicon modules with embedded emissions documentation from standard-tier Chinese-assembled alternatives lacking carbon intensity disclosure. Cost compression in the standard tier intensifies as polysilicon input volatility feeds through module assembler margins. Commercial rooftop segments in Vienna exhibit lowest price sensitivity due to balance-sheet-offloading energy-as-a-service structures, while residential self-consumption buyers in Tyrol's mountain municipalities negotiate hardest on upfront capital outlays.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale developer demand for ground-mounted arrays above 25 kW, bypassing distributor markups through frame agreements with module manufacturers. Geographic supply concentration centers on Chinese polysilicon refiners for feedstock, Southeast Asian cell and module assembly for cost-optimized tiers, and European manufacturing for premium carbon-compliant panels. Raw material dependencies span metallurgical-grade silicon, silver paste for cell metallization, and aluminum framing extrusions. Single-source vulnerability from Chinese polysilicon concentration exposes Austrian project sponsors to trade policy friction and input cost spikes. Distribution runs through specialized renewable energy wholesalers for commercial and residential segments, with EPC contractors maintaining direct procurement relationships for utility-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around capital access and grid interconnection expertise, with EAG permitting acceleration forcing sub-scale developers into acquisition or exit as project pipelines outstrip workforce training capacity.
For Market Incumbents: Deploy municipal ratepayer-backed balance sheets to lock in Vienna rooftop leasing inventory before competitor programs scale. Acquire distressed EPC contractors in western federal states to capture scarce electrical engineering talent and pre-qualified grid interconnection queues. Defensive consolidation against emerging energy-as-a-service platforms requires backward integration into storage dispatch software rather than hardware-only positioning.
For New Entrants and Emerging Players: Begin with agricultural dual-use standardization in Burgenland's crop belts, replicating Styria's wine-sector agrivoltaic model where federal subsidy structures remain underexploited. Target floating solar deployment in Styria's hydroelectric balancing ponds, a geography incumbent utilities have deprioritized for ground-mounted alternatives. Go-to-market through cooperative arrangements with regional agricultural associations unlocks land access without direct acquisition friction.
For Investors and Strategic Acquirers: Re-rating potential sits with software-defined energy management specialists given wholesale market arbitrage capabilities and EAG flexibility compliance requirements. Long-term viability over a decade horizon favors asset-light dispatch optimization platforms over balance-sheet-heavy project development. Acquisition target archetype: inverter and energy management technology developers with Graz-based R&D operations and established utility relationships. Signal to watch: grid-scale battery pairing mandates in EAG amendments as photovoltaic penetration saturates distribution hosting capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Scale Battery Pairing | Co-located lithium-ion storage captures wholesale arbitrage and satisfies EAG flexibility requirements for large solar submissions. |
| Municipal Rooftop Leasing Scale-Up | Wien Energie GmbH-style programs exploit Vienna's dense commercial roof inventory without land acquisition friction. |
| Agrivoltaic Standardization | Federal agricultural subsidies for dual-use systems replicate Styria's wine-sector model across Burgenland crop territories. |
| Backward Integration into Polysilicon | European module assemblers mitigate Chinese supply concentration through captive sourcing or long-term offtake structures. |
| Software-Defined Dispatch Optimization | Energy management platforms monetize installations through grid services and behind-the-meter arbitrage beyond hardware margins. |
Study Parameters
Independent corroboration across utility planning officers, EPC contractors, and inverter technology developers underwrites the qualitative findings in this study. Primary interviews with IPP project developers, grid operators, and agricultural cooperative managers combined with secondary validation from EAG regulatory filings, IEA renewable energy databases, and ÖNORM technical specifications. Bottom-up project pipeline aggregation and top-down federal state capacity targets triangulate market sizing across the analysis window.
Comparable-period anchoring to historical deployment trajectories in Germany and Switzerland calibrated the forecast framework for Austrian market maturation. Segmentation dimensions span product type, application scale, installation configuration, and regional grid hosting capacity. CAGRs derive from installed capacity build rates, module cost decline curves, and EAG policy implementation timelines. Forecast inputs incorporate polysilicon price volatility scenarios and distribution network upgrade schedules from regional grid operators.
Underlying measurement precision varies by segment; utility-scale deployments with disclosed interconnection agreements carry tighter precision than fragmented residential rooftop estimates. Forecasts embed assumptions around EAG permitting timelines, EU carbon border adjustment enforcement, and grid congestion resolution in western federal states. Practitioners should monitor EAG amendment proceedings, transformer saturation alerts from regional grid operators, and polysilicon trade policy developments for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Middle-East Solar Power Market
Solar Power Systems
South Korea Solar Energy Market
Solar Power Systems
Solar Power Tracker Market
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
Global Solar PV Balance of System Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
IBC Solar Cells Market
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
South America Solar Photovoltaic Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
India Residential Solar Inverter Market
Solar Power Systems
APAC Solar Micro Inverters Market
Solar Power Systems
Solar Skin Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
Concentrated Photovoltaic System Market