
 Solar PV Backsheet Market | 2026-2036
Solar PV Backsheet Market Size, Share, and Industry Trends Forecast 2026-2036
Solar PV Backsheet Market Analysis
Direct procurement channels between module manufacturers and backsheet producers is reshaping traditional distributor-heavy supply chains. Arkema SA leverages its fluoropolymer chemistry heritage to sustain premium positioning in photovoltaic-grade films. DuPont de Nemours Inc. anchors North American supply security through localized Tedlar production and technical service networks. RenewSys India Pvt. Ltd. competes on integrated module-component bundling across South Asian project pipelines.
A solar PV backsheet is the outermost protective layer of a photovoltaic module, typically a multilayer polymer film measuring 250-350 microns that shields cells from moisture ingress, ultraviolet degradation, and electrical insulation failure. The construction combines a weather-resistant fluoropolymer or coated polyester outer skin, a PET core for dielectric strength, and an EVA-compatible inner surface laminated under controlled temperature and pressure. Fluoropolymer materials command the highest margin pools due to proven 25-year field performance in desert and coastal environments, while polyester variants gain volume traction in cost-sensitive utility-scale deployments where balance-of-system economics dominate procurement criteria. Application segmentation shows utility-scale projects consuming the majority of backsheet area, though residential distributed generation in Germany and Australia creates differentiated demand for lighter, flexible constructions.
REACH and RoHS frameworks in Europe restrict halogenated flame retardants and certain phthalate plasticizers in polymer formulations, forcing reformulation of legacy backsheet constructions. The EU Green Deal and associated CSRD disclosure rules compel module buyers to document supply-chain carbon intensity, including backsheet film production. India's BIS certification mandates specific thermal cycling and damp-heat test protocols for imported photovoltaic materials. Stakeholders must monitor evolving country-of-origin requirements and carbon-border adjustment mechanisms as these determine competitive access for Asian versus European-manufactured films.
Market Dynamics
Direct mill relationships between integrated Chinese cell-to-module producers and fluoropolymer film manufacturers are compressing distributor margins and reshaping price discovery mechanisms across the value chain.
Growth Catalysts
- EU Green Deal durability mandates:Accelerated renewable targets under the EU Green Deal are tightening field-performance requirements for desert and coastal installations, pushing procurement toward multilayer fluoropolymer constructions with proven 25-year track records.
- Utility-scale deployment in India:India's PLI scheme for solar module manufacturing is stimulating captive backsheet demand from domestic producers seeking BIS-certified supply chains for gigawatt-scale project pipelines.
- Fluoropolymer chemistry advances:Arkema SA and specialized film coaters are extending weathering resistance through modified PVDF formulations that reduce ultraviolet-induced embrittlement in high-irradiance environments.
Market Restraints
- Petroleum-based feedstock volatility:Polyester and fluoropolymer resins track crude oil and natural gas derivatives, exposing backsheet producers to margin compression when energy markets spike.
- Chinese supply concentration:Integrated cell-to-module manufacturers in Jiangsu and Zhejiang provinces control over 70 percent of captive backsheet procurement, limiting market access for independent film suppliers.
- REACH formulation costs:ECHA restrictions on halogenated flame retardants and phthalate plasticizers force costly reformulation of legacy PET core constructions, eroding cost advantages against fluoropolymer alternatives.
Strategic Opportunities
- Middle East utility-scale expansion:Saudi Arabia's renewable energy targets under Vision 2030 are creating demand for high-durability backsheets in extreme desert thermal cycling conditions where fluoropolymer performance premiums justify procurement.
- CSRD carbon disclosure tailwinds:The EU's Corporate Sustainability Reporting Directive creates procurement preference for backsheet films with documented supply-chain carbon intensity, favoring European manufacturers with localized PET extrusion.
- Floating solar convergence:The intersection of marine-grade corrosion resistance and photovoltaic encapsulation is opening specialized demand for co-extruded multilayer films in Southeast Asian reservoir installations.
Industry Challenges
- IEC 61215 certification timelines:Extended damp-heat and thermal cycling test protocols create 18-24 month product qualification cycles that delay revenue recognition for new multilayer constructions.
- Polymer compounding talent scarcity:Formulation chemists with expertise in photovoltaic-grade fluoropolymer adhesion and EVA compatibility command premium compensation in a shallow labor pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar PV Backsheet Market |
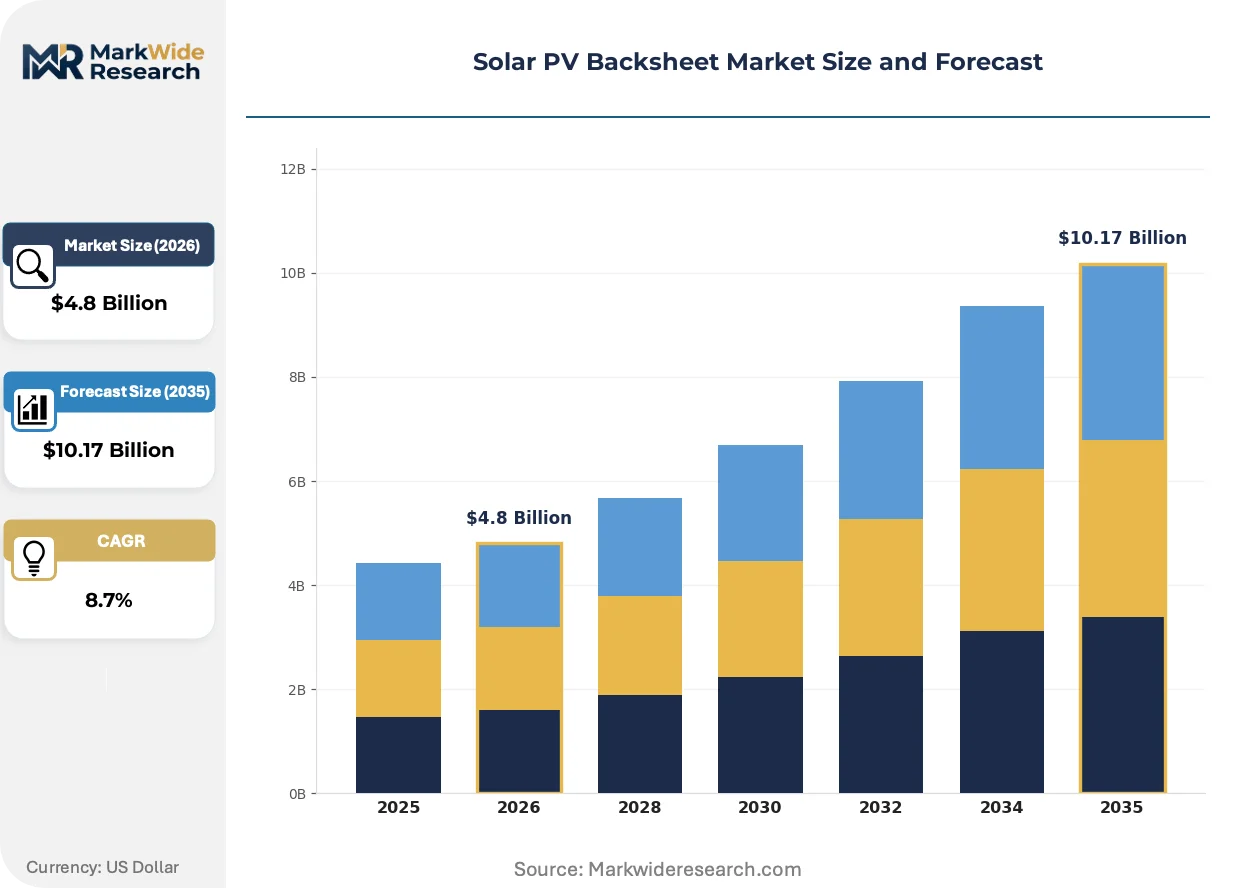
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyester, Polyvinyl Fluoride, Polycarbonate, Fluoropolymer Application: Residential, Commercial, Utility Scale, Off-grid Systems Component: Films, Insulation, Adhesives, Coatings End User: Manufacturers, Installers, Distributors, Project Developers |
| Companies Covered | Arkema SA, Krempel GmbH, DuPont de Nemours Inc., Coveme S.P.A., RenewSys India Pvt. Ltd., 3M Company, Cybrid Technologies Inc., Jolywood, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar PV Backsheet Market Emerging Trajectories
Backsheet construction is bifurcating between premium fluoropolymer multilayers for harsh environments and cost-optimized coated polyesters where balance-of-system economics dominate procurement decisions.
Co-extruded fluoropolymer-PET-fluoropolymer tri-laminates serve as the primary weather barrier in utility-scale modules. Indian and Middle Eastern project developers are specifying these constructions for 25-year warranties in 85°C ambient conditions. The technology is migrating from European premium residential markets toward cost-sensitive Asian utility procurement where module-level reliability guarantees now override upfront material cost minimization.
REACH and RoHS frameworks enforced by ECHA continue tightening permissible substance lists for polymer additives. Legacy backsheet constructions containing restricted halogenated flame retardants face import barriers into EU member states. Module assemblers serving German and Dutch residential markets are accelerating qualification of reformulated PET cores to maintain CE marking compliance.
Integrated producers in China are bypassing regional distributors to secure direct mill supply of fluoropolymer films. This channel compression eliminates traditional stocking and technical service margins that independent distributors historically captured. The pattern is most visible in Jiangsu province where cell-to-module manufacturers with captive module assembly lines now source backsheet films through direct procurement teams co-located with resin suppliers.
Solar PV Backsheet Market Segmentation
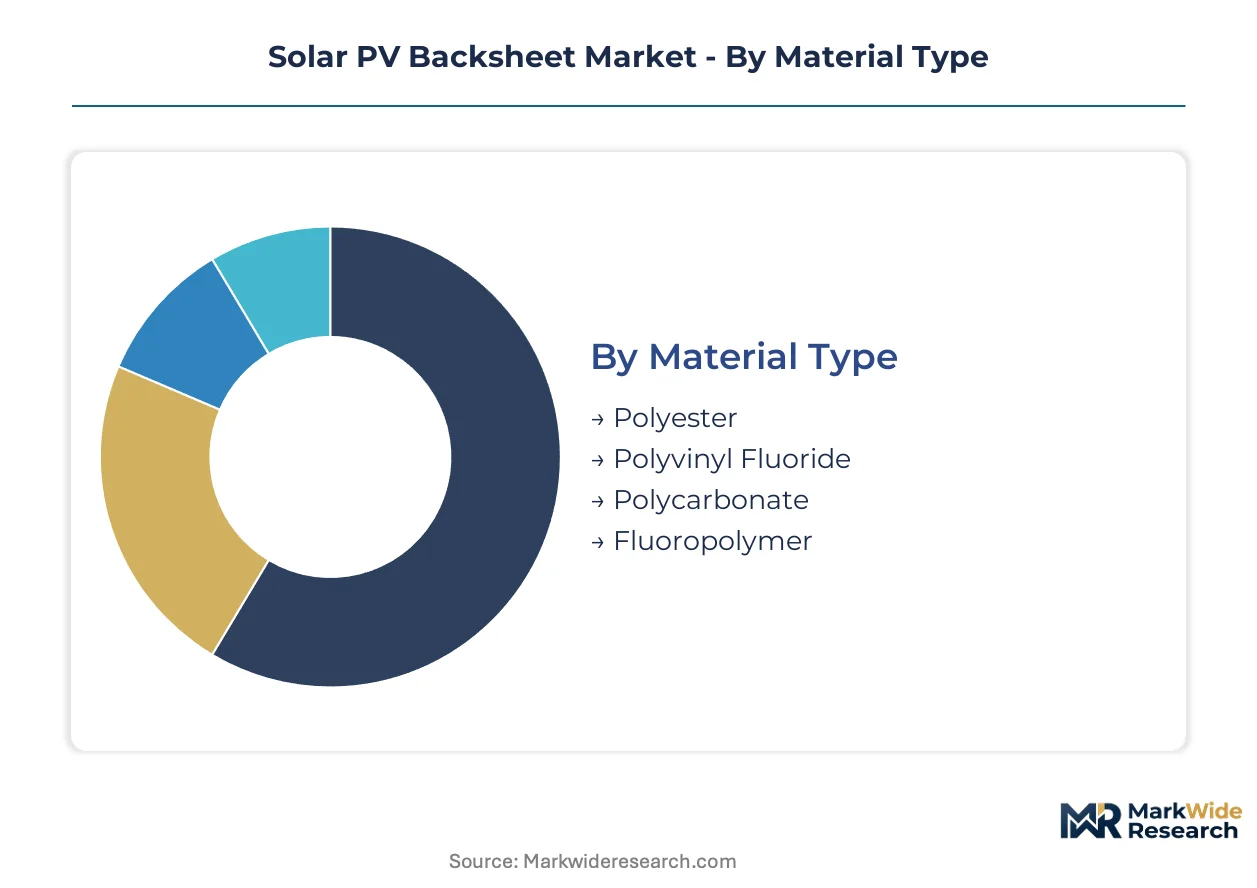
Backsheet procurement patterns diverge sharply across material grades and installation scales. Segment boundaries reflect durability requirements, warranty obligations, and the balance-of-system economics that govern module assembly decisions.
Material Type:
Mature fluoropolymer constructions coexist with emerging coated polyester alternatives as cost pressures reshape procurement.
- Fluoropolymer:Multilayer PVDF or ETFE outer skins laminated to PET cores deliver proven 25-year weathering resistance in desert and coastal installations. Saudi Arabian utility developers specify these constructions for 85°C ambient thermal cycling under Vision 2030 gigawatt pipelines.
- Polyester:Coated PET films with fluorinated surface treatments compete on upfront material cost for utility-scale deployments where balance-of-system economics override premium durability guarantees. Indian PLI-scheme module producers are qualifying BIS-certified polyester constructions for domestic project pipelines.
- Polyvinyl Fluoride:Tedlar-based laminates anchor North American supply security through localized extrusion and technical service networks.
- Polycarbonate:Emerging transparent backsheet variants enable bifacial module architectures with rear-side light transmission requirements.
Fluoropolymer retains volume leadership; polycarbonate holds the steepest expansion curve.
Application:
Installation scale determines construction specifications, with thermal cycling severity and warranty duration driving material selection.
- Utility Scale:Ground-mounted arrays in Rajasthan and the Middle East consume the majority of backsheet area, specifying multilayer fluoropolymer for 25-year performance guarantees under extreme irradiance and temperature differentials.
- Residential:Distributed generation in Germany and Australia creates demand for lighter, flexible constructions with simplified installation mechanics and aesthetic integration requirements.
- Commercial:Rooftop and carport installations balance durability with weight constraints across C&I project portfolios.
- Off-grid Systems:Remote telecommunications and rural electrification projects prioritize cost minimization over extended warranty coverage.
Utility scale commands procurement volume; residential applications are climbing the fastest as distributed generation accelerates.
Component:
Film and coating technologies concentrate margin capture, while adhesives and insulation layers face commoditization pressure.
- Films:Co-extruded fluoropolymer-PET-fluoropolymer tri-laminates serve as the primary weather barrier, with Arkema SA and specialized coaters extending ultraviolet resistance through modified PVDF formulations.
- Coatings:Surface-functionalized fluoropolymer layers determine field performance in high-irradiance environments, commanding premium positioning through chemistry differentiation.
- Adhesives:EVA-compatible inner surfaces require controlled lamination temperature and pressure protocols to ensure cell encapsulation integrity.
- Insulation:PET core layers provide dielectric strength and mechanical stability, facing margin compression from petroleum-based feedstock volatility.
Films retain volume leadership; coatings hold the steepest expansion curve as surface engineering advances.
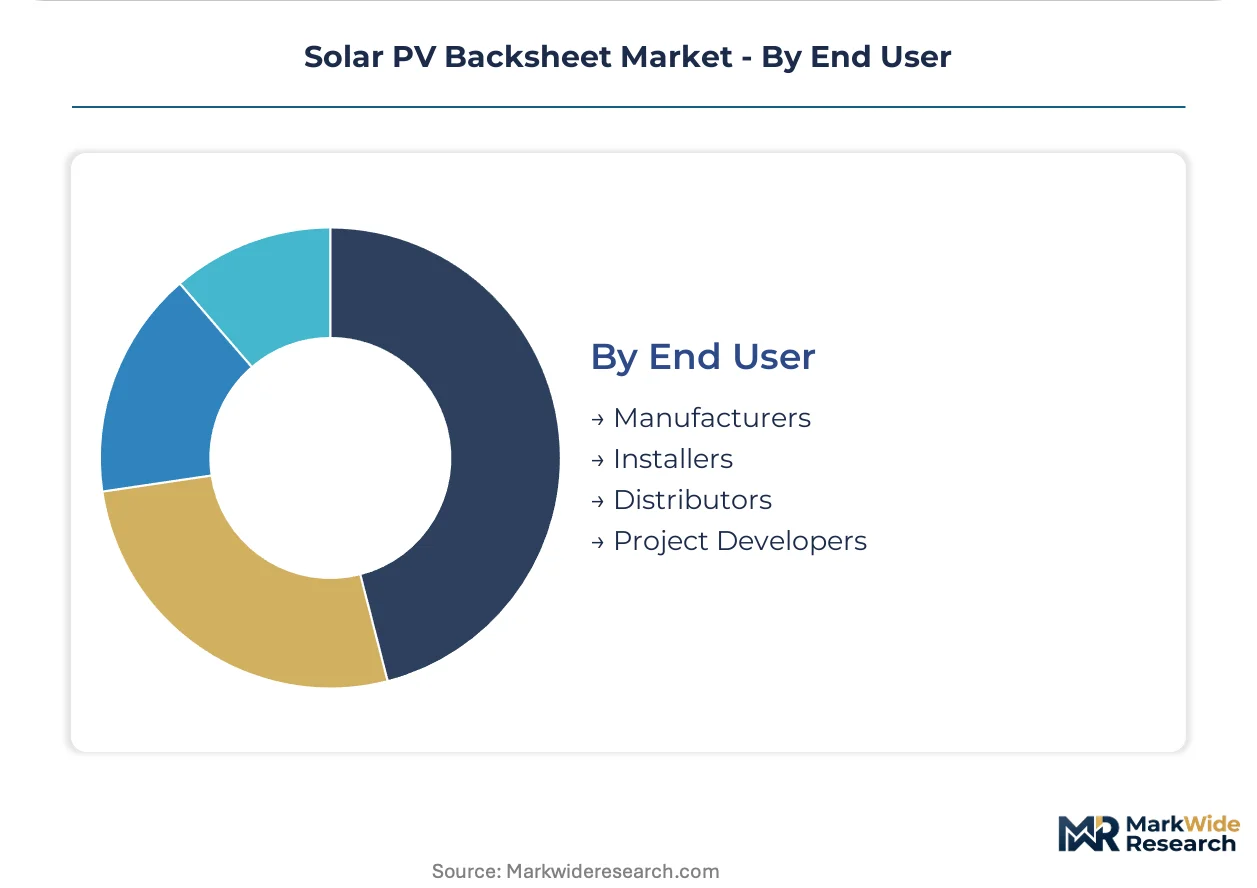
End User:
Channel structure is bifurcating between integrated manufacturers with captive supply and independent distributors facing compression.
- Manufacturers:Integrated cell-to-module producers in Jiangsu and Zhejiang provinces control over 70 percent of captive backsheet procurement through direct mill relationships with fluoropolymer film suppliers.
- Project Developers:Utility-scale developers in India and Saudi Arabia specify certified backsheet constructions in EPC contracts, driving qualification requirements upstream.
- Distributors:Traditional stocking and technical service margins are eroding as direct procurement channels eliminate intermediary layers.
- Installers:Residential and commercial contractors source through module OEMs rather than independent backsheet procurement.
Manufacturers retain volume leadership; project developers are gaining procurement influence fastest as EPC specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's dual carbon goals and GB standards anchor Chinese procurement patterns, while BIS certification and EU Green Deal durability mandates reshape import and qualification requirements across major installation geographies.
China
Jiangsu and Zhejiang provinces host integrated cell-to-module manufacturers controlling captive backsheet procurement through direct mill relationships with fluoropolymer film suppliers. MIIT's dual carbon targets accelerate domestic module deployment, tightening supply chain localization requirements. Suzhou-based film coaters extend ultraviolet resistance through modified PVDF formulations for desert installations.
India
Rajasthan's gigawatt-scale solar parks drive multilayer fluoropolymer demand for 25-year performance guarantees under extreme thermal cycling. The PLI scheme for solar module manufacturing stimulates captive backsheet demand from domestic producers seeking BIS-certified supply chains. Gujarat's module assembly clusters qualify polyester constructions for cost-sensitive utility pipelines.
Germany
Residential distributed generation in Bavaria and Baden-Württemberg creates differentiated demand for lighter, flexible backsheet constructions with aesthetic integration requirements. REACH and RoHS frameworks enforced by ECHA restrict halogenated flame retardants, forcing reformulation of legacy PET core constructions. The EU Green Deal's accelerated renewable targets tighten durability standards for coastal installations.
Saudi Arabia
Vision 2030 renewable energy targets generate procurement for high-durability backsheets in extreme desert thermal cycling conditions where fluoropolymer performance premiums justify specification. The national renewable energy program mandates extended warranty coverage for utility-scale arrays. Riyadh-based project developers specify certified constructions in EPC contracts.
United States
Localized Tedlar production anchors North American supply security through technical service networks serving utility-scale developers. The IRA's domestic content bonuses incentivize module assemblers to source from regional film extrusion operations. Texas and California utility pipelines concentrate demand for proven 25-year weathering resistance in high-irradiance environments.
Solar PV Backsheet Market Vendor Landscape
Integrated chemical conglomerates and specialized film coaters split the market between captive supply security and technical differentiation. Three strategic archetypes dominate: fluoropolymer chemistry heritage players, polyester cost-optimization specialists, and integrated module-component bundlers. Competitive moves concentrate on direct mill relationship formation and multilayer construction qualification acceleration.
Within the chemistry-heritage tier, Arkema SA and DuPont de Nemours Inc. exemplify premium positioning through fluoropolymer formulation expertise and localized production networks. RenewSys India Pvt. Ltd. occupies a position as an integrated module-component bundler across South Asian project pipelines. Krempel GmbH represents the specialized film fabrication archetype with European manufacturing concentration.
| Leading Market Players |
|---|
| Arkema SA |
| Krempel GmbH |
| DuPont de Nemours Inc. |
| Coveme S.P.A. |
| RenewSys India Pvt. Ltd. |
| 3M Company |
| Cybrid Technologies Inc. |
| Jolywood |
| Dow Inc. |
| Others |
Supply Flow & Price Mechanics
Petroleum-based feedstock volatility acts as the primary risk vector, compressing margin pools across both fluoropolymer and polyester tiers while simultaneously accelerating backward integration into resin production and direct mill procurement channels.
Pricing Analysis
The customization-premium spread separates configured-to-order multilayer fluoropolymer constructions from standard coated polyester films. Project-based long-term offtake contracts dominate utility-scale procurement, with price differentiation driven by certification grade (IEC 61215 thermal cycling tiers) and volume scale. Cost compression in polyester tiers is intensifying because Indian PLI-scheme module producers are qualifying BIS-certified domestic supply. Utility-scale EPC contractors demonstrate highest price sensitivity; Saudi Arabian developers under Vision 2030 show lowest sensitivity due to 25-year warranty requirements.
Supply Chain Analysis
Contract manufacturing concentration rests with integrated cell-to-module producers in Jiangsu and Zhejiang provinces who have absorbed traditional film coating capacity. Geographic supply concentration centers on China, India, and Saudi Arabia for module assembly; fluoropolymer resin production draws from Arkema's French facilities and DuPont's US extrusion operations. Raw material dependencies include PVDF resin, PET film substrates, and EVA-compatible adhesives. Single-source vulnerability pervades fluoropolymer chemistry expertise. Distribution runs through direct procurement teams co-located with resin suppliers, bypassing independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's accelerated durability mandates constitute a regulatory inflection that will displace legacy PET constructions and consolidate procurement around multilayer fluoropolymer suppliers with proven field performance.
For Market Incumbents: Build chemistry IP moats through modified PVDF formulations that extend ultraviolet resistance in 85°C ambient conditions. Deepen backward integration into PET extrusion to secure dielectric core supply against petroleum feedstock spikes. Accelerate IEC 61215 qualification cycles for co-extruded tri-laminates before REACH reformulation deadlines erode legacy product viability.
For New Entrants and Emerging Players: Establish a beachhead in polycarbonate transparent backsheet variants for bifacial module architectures where rear-side light transmission requirements create unmet demand. Target floating solar installations in Southeast Asian reservoirs where marine-grade corrosion resistance specifications remain underdeveloped. Pursue co-development partnerships with EPC contractors seeking localized supply under India's PLI scheme.
For Investors and Strategic Acquirers: The EU CSRD disclosure rules reshape the acquisition landscape by elevating supply-chain carbon documentation capabilities as a valuation differentiator. Five-to-ten-year viability favors European manufacturers with localized PET extrusion and verified low-carbon intensity production. Target film coaters with BIS certification for Indian market access and existing direct mill relationships with Jiangsu module producers. Monitor quarterly BIS import protocol updates as inflection indicators for captive supply versus independent distributor margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVDF Resin Production | Arkema and chemistry-heritage players secure margin pools against petroleum volatility and Chinese supply concentration. |
| Long-term Supply Agreement with Utility EPCs | Saudi Vision 2030 developers lock in 25-year fluoropolymer volumes under extreme desert thermal cycling specifications. |
| Green Certification Program for Carbon Disclosure | European manufacturers capture CSRD-compliant procurement preference through verified low-intensity PET extrusion. |
| Joint Venture with Indian Module Producers | Foreign film coaters satisfy BIS certification requirements and PLI-scheme domestic content thresholds. |
| Capacity Expansion in Co-extruded Tri-laminates | Specialized coaters meet migrating demand from European residential to Asian utility-scale procurement. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC 10-K filings from chemical conglomerates, and IEC certification databases. Primary interviews engaged module procurement directors at integrated cell-to-module manufacturers, fluoropolymer formulation chemists, EPC contract specification officers, and BIS certification auditors. Secondary validation drew from MIIT dual carbon policy documents, EU Green Deal implementation guidance, and Saudi Vision 2030 renewable energy program disclosures. Bottom-up module deployment forecasts triangulated against top-down polymer resin demand projections.
Forecast inputs incorporate material grade segmentation by fluoropolymer, polyester, polycarbonate, and polyvinyl fluoride tiers; application scale across utility, residential, commercial, and off-grid installations; and end-user channel structure distinguishing captive manufacturer procurement from independent distributor flows. CAGRs were derived through regression analysis of historical backsheet area consumption against module deployment pipelines. Industry-specific inputs include IEC 61215 test protocol evolution timelines and REACH substance restriction phase-in schedules.
Macroeconomic conditions sit as an overlay; deviation in crude oil and natural gas derivatives pricing would shift the trajectory of polyester versus fluoropolymer competitiveness. Forecasts reflect documented assumptions about BIS certification adoption rates and EU carbon border adjustment implementation scope. Quarterly review of ECHA substance restriction proposals, MIIT localization requirement updates, and Saudi EPC contract award flows is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Solar Bug Zapper Market
Solar Power Systems
Agriculture Solar Water Pumps Market
Solar Power Systems
Chile Renewable Energy Market
Solar Power Systems
Printable Solar Cells Market
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
Global Micro Solar Inverter Market
Solar Power Systems
Solar Power Meters Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
India Solar Tracker Market