
 US Solar Power Meters Market | 2026-2036
US Solar Power Meters Market Size, Share, and Industry Trends Forecast 2026-2036
US Solar Power Meters Market Insights
The Inflation Reduction Act is restructuring capital flows into distributed solar infrastructure across the United States. Fluke Corporation leverages its calibration heritage to dominate high-accuracy segments for utility commissioning teams. Campbell Scientific, Inc. anchors its position through ruggedized designs purpose-built for environmental monitoring stations in harsh desert climates. Solar Light Company, Inc. differentiates via spectral measurement capabilities that serve photovoltaic research laboratories and certification bodies.
Solar power meters are precision instruments that quantify irradiance, energy yield, and system performance through photodiode or thermopile sensors calibrated to standard solar spectra. These devices enable installers, operators, and regulators to verify panel output, detect shading losses, and validate power purchase agreements through traceable measurement chains. Smart meters and revenue-grade net meters command premium positioning as utilities in California, Arizona, and Hawaii enforce bidirectional billing protocols and time-of-use rate structures. The residential end-user segment shows structural momentum where rooftop solar penetration triggers mandatory production metering for incentive compliance and grid export compensation.
The Federal Energy Regulatory Commission and state public utility commissions shape meter accuracy requirements through interconnection standards and net metering rulemakings. The National Institute of Standards and Technology maintains traceability protocols that manufacturers must satisfy for revenue-grade certification. Stakeholders must monitor evolving state-level net metering reforms and distributed energy resource aggregation rules that will redefine metering functionality requirements and procurement cycles.
Market Dynamics
The Inflation Reduction Act's production tax credits are accelerating utility-scale solar deployments across the Southwest, compressing procurement cycles for revenue-grade metering infrastructure as interconnection queues swell.
Growth Catalysts
- Interconnection queue reforms:FERC Order 2023 streamlines grid access protocols, forcing utilities to install precision production meters ahead of project energization dates.
- Net metering restructuring:California's NEM 3.0 transition to export compensation rates triggers mandatory smart meter upgrades for 1.5 million existing rooftop systems.
- Photovoltaic research expansion:National Renewable Energy Laboratory certification programs expand spectral measurement requirements for next-generation perovskite-silicon tandem cells.
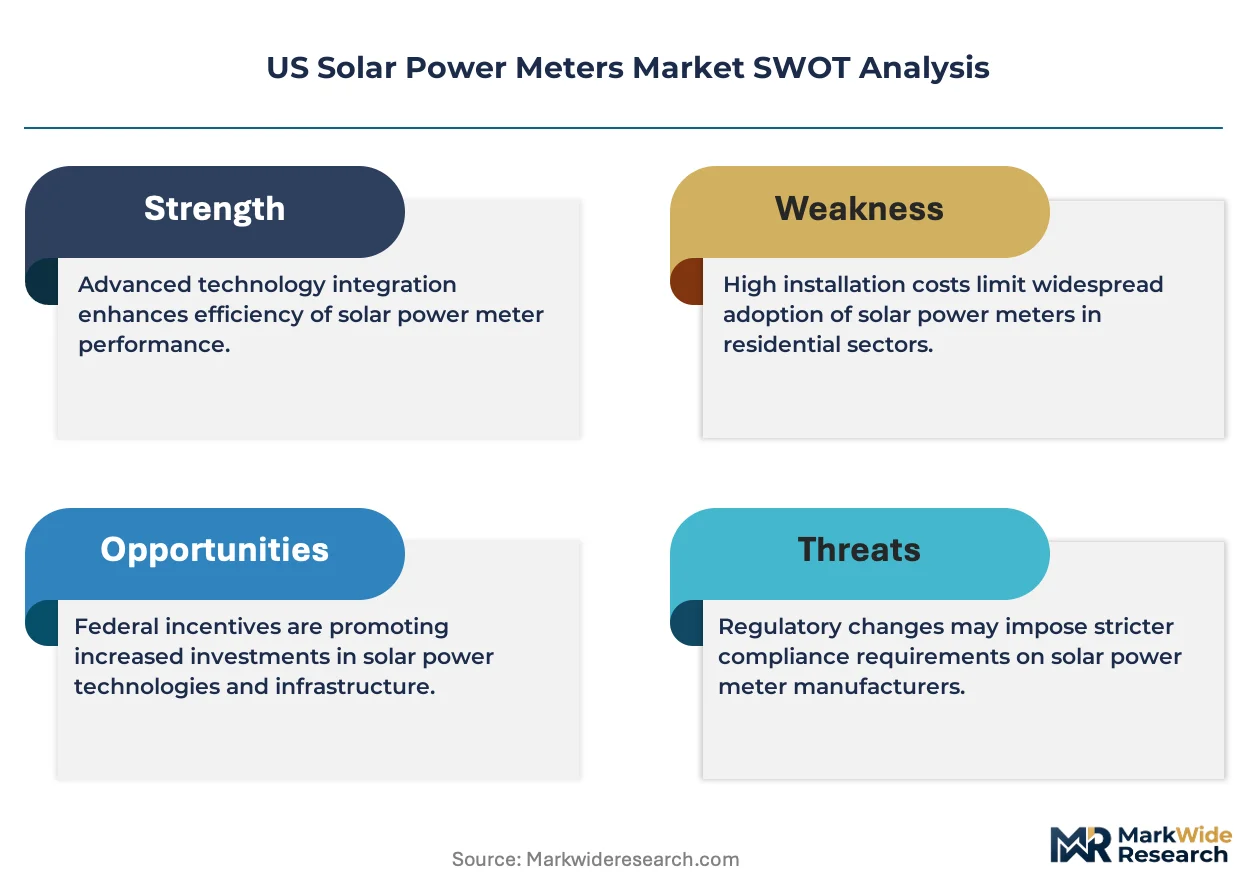
Market Restraints
- Sensor component concentration:Thermopile detector manufacturing concentrates in German and Japanese suppliers, exposing US meter assemblers to 14-week lead times.
- Revenue-grade certification barriers:NIST traceability protocols require 18-month laboratory validation cycles that delay product commercialization.
- Silicon photodiode substitution:Lower-cost irradiance sensors from Chinese manufacturers undercut domestic thermopile-based instruments in non-revenue applications.
Strategic Opportunities
- Texas ERCOT grid expansion:The state's 35 GW solar pipeline creates demand for bidirectional meters capable of real-time frequency response signaling.
- Community solar aggregation:Virtual net metering programs in New York and Minnesota require submetering networks for multi-subscriber billing allocation.
- AI-enabled predictive maintenance:Machine learning algorithms applied to irradiance data streams open software-recurring revenue models for meter OEMs.
Industry Challenges
- Metrology talent scarcity:Calibration technicians with NIST-traceable certification command 40% salary premiums, constraining manufacturer expansion.
- Legacy AMI integration:Utilities running 15-year-old smart meter infrastructure face protocol incompatibility with IEEE 2030.5 solar production standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Solar Power Meters Market |
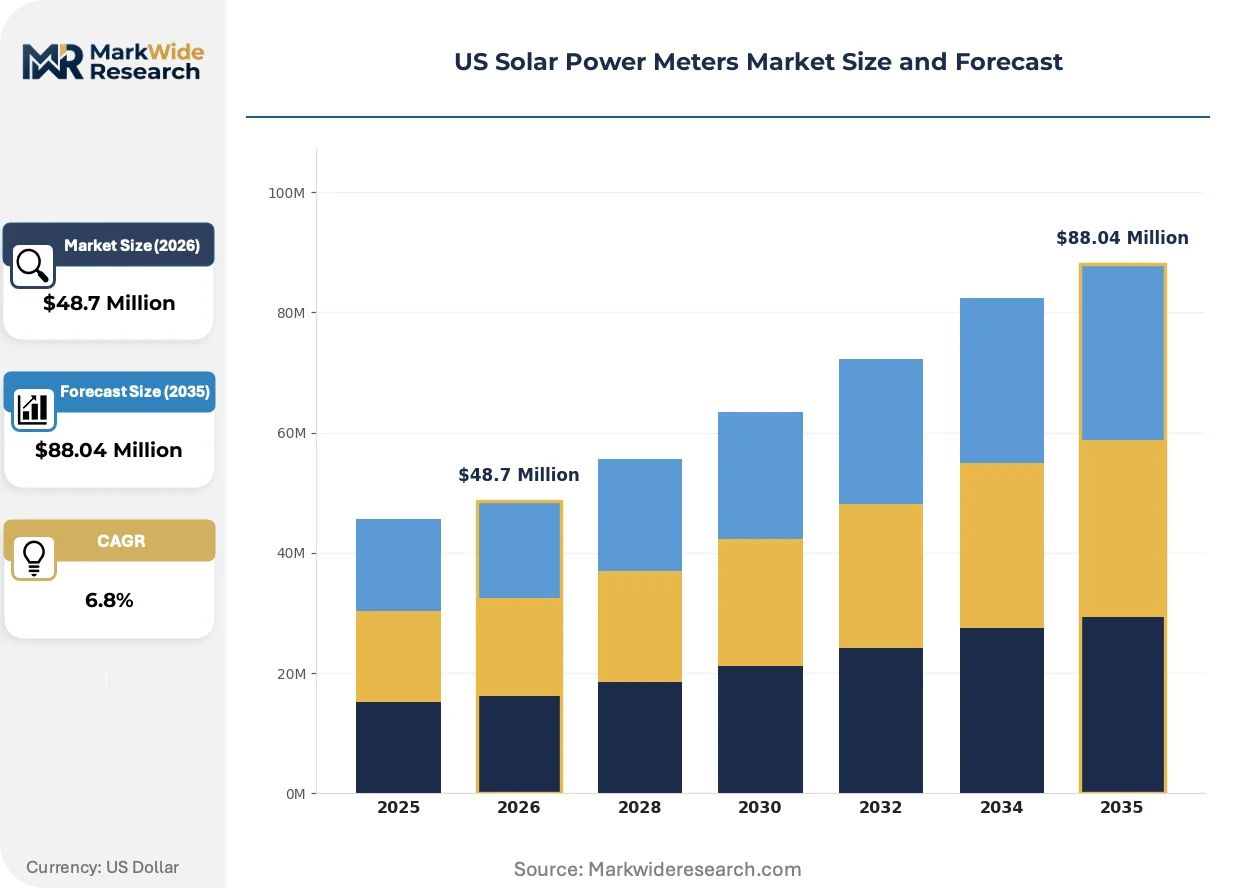
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Net Meters, Smart Meters, Inverter Meters, Revenue Meters End User: Residential, Commercial, Industrial, Utilities Technology: Grid-Tied, Off-Grid, Hybrid, Microgrid Installation Type: Wall-Mount, Pole-Mount, Portable, Embedded |
| Companies Covered | Campbell Scientific, Inc., Solar Light Company, Inc., Fluke Corporation, EKO Instruments Co., Ltd., General Tools & Instruments, FLIR Systems, Apogee Instruments, Inc., OTT HydroMet B.V., Amprobe, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Solar Power Meters Market Trends and Innovations
Digitalization of solar asset management is collapsing the distinction between field measurement instruments and permanent monitoring hardware, reshaping how operators validate performance guarantees.
Silicon carbide-based power electronics in utility inverters is consolidating the functional boundary between DC-side string monitoring and AC-side revenue metering. Arizona Public Service and Duke Energy are deploying integrated sensor arrays that eliminate separate irradiance reference stations. This consolidation reduces capital expenditure per megawatt while compressing the addressable market for standalone pyranometer suppliers.
California Public Utilities Commission Rulemaking 22-07-005 mandates granular 15-minute interval data reporting for all new distributed solar interconnections. The regulation forces meter manufacturers to embed cellular LTE-M modems and cloud-agnostic APIs as standard features. Installer procurement teams now disqualify products lacking CPUC-certified firmware, reshaping competitive positioning toward software-integrated hardware bundles.
Equipment-as-a-service models are displacing capital purchase contracts for precision irradiance measurement systems. Third-party asset managers like NovaSource and SOLV Energy now lease Class A pyranometers with guaranteed calibration replacement schedules. This shift concentrates procurement authority with national O&M providers rather than fragmented EPC contractors, most visible in Florida's utility-scale pipeline where SolUnesco and Origis Energy have standardized on subscription-based meter fleets.
US Solar Power Meters Market Segmentation
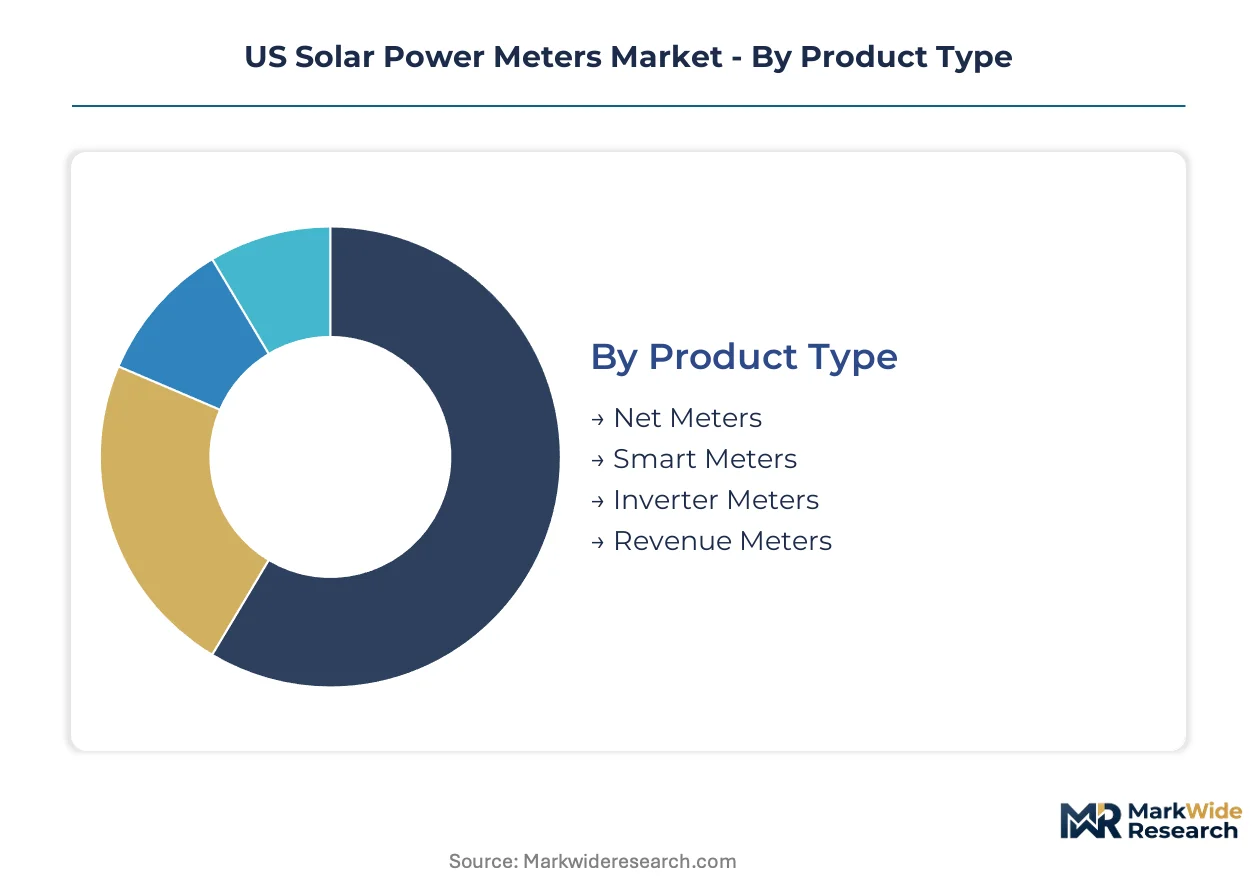
Solar power meter procurement patterns diverge sharply across application contexts, with accuracy requirements and connectivity specifications determining vendor selection and pricing tiers. Understanding these segment boundaries clarifies where manufacturers must compete on certification depth versus cost engineering.
Product Type:
Utility procurement teams prioritize certification grade over unit cost, while residential installers balance accuracy with installation simplicity.
- Net Meters:Bidirectional measurement devices calibrated for grid export compensation under state net metering frameworks. California's NEM 3.0 transition drives replacement demand across 1.5 million existing rooftop systems as utilities mandate interval data reporting.
- Smart Meters:Cellular-enabled devices with embedded LTE-M modems and cloud-agnostic APIs for real-time production monitoring. Arizona Public Service and Duke Energy deployments favor integrated sensor arrays that consolidate revenue metering with irradiance reference functions.
- Inverter Meters:DC-side string monitoring hardware integrated with silicon carbide power electronics. Demand concentrates in utility-scale Southwest deployments where string-level diagnostics reduce O&M truck rolls.
- Revenue Meters:NIST-traceable instruments requiring 18-month laboratory validation cycles for certification compliance. Procurement concentrates with national EPC contractors managing interconnection queue deadlines.
Volume sits with Net Meters; growth tilts toward Smart Meters.
End User:
Scale determines metering architecture, from single-point residential production verification to distributed sensor networks across utility portfolios.
- Residential:Single-phase production meters triggered by rooftop solar penetration and mandatory incentive compliance metering. Florida and Texas lead deployment volume as net metering reforms spread.
- Commercial:Three-phase submetering for behind-the-meter solar plus storage configurations. Demand clusters in California and New York where time-of-use rate structures maximize bill savings.
- Industrial:High-voltage revenue-grade instrumentation for on-site generation offsetting peak demand charges. Procurement cycles align with corporate renewable energy certificate commitments.
- Utilities:Fleet-scale AMI-integrated production meters for utility-owned solar and grid-connected independent power producers. ERCOT's 35 GW solar pipeline compresses procurement timelines.
Utilities command procurement volume; residential applications are climbing fastest.
Technology:
Grid interconnection status dictates meter communication protocols and anti-islanding protection requirements.
- Grid-Tied:Synchronized inverters with IEEE 1547-compliant ride-through capabilities. Southwest and Southeast corridors dominate deployment as interconnection queues swell.
- Off-Grid:Standalone charge controllers with battery state-of-charge integration. Remote Alaska and Hawaii installations drive specialized demand for ruggedized enclosures.
- Hybrid:Dual-mode inverters switching between grid-tied and islanded operation. California wildfire safety shutoff mandates accelerate backup power adoption.
- Microgrid:Distributed energy resource management system controllers with peer-to-peer load balancing. Military bases and university campuses pilot multi-node metering architectures.
Grid-Tied systems anchor current volume; Hybrid configurations show the steepest expansion trajectory.
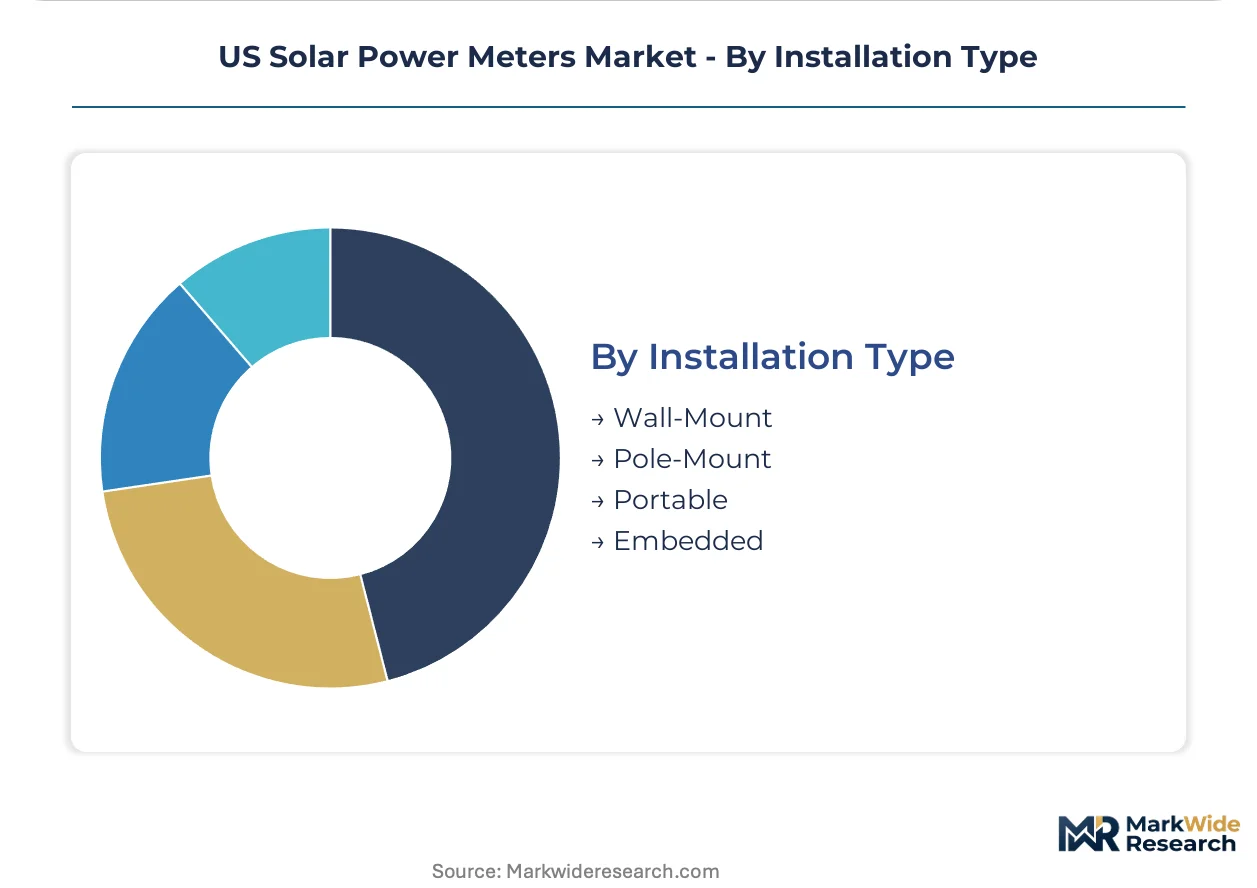
Installation Type:
Mounting geometry determines environmental sealing ratings and cabling complexity for field deployment teams.
- Wall-Mount:NEMA 4X enclosures for residential and light commercial electrical service panels. Standardized form factors reduce installer training overhead.
- Pole-Mount:Elevated instrumentation for utility-scale solar farms with integrated cellular antennas. Texas and Florida utility-scale pipelines favor this configuration for theft deterrence.
- Portable:Handheld irradiance meters for commissioning verification and performance ratio audits. Third-party asset managers like NovaSource lease Class A pyranometers with guaranteed calibration schedules.
- Embedded:Factory-integrated sensors within module-level power electronics or string combiner boxes. Module manufacturers source these for warranty validation data streams.
Pole-Mount dominates utility procurement; Portable meters gain share in O&M service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Imperial Valley-Salton Sea corridor in California anchors North American solar irradiance measurement demand, hosting the densest concentration of utility-scale photovoltaic installations requiring Class A pyranometer validation.
California
California Public Utilities Commission Rulemaking 22-07-005 mandates 15-minute interval data reporting for distributed solar interconnections, forcing firmware upgrades across 1.5 million existing rooftop systems. The California Independent System Operator manages interconnection queues exceeding 70 GW of solar capacity, compressing procurement timelines for revenue-grade meters. The Central Valley solar belt from Fresno to Bakersfield concentrates utility-scale deployments where precision irradiance monitoring validates power purchase agreements.
Texas
ERCOT's 35 GW solar pipeline creates demand for bidirectional meters capable of real-time frequency response signaling and grid export compensation. The Public Utility Commission of Texas oversees interconnection standards for utility-scale solar farms across the Permian Basin and West Texas renewable zones. The Odessa-Midland corridor hosts rapid utility-scale expansion where meter procurement concentrates with national EPC contractors managing queue deadlines.
Florida
Florida Power & Light's solar expansion program drives residential production metering mandates as net metering reforms spread across investor-owned utility territories. The Florida Public Service Commission regulates interconnection standards for rooftop solar systems exceeding 10 kW capacity. The Tampa-Orlando corridor leads deployment volume where third-party asset managers standardize on subscription-based meter fleets for O&M contracts.
Arizona
Arizona Public Service deploys integrated sensor arrays that consolidate revenue metering with irradiance reference functions, reducing standalone pyranometer procurement. The Arizona Corporation Commission oversees distributed generation interconnection rules requiring smart meter compatibility with IEEE 2030.5 standards. The Phoenix-Mesa metropolitan area concentrates commercial and industrial behind-the-meter solar installations requiring three-phase submetering for time-of-use rate optimization.
US Solar Power Meters Market Competitive Landscape
The competitive structure tilts toward calibration-heritage specialists defending premium positioning through NIST-traceable certification depth. Three archetypes dominate: multinationals with diversified test and measurement portfolios, environmental instrumentation specialists with ruggedized field designs, and precision optics laboratories serving research certification bodies. Competitive moves concentrate on strategic partnerships with national EPC contractors and portfolio diversification into subscription-based calibration services.
Within the environmental monitoring tier, Campbell Scientific, Inc. and Apogee Instruments, Inc. exemplify ruggedized design specialists purpose-built for harsh desert climates and remote deployment durability. Fluke Corporation occupies a position among multinationals leveraging calibration heritage for utility commissioning team relationships. Solar Light Company, Inc. anchors the precision optics segment where spectral measurement capabilities serve photovoltaic research laboratories and certification protocols.
| Leading Market Players |
|---|
| Campbell Scientific, Inc. |
| Solar Light Company, Inc. |
| Fluke Corporation |
| EKO Instruments Co., Ltd. |
| General Tools & Instruments |
| FLIR Systems |
| Apogee Instruments, Inc. |
| OTT HydroMet B.V. |
| Amprobe |
| Others |
Pricing and Supply Chain Analysis
Certification-grade stratification between NIST-traceable revenue meters and handheld irradiance sensors splits the market into divergent pricing architectures and sourcing configurations. Premium tiers command calibration-heritage premiums through 18-month laboratory validation cycles, while commodity segments face cost compression from silicon photodiode substitution sourced through Asian component channels.
Pricing Analysis
Yield-guarantee pricing anchors utility procurement contracts, where meter accuracy directly underwrites power purchase agreement performance validations. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with revenue-grade instruments carrying 3-4x multiples over handheld commissioning tools. Price erosion runs through the residential installer tier as Chinese photodiode sensors undercut thermopile-based alternatives. Utilities exhibit lowest price sensitivity, prioritizing interconnection queue compliance over unit cost.
Supply Chain Analysis
Calibration technician scarcity in German and Japanese thermopile manufacturing hubs constrains detector output and extends lead times for US meter assemblers. Component sourcing draws from Japanese sensor foundries, German optics laboratories, and domestic firmware development centers. Single-source vulnerability concentrates in thermopile detector supply, exposing assemblers to 14-week procurement delays. Distribution runs through national EPC contractor networks and third-party asset manager subscription fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metrology talent scarcity props pricing power for calibration-capable manufacturers, with NIST-traceable technician availability serving as the binding capacity constraint across revenue-grade production.
For Market Incumbents: To counter silicon photodiode substitution from Chinese competitors, deepen calibration service subscriptions with guaranteed replacement schedules and embed cellular LTE-M modems as standard firmware features. Secure backward integration into thermopile detector supply through exclusive partnerships with Japanese component houses. For New Entrants and Emerging Players: AI-enabled predictive maintenance algorithms offer a technology-first wedge into O&M service contracts, where NovaSource and SOLV Energy procurement teams seek software-recurring revenue partnerships. Target Texas ERCOT grid expansion for bidirectional meter deployment, leveraging frequency response signaling capabilities as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with ruggedized environmental instrumentation specialists given Inflation Reduction Act production tax credit acceleration across Southwest solar corridors. Long-term viability favors calibration-heritage assets with embedded utility relationships. Watch California NEM 3.0 implementation velocity as the inflection signal for smart meter replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Subscription | Captures recurring revenue from third-party asset managers like NovaSource standardizing on leased meter fleets. |
| Cellular Modem Firmware Integration | Meets California CPUC Rulemaking 22-07-005 mandates for 15-minute interval data reporting compliance. |
| Thermopile Detector Supply Agreement | Secures component access against 14-week lead times from concentrated Japanese and German suppliers. |
| AI Predictive Maintenance Platform | Opens software-recurring models through machine learning applied to irradiance data streams. |
| ERCOT Grid Certification Pathway | Enables real-time frequency response signaling for Texas utility-scale solar pipeline procurement. |
Research Methodology
Document review covered FERC interconnection filings, state public utility commission rulemakings, and NIST traceability protocols, complemented by interviews with utility planning officers, EPC procurement managers, and calibration laboratory directors. Secondary validation drew from EIA generation data, IEA renewable technology reports, and project development databases. Bottom-up meter shipment estimates triangulated against top-down solar capacity deployment projections.
Historical installation patterns cross-referenced with panel input from meter OEMs and utility procurement teams shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product certification grade, end-user scale tier, installation mounting configuration, and regional regulatory cluster. CAGRs derived from capacity-weighted deployment timelines and replacement cycle assumptions for existing net meter infrastructure.
Several conditions sit outside the modeled scope, including potential NIST protocol revisions, abrupt net metering policy reversals, and thermopile supply chain disruptions. Forecasts reflect stated interconnection queue progressions and incentive program continuity assumptions. Material deviation in California NEM 3.0 implementation velocity or Japanese component export restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
Parabolic Solar Cookers Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
Asia-Pacific Bifacial Solar Market
Solar Power Systems
Bifacial Solar Cells Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Asia-Pacific Solar Photovoltaic (PV) Market
Solar Power Systems
Bifacial Solar Panels Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
Solar Skin Market
Solar Power Systems
Graphene Solar Cell Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Utility Solar PV EPC Market
Solar Power Systems
Fixed Tilt Solar PV Market