
 Qatar Solar Energy Market | 2026-2036
Qatar Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Solar Energy Market Analytics
Multi-source EPC contracting is shifting from European-dominated supply chains toward Asian module suppliers and local balance-of-system integrators. Qatar Solar Energy leverages captive polysilicon sourcing through joint ventures. Siraj Energy anchors its position via stakes in utility-scale independent power producers. ACWA Power competes on desalination-coupled solar project experience transferred from Saudi Arabia.
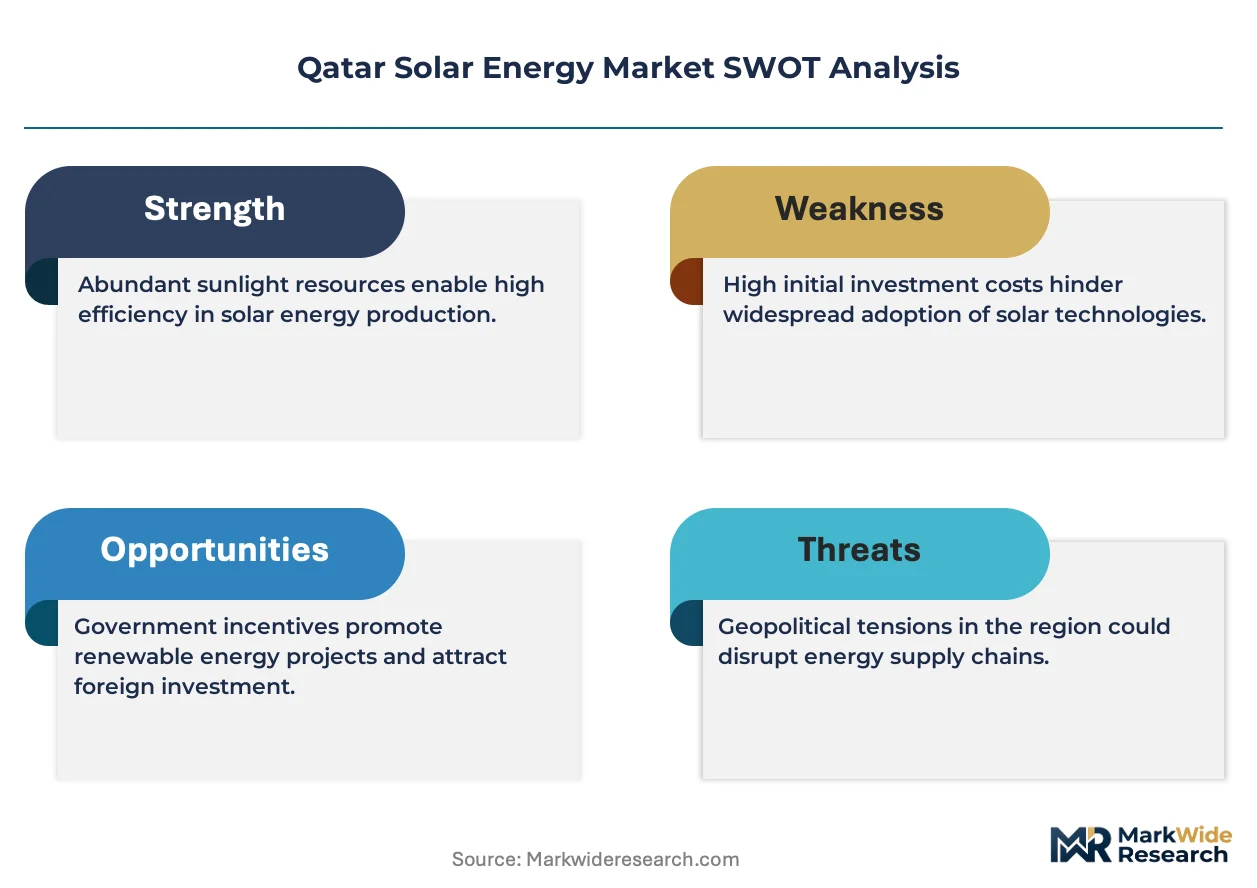
Solar energy in Qatar encompasses photovoltaic and concentrated solar power systems engineered to convert incident irradiance exceeding 2,200 kWh per square meter annually into grid-connected electricity or thermal output for industrial process heat. Crystalline Silicon modules dominate installed capacity given proven bankability under Gulf humidity and salinity stressors. Ground-Mounted installations lead the pipeline as desert land availability removes rooftop constraints. Floating solar trials in cooling ponds at power stations represent an emerging margin pool for technology differentiation.
Qatar General Electricity and Water Corporation (Kahramaa) sets renewable purchase obligations that determine offtake security for project finance. The Qatar Financial Centre Regulatory Authority governs green bond issuance structures mobilizing institutional capital. Qatar Central Bank prudential guidelines on sustainable lending shape domestic bank participation. Stakeholders must monitor Kahrama's auction schedule and tariff escalation clauses to time procurement and development commitments.
Market Dynamics
Utility-scale power procurement by Kahramaa is compressing project development timelines and forcing EPC contractors to localize supply chains. This structural pull from Qatar's single-buyer market architecture dominates competitive positioning.
Growth Catalysts
- Qatar National Vision 2030:The national framework mandates renewable energy integration into the electricity mix. This policy anchor provides long-term offtake certainty for independent power producers.
- Industrial zone clustering:Ras Laffan energy corridor developments concentrate demand from petrochemical and LNG facilities seeking process heat decarbonization. These load centers justify transmission infrastructure investment.
- Bifacial module technology:High-albedo desert surfaces amplify rear-side energy yield. Developers are specifying bifacial crystalline silicon for new ground-mounted installations.
Market Restraints
- Polysilicon supply concentration:Captive sourcing dependencies through joint ventures limit supplier diversification. Asian polysilicon producers control upstream material flows.
- Desert soiling losses:Dust accumulation on module surfaces degrades performance without automated cleaning systems. O&M costs escalate in high-particulate environments.
- Grid integration standards:Kahramaa technical codes for inverter compliance create certification bottlenecks. Testing timelines extend project commissioning schedules.
Strategic Opportunities
- Floating solar deployment:Cooling ponds at power stations and industrial facilities offer water surface area for PV installation. This application circumvents land-use constraints in coastal zones.
- Green hydrogen co-location:Electrolyzer integration with solar generation enables export-oriented hydrogen production. Qatar's LNG infrastructure provides offtake pathways.
- Desalination coupling:Thermal desalination plants require steady thermal input. Concentrated solar power with thermal storage matches this load profile.
Industry Challenges
- Specialized EPC talent scarcity:Local engineering capacity for utility-scale solar construction remains thin. Contractors import project management expertise from established markets.
- Humidity and salinity stress testing:Module certification for Gulf environmental conditions requires extended validation protocols. Bankability assessments delay financial close.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Solar Energy Market |
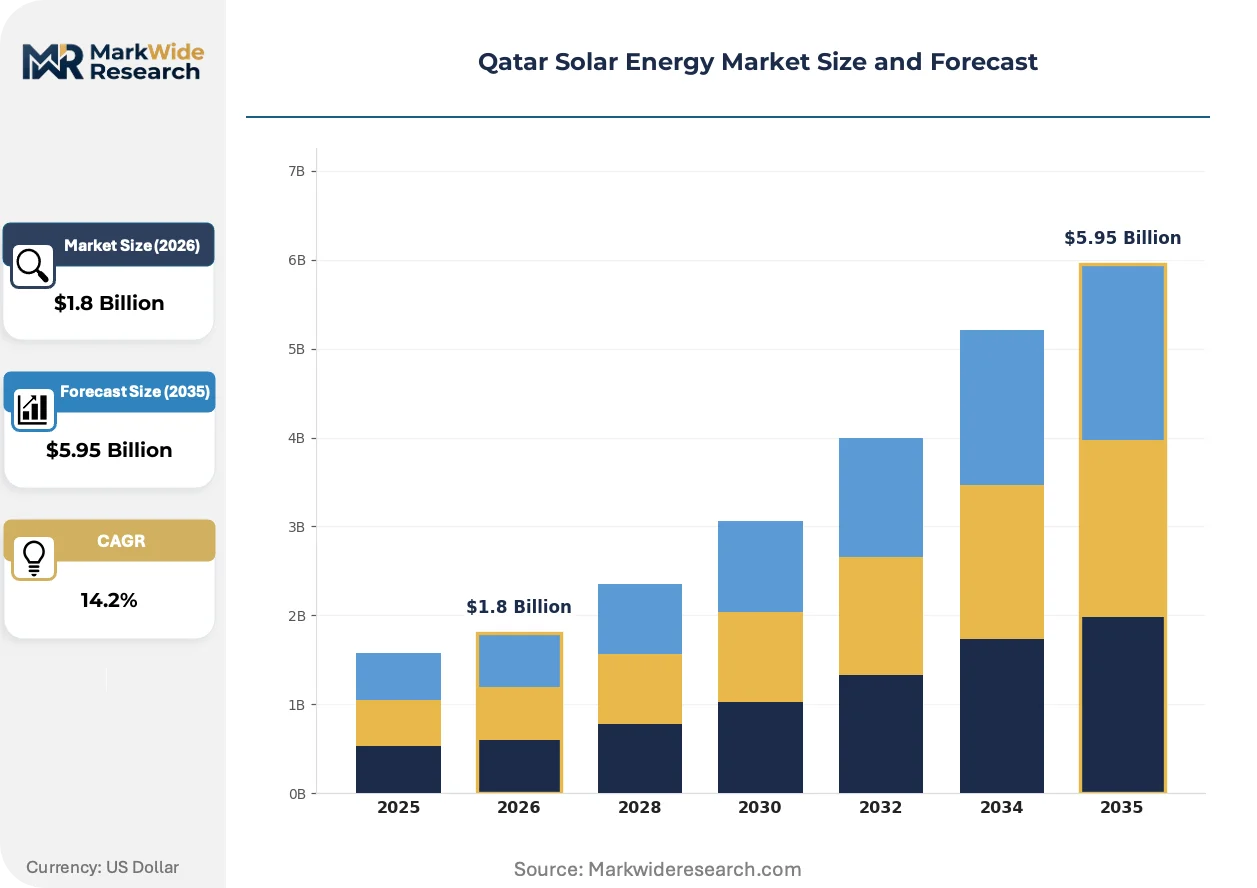
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Solar Inverters, Solar Batteries, Solar Thermal Collectors End User: Residential, Commercial, Industrial, Government Technology: CSP, Thin-Film, Crystalline Silicon, BIPV Installation: Ground-Mounted, Roof-Mounted, Floating, Hybrid Systems |
| Companies Covered | Qatar Solar Energy, Siraj Energy, Qatar Solar Technologies, Powergreen WLL, MCT Group Trading WLL, Marubeni Corp, Nebras Power Q.S.C, ACWA Power, TotalEnergies SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Solar Energy Market Evolving Landscape
Technology convergence between photovoltaic generation and thermal applications is expanding addressable demand beyond pure electricity offtake. This shift reconfigures project economics and EPC scope.
Bifacial crystalline silicon modules with tracking systems are rewriting capacity factor assumptions for desert installations. Industrial offtakers in Ras Laffan are specifying these configurations for behind-the-meter supply. The technology is compressing levelized cost thresholds and displacing conventional fixed-tilt designs in new tenders.
Qatar Financial Centre Regulatory Authority guidelines for green bond issuance are mobilizing institutional capital into renewable infrastructure. These structures reduce cost of capital for utility-scale developers. Kahramaa-backed projects are accessing this financing channel to accelerate procurement schedules.
Long-term power purchase agreements with fixed escalation clauses are displacing merchant exposure in developer business models. EPC contractors are aligning equipment procurement with these contract tenors. Qatar's single-buyer market structure makes this shift most pronounced compared to multi-buyer jurisdictions.
Qatar Solar Energy Market Segmentation
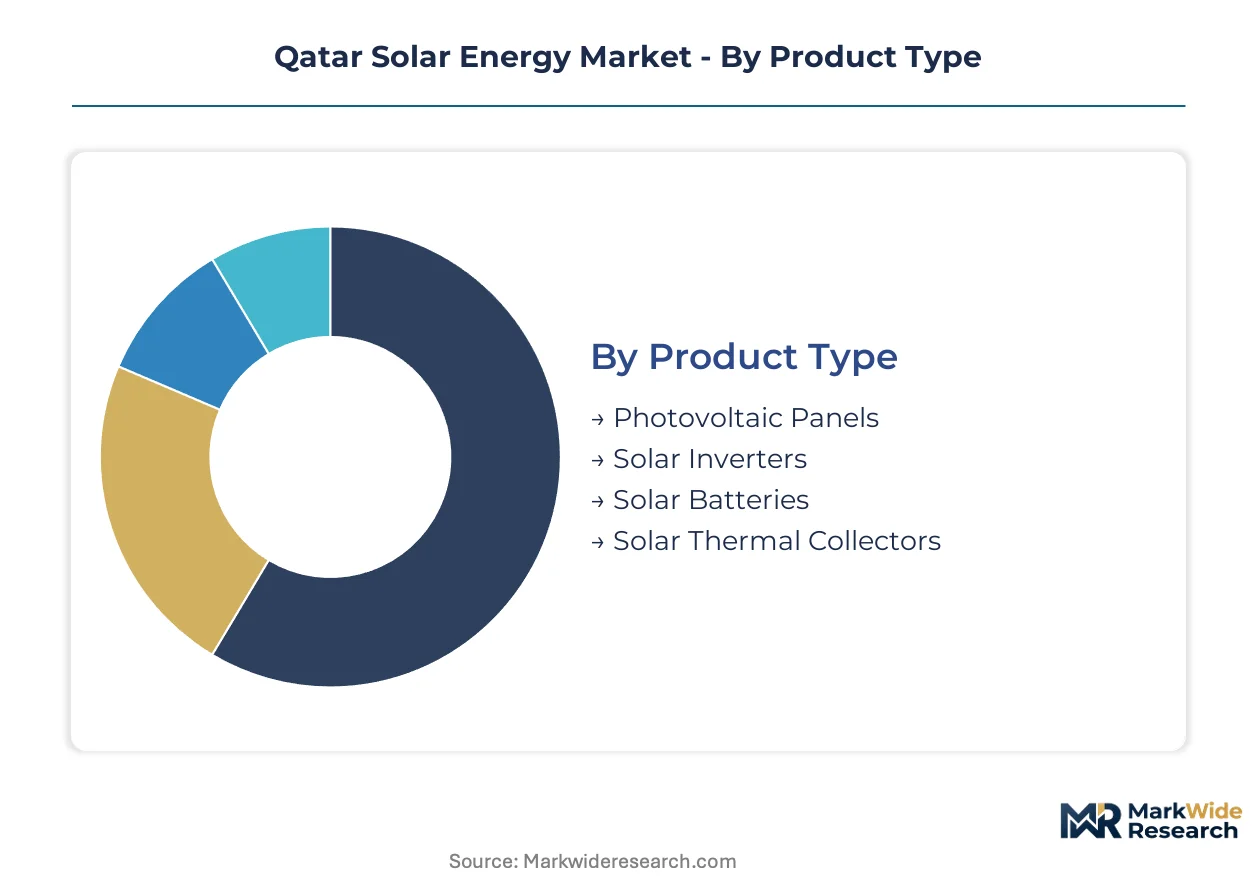
Segmentation in Qatar's solar energy market reveals how Kahramaa's procurement architecture directs investment toward specific technology configurations. Equipment categories face divergent certification requirements under Gulf environmental standards. End-user concentration in industrial zones reshapes product mix priorities across each segment.
Product Type:
Photovoltaic Panels require IEC 61215 certification for humidity and salinity resistance under Gulf conditions. Solar Inverters face Kahramaa grid code compliance testing that extends commissioning timelines. Solar Batteries and Solar Thermal Collectors carry distinct regulatory burdens for thermal cycling validation.
- Photovoltaic Panels:Crystalline silicon modules dominate procurement specifications given proven bankability under desert soiling stress. Ras Laffan petrochemical facilities specify bifacial configurations for behind-the-meter supply, leveraging high-albedo desert surfaces for rear-side yield amplification.
- Solar Inverters:String and central inverter architectures require Kahramaa technical code certification for voltage ride-through capabilities. Grid integration standards create testing bottlenecks that compress EPC delivery schedules for utility-scale projects.
- Solar Batteries:Lithium-ion storage systems integrate with solar generation for evening discharge matching Qatar's peak demand curves.
- Solar Thermal Collectors:Flat-plate and evacuated tube configurations supply process heat for industrial desalination and district cooling applications.
Leading the category by volume: Photovoltaic Panels. Growing fastest: Solar Batteries.
End User:
Cost tier differentiation separates premium industrial installations from standardized residential deployments. Government-backed procurement commands lowest capital costs through scale aggregation.
- Residential:Rooftop installations concentrate in Doha's suburban districts with net metering frameworks under Kahramaa regulations. Smaller system sizes limit supplier margins compared to utility-scale segments.
- Commercial:Shopping malls and hotel complexes deploy solar for corporate sustainability mandates and tariff hedging against grid electricity escalation clauses.
- Industrial:Ras Laffan energy corridor developments anchor demand volume. LNG and petrochemical facilities procure multi-megawatt installations for process heat decarbonization and behind-the-meter electricity supply.
- Government:Kahramaa-anchored utility-scale projects provide long-term offtake certainty through sovereign-backed power purchase agreements. This segment accesses Qatar Financial Centre green bond structures for reduced cost of capital.
Industrial procurement commands the largest absolute capacity additions. Residential deployment expands most quickly from a low base.
Technology:
Application requirements dictate technology selection across electricity and thermal output needs. CSP configurations match desalination baseload profiles while PV dominates variable generation.
- CSP:Concentrated solar power with thermal storage supplies steady thermal input for multi-effect distillation desalination plants. ACWA Power transfers Saudi project experience for Qatar deployment.
- Thin-Film:Cadmium telluride and CIGS modules offer temperature coefficient advantages in extreme desert heat. Limited bankability under local financing constraints restricts adoption.
- Crystalline Silicon:Monocrystalline and polycrystalline variants constitute the installed capacity base. Bifacial specifications with tracking systems are displacing fixed-tilt designs in new tenders.
- BIPV:Building-integrated photovoltaics serve architectural glazing applications in Doha's commercial high-rise construction. Higher capital costs limit penetration outside premium developments.
Crystalline Silicon leads by installed capacity. BIPV gains share fastest in new commercial construction.
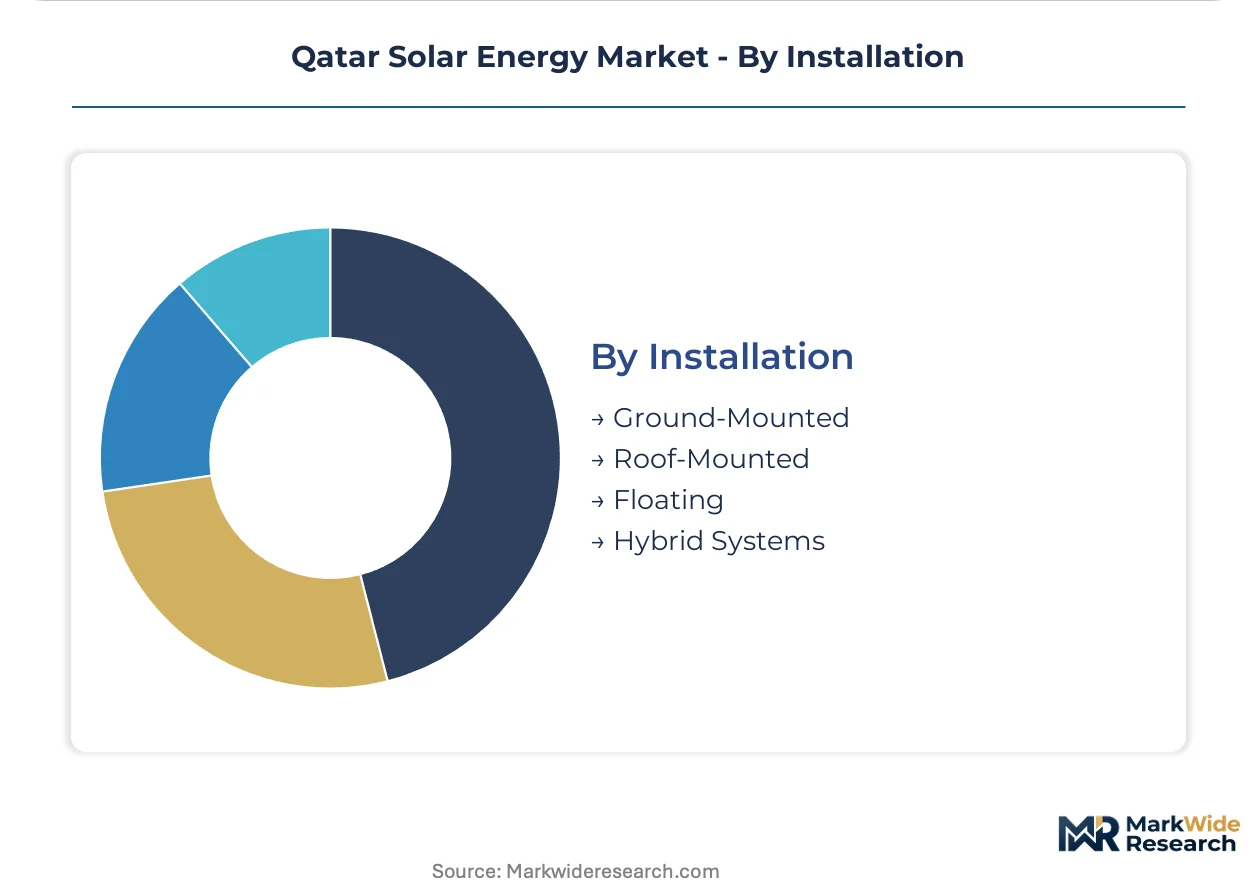
Installation:
Geography within Qatar determines installation category viability. Coastal land constraints push floating solar trials while desert availability favors ground-mounted expansion.
- Ground-Mounted:Desert land availability removes rooftop constraints for utility-scale development. Kahramaa's Al Kharsaah facility exemplifies this configuration at scale.
- Roof-Mounted:Commercial and residential applications in Doha's built environment face structural load assessments and shading analysis. Smaller individual project sizes fragment EPC contracting.
- Floating:Cooling ponds at power stations and industrial facilities offer water surface deployment. This category circumvents land-use constraints in coastal zones where desert availability is limited.
- Hybrid Systems:Solar-plus-storage and solar-desalination configurations integrate multiple generation assets. Green hydrogen co-location represents an emerging hybrid architecture for export-oriented production.
Ground-Mounted installations lead by megawatt capacity. Floating solar climbs the fastest from minimal existing base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polysilicon feedstock sourcing from East Asian suppliers anchors Qatar's solar manufacturing partnerships. Desert land availability in the Arabian Peninsula shapes utility-scale project economics. Kahramaa's single-buyer procurement model concentrates development timelines within the Gulf Cooperation Council corridor.
Doha Metropolitan Area
Industrial zone clustering in Doha's southern districts concentrates behind-the-meter solar demand from petrochemical facilities. Kahramaa net metering regulations govern rooftop installations in suburban districts. The Ras Abu Aboud and Mesaieed industrial corridors host multi-megawatt ground-mounted systems serving LNG process heat requirements.
Al Kharsaah Region
Utility-scale power procurement by Kahramaa targets this desert expanse for gigawatt-scale solar parks. Qatar Central Bank prudential guidelines on sustainable lending finance these sovereign-backed developments. The Al Kharsaah Independent Power Producer facility exemplifies crystalline silicon deployment with bifacial tracking configurations.
Ras Laffan Energy Corridor
Desalination-coupled solar demand from LNG export facilities drives thermal collector specifications in this northern industrial zone. Qatar Financial Centre Regulatory Authority green bond structures mobilize institutional capital for these integrated projects. ACWA Power transfers Saudi project experience for thermal desalination load matching.
Umm Al Houl Industrial Area
Cooling pond floating solar trials target water surface deployment at power generation facilities. Kahramaa technical codes for inverter compliance create certification pathways for these emerging installations. The area's coastal location circumscribes land-use constraints through marine-adjacent photovoltaic deployment.
Al Wakrah Municipality
Residential rooftop installations concentrate in southern Doha suburban developments under Kahramaa distributed generation frameworks. Smaller system sizes fragment EPC contracting compared to utility-scale segments. The municipality anchors demand expansion from low residential solar penetration baselines.
Qatar Solar Energy Market Competitive Landscape
Global majors compete with regional champions across EPC contracting and module supply chains in Qatar's single-buyer market. The vendor base stratifies between captive polysilicon producers, utility-scale IPP developers, and balance-of-system integrators. Three archetypes dominate: state-backed energy champions with sovereign offtake access, Gulf-based EPC specialists with desert construction experience, and international IPP developers with thermal-coupled project expertise. Competitive positioning hinges on strategic partnerships with Kahramaa and backward integration into polysilicon supply.
Within the state-backed champion tier, Qatar Solar Energy exemplifies captive upstream control through joint venture polysilicon sourcing. Siraj Energy occupies a position anchoring utility-scale IPP stakes. ACWA Power represents the international developer archetype with desalination-coupled solar experience transferred from Saudi Arabia. These three entities illustrate how procurement alignment with Kahramaa's auction schedule determines market access.
| Leading Market Players |
|---|
| Qatar Solar Energy |
| Siraj Energy |
| Qatar Solar Technologies |
| Powergreen WLL |
| MCT Group Trading WLL |
| Marubeni Corp |
| Nebras Power Q.S.C |
| ACWA Power |
| TotalEnergies SE |
| Others |
Value Network & Pricing Analysis
Captive polysilicon sourcing through joint ventures anchors Qatar Solar Energy's supply position and pricing power against merchant module competitors. This backward integration into upstream material flows insulates project economics from Asian feedstock volatility while compressing EPC contractor margins on unbundled component procurement.
Pricing Analysis
Extended warranty and O&M service bundling distinguishes Kahramaa-backed utility-scale tenders from merchant solar deployments. Three-tier pricing structure across premium, standard, and economy levels reflects bifacial tracking specifications, IEC 61215 certification grades, and desert soiling resilience testing. Cost compression in standard-tier crystalline silicon modules is intensifying because Asian suppliers are flooding Gulf markets with excess capacity. Industrial offtakers in Ras Laffan exhibit lowest price sensitivity due to process heat decarbonization mandates, while residential rooftop buyers in Al Wakrah demand aggressive tariff hedging.
Supply Chain Analysis
Direct-to-EPC channels handle Kahramaa's hyperscale procurement volumes, bypassing distributor markups that fragment residential contracting. Polysilicon feedstock concentrates in China, South Korea, and Germany, with Qatar Solar Energy's joint ventures drawing from selective Asian partnerships. High-purity silicon ingots, tempered glass, and aluminum frames constitute critical component dependencies. Single-source vulnerability in polysilicon purification creates supply chain risk given geopolitical friction in East Asian trade corridors. Distribution runs through balance-of-system integrators for utility-scale projects and local electrical contractors for distributed rooftop segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's solar market has become a vertical-integration race where captive upstream control over polysilicon and downstream access to Kahramaa offtake agreements determine competitive survival. Players lacking either lever face margin compression from integrated champions.
For Market Incumbents: Cement sovereign offtake relationships through early alignment with Kahramaa's auction schedule and tariff escalation clauses. Deepen backward integration into module assembly capacity to defend against emerging Asian EPC contractors with captive supply chains. The threat of Saudi-experienced developers like ACWA Power transferring thermal-coupled project expertise demands accelerated localization of engineering talent. For New Entrants and Emerging Players: Qatar Financial Centre Regulatory Authority guidelines for green bond issuance open a window for financial engineering specialists to structure institutional capital vehicles. Target floating solar deployment in coastal cooling ponds where land-use constraints create penetrable white-space outside desert ground-mounted competition. Partner with established balance-of-system integrators for Kahramaa grid code certification rather than building compliance capabilities in-house. For Investors and Strategic Acquirers: Exit pathways concentrate in utility-scale IPP stake sales to regional sovereign wealth vehicles seeking yield-backed infrastructure exposure. Long-term viability hinges on developers securing fixed-escalation PPA tenors that outlast merchant price cycles. Watch Kahramaa's technical code revisions for inverter compliance as the inflection signal determining which EPC contractors can sustain commissioning timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Qatar Solar Energy's joint ventures insulate project margins from Asian feedstock price volatility. |
| Green Bond Structuring | Qatar Financial Centre guidelines mobilize institutional capital for Kahramaa-backed utility-scale developments. |
| Floating Solar Deployment | Cooling pond installations at Umm Al Houl circumvent coastal land constraints for technology differentiation. |
| Bifacial Tracking Configuration | High-albedo desert surfaces amplify rear-side yield for Ras Laffan industrial behind-the-meter supply. |
| Desalination Coupling | Thermal storage integration matches steady baseload requirements for multi-effect distillation plants. |
Research Methodology
Multi-period observation of Kahramaa procurement schedules, EPC contractor localization rates, and module import volumes anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, grid operators, and balance-of-system integrators. Secondary validation drew from Qatar Central Bank prudential guidelines, Kahramaa technical codes, IEA renewable energy reports, and project finance database disclosures. Bottom-up capacity addition modeling triangulated against top-down national renewable target trajectories.
Input-output matrices mapped polysilicon feedstock flows through module assembly to installed capacity across the projection horizon. Segmentation dimensions modeled include technology type, installation category, end-user sector, and project scale tier. CAGRs were derived from regression analysis of historical auction tariffs and learning curve coefficients applied to bifacial module cost declines. Forecast inputs incorporated desert soiling loss assumptions and grid integration timeline distributions.
The model assumes a particular technology adoption path; alternative pathways for concentrated solar power with thermal storage would alter the outlook if desalination coupling accelerates beyond photovoltaic dominance. Forecasts reflect base-case assumptions regarding Kahramaa procurement continuity, Asian supply chain stability, and Gulf environmental certification protocols. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Utility Solar PV EPC Market
Solar Power Systems
PERC Solar Cell Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Solar Simulator Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Solar Crimp Set Market
Solar Power Systems
Building Applied Photovoltaics (BAPV) Market
Solar Power Systems
Ghana Solar Energy Market
Solar Power Systems
Middle-East Solar Power Market
Solar Power Systems
United Arab Emirates Solar Energy Market
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
Asia-Pacific Solar Tracker Market
Solar Power Systems
India Residential Solar Inverter Market
Solar Power Systems
Parabolic Solar Cookers Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market