
 Middle-East Solar Power Market | 2026-2036
Middle-East Solar Power Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East Solar Power Market Outlook
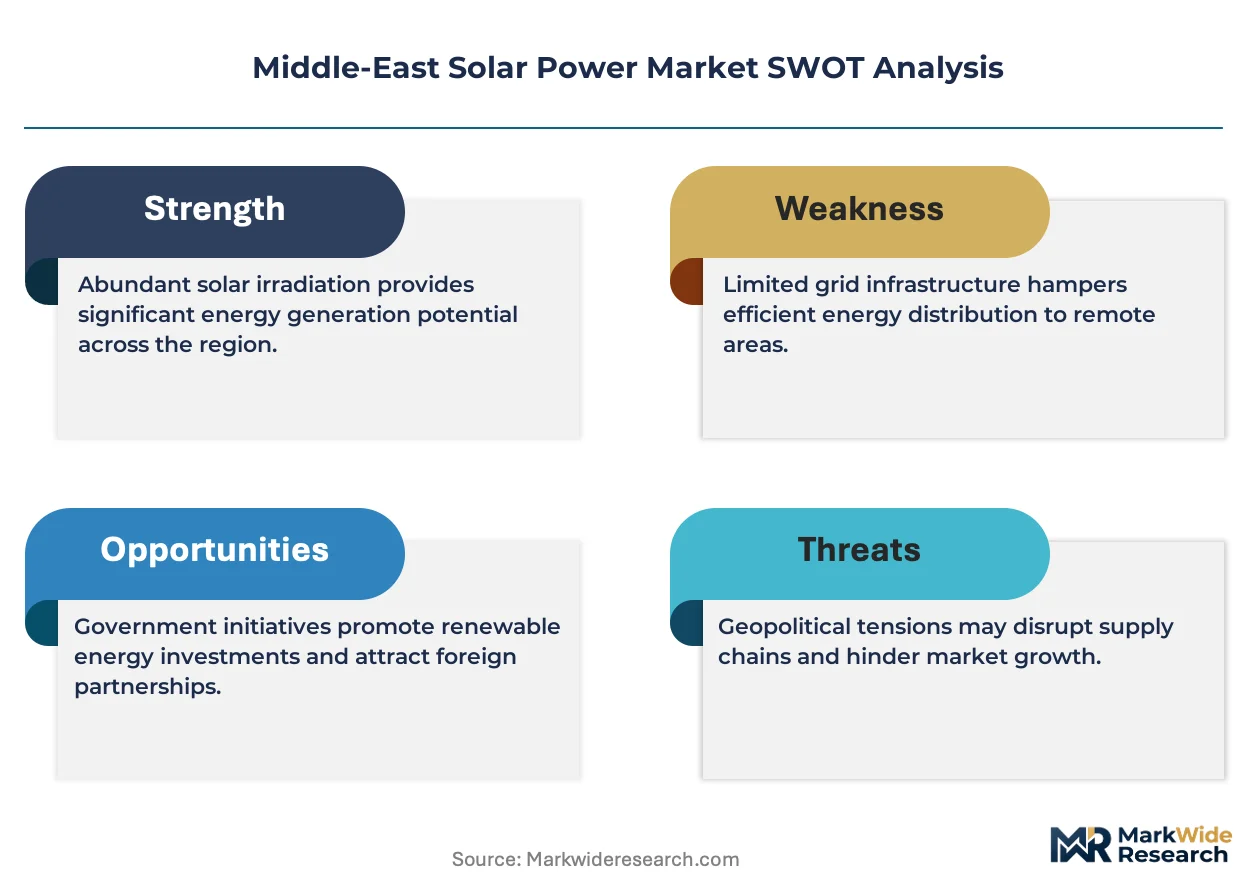
ISO 50001 energy management certification is collapsing as a baseline qualification for EPC contractors bidding on utility-scale solar projects across the Middle East. ACWA Power leverages its integrated development model to anchor Saudi Arabia's renewable energy program. Masdar sustains technology leadership through concentrated solar power deployments in the UAE. JinkoSolar competes aggressively on module supply contracts for regional gigawatt-scale tenders.
Middle-East solar power encompasses photovoltaic and thermal systems converting solar irradiance into electricity, with monocrystalline silicon modules achieving conversion efficiencies above 22% in desert conditions where ambient temperatures exceed 45 degrees Celsius. The technology serves commercial and industrial offtakers seeking to displace gas-fired generation and reduce exposure to volatile hydrocarbon feedstock costs. Photovoltaic systems dominate installed capacity due to modular deployment speed and declining levelized cost structures. Concentrated solar power with thermal storage commands premium project valuations where evening grid dispatch is required. Utility-scale installations attract the majority of capital allocation as sovereign wealth funds prioritize centralized generation assets with long-term power purchase agreements.
Saudi Arabia's National Renewable Energy Program and the UAE's net-zero strategy shape procurement timelines and local content requirements for solar developers. Grid codes issued by the Saudi Electricity Company and Emirates Water and Electricity Company mandate frequency response capabilities and inverter standards that filter equipment suppliers. International Electrotechnical Commission certifications for desert-rated modules function as de facto market access requirements. Stakeholders must monitor evolving domestic manufacturing incentives and storage co-location mandates that will determine project bankability and supply chain configuration across the region.
Market Dynamics
Utility-scale procurement in Saudi Arabia and the UAE is compressing project timelines as sovereign wealth funds prioritize centralized generation assets with long-term power purchase agreements, forcing EPC contractors to accelerate certification and local content compliance.
Growth Catalysts
- Saudi National Renewable Energy Program:Gigawatt-scale tender rounds mandate domestic manufacturing partnerships, pulling module assembly lines into the Kingdom's industrial zones.
- Desert-rated module efficiency gains:Monocrystalline silicon conversion above 22 percent at 45-degree ambient temperatures improves project IRR calculations for independent power producers.
- Industrial offtaker demand:Petrochemical and aluminum smelting facilities seek to hedge volatile natural gas feedstock costs through behind-the-meter solar installations.
Market Restraints
- Polysilicon supply concentration:Upstream ingot and wafer production clusters in China expose Middle Eastern developers to tariff and logistics risk.
- Grid integration standards:Saudi Electricity Company frequency response mandates filter inverter suppliers lacking IEC 61850 certification.
- Land acquisition complexity:Utility-scale parks require coordinated approvals across multiple government entities, extending development timelines.
Strategic Opportunities
- Oman and Jordan green hydrogen corridors:Electrolyzer co-location with solar generation creates integrated export-oriented asset classes.
- Storage co-location mandates:Emirates Water and Electricity Company requirements for evening dispatch capability premium-price thermal and battery hybrids.
- Building-integrated photovoltaics:Commercial real estate developers in Dubai adopt facade-embedded modules to meet net-zero certification thresholds.
Industry Challenges
- Certification timeline compression:ISO 50001 energy management and IEC desert-rating approvals now function as baseline bid qualifications, squeezing smaller EPCs.
- Skilled technician scarcity:Concentrated solar power thermal maintenance and high-voltage DC string commissioning require specialized labor pools not yet developed regionally.
- Supply chain reconfiguration:Local content rules force developers to qualify new module and inverter suppliers, introducing performance uncertainty into bankability models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East Solar Power Market |
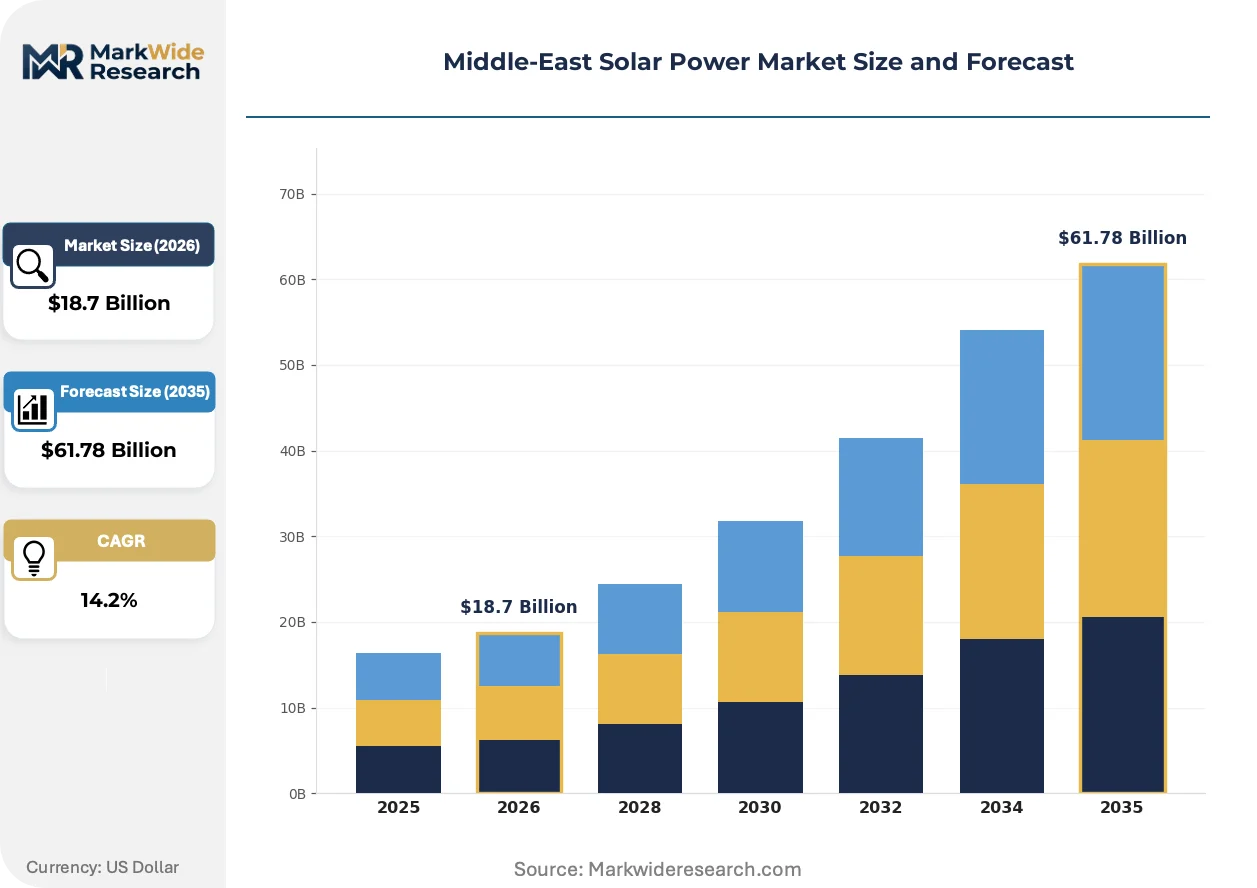
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Systems, Concentrated Solar Power, Solar Water Heaters, BIPV Technology: Monocrystalline, Polycrystalline, Thin Film, Hybrid Systems Application: Residential, Commercial, Industrial, Utility Installation: On-Grid, Off-Grid, Rooftop, Ground-Mounted |
| Companies Covered | ACWA Power, Masdar, Dubai Electricity and Water Authority (DEWA), Abu Dhabi National Energy Company (TAQA), EDF Renewables, Engie, JinkoSolar Holding Co., Ltd., First Solar, Inc., Scatec ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East Solar Power Market Strategic Shifts
Module technology and procurement structures are diverging as desert-specific performance requirements and sovereign manufacturing mandates reshape supplier relationships and project economics.
Bifurcation between monocrystalline PERC and TOPCon cell architectures is bifurcating the equipment supply base. Saudi gigawatt-scale tenders favor TOPCon modules for their superior temperature coefficient performance, while UAE commercial rooftop developers prioritize PERC for cost-sensitive distributed generation. This technical split is compressing margins for module manufacturers lacking dual-platform production flexibility.
SFDA and MOHAP safety frameworks for industrial equipment are converging with IEC standards to create unified certification pathways for solar inverters and transformers. The industrial consequence is reduced regulatory friction for multinational EPCs operating across Saudi Arabia and the UAE. Grid-scale developers in both markets are responding by consolidating procurement specifications to capture economies of scale in equipment sourcing.
Long-term power purchase agreements are displacing merchant exposure as the dominant offtake structure for utility-scale assets. Independent power producers in Saudi Arabia's PIF-backed program now anchor revenue models on 25-year contracts with Saudi Electricity Company, compressing equity risk premiums. This contractual shift is most visible in the Red Sea coastal zone where gigawatt parks cluster around centralized transmission infrastructure.
Middle-East Solar Power Market Segmentation
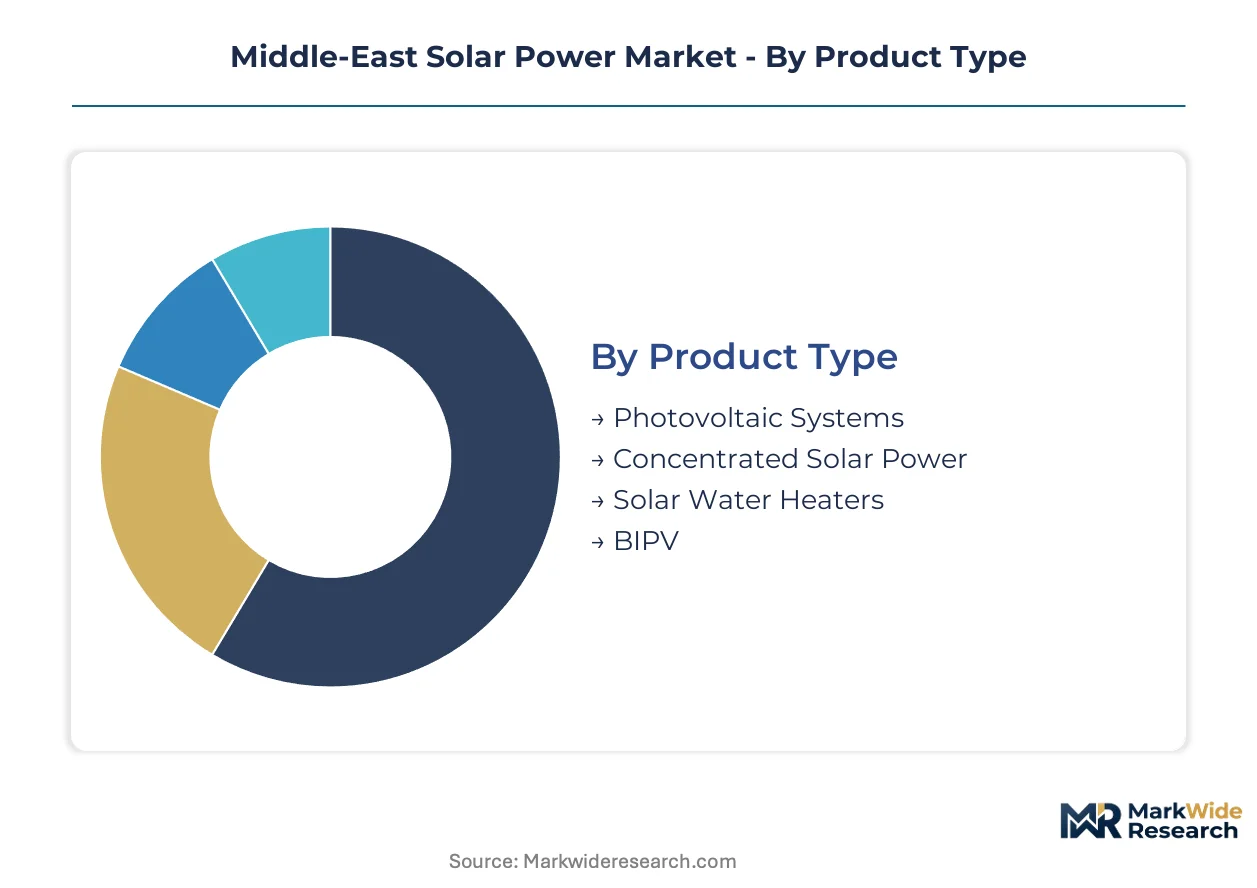
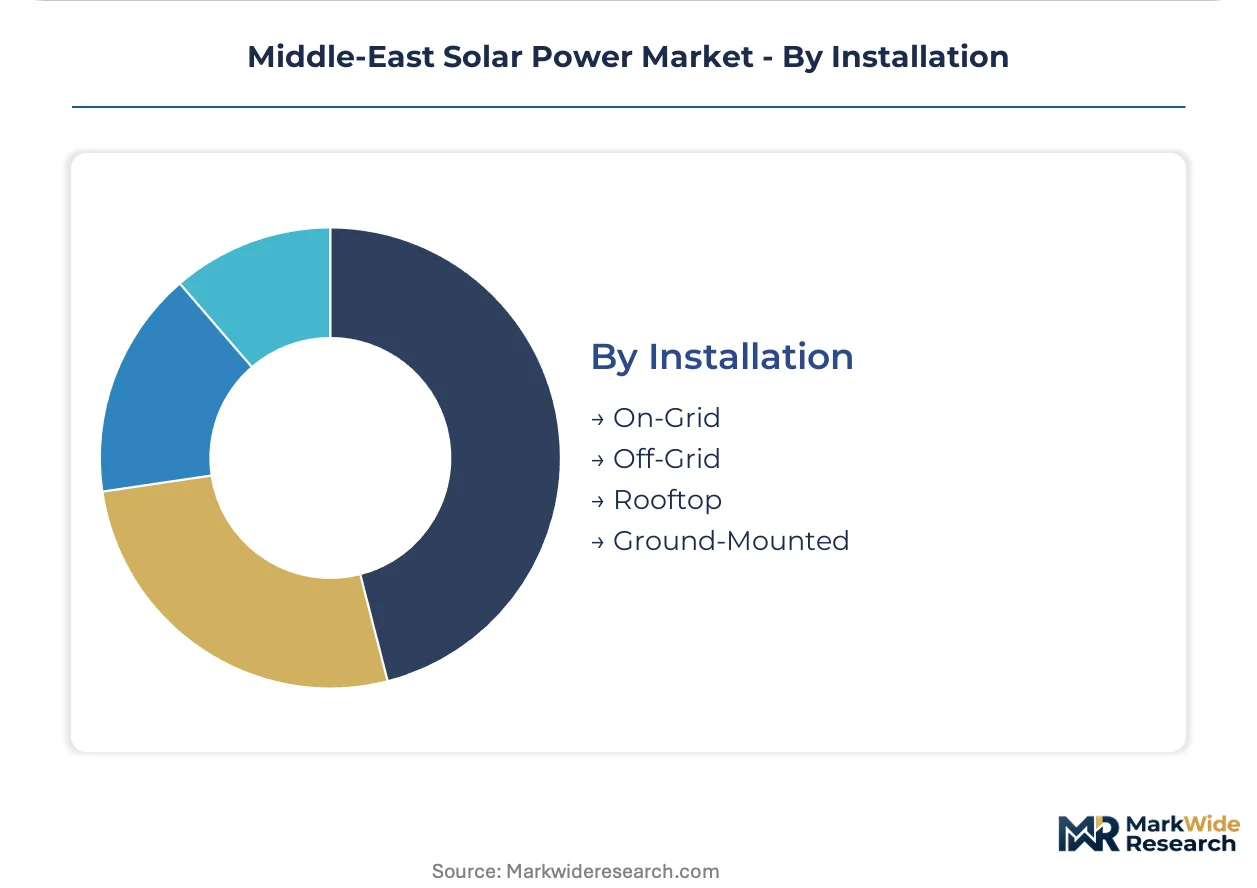
Segmentation in the Middle-East solar power market reveals how technology choices and installation configurations map to distinct procurement channels and regulatory pathways across Saudi Arabia and the UAE.
Product Type:
Photovoltaic systems face intensifying substitution pressure from concentrated solar power where evening dispatch mandates create technology switching incentives for utility developers.
- Photovoltaic Systems:Modular silicon-based arrays dominate procurement volumes in Saudi Arabia's gigawatt-scale parks. Utility-scale tenders from ACWA Power and Masdar prioritize monocrystalline modules for desert temperature performance.
- Concentrated Solar Power:Parabolic trough and tower configurations with molten salt storage command premium valuations in Dubai's Mohammed bin Rashid Al Maktoum Solar Park expansion zones where evening grid injection is mandatory.
- Solar Water Heaters:Flat-plate and evacuated tube collectors serve residential and light commercial thermal loads in Jordan and Lebanon's distributed energy markets.
- BIPV:Building-integrated photovoltaic facades and skylights penetrate Dubai's commercial real estate sector as developers pursue net-zero certification thresholds.
Photovoltaic systems retain volume leadership; concentrated solar power holds the steepest expansion curve where storage co-location mandates apply.
Technology:
Cost tier stratification separates premium cell architectures from commodity alternatives in module procurement specifications issued by Saudi Electricity Company and Emirates Water and Electricity Company.
- Monocrystalline:Single-crystal silicon cells achieve conversion efficiencies above 22 percent at 45-degree ambient temperatures. Saudi gigawatt-scale tenders specify monocrystalline PERC and TOPCon platforms for utility-scale deployment.
- Polycrystalline:Multi-crystal silicon modules trade efficiency for capital cost advantages in distributed commercial rooftop applications across the UAE's cost-sensitive building sector.
- Thin Film:Cadmium telluride and CIGS technologies occupy niche utility-scale roles where temperature coefficient performance outweighs area efficiency constraints.
- Hybrid Systems:Photovoltaic-thermal combinations and solar-wind configurations emerge in Oman and Jordan's green hydrogen corridor planning.
Monocrystalline technology captures the premium procurement tier; hybrid systems are gaining share fastest in integrated export-oriented asset classes.
Application:
Customer type concentration varies sharply across segments, with sovereign wealth fund deployment patterns diverging from private offtaker risk appetites.
- Utility:Centralized generation assets with 25-year power purchase agreements anchor capital allocation in Saudi Arabia's PIF-backed program and UAE sovereign wealth portfolios.
- Industrial:Behind-the-meter installations at petrochemical and aluminum smelting facilities in Jubail Industrial City and Abu Dhabi's Kizad zone displace volatile natural gas feedstock exposure.
- Commercial:Distributed generation on logistics facilities and retail properties in Dubai's Jebel Ali zone and Riyadh's King Abdullah Financial District targets net-zero operational targets.
- Residential:Small-scale rooftop penetration remains constrained by financing access and grid interconnection timelines in Saudi Arabia's secondary cities.
Utility applications dominate capital deployment; industrial offtake is expanding most quickly as feedstock hedging motivations intensify.
Installation:
Supply concentration in grid-tied infrastructure shapes segment accessibility, with transmission availability determining viable project configurations.
- Ground-Mounted:Utility-scale parks in Saudi Arabia's Red Sea coastal zone and UAE desert regions cluster around centralized transmission infrastructure with 500kV interconnection capacity.
- On-Grid:Grid-tied installations must comply with Saudi Electricity Company frequency response mandates and IEC 61850 inverter certification requirements.
- Rooftop:Distributed commercial and residential systems in Dubai's sustainable city developments and Riyadh's diplomatic quarter navigate building-integrated permitting pathways.
- Off-Grid:Stand-alone systems serve remote industrial camps and agricultural pumping loads in Oman's interior and Jordan's border regions beyond transmission reach.
Ground-mounted installations command the majority of capital allocation; rooftop deployment is climbing the fastest as building codes mandate solar readiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale offtakers concentrate procurement authority in sovereign wealth funds and state-backed developers, compressing vendor selection criteria and accelerating project timelines across national renewable energy programs.
Saudi Arabia
ACWA Power anchors gigawatt-scale solar park development in the Red Sea coastal zone, with the National Renewable Energy Program mandating domestic manufacturing partnerships. SFDA safety frameworks converge with IEC standards for inverter certification. NEOM Northwest hosts integrated renewable hydrogen and solar generation clusters where electrolyzer co-location creates export-oriented asset classes.
United Arab Emirates
Masdar sustains concentrated solar power deployments with molten salt storage in Dubai's Mohammed bin Rashid Al Maktoum Solar Park expansion zones. MOHAP safety regulations unify certification pathways for multinational EPCs operating across emirates. Abu Dhabi's TAQA-backed developments cluster around centralized transmission infrastructure with 500kV interconnection capacity.
Oman
Green hydrogen corridor planning pulls electrolyzer co-location demand into solar generation zones beyond transmission reach. The country's national renewable energy regulator mandates storage co-location for evening dispatch capability. Dhofar and Al Wusta governorates host remote industrial camps where stand-alone solar serves agricultural pumping loads.
Jordan
Net-metering reforms accelerate distributed commercial rooftop penetration in Amman and Aqaba special economic zones. The national electricity regulatory commission issues grid codes filtering inverter suppliers without frequency response capabilities. Mafraq and Ma'an governorates concentrate utility-scale parks near border transmission interconnections with neighboring markets.
Qatar
World Cup legacy infrastructure drives building-integrated photovoltaic adoption in Lusail and Education City developments. Kahramaa grid integration standards mandate IEC 61850 certification for utility-scale connections. Ras Laffan Industrial City hosts behind-the-meter installations at petrochemical facilities seeking feedstock cost hedging.
Middle-East Solar Power Market Competitive Environment
Player mix skews toward state-backed developers with integrated generation portfolios, compressing private independent power producer access to long-term offtake contracts. Market structure concentrates around three strategic archetypes: sovereign wealth fund developers controlling procurement timelines, multinational EPC contractors managing certification compliance, and module manufacturers qualifying for domestic content mandates. Competitive moves center on local partnership formation and backward integration into component assembly.
Within the sovereign developer tier, ACWA Power and Masdar exemplify state-backed vertical integration models that anchor national renewable energy programs. Among international module suppliers, JinkoSolar Holding Co., Ltd. and First Solar, Inc. occupy positions shaped by desert-rating certification requirements and gigawatt-scale tender participation. EDF Renewables and Engie represent European utility entrants competing through technology licensing and EPC consortium structures.
| Leading Market Players |
|---|
| ACWA Power |
| Masdar |
| Dubai Electricity and Water Authority (DEWA) |
| Abu Dhabi National Energy Company (TAQA) |
| EDF Renewables |
| Engie |
| JinkoSolar Holding Co., Ltd. |
| First Solar, Inc. |
| Scatec ASA |
| Others |
Value Chain & Pricing Dynamics
Ninety-day module inventory cycles in Jeddah port terminals concentrate pricing power with Chinese polysilicon suppliers and compress margin buffers for EPC contractors bidding on Saudi gigawatt-scale tenders. This lead-time exposure anchors procurement negotiations and forces developers to absorb upstream volatility through index-linked contract structures.
Pricing Analysis
Cost-plus arrangements indexed to Shanghai Metal Market polysilicon spot rates dominate module procurement contracts for Saudi Arabia's National Renewable Energy Program tenders. Pricing stratifies across IEC desert-rated premium tiers, standard utility-grade modules, and economy polycrystalline alternatives for distributed commercial applications. Cost compression in the standard tier is intensifying because Saudi local content mandates force qualification of new assembly partners with unproven bankability. Industrial offtakers at Jubail petrochemical facilities demonstrate highest price sensitivity due to feedstock hedging calculations, while sovereign wealth fund developers prioritize performance guarantees over capital cost minimization.
Supply Chain Analysis
Module inventory cycles stretching to 120 days at Dubai Jebel Ali free zone terminals expose developers to polysilicon price swings and shipping rate volatility. Upstream ingot and wafer production draws from China, Malaysia, and Vietnam, with cell assembly concentrating in Chinese industrial zones. Raw material dependencies span metallurgical-grade silicon, silver paste for cell metallization, and aluminum framing extrusions. Single-source vulnerability in TOPCon cell architecture equipment creates qualification bottlenecks for Saudi domestic manufacturing mandates. Distribution runs through EPC contractor consortia with established relationships to Saudi Electricity Company and Emirates Water and Electricity Company procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East solar power market functions as a defensive-moat arena where regulatory entrenchment through IEC certification and local content compliance creates durable barriers against unqualified entrants. Sovereign wealth fund procurement concentration amplifies switching costs for established developers.
For Market Incumbents: Fortify certification moats by accelerating IEC 61850 inverter compliance and ISO 50001 energy management accreditation ahead of Saudi Electricity Company mandate expansions. Deepen backward integration into module assembly within Saudi Arabia's industrial zones to satisfy National Renewable Energy Program domestic content thresholds and neutralize emerging Chinese manufacturer joint ventures.
For New Entrants and Emerging Players: Lead with building-integrated photovoltaic facades targeting Dubai commercial real estate developers pursuing net-zero certification, the most penetrable segment given fragmented EPC competition and permissive permitting pathways. Develop specialized commissioning capabilities for concentrated solar power thermal maintenance to capture premium service contracts in Masdar's molten salt storage deployments.
For Investors and Strategic Acquirers: Carve-out targets emerge from European utility renewable divisions seeking to monetize Middle-East development pipelines amid capital reallocation pressures. Long-term viability hinges on 25-year power purchase agreement access secured through sovereign relationships rather than merchant exposure. Watch for Saudi PIF tender round frequency acceleration as the primary inflection indicator for deployable capital availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Partnership | Secures bid qualification under Saudi National Renewable Energy Program local content mandates. |
| IEC Desert-Rating Certification | Unlocks equipment supply contracts for 45-degree ambient temperature performance specifications. |
| Storage Co-location Integration | Captures Emirates Water and Electricity Company evening dispatch premium pricing structures. |
| Green Hydrogen Corridor Development | Creates integrated export-oriented asset classes in Oman and Jordan planning zones. |
| Long-term Power Purchase Agreement | Compresses equity risk premiums through Saudi Electricity Company 25-year contract anchoring. |
Study Parameters
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through IEA renewable energy databases, FERC-style regulatory filings from Saudi Electricity Company, project development tracking databases, and customs trade records for module import flows. Bottom-up installation capacity modeling triangulated against top-down sovereign wealth fund capital deployment disclosures.
Sensitivity analysis framed volume and value outputs across the projection horizon, with segmentation dimensions spanning photovoltaic versus concentrated solar power technology, monocrystalline PERC versus TOPCon cell architecture, utility-scale versus distributed application scale, and regulatory framework clusters across Saudi Arabia, UAE, Oman, and Jordan. CAGRs derived from regression analysis of historical tender award patterns and announced pipeline capacities. Industry-specific forecast inputs incorporated polysilicon supply elasticity assumptions and grid interconnection queue processing rates.
Forecasts assume regulatory continuity in Saudi Arabia's National Renewable Energy Program and UAE net-zero strategy implementation; material policy shifts around local content thresholds or storage co-location mandates would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Europe Solar Microinverter Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Greece Solar Energy Market
Solar Power Systems
Solar Pontoon Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
Czech Republic Solar Energy Market
Solar Power Systems
Floating Solar System Market
Solar Power Systems
Solar Photovoltaic Glass Market
Solar Power Systems
Australia Rooftop Solar Market
Solar Power Systems
Building Integrated Photovoltaic (BIPV) Market
Solar Power Systems
PV Solar Data Logger Market