
 Network As a Service (Naas) Market | 2026-2036
Network As a Service (Naas) Market Size, Share, and Industry Trends Forecast 2026-2036
Network As a Service (Naas) Market Intelligence
The EU Green Deal is decoupling enterprise network infrastructure from on-premises hardware ownership, pushing CIOs toward subscription-based consumption models. Cisco Systems leverages its Internet backbone footprint to anchor large-scale SD-WAN deployments across European manufacturing zones. Juniper Networks differentiates through Mist AI integration, sustaining automation-driven margin pools in campus and branch environments.
Network As a Service (NaaS) denotes the delivery of network functionality—spanning switching, routing, security, and WAN optimization—via cloud-based subscription models with service-level agreements guaranteeing throughput, latency, and uptime thresholds. The architecture eliminates capital-intensive hardware procurement while enabling elastic bandwidth provisioning aligned to real-time application demands. Hybrid Cloud deployment now captures the largest revenue share as enterprises retain sensitive workloads on-premises while bursting traffic to public infrastructure. SD-WAN within Solution Offering represents the fastest-expanding category, displacing legacy MPLS contracts with policy-driven path selection across multiple transport types.
EMA guidelines on critical infrastructure resilience, EU NIS2 cybersecurity mandates, and GDPR data-localization requirements collectively shape NaaS procurement specifications across European member states. Compliance complexity elevates vendor selection criteria toward certified managed security service bundles with audited encryption standards. Stakeholders must evaluate whether provider ecosystems can absorb upcoming CSRD disclosure obligations without passing compliance costs through to enterprise subscribers.
Market Dynamics
Enterprise abandonment of capital-intensive MPLS circuits is compressing procurement cycles and forcing vendors toward consumption-based pricing models anchored by SD-WAN automation.
Growth Catalysts
- EU NIS2 Directive:Mandatory cybersecurity risk management for critical infrastructure operators is accelerating outsourced network security adoption across energy and transport sectors.
- Industrial automation clusters:German manufacturing zones are deploying private NaaS instances to synchronize OT-IT convergence with deterministic latency guarantees.
- Cloud-native architectures:Financial services firms are rebuilding core payment networks on containerized routing stacks to enable elastic capacity during settlement windows.
Market Restraints
- Silicon supply concentration:Merchant silicon dependence on Taiwan-based foundries exposes SD-WAN appliance vendors to fab capacity allocation volatility.
- GDPR localization friction:Data residency requirements fragment cross-border network designs and inflate compliance engineering overhead for multinational deployments.
- Legacy skill scarcity:Enterprise IT organizations lack personnel fluent in both BGP policy engineering and Kubernetes network abstraction layers.
Strategic Opportunities
- Edge AI inference networks:Convergence of 5G slicing with GPU-accelerated edge nodes creates managed low-latency backhaul demand from autonomous systems developers.
- CSRD disclosure services:Upcoming corporate sustainability reporting mandates position NaaS providers to bundle Scope 3 emissions tracking into network telemetry dashboards.
- France healthcare digitization:The country's national electronic health record expansion requires secure multi-site connectivity for regional hospital federations.
Industry Challenges
- Brownfield integration complexity:Enterprises maintaining decades-old VLAN segmentation struggle to map policy domains into cloud-native zero-trust frameworks without service disruption.
- Multi-cloud orchestration talent:Shortage of engineers proficient in Terraform, Ansible, and vendor-specific SD-WAN controllers delays deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network As a Service (Naas) Market |
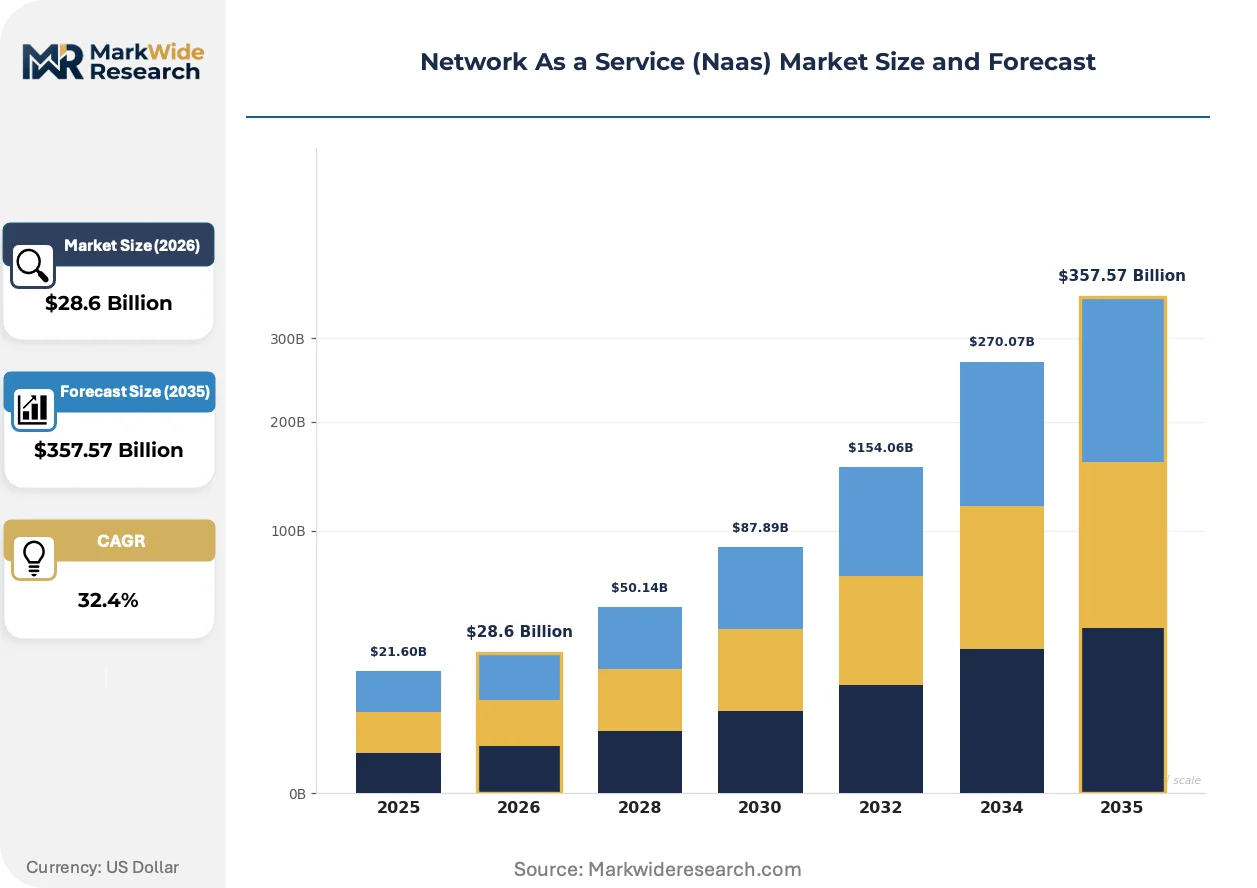
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $357.57 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Offering: Virtual Private Network, Bandwidth on Demand, SD-WAN, Network Security, Edge Connectivity Application: Data Center Interconnect, Content Delivery, Cloud Connectivity, Disaster Recovery End User Industry Vertical: Telecommunication Providers, Financial Services Firms, Government Agencies, Educational Institutions |
| Companies Covered | Cisco Systems, AT&T, Verizon Communications, IBM Corporation, Hewlett Packard Enterprise, Juniper Networks, Megaport, Amdocs, Cloudflare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network As a Service (Naas) Market Strategic Shifts & Innovations
Network functionality is migrating from proprietary hardware to software-defined abstraction layers, with AI-driven operations and consumption economics reshaping vendor-customer relationships.
Intent-based networking systems are overtaking CLI-centric administration in campus environments. Large retail chains are deploying these platforms to automate thousands of branch configurations from central policy engines. The technology is compressing mean-time-to-repair metrics while reducing specialized networking headcount requirements.
REACH chemical restrictions on flame-retardant substances in electronics are forcing network equipment manufacturers to reformulate PCB substrates and enclosure materials. Industrial consequences include extended qualification timelines for new hardware platforms. European manufacturing and smart building deployments are absorbing these compliance costs through longer procurement cycles.
Subscription-based consumption is replacing perpetual licensing for WAN edge appliances. Mid-market enterprises are abandoning three-year capital refresh cycles in favor of monthly bandwidth commitments with embedded hardware upgrades. This behavioral shift is most pronounced in Germany's automotive supplier ecosystem, where CFOs prioritize opex predictability over asset ownership.
Network As a Service (Naas) Market Segmentation
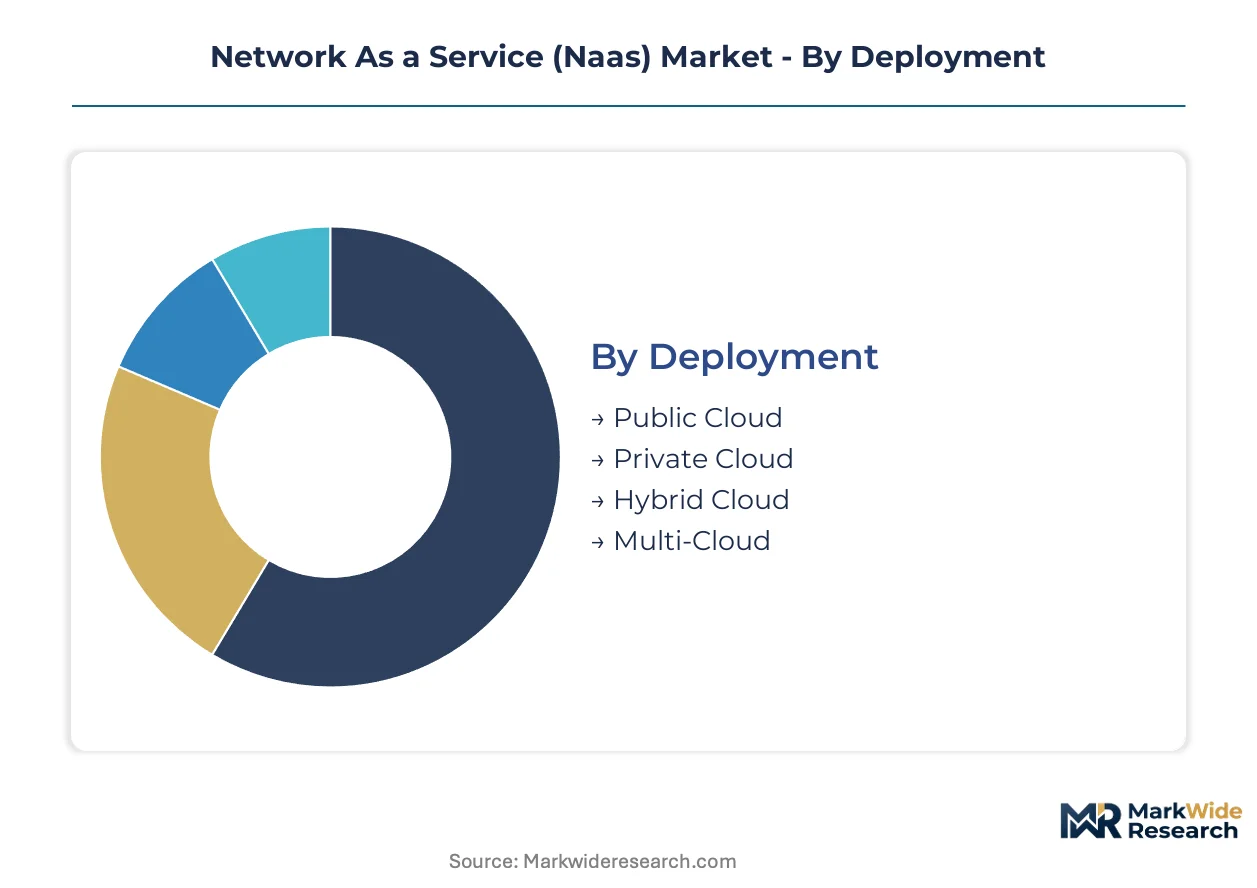
Network As a Service procurement patterns diverge sharply between enterprises seeking elastic burst capacity and those demanding sovereign infrastructure control. Segmentation reveals how workload sensitivity, compliance posture, and operational technology integration shape subscription preferences across European verticals.
Deployment:
Volume deployments cluster in standardized public configurations, while premium pricing attaches to sovereign-controlled private instances with dedicated hardware isolation.
- Public Cloud:Shared infrastructure pools deliver elastic bandwidth provisioning without capital commitment. German mid-market manufacturers favor this model for non-production development environments where latency tolerances exceed 50ms.
- Private Cloud:Dedicated network slices run on single-tenant hardware with audited encryption boundaries. French healthcare federations mandate this architecture for patient record exchange under CNIL data localization requirements.
- Hybrid Cloud:Policy-orchestrated traffic steering between on-premises stacks and public burst capacity. Financial settlement systems in Frankfurt deploy this model to retain transaction ledgers locally while scaling payment validation to cloud during peak windows.
- Multi-Cloud:Abstraction layers normalize connectivity across AWS, Azure, and GCP footprints simultaneously. Enterprise architects in Amsterdam and Stockholm use this approach to avoid vendor lock-in while maintaining consistent security posture.
Mature deployment sits with Hybrid Cloud. Newer deployment is concentrated in Multi-Cloud.
Solution Offering:
Application-layer integration determines margin capture, with infrastructure-agnostic software commanding premium positioning over commoditized transport services.
- SD-WAN:Policy-driven path selection across MPLS, broadband, and 5G transport with centralized orchestration. Dutch logistics operators deploy this to maintain warehouse connectivity during primary circuit failures without truck dispatch interruption.
- Network Security:Firewall-as-a-service and zero-trust access bundled with connectivity subscriptions. EU NIS2 Directive compliance deadlines are accelerating procurement across Danish energy distribution networks.
- Virtual Private Network:Encrypted tunnel overlays for remote workforce access with session-based billing. Italian professional services firms standardize on this for consultant mobility without permanent site licensing.
- Bandwidth on Demand:API-triggered capacity scaling aligned to application telemetry thresholds. Broadcast media companies in London provision this for live event streaming with hourly granularity.
- Edge Connectivity:5G slicing integration with distributed compute nodes for sub-10ms latency. Autonomous vehicle testing corridors around Munich require this for real-time sensor fusion backhaul.
Revenue concentration weights toward Network Security. Steepest expansion trajectory belongs to Edge Connectivity.
Application:
Workload criticality stratifies pricing, with synchronous replication services commanding multiples over asynchronous backup tiers.
- Cloud Connectivity:Optimized routing into hyperscaler regions with dedicated peering relationships. Spanish retail chains leverage this for ERP system cloud migration without re-architecting legacy database connections.
- Data Center Interconnect:Layer 2 extension between facilities with guaranteed throughput and jitter bounds. Swiss banking consortia require this for active-active trading platform architectures across Zurich and Geneva.
- Disaster Recovery:Automated failover orchestration with recovery time objectives contractually enforced. Austrian critical infrastructure operators specify this for NIS2-mandated business continuity compliance.
- Content Delivery:Caching layer integration with origin shielding and geographic load balancing. Nordic streaming services deploy this to reduce transit costs for 4K video distribution.
Established demand centers on Cloud Connectivity. Emerging demand clusters in Disaster Recovery.
End User Industry Vertical:
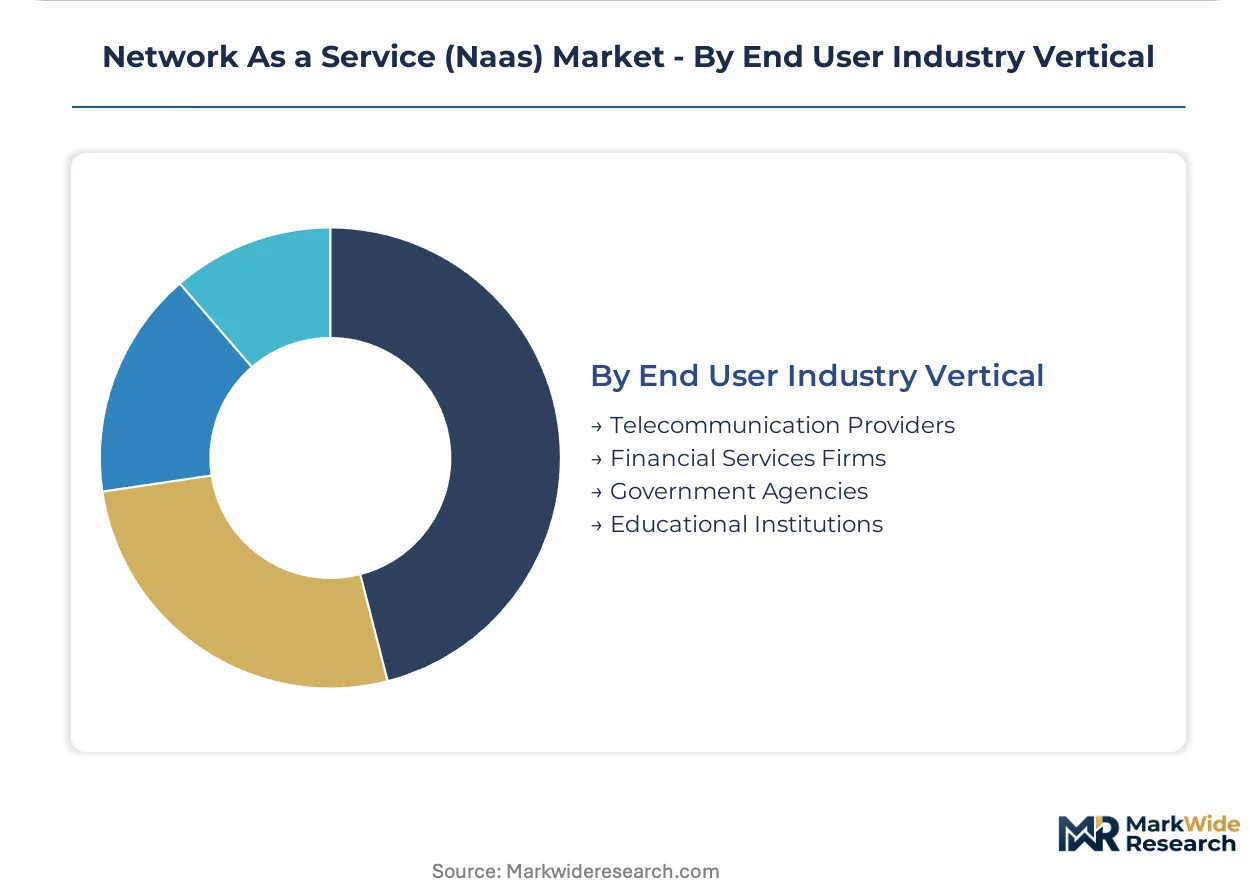
Regulatory intensity separates price-insensitive buyers with compliance engineering budgets from cost-optimized adopters seeking operational efficiency.
- Financial Services Firms:Payment network modernization with containerized routing and real-time fraud detection integration. ECB settlement system requirements drive private cloud NaaS adoption across Frankfurt and Paris banking clusters.
- Government Agencies:Sovereign cloud mandates with certified encryption and domestic data residency. German federal IT consolidation projects specify this for administrative network unification.
- Telecommunication Providers:Wholesale network slicing resale to enterprise customers with white-label orchestration. Incumbent operators in Belgium and Netherlands use this to monetize 5G infrastructure without direct enterprise sales overhead.
- Educational Institutions:Campus-wide SD-WAN with research network federation integration. Dutch university medical centers combine this with SURFnet high-performance computing access for genomic data collaboration.
Contract value leadership resides with Financial Services Firms. Fastest procurement cycle acceleration appears in Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's banking district anchors European NaaS procurement intensity, with the city's concentration of ECB-regulated payment processors driving private cloud network deployments. Industrial automation corridors in southern Germany and financial services clusters in Paris and Amsterdam shape continental demand patterns. Regulatory fragmentation across member states forces providers to maintain multiple compliance certifications.
Germany
Automotive suppliers in Baden-Württemberg and Bavaria deploy private NaaS instances for OT-IT convergence with deterministic latency guarantees. The EU NIS2 Directive compels energy distributors to outsource cybersecurity risk management to certified managed service providers. Munich's autonomous vehicle testing corridors demand edge connectivity with sub-10ms latency for real-time sensor fusion backhaul.
France
Healthcare digitization accelerates through regional hospital federation networks requiring secure multi-site connectivity under CNIL data localization mandates. The national electronic health record expansion drives procurement of dedicated network slices with audited encryption boundaries. Paris banking clusters modernize payment infrastructure under ECB settlement system requirements.
United Kingdom
Broadcast media companies in London provision bandwidth-on-demand services for live event streaming with hourly granularity. GDPR cross-border data transfer restrictions fragment network designs and inflate compliance engineering overhead for multinational deployments. The City's financial institutions retain transaction ledgers locally while scaling payment validation to cloud during peak settlement windows.
Netherlands
Logistics operators deploy SD-WAN across Rotterdam port zones and warehouse networks to maintain connectivity during primary circuit failures. Dutch university medical centers combine campus SD-WAN with SURFnet high-performance computing access for genomic data collaboration. Amsterdam enterprise architects normalize connectivity across AWS, Azure, and GCP footprints simultaneously to avoid vendor lock-in.
Italy
Professional services firms standardize on VPN-as-a-service for consultant mobility without permanent site licensing obligations. REACH chemical restrictions on flame-retardant substances force equipment manufacturers to reformulate PCB substrates, extending hardware qualification timelines. Milan's industrial districts absorb these compliance costs through longer procurement cycles for smart building deployments.
Network As a Service (Naas) Market Key Industry Players
The competitive structure tilts toward telecommunications incumbents with backbone infrastructure assets and cloud-native specialists with software-defined orchestration platforms. Tier-one carriers leverage existing fiber footprints to anchor large-scale SD-WAN deployments, while infrastructure-agnostic vendors capture margin through automation-driven management layers. Two strategic archetypes dominate: integrated connectivity providers bundling security and transport, and pure-play orchestration vendors abstracting multi-cloud complexity. Competitive moves concentrate on strategic partnerships with hyperscaler platforms and geographic expansion through local system integrator channels.
Within the integrated connectivity tier, Cisco Systems and Juniper Networks exemplify infrastructure-anchored positioning, while AT&T represents carrier-originated service bundling. Cisco's Internet backbone footprint sustains manufacturing zone deployments across European industrial corridors. Juniper's Mist AI integration anchors automation-driven margin pools in campus and branch environments. AT&T leverages wireless spectrum assets to converge 5G slicing with managed WAN services. Cloudflare occupies a position at the cloud-native edge, exemplifying security-centric network abstraction without hardware dependency.
| Leading Market Players |
|---|
| Cisco Systems |
| AT&T |
| Verizon Communications |
| IBM Corporation |
| Hewlett Packard Enterprise |
| Juniper Networks |
| Megaport |
| Amdocs |
| Cloudflare |
| Others |
Cost & Logistics Intelligence
Network automation engineers concentrated in southern Germany and the Netherlands command wage premiums that compress margin pools for mid-market SD-WAN deployments. Labor-cost differentials between these specialized talent clusters and Eastern European delivery centers widen pricing-tier spreads across premium managed services and economy self-service tiers.
Pricing Analysis
Throughput-guaranteed service level agreements anchor value-based pricing for NaaS subscriptions, with latency-bound tiers commanding multiples over best-effort bandwidth pools. Pricing stratifies across premium sovereign-private instances, standard hybrid orchestration, and economy public-cloud burst capacity. Cost compression in economy tiers is intensifying because hyperscaler commoditization of basic connectivity erodes vendor differentiation. Mid-market manufacturers in Germany exhibit highest price sensitivity, while Frankfurt banking clusters prioritize compliance-grade uptime over unit cost.
Supply Chain Analysis
Workforce availability constraints in Taiwan-based merchant silicon foundries and Dutch semiconductor equipment hubs tether SD-WAN appliance production to fab capacity allocation cycles. Supply draws from Taiwan for advanced switching ASICs, South Korea for memory components, and Germany for precision optical modules. Single-source vulnerability concentrates in Taiwan Semiconductor Manufacturing capacity for programmable forwarding chips. Distribution runs through carrier-direct channels for enterprise accounts and systems integrator networks for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Merchant silicon foundry capacity serves as the binding constraint propping pricing power for appliance-anchored NaaS tiers. Equipment vendors with secured wafer allocations capture margin expansion unavailable to supply-exposed competitors.
For Market Incumbents: Extend automation platform footprints into OT-IT convergence environments to defend against industrial-specialist challengers. Secure long-term foundry capacity agreements in Taiwan and South Korea to insulate margin pools from allocation volatility. Deepen vertical integration into Mist AI and Kubernetes abstraction layers to reduce dependence on scarce BGP-Kubernetes bilingual engineering talent. For New Entrants and Emerging Players: Regional hospital federations in France present the most penetrable white-space target, with CNIL-mandated private network slices creating compliance-driven procurement urgency. Target bandwidth-on-demand services for London broadcast media clusters where hourly granularity requirements exceed incumbent agility. Pursue white-label orchestration partnerships with Belgian and Dutch telecommunications incumbents to bypass direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native orchestration specialists given hyperscaler partnership velocity as the catalyst. Long-term viability favors platforms with containerized routing stacks and API-native telemetry architectures over hardware-dependent legacy vendors. Watch autonomous vehicle edge-connectivity procurement volumes around Munich as the inflection signal for GPU-accelerated low-latency network demand.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperscaler Partnership Deepening | AWS Direct Connect and Azure ExpressRoute integration secures enterprise cloud-migration attach rates for SD-WAN vendors. |
| AI-Native Operations Platform Launch | Mist AI and intent-based networking compress mean-time-to-repair metrics for retail branch deployments. |
| Private 5G Slicing Integration | Edge connectivity bundling with GPU-accelerated nodes captures autonomous systems developer procurement in Munich corridors. |
| Sovereign Cloud Certification Investment | CNIL and BSI audits enable French healthcare and German federal network unification contract eligibility. |
| Systems Integrator Channel Expansion | Local SI partnerships in Amsterdam and Stockholm accelerate multi-cloud abstraction layer adoption without direct sales overhead. |
Research Approach
Independent corroboration across CTO interviews at Frankfurt banking clusters, network procurement officers at Dutch logistics operators, and regulatory affairs leads at French healthcare federations underwrites the qualitative findings. Secondary validation draws from EMA infrastructure resilience guidelines, EU NIS2 implementation timelines, hyperscaler capex disclosures, and customs data on SD-WAN appliance trade flows. Bottom-up subscription volume estimates triangulate against top-down addressable market calculations across deployment models and vertical segments.
Historical reference periods spanning pre-pandemic MPLS contract cycles through cloud-acceleration phases anchor the forecast window. The analytical framework models deployment architecture, solution offering, end-user vertical, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from elasticity-adjusted adoption curves incorporating EU AI Act compliance deadlines and industrial automation investment cycles. Forecast inputs include foundry capacity allocation projections and Kubernetes networking abstraction adoption rates.
Caveats apply where Taiwan semiconductor export restrictions or REACH chemical reformulation delays could materially shift the outlook. Forecasts reflect assumptions on NIS2 enforcement uniformity and hyperscaler peering cost trajectories. Material deviation in foundry capacity allocation or autonomous vehicle corridor deployment timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Mobile Data Traffic Market
Data Center and Networking
Switzerland Data Center Networking Market
Data Center and Networking
Mobile Data Offload Market
Data Center and Networking
Graph Database Market
Data Center and Networking
Computer Network Design Services Market
Data Center and Networking
Internet Protocol Version 6 (IPv6) Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Vietnam Data Center Networking Market
Data Center and Networking
Global Data Center Networking Market
Data Center and Networking
MPLS-Based Core Network Market
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
Sweden Data Center Networking Market
Data Center and Networking
Cluster Computing Market
Data Center and Networking
Voice Over Internet Protocol (Voip) Market