
 Global Data Warehouse Market | 2026-2036
Global Data Warehouse Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Warehouse Market Foresight
SSD storage is hardening as the default persistence layer over traditional spinning disk in enterprise data warehouse deployments, cutting query latency by orders of magnitude while raising capital intensity. Snowflake Inc. leverages a fully separated storage-compute architecture that lets customers scale resources independently. Amazon Web Services anchors the largest installed base through Redshift and adjacent analytics services. Microsoft Corporation dominates hybrid deployments by extending on-premises SQL Server functionality into Azure Synapse environments.
A data warehouse is a centralized repository designed to store, integrate, and analyze structured data from multiple operational sources, typically supporting petabyte-scale volumes with columnar indexing and massively parallel processing architectures optimized for complex analytical queries rather than transactional throughput. Cloud-based deployment now leads new capacity additions as enterprises retire on-premise appliances, while data governance solutions command premium pricing due to regulatory complexity. Analytics and reporting applications absorb the largest share of professional services spend, though fraud detection workloads in banking are expanding fastest as real-time inference requirements intensify.
The EU AI Act imposes documentation and auditability requirements on automated decision systems that feed from warehouse layers, compelling vendors to embed lineage tracking natively. HIPAA in the United States enforces access controls and audit trails for healthcare data warehouses, while BIS cloud standards in India mandate data localization for financial institutions. Stakeholders must weigh sovereignty requirements against the operational simplicity of hyperscale platforms when architecting cross-border analytics infrastructure.
Market Dynamics
SSD storage is hardening as the default persistence layer over traditional spinning disk in enterprise data warehouse deployments, cutting query latency by orders of magnitude while raising capital intensity and compressing refresh cycles across financial services and healthcare verticals.
Growth Catalysts
- EU AI Act documentation mandates:The regulation imposes auditability requirements on automated decision systems that feed from warehouse layers, compelling enterprises to replace legacy platforms with lineage-native architectures.
- Healthcare interoperability:HIPAA data portability rules in the United States enforce access controls and audit trails, driving hospital systems toward cloud-based warehouse consolidation.
- India's digital banking push:RBI mandates and BIS cloud standards are accelerating domestic data center buildouts for financial institutions requiring localized analytics infrastructure.
Market Restraints
- Flash memory supply concentration:NAND fabrication capacity concentrates in South Korea and Taiwan, exposing warehouse appliance vendors to input cost volatility and geopolitical disruption risk.
- Data sovereignty fragmentation:Cross-border transfer restrictions under GDPR, China's data security law, and India's localization mandates fragment architecture design and inflate compliance overhead.
- Legacy appliance stranded assets:On-premise MPP database installations face accelerated depreciation as cloud migration timelines compress, freezing capital recovery for mid-market enterprises.
Strategic Opportunities
- Brazilian financial modernization:Open banking regulations under the country's central bank are creating greenfield demand for real-time analytics infrastructure among tier-2 institutions.
- Edge-to-cloud federated query:Convergence of 5G low-latency networking with warehouse query federation protocols enables distributed analytics across manufacturing plant floors and central repositories.
- Saudi Vision 2030 data localization:SFDA healthcare digitization and central bank fintech licensing are mandating sovereign cloud deployments with embedded warehouse layers.
Industry Challenges
- Distributed systems engineering scarcity:Talent pipelines for Kubernetes-orchestrated, multi-tenant warehouse operations remain shallow relative to deployment demand.
- Cross-platform lineage reconciliation:Enterprises struggle to maintain consistent metadata catalogs across hybrid environments spanning Snowflake, Databricks, and on-premise appliances.
- Real-time inference latency budgets:Fraud detection workloads in banking require sub-100-millisecond query response, forcing expensive architectural overhauls of batch-optimized legacy stacks.
Report Scope
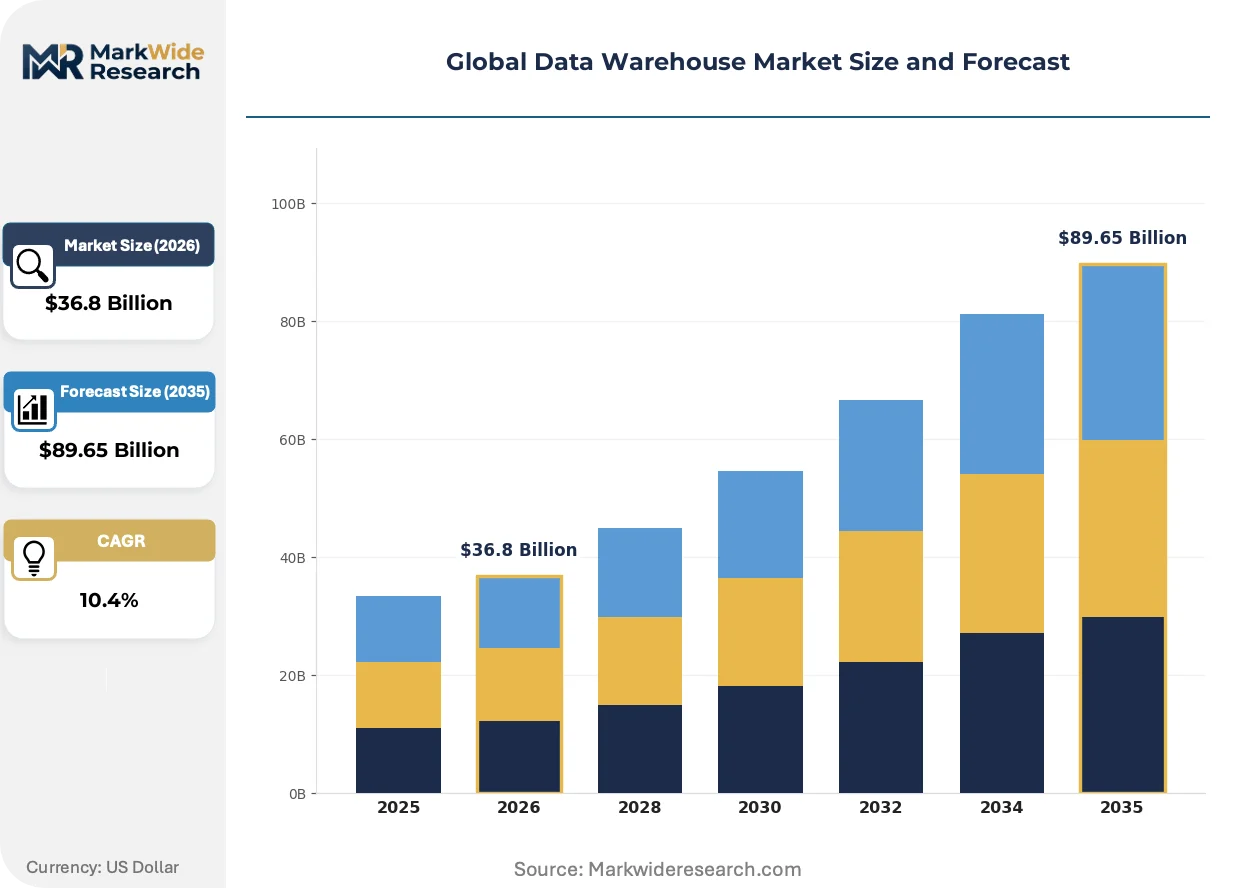
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Warehouse Market |
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $89.65 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
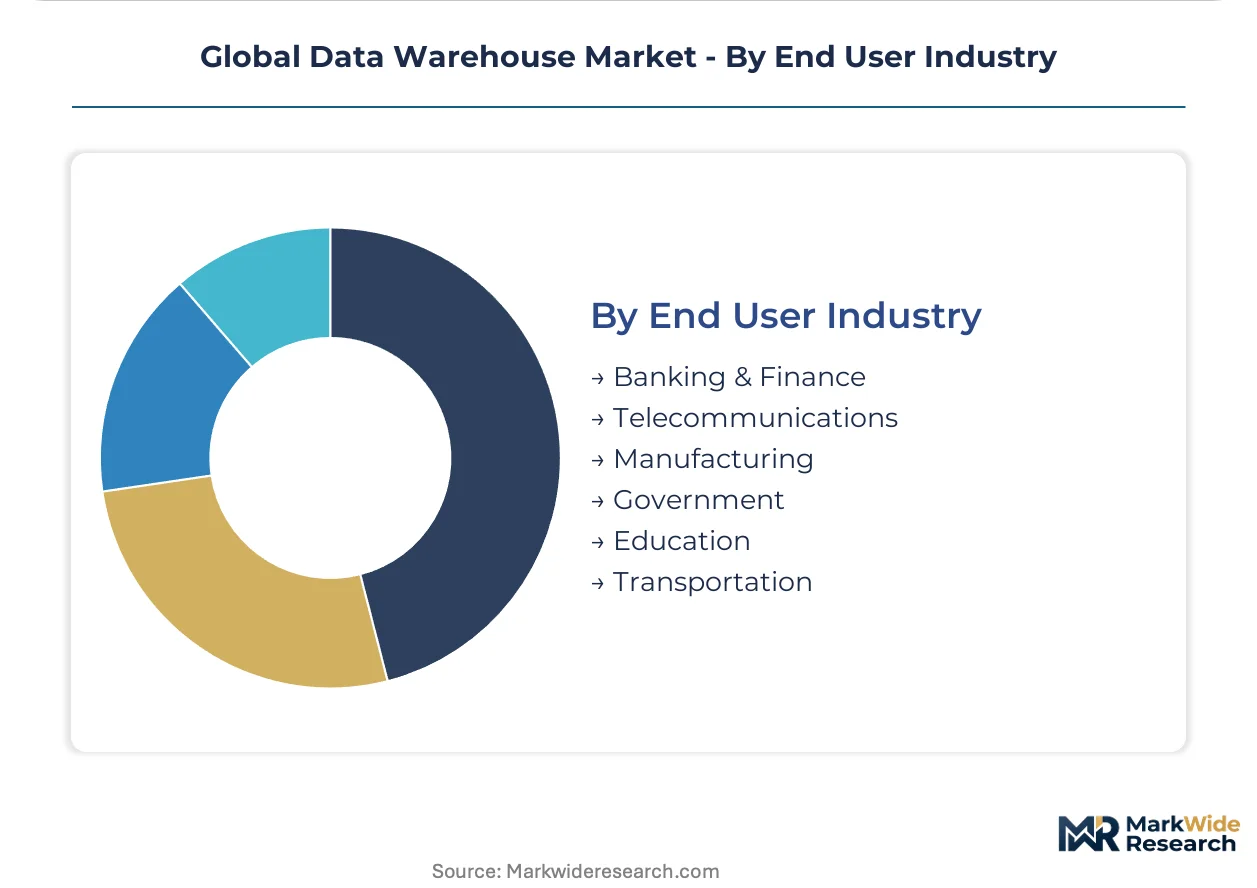
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services Solution/Offering: Data Integration, Data Governance, Analytics & Reporting, Data Storage, Data Security, Metadata Management Application: Customer Insights, Fraud Detection, Supply Chain Optimization, Risk Management, Sales Performance, Market Analysis End User Industry: Banking & Finance, Telecommunications, Manufacturing, Government, Education, Transportation |
| Companies Covered | Snowflake Inc., Amazon Web Services, Google Cloud Platform, Microsoft Corporation, Teradata Corporation, Oracle Corporation, SAP SE, IBM Corporation, Databricks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Warehouse Market Shifts & Advancements
Query execution architectures are fragmenting across storage-compute separation, regulatory-native design, and consumption-based commercial models, each trend carrying distinct implications for vendor R&D allocation and buyer procurement patterns.
Columnar storage formats optimized for object stores are rewriting the economics of petabyte-scale analytics. Financial services firms in Singapore and London are migrating historical trade data to Apache Iceberg and Delta Lake implementations, collapsing the cost curve for regulatory reporting while compressing time-to-insight from hours to minutes.
The EU AI Act's risk-based classification system is forcing warehouse vendors to embed model provenance and bias audit trails at the storage layer. Healthcare and credit scoring applications across Germany and France now require immutable lineage logs, driving premium pricing for governance-integrated platforms and disqualifying stripped-down alternatives from sensitive use cases.
Consumption-based pricing is displacing capacity reservations as the dominant procurement model. Mid-market retailers in Australia and Southeast Asia are abandoning three-year appliance leases for on-demand query credits, shifting vendor revenue recognition from upfront hardware to recurring usage metrics and compressing sales cycle timelines.
Global Data Warehouse Market Segmentation
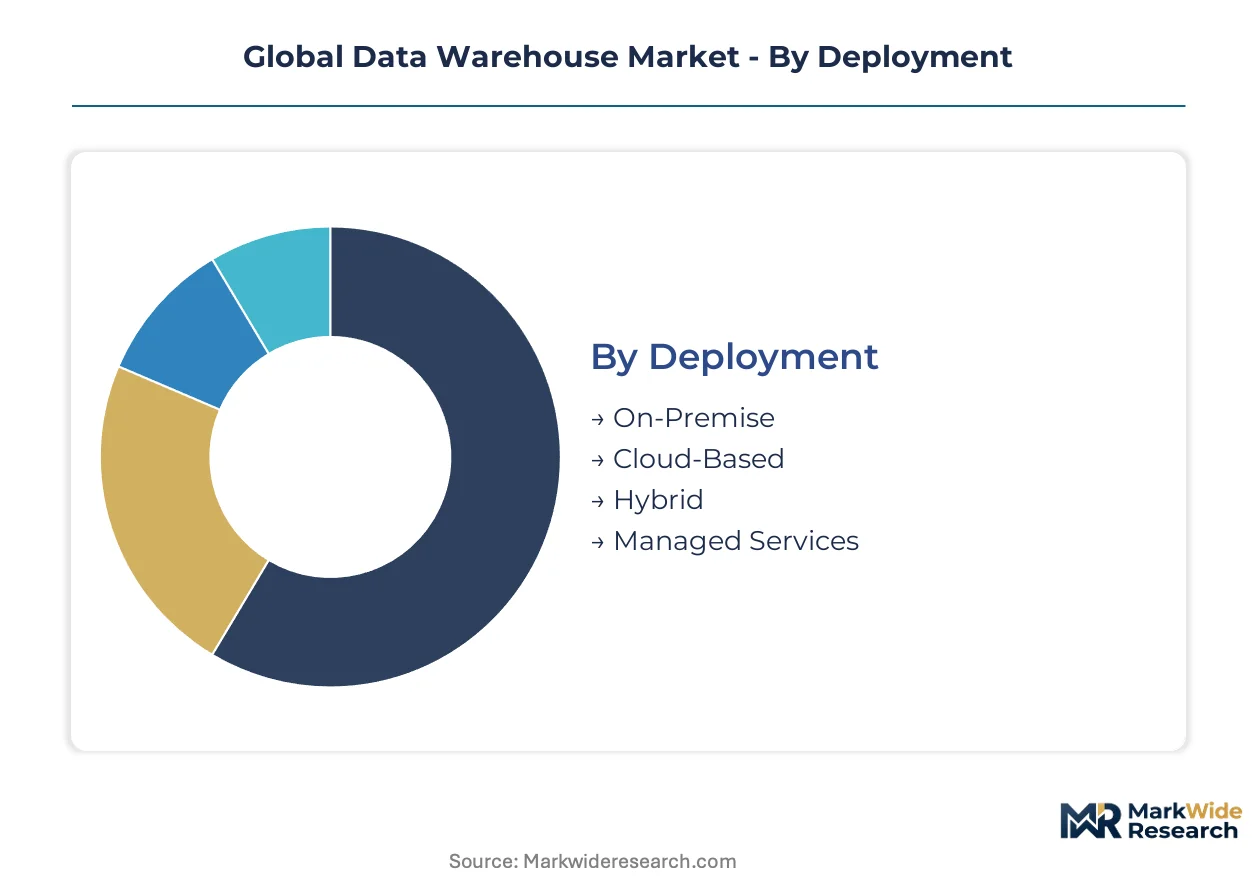
Data warehouse procurement patterns diverge sharply across deployment models, solution layers, and industry verticals. Buyers optimize for sovereignty requirements, latency budgets, and regulatory exposure rather than raw performance metrics alone.
Deployment:
Standardization dominates at the infrastructure layer, though sovereignty mandates force customization at the policy tier.
- Cloud-Based:Separated storage-compute architectures dominate new capacity additions. Financial services firms in Singapore and healthcare systems in Germany are retiring on-premise appliances for consumption-priced platforms that satisfy GDPR localization requirements.
- Hybrid:Split workloads across sovereign on-premise nodes and burst capacity to hyperscale regions. Manufacturers in Japan and government agencies in Australia favor this model for sensitive operational data that cannot exit national boundaries.
- On-Premise:Legacy MPP installations persist where data residency is non-negotiable. Defense contractors and central banks maintain captive infrastructure despite higher total cost of ownership.
- Managed Services:Third-party operations of customer-controlled hardware. Mid-market retailers in Brazil and Southeast Asia adopt this to access specialist talent without building internal platform teams.
Leading the category by volume: Cloud-Based. Growing fastest: Hybrid.
Solution/Offering:
Cost tier stratification separates commodity storage from premium governance layers commanding three to five multiple pricing.
- Data Governance:Embedded lineage tracking and policy enforcement engines. EU AI Act documentation mandates and HIPAA audit trail requirements in the United States are concentrating demand among healthcare and credit scoring applications.
- Analytics & Reporting:Visualization and query interfaces consuming the largest professional services spend. Banking regulators in India and the United Kingdom are mandating real-time regulatory reporting that drives platform refreshes.
- Data Integration:ETL and streaming pipeline orchestration. Manufacturing firms in Germany unify plant floor SCADA with enterprise ERP through these tools.
- Data Storage:Columnar persistence layers optimized for object stores. Historical trade data migration in London and Singapore is collapsing cost curves for petabyte-scale retention.
- Data Security:Encryption, masking, and access control modules. Mandatory for SFDA healthcare digitization in Saudi Arabia and RBI-mandated financial infrastructure in India.
- Metadata Management:Catalog and discovery services. Enterprises struggle to maintain consistency across Snowflake, Databricks, and legacy appliance environments.
Data Governance claims the steepest expansion trajectory. Data Storage leads by installed base.
Application:
Volume concentrates in descriptive analytics while margin migrates toward real-time inference workloads.
- Fraud Detection:Sub-100-millisecond query response requirements force architectural overhauls of batch-optimized stacks. Tier-1 banks in the United States and United Kingdom are replacing decade-old platforms.
- Customer Insights:Unified profiling across fragmented operational systems. Telecommunications operators in India and Brazil consolidate subscriber data for churn prediction and upsell targeting.
- Risk Management:Counterparty exposure and stress testing analytics. Basel III compliance deadlines in the European Union and Singapore are accelerating procurement cycles.
- Supply Chain Optimization:Demand forecasting and inventory positioning. Consumer goods manufacturers in Germany and Japan integrate warehouse data with external weather and shipping feeds.
- Sales Performance:Territory and quota management dashboards. Pharmaceutical field forces in the United States and Switzerland rely on these for incentive compensation.
- Market Analysis:External data fusion for trading and strategy. Hedge funds in London and New York consume alternative data through warehouse-native query interfaces.
Customer Insights leads by deployment count. Fraud Detection is climbing the fastest.
End User Industry:
Maturity gaps separate regulated verticals with mandatory refresh cycles from lagging adopters running depreciated platforms.
- Banking & Finance:Largest absolute spend with strictest latency and sovereignty requirements. RBI digital banking mandates in India and open banking regulations in Brazil are creating greenfield demand among tier-2 institutions.
- Telecommunications:Subscriber data unification for 5G network optimization and personalized marketing. Operators in South Korea and the United Arab Emirates lead deployment sophistication.
- Government:Tax, census, and benefits administration platforms. Data localization laws in China and Saudi Arabia are mandating sovereign cloud buildouts.
- Manufacturing:Edge-to-cloud federated query for predictive maintenance. Automotive suppliers in Germany and electronics assemblers in Taiwan connect plant floor systems to central repositories.
- Transportation:Fleet optimization and route planning. Airlines in the United States and logistics operators in the Netherlands consolidate operational and customer data.
- Education:Student information systems and research data management. Universities in Australia and Canada are migrating from on-premise legacy databases.
Banking & Finance dominates by revenue contribution. Telecommunications is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services digitization and sovereign data mandates concentrate demand across five national markets, each exhibiting distinct procurement patterns shaped by regulatory deadlines and domestic cloud infrastructure buildouts.
United States
Healthcare interoperability mandates and real-time fraud detection workloads drive platform refreshes among tier-1 banks and hospital systems. HIPAA audit trail requirements enforce access controls that cloud-native warehouses satisfy more readily than legacy on-premise appliances. The New York and San Francisco metropolitan corridors host the densest concentration of fintech and healthtech deployments.
Germany
Industrial manufacturers unify plant floor SCADA with enterprise ERP through hybrid warehouse architectures. The EU AI Act's risk-based classification system forces embedding of model provenance at the storage layer, disqualifying stripped-down alternatives from credit scoring use cases. Frankfurt and Munich anchor the country's financial and automotive data center clusters.
India
RBI digital banking mandates and BIS cloud standards accelerate domestic data center buildouts for tier-2 financial institutions. The country's national pharmaceutical regulator enforces data localization for clinical trial repositories. Mumbai and Bangalore concentrate fintech and IT services procurement activity.
Singapore
Basel III compliance deadlines and real-time regulatory reporting requirements compress procurement cycles among trading houses and private banks. The Monetary Authority of Singapore's technology risk management guidelines prescribe auditability standards for automated decision systems. The Marina Bay financial district hosts the densest warehouse deployment cluster in Southeast Asia.
Saudi Arabia
SFDA healthcare digitization and central bank fintech licensing mandate sovereign cloud deployments with embedded warehouse layers. Vision 2030 localization requirements prohibit cross-border analytics for sensitive government and financial datasets. Riyadh and the Eastern Province concentrate public sector and energy sector buildouts.
Global Data Warehouse Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers commanding volume while pure-play analytics vendors capture premium pricing for governance-integrated platforms. The vendor base organizes into three tiers: infrastructure-anchored hyperscalers, storage-compute separation specialists, and legacy appliance incumbents defending installed bases. Dominant competitive moves include strategic partnerships between cloud platforms and regional system integrators, plus portfolio diversification into adjacent data governance and AI/ML tooling.
Within the storage-compute separation tier, Snowflake Inc. exemplifies the consumption-priced model displacing capacity reservations among mid-market adopters. Amazon Web Services anchors infrastructure-anchored competition through Redshift and adjacent analytics services. Microsoft Corporation occupies a hybrid-deployment position by extending on-premises SQL Server functionality into Azure environments.
| Leading Market Players |
|---|
| Snowflake Inc. |
| Amazon Web Services |
| Google Cloud Platform |
| Microsoft Corporation |
| Teradata Corporation |
| Oracle Corporation |
| SAP SE |
| IBM Corporation |
| Databricks |
| Others |
Supply & Pricing Matrix
Consumption-based procurement mandates from mid-market retailers in Australia and Southeast Asia are forcing NAND flash vendors to abandon long-term capacity reservations, compressing margin visibility and accelerating spot-market exposure for warehouse appliance manufacturers.
Pricing Analysis
Volume concentrates in consumption-priced cloud platforms while margin migrates toward governance-integrated tiers. Three-tier pricing structure across premium lineage-native, standard analytics, and economy storage tiers separates EU AI Act-compliant deployments from stripped-down alternatives. Pricing pressure stems from hyperscale cloud providers absorbing infrastructure costs to capture enterprise workloads. Mid-market retailers exhibit highest price sensitivity; tier-1 banks in the United States and United Kingdom show lowest, prioritizing sub-100-millisecond latency over unit cost.
Supply Chain Analysis
NAND flash supply rests on fabrication capacity concentrated in South Korea and Taiwan, with controller silicon sourcing from United States and Chinese semiconductor foundries. Raw material dependencies span high-purity silicon wafers, rare earth elements for solid-state storage, and specialized epoxy resins for packaging. Single-source vulnerability in advanced node lithography equipment exposes vendors to geopolitical disruption risk. Distribution runs through hyperscale cloud marketplaces and regional system integrators serving sovereign deployment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU AI Act documentation mandates is forcing lineage-naive vendors toward distressed exits, creating acquisition opportunities for governance-native platforms.
For Market Incumbents: Hedge against margin erosion in commodity storage tiers by embedding model provenance and bias audit trails at the persistence layer, disqualifying stripped-down competitors from healthcare and credit scoring use cases. Acquire Kubernetes-orchestrated operations talent in India and Singapore to address distributed systems engineering scarcity.
For New Entrants and Emerging Players: Capture greenfield demand among tier-2 Brazilian financial institutions modernizing under central bank open banking regulations, where real-time analytics infrastructure lacks entrenched incumbents. Lead with edge-to-cloud federated query capabilities targeting German automotive suppliers unifying plant floor SCADA with enterprise ERP.
For Investors and Strategic Acquirers: The window for entry favors storage-compute separation specialists with native governance integration and established hyperscale marketplace distribution. Long-term viability hinges on lineage-native architecture as EU AI Act risk classifications harden. Watch RBI digital banking mandate enforcement velocity as inflection indicator for Indian domestic data center buildout pace.
| Strategic Initiative | Industry Significance |
|---|---|
| Storage-Compute Separation | Snowflake's consumption model displaces capacity reservations among mid-market adopters in Australia. |
| Lineage-Native Architecture | Embedded model provenance satisfies EU AI Act documentation mandates for German credit scoring applications. |
| Sovereign Cloud Partnership | Regional system integrators in Saudi Arabia and India satisfy Vision 2030 and RBI data localization requirements. |
| Edge-to-Cloud Federation | 5G low-latency networking enables distributed analytics across Japanese manufacturing plant floors. |
| Consumption Pricing Transition | On-demand query credits compress sales cycles for Southeast Asian retailers abandoning appliance leases. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and regulatory mandate databases formed the secondary backbone, cross-referenced with primary interviews across CTOs, IT procurement officers, platform engineers, and channel partners specializing in analytics infrastructure. Bottom-up and top-down triangulation validated deployment counts and pricing trajectories across cloud, hybrid, on-premise, and managed service delivery models.
Bottom-up sizing aggregated individual vendor revenue disclosures and capacity expansion announcements, while top-down demand modeling traced regulatory deadline impacts across banking, healthcare, and government verticals. Segmentation dimensions spanned deployment model, solution layer, application workload, and end-user industry, with CAGRs derived from regression analysis against historical platform replacement cycles and sovereign cloud buildout timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NAND flash supply disruption, cross-border data transfer restriction expansion, and hyperscale pricing warfare. Forecasts reflect documented assumptions regarding regulatory enforcement velocity and enterprise cloud migration pace. A small set of named triggers—EU AI Act audit penalty severity, RBI mandate compliance deadlines, and South Korean-Taiwanese geopolitical stability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Network Virtualization Software Market
Data Center and Networking
New Zealand Data Center Networking Market
Data Center and Networking
Global WAN Optimization Market
Data Center and Networking
Global Heterogeneous Network Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Global Managed SD-WAN Service Market
Data Center and Networking
Communications Service Provider (CSP) Network Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
Global Virtual Network Functions Market
Data Center and Networking
United States Data Center Networking Market
Data Center and Networking
US Dark Fiber Network Market
Data Center and Networking
Vietnam Data Center Networking Market
Data Center and Networking
Cache Server Market
Data Center and Networking
Wide Area Network Optimization Market
Data Center and Networking
Global Scalable Software Defined Networking Market
Data Center and Networking
Broadband Network Gateway Market