
 Service Provider Router Market | 2026-2036
Service Provider Router Market Size, Share, and Industry Trends Forecast 2026-2036
Service Provider Router Market Outlook
Direct procurement between semiconductor foundries and tier-one network equipment vendors is narrowing as custom ASIC development costs climb. Cisco Systems leverages its Silicon One architecture to sustain merchant-silicon independence while controlling supply chain risk. Huawei anchors massive domestic deployment scale across China's state-backed 5G buildouts, though geopolitical restrictions limit its channel reach in Western markets. Juniper Networks differentiates through cloud-native routing software that competes against vertically integrated hardware stacks.
Service provider routers are high-capability packet-forwarding systems built around specialized network processors, terabit-scale switch fabrics, and programmable forwarding pipelines operating at 400G/800G port densities. These systems direct IP traffic across autonomous system boundaries, peering exchanges, and metro aggregation rings that form the internet's physical backbone. Edge routers handling subscriber-facing MPLS and VPN termination represent the fastest-expanding segment as operators disaggregate access functions from centralized core platforms. Core routers maintain mature but critical positions in long-haul fiber backbones where margin pools concentrate among vendors with in-house silicon design. Cloud-based and virtualized deployment models are gaining structural share as network functions virtualization reduces dependence on purpose-built hardware chassis.
FCC open internet rules and EU GDPR data sovereignty requirements shape how carriers architect traffic inspection and lawful intercept capabilities into router platforms. ETSI network function virtualization standards and IEEE 802.3 Ethernet speed grades govern interoperability benchmarks that vendors must satisfy for procurement eligibility. Stakeholders must monitor how open-source routing stacks and merchant silicon from Broadcom and Marvell reshape vendor moats previously built on proprietary forwarding ASICs.

Market Dynamics
Merchant silicon from Broadcom and Marvell is collapsing the proprietary ASIC moats that once defined vendor differentiation, forcing incumbents to compete on software velocity rather than hardware exclusivity.
Growth Catalysts
- ETSI NFV Standards:European carriers are mandating disaggregated routing functions, accelerating procurement of white-box hardware running containerized control planes.
- 5G Backhaul Buildouts:Indian telecom operators under the BharatNet initiative are deploying terabit-scale core routers to support fiber-to-the-tower densification.
- Silicon Photonics Integration:Co-packaged optics at 800G port densities are reducing power-per-bit costs for hyperscale peering exchanges.
Market Restraints
- Custom ASIC NRE Costs:Tape-out expenses for 3nm network processors now exceed viable payback periods for sub-$500M product lines.
- Foundry Concentration:Taiwan-based advanced-node capacity constraints are extending lead times for merchant switch silicon by 40-60 weeks.
- Optical Component Scarcity:Coherent DSP supply from vertically integrated photonics vendors remains captive to internal chassis production.
Strategic Opportunities
- Indonesia National Broadband:Palapa Ring backbone expansion creates demand for 400G edge aggregation platforms in secondary metro markets.
- AI Training Cluster Interconnect:Hyperscale data centers are procuring terabit routers for east-west traffic between GPU racks.
- Open RAN Transport Convergence:Fronthaul gateway functions are merging into cell site routers, consolidating two hardware categories.
Industry Challenges
- Segment Routing Skill Gaps:Carrier engineering teams lack proficiency in SRv6 policy engineering, slowing production rollouts.
- Legacy MPLS Migration:Brownfield core networks require five-to-seven year depreciation cycles before SDN controller overlay deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Provider Router Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
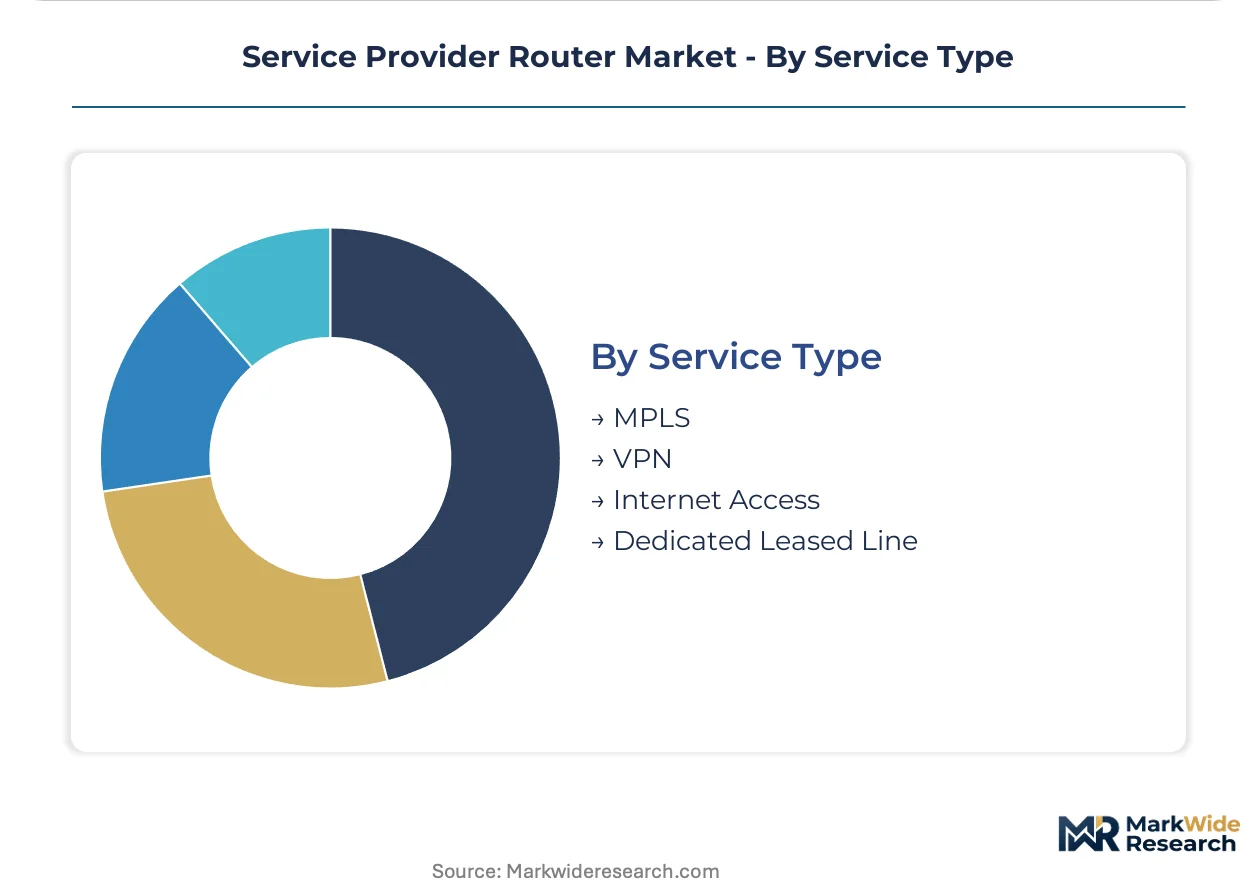
| Segmentation | Product Type: Multi-service Routers, Edge Routers, Core Routers, Aggregation Routers Deployment Model: Cloud-based, On-premises, Hybrid, Virtualized End User: Telecom Operators, ISPs, Enterprises, Government Agencies Service Type: MPLS, VPN, Internet Access, Dedicated Leased Line |
| Companies Covered | Cisco Systems, Huawei Technologies, Juniper Networks, Nokia, ZTE Corporation, Ciena Corporation, ADTRAN, Infinera Corporation, Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Provider Router Market Strategic Shifts
Routing architecture is bifurcating between cloud-native control planes and purpose-built forwarding silicon, with software-defined automation becoming the primary procurement criterion over port density specifications.
Co-packaged optics is collapsing the pluggable transceiver supply chain into router ASIC substrates, eliminating the optical component ecosystem that has dominated interconnect economics for two decades. Tier-one cloud operators are now qualifying chassis with embedded silicon photonics at 51.2T switch capacity. This compression is eroding margins for standalone optical module vendors and rewiring supplier relationships toward foundry-direct silicon sourcing.
EU CSRD disclosure mandates are forcing European carriers to document embodied carbon in network equipment procurement decisions, favoring vendors with verified supply chain emissions data. The regulation is reshaping RFP scoring matrices to weight sustainability metrics alongside technical performance. Equipment vendors without Scope 3 visibility are losing qualified status in German and French backbone upgrade tenders.
Hyperscale buyers are consolidating routing procurement under direct-to-foundry silicon sourcing agreements, bypassing traditional OEM channel structures. Cloud operators with internal switching teams are now qualifying merchant silicon reference designs through ODM partners. This disintermediation is most advanced in North American and Chinese markets where single-tenant network scale justifies custom hardware development.
Service Provider Router Market Segmentation

Service provider router procurement decisions hinge on deployment scale, traffic engineering complexity, and operational staffing models. Vendors structure product portfolios around distinct hardware-software boundaries that reshape competitive positioning across carrier, cloud, and enterprise verticals.
Product Type:
After-sales-service intensity varies sharply across router categories, with edge platforms requiring frequent software patches and core systems demanding specialized field engineering for chassis maintenance.
- Multi-service Routers:Unified platforms combine subscriber management, policy enforcement, and traffic engineering in single chassis designs. Indian telecom operators under BharatNet specifications prioritize these systems for rural aggregation nodes where technician dispatch costs constrain operational budgets.
- Edge Routers:High-port-density systems terminate subscriber-facing MPLS and VPN circuits at metro aggregation layers. Southeast Asian markets including Indonesia and Vietnam concentrate procurement here as fiber-to-the-home rollouts accelerate access layer densification.
- Core Routers:Terabit-scale forwarding engines direct inter-autonomous-system traffic across long-haul fiber backbones.
- Aggregation Routers:Mid-range platforms consolidate cell site backhaul and business Ethernet handoffs at regional PoPs.
By volume, Edge Routers lead carrier procurement cycles. By growth pace, Multi-service Routers are expanding most quickly as operators consolidate operational functions.
Deployment Model:
Cost tier separation between fully managed appliances and disaggregated software licenses determines total cost of ownership calculations across procurement evaluations.
- Cloud-based:Control plane functions run as containerized workloads on hyperscale infrastructure, separating forwarding hardware from routing intelligence. European carriers subject to ETSI NFV mandates accelerate adoption here, though latency-sensitive applications constrain migration scope.
- On-premises:Traditional chassis-based deployments retain dominance where data sovereignty requirements or submarine cable landing station constraints prohibit off-premise control plane hosting.
- Hybrid:Split architectures locate forwarding silicon at edge PoPs while centralizing policy engines in cloud regions.
- Virtualized:White-box hardware running third-party network operating systems gains traction among cable operators seeking vendor diversification.
By volume, On-premises retains installed base dominance. By growth pace, Cloud-based deployments are gaining share fastest as hyperscale peering exchange operators rearchitect interconnection fabrics.
End User:
Customer type segmentation reveals divergent procurement authority structures, with telecom operators maintaining centralized network planning teams while enterprise buyers delegate to systems integrators.
- Telecom Operators:Tier-one carriers with autonomous system numbers drive merchant silicon qualification programs and custom ASIC co-development agreements. India's Reliance Jio and Bharti Airtel anchor volume demand through national 5G backhaul buildouts.
- ISPs:Regional broadband providers prioritize cost-optimized platforms for residential aggregation, often sourcing through distributor channels rather than direct OEM relationships.
- Enterprises:Financial services and cloud-native firms procure SD-WAN edge platforms for hybrid cloud connectivity.
- Government Agencies:Defense and critical infrastructure operators mandate TEMPEST-certified or domestic-sourced silicon variants with restricted supply chain visibility.
By volume, Telecom Operators command procurement scale. By growth pace, Enterprises are climbing the fastest as SD-WAN refresh cycles displace legacy branch routing hardware.
Service Type:
Application-specific traffic engineering requirements shape forwarding pipeline design, with latency-sensitive services demanding deterministic path computation capabilities.
- MPLS:Label-switched path technologies retain dominance in enterprise VPN services despite segment routing migration roadmaps. Brownfield core networks in Germany and France require five-to-seven year depreciation cycles before controller-based overlay deployment.
- VPN:IPsec and SSL termination functions concentrate at network edges where subscriber privacy regulations including GDPR mandate traffic inspection capabilities.
- Internet Access:Border gateway protocol peering functions scale with content delivery network expansion and streaming traffic growth.
- Dedicated Leased Line:Point-to-point Ethernet services for financial trading and industrial automation require deterministic latency guarantees.
By volume, Internet Access platforms lead port shipment counts. By growth pace, VPN services are expanding most quickly as zero-trust security architectures reshape remote access infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TRAI's BharatNet specifications anchor the dominant geography for service provider router procurement. FCC open internet rules and EU CSRD disclosure mandates shape carrier architecture decisions across secondary markets. National broadband initiatives in emerging Asian economies concentrate backbone upgrade cycles.
India
Reliance Jio and Bharti Airtel drive terabit-scale core router procurement for 5G backhaul densification. TRAI mandates interoperability standards under BharatNet rural connectivity programs. Mumbai and Bangalore host engineering centers where carriers qualify merchant silicon reference designs.
China
State-backed 5G buildouts sustain massive domestic deployment scale for backbone infrastructure. MIIT governs network equipment certification and domestic sourcing requirements. Shenzhen and Beijing concentrate vertically integrated chassis production for captive optical component supply.
Germany
Deutsche Telekom and Vodafone anchor European demand for disaggregated routing platforms under ETSI NFV mandates. EU CSRD disclosure requirements weight sustainability metrics in RFP scoring matrices. Frankfurt's peering exchange infrastructure drives 800G port density qualification programs.
United States
Hyperscale cloud operators consolidate routing procurement under direct-to-foundry silicon sourcing agreements. FCC open internet rules shape traffic inspection and lawful intercept capabilities. Northern Virginia's data center corridor hosts east-west traffic interconnect for AI training clusters.
Indonesia
Palapa Ring backbone expansion creates demand for 400G edge aggregation platforms in secondary metro markets. The national broadband initiative accelerates fiber-to-the-home rollout timelines. Jakarta and Surabaya concentrate procurement authority for regional PoP consolidation.
Service Provider Router Market Competitive Environment
Vertically integrated incumbents and merchant-silicon specialists split the market between proprietary ASIC stacks and disaggregated software platforms. The vendor base concentrates around three strategic archetypes: those with captive silicon design capabilities, those competing on cloud-native routing software velocity, and those leveraging domestic scale advantages in restricted markets. Dominant competitive moves include strategic partnerships with semiconductor foundries and portfolio diversification into co-packaged optics substrates.
Within the vertically integrated tier, Cisco Systems and Huawei Technologies exemplify divergent geographic positioning under divergent regulatory constraints. Juniper Networks occupies a position emphasizing cloud-native software differentiation against hardware-centric stacks. Nokia and ZTE Corporation sit within the scale-driven mid-tier, with ZTE's domestic Chinese base constraining Western market access. Ericsson and Ciena Corporation represent specialists converging routing with optical transport integration. Ciena Corporation and Infinera Corporation anchor the photonics-integrated chassis segment where coherent DSP supply remains strategically contested.
| Leading Market Players |
|---|
| Cisco Systems |
| Huawei Technologies |
| Juniper Networks |
| Nokia |
| ZTE Corporation |
| Ciena Corporation |
| ADTRAN |
| Infinera Corporation |
| Ericsson |
| Others |
Value Chain & Pricing Dynamics
Taiwan-based foundry concentration for 3nm network processors concentrates margin capture upstream, forcing router OEMs to absorb silicon cost volatility through chassis pricing or surrender hardware margins to merchant-silicon competitors. This structural asymmetry rewards vendors with captive ASIC design or direct foundry relationships while squeezing mid-tier suppliers dependent on Broadcom and Marvell merchant silicon.
Pricing Analysis
North American hyperscale buyers command 15-25% chassis discounts against European telecom operators due to consolidated procurement scale and direct-to-foundry silicon sourcing. Three-tier pricing structure across premium, standard, and economy levels separates cloud-optimized 800G platforms from legacy 400G core systems and white-box edge aggregation units. Pricing pressure stems from merchant silicon commoditization collapsing proprietary ASIC premiums. Regional ISPs exhibit highest price sensitivity, while tier-one cloud operators prioritize performance density over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 120 days now characterize procurement between Taiwanese foundries and North American OEMs, straining working capital for mid-tier vendors. Supply concentration rests on Taiwan for advanced-node fabrication, China for optical component assembly, and Malaysia for chassis manufacturing. Dependencies include coherent DSPs from vertically integrated photonics vendors, terabit switch fabrics, and programmable forwarding pipelines. Single-source vulnerability in Taiwan-based 3nm capacity exposes lead time extension risks. Distribution runs through direct OEM channels for tier-one carriers and distributor networks for regional ISPs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service provider router demand tracks carrier capex cycles with 5G backhaul buildouts and fiber densification programs driving the current upswing. The market exhibits recovery characteristics as deferred core network upgrades from prior periods now accelerate procurement timelines.
For Market Incumbents: Build software velocity moats through cloud-native routing stacks that decouple control plane value from merchant silicon commoditization. Incumbents should consolidate field engineering capabilities for core chassis maintenance while automating edge router deployment through zero-touch provisioning. The threat of hyperscale direct-to-foundry disintermediation demands defensive moves into co-packaged optics substrates and captive silicon design partnerships with TSMC or Samsung Foundry.
For New Entrants and Emerging Players: Pursue white-box edge aggregation opportunities in Indonesia's Palapa Ring expansion and Vietnam's fiber-to-the-home rollout where incumbent vendor relationships remain underdeveloped. New entrants should target disaggregated routing software licenses for European carriers under ETSI NFV mandates, positioning against vertically integrated hardware stacks. A channel partnership strategy with Taiwanese ODMs enables rapid hardware qualification without captive manufacturing investment.
For Investors and Strategic Acquirers: Capital is best deployed toward merchant-silicon specialists with proven Broadcom and Marvell reference design qualifications and established carrier certification pathways. Long-term viability hinges on software-defined differentiation as hardware margins compress across the projection horizon. Acquisition targets should demonstrate cloud-native routing stack maturity and hyperscale peering exchange deployments. The signal to monitor is hyperscale procurement consolidation velocity—accelerated direct-to-foundry sourcing would accelerate OEM margin erosion and trigger strategic consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-packaged Optics Integration | Embedded silicon photonics at 51.2T switch capacity eliminates pluggable transceiver supply chains for hyperscale peering exchanges. |
| Cloud-native Control Plane Development | Containerized routing software decouples vendor value from merchant silicon commoditization under ETSI NFV mandates. |
| Direct Foundry Partnership | TSMC and Samsung Foundry relationships secure advanced-node capacity allocation against 40-60 week lead time extensions. |
| Segment Routing Skill Investment | SRv6 policy engineering capabilities address carrier engineering team proficiency gaps slowing production rollouts. |
| Sustainability Certification Program | EU CSRD-compliant Scope 3 emissions documentation preserves qualified vendor status in German and French backbone tenders. |
Study Parameters
Initial hypotheses were tested against primary input from carrier network planning executives, semiconductor procurement leads at tier-one OEMs, and optical component engineering directors, then refined through secondary validation. Primary fieldwork encompassed structured interviews with hyperscale infrastructure architects, ETSI standards committee participants, and field service engineers at major router deployments. Secondary sources included SEC 10-K filings from network equipment vendors, TRAI BharatNet procurement disclosures, EU CSRD regulatory filings, IEEE 802.3 Ethernet standards documentation, and customs trade data for optical component flows. Bottom-up port shipment estimates were triangulated against top-down carrier capex allocation models.
Demand-supply balance dynamics across the analysis window were modeled through carrier capacity expansion schedules, foundry capacity allocation disclosures, and hyperscale data center buildout pipelines. Segmentation dimensions encompassed product type, deployment model, end user vertical, and service application with geographic regulatory clustering. CAGRs were derived from installed base depreciation cycles and replacement demand curves rather than extrapolated trend fitting. Industry-specific inputs included 5G backhaul densification timelines, fiber-to-the-home rollout schedules, and Open RAN transport convergence roadmaps.
Sensitivities concentrate around foundry capacity constraints, carrier capex cycle amplitude, and regulatory acceleration of disaggregated routing mandates. Forecasts reflect documented assumptions regarding merchant silicon adoption velocity and cloud-native control plane migration rates. Macroeconomic deterioration, export control expansion, or breakthrough silicon photonics cost reduction would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Global Mobile Content Delivery Network Market
Data Center and Networking
Nosql Market
Data Center and Networking
Cache Server Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
Taiwan Data Center Networking Market
Data Center and Networking
United States Data Center Networking Market
Data Center and Networking
Global Data Center and Network Third-Party Hardware Maintenance Service Market
Data Center and Networking
Austria Data Center Networking Market
Data Center and Networking
Network Optimization Services Market
Data Center and Networking
Belgium Data Center Networking Market
Data Center and Networking
Network Slicing Market
Data Center and Networking
Global Heterogeneous Network Market
Data Center and Networking
Global Data Warehouse As a Service (Dwaas) Market