
 North America Completion Equipment and Services Market | 2026-2036
North America Completion Equipment and Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Completion Equipment and Services Market Analytics
Integrated plug-and-perf bundling is repositioning how operators procure completion packages across North American shale plays. Halliburton Company leverages its vertical integration across pumping services and downhole tools to anchor long-term supply agreements in the Permian. Baker Hughes Company competes through proprietary frac fleet electrification and digital wellsite architectures. Weatherford International plc specializes in liner hanger systems and expandable completion technologies for extended-reach laterals.
Completion equipment and services encompass the hardware, fluids, and engineered services required to prepare a drilled well for hydrocarbon production, including packers rated to 15,000 psi, multi-stage fracturing tools, and cemented liner systems that isolate formations and enable controlled stimulation. The primary purpose is to maximize reservoir contact and ensure zonal isolation during hydraulic fracturing and subsequent flowback operations. Packers and completion tools command the deepest margin pools where proprietary metallurgy and seal designs create switching costs. Stimulation services generate the largest revenue footprint but face margin compression as operator capital discipline favors efficiency over raw pumping horsepower. Well testing and wireline services occupy adjacent value positions where real-time diagnostics and perforation optimization justify premium pricing.
EPA methane regulations under the Clean Air Act and BLM venting and flaring rules shape equipment specifications by mandating reduced-emission completions and pneumatic device retrofits. Texas Railroad Commission and New Mexico EMNRD state rules layer additional compliance obligations that favor service providers with certified low-emission fleets and integrated emissions monitoring. State-level groundwater protection standards and OSHA oilfield safety directives further constrain operational parameters and equipment qualification requirements. Stakeholders must monitor the pace of EPA rulemaking on orphaned well plugging standards and state-level bonding reforms that could redirect service capacity toward abandonment markets.
Market Dynamics
Integrated completion packages are compressing procurement cycles across North American shale plays as operators consolidate vendors to reduce wellsite complexity and improve multi-well pad economics. This bundling dynamic favors service providers with captive manufacturing of high-pressure packers and frac plugs.
Growth Catalysts
- EPA methane rules:Reduced-emission completion mandates under the Clean Air Act are retrofitting pneumatic devices and driving demand for certified low-emission fleets across Texas and New Mexico.
- Pad drilling density:Multi-well completion efficiency requirements in the Permian Basin are accelerating adoption of simultaneous operations and zipper frac sequencing.
- Extended-reach laterals:Liner hanger systems rated for 15,000 psi and expandable completion technologies are enabling longer horizontal sections in unconventional reservoirs.
Market Restraints
- Proppant supply concentration:Northern White sand logistics from Wisconsin and Minnesota face rail bottlenecks and regional mining permit constraints that inflate delivered costs to Permian wellsites.
- Specialized alloy scarcity:High-nickel metallurgy for sour-service packers depends on concentrated specialty steel mills with limited surge capacity during demand spikes.
- BLM venting rules:Federal land restrictions on routine flaring create compliance friction for operators on tribal and federal leases, delaying completion schedules.
Strategic Opportunities
- Orphaned well plugging:State-level bonding reforms in Texas and New Mexico are redirecting service capacity toward abandonment markets and P&A tooling demand.
- Frac fleet electrification:Grid-tied and natural-gas-powered pumping equipment convergence with digital wellsite architectures reduces fuel logistics and emissions intensity.
- Real-time diagnostics:Wireline services integrating perforation optimization with live pressure monitoring command premium pricing in extended-reach laterals.
Industry Challenges
- Pressure control certification:API 6A and 11D qualification timelines for new packer seal designs extend 18-24 months, delaying product commercialization.
- Skilled frac crew scarcity:Experienced pump operators and wireline engineers command wage premiums that compress service margins during labor tightness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Completion Equipment and Services Market |
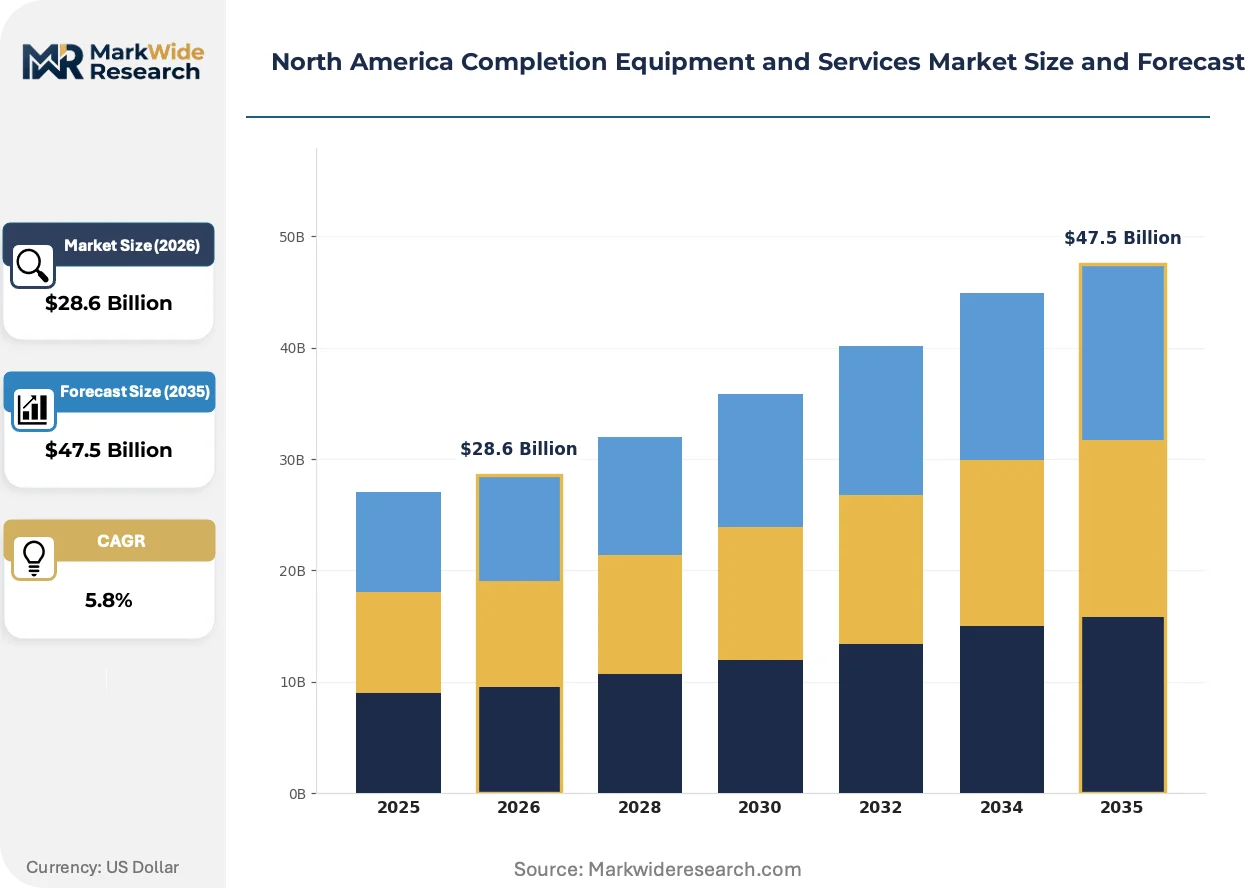
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wireline Services, Stimulation Services, Cementing Services, Well Testing Product Type: Packers, Tubing, Completion Tools, Fracturing Equipment End User: Independent Operators, National Oil Companies, Service Companies, Onshore Operators Technology: Pressure Control, Coiled Tubing, Hydraulic Fracturing, Sand Control |
| Companies Covered | Weatherford International plc, National-Oilwell Varco Inc, Halliburton Company, NCS Multistage, Packers Plus Energy Services Inc., Schlumberger Ltd., Superior Energy Services Inc., FTS International, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Completion Equipment and Services Market Evolving Landscape
Completion technology is pivoting toward emissions reduction and digital integration as regulatory pressure and operator capital discipline converge. Hardware specifications now embed monitoring capabilities previously handled by separate service lines.
Electric frac fleets powered by natural gas turbine generators or direct grid connection are electrifying pumping operations across the Permian and Eagle Ford. Operators with ESG mandates and methane reduction targets are adopting these systems fastest. This electrification is compressing diesel logistics costs and enabling real-time power load optimization through integrated SCADA.
EPA methane regulations under the Clean Air Act are mandating reduced-emission completions and pneumatic device retrofits on all new and modified wells. Equipment specifications now require certified low-emission designs for surface valves and downhole tools. Service providers in Texas and New Mexico are rebuilding inventories to meet these certified specifications ahead of enforcement deadlines.
Integrated plug-and-perf bundling is consolidating procurement decisions around single-vendor accountability for downhole tools and pumping services. Operators are displacing fragmented multi-vendor arrangements with long-term supply agreements that embed efficiency guarantees. This consolidation is most visible among Permian Basin independents optimizing multi-well pad economics.
North America Completion Equipment and Services Market Segmentation
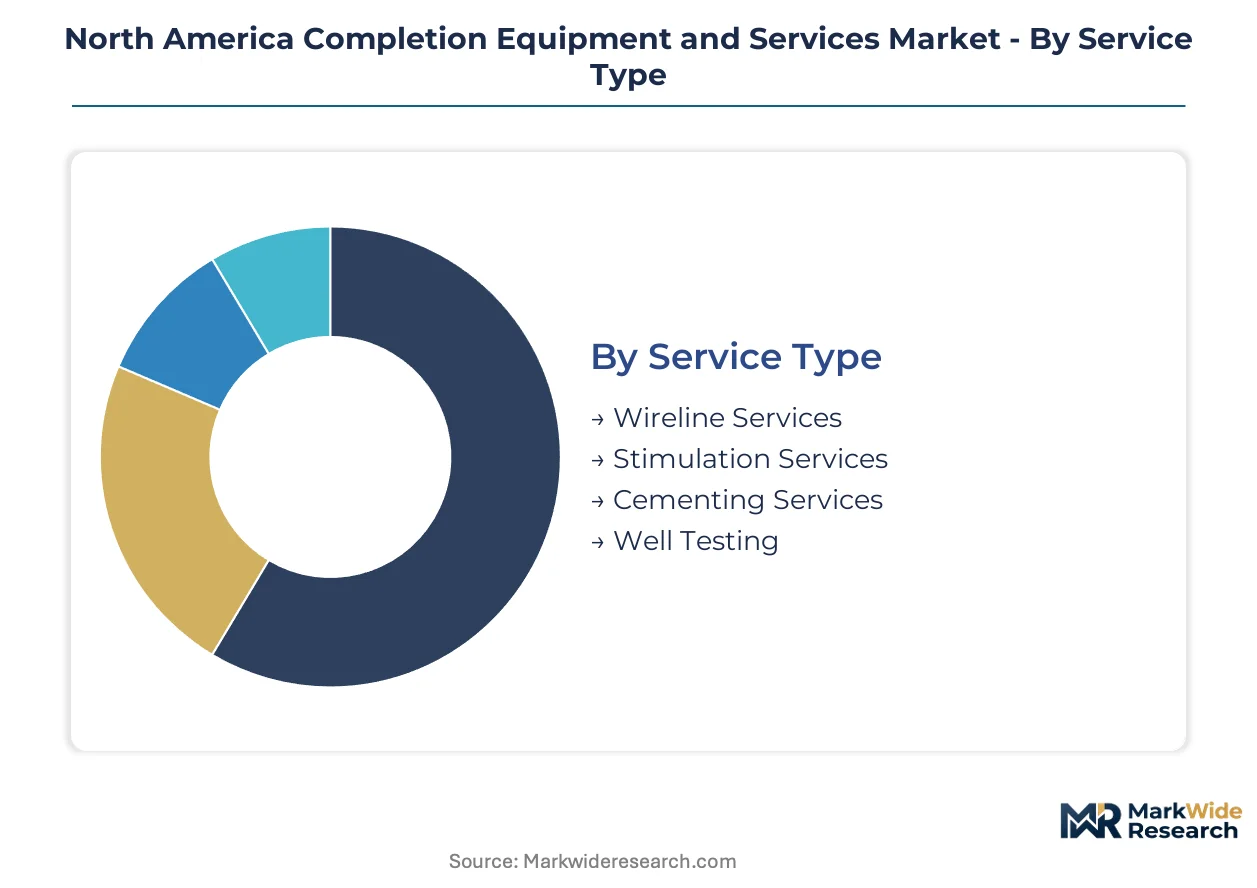
Completion equipment and services segment along four distinct axes that reshape procurement patterns and vendor relationships. Service type and product type splits dominate capital allocation decisions, while end-user configuration and technology adoption determine margin capture and upgrade cycles.
Service Type:
Replacement cycles for service equipment accelerate as EPA methane rules and extended-reach lateral complexity strain legacy fleet capabilities.
- Stimulation Services:Multi-stage hydraulic fracturing operations deploy high-pressure pumping fleets and proppant logistics coordination. Permian Basin operators favor simultaneous operations and zipper frac sequencing to compress multi-well pad timelines. Demand concentrates where pad drilling density exceeds four wells per pad and diesel-to-electric fleet conversions justify capital redeployment.
- Wireline Services:Perforation, logging, and real-time diagnostics require specialized cable units rated for 15,000 psi wellbore conditions. Extended-reach laterals in the Delaware Basin drive demand for tractor-conveyed tools and live pressure monitoring that commands premium pricing over conventional slickline alternatives.
- Cementing Services:Zonal isolation and liner cementing operations ensure formation integrity during stimulation and production phases.
- Well Testing:Flowback diagnostics and reservoir characterization services validate completion effectiveness before handover to production operations.
Stimulation services sit at the top of the volume ranking, with wireline services climbing the fastest as real-time diagnostics displace conventional perforation approaches.
Product Type:
Product selection tracks pressure rating requirements and metallurgy specifications that vary sharply between conventional and sour-service applications.
- Packers:Downhole sealing devices rated to 15,000 psi isolate formations and enable controlled stimulation through proprietary elastomer and metal-to-metal seal designs. High-nickel alloy scarcity for sour-service variants creates switching costs that favor incumbent suppliers with captive metallurgy sourcing.
- Completion Tools:Multi-stage fracturing sleeves, sliding sleeves, and frac plugs enable zonal isolation and sequential stimulation in horizontal wells. Integrated plug-and-perf bundling is compressing vendor counts as operators consolidate procurement around single-source accountability for downhole hardware.
- Tubing:Production conduit systems convey hydrocarbons from reservoir to surface with corrosion-resistant alloy options for high-CO2 environments.
- Fracturing Equipment:Surface pumping units, blenders, and hydration systems deliver proppant slurry at pressures exceeding 10,000 psi.
Packers command the deepest margin pools in this category, while completion tools gain share fastest through bundling arrangements that displace fragmented multi-vendor setups.
End User:
Customer type determines contract structure, with independents favoring spot market flexibility and integrated operators pursuing long-term supply agreements.
- Independent Operators:Privately held and publicly traded E&P companies without downstream integration dominate Permian Basin activity. Capital discipline and multi-well pad economics drive preference for integrated completion packages that reduce wellsite complexity and improve cycle time predictability.
- Onshore Operators:Dedicated unconventional-focused producers with concentrated acreage positions in Texas and New Mexico. Pad drilling density requirements accelerate adoption of simultaneous operations and certified low-emission fleets to meet state-level flaring restrictions.
- National Oil Companies:State-owned upstream entities with North American joint venture positions.
- Service Companies:Integrated oilfield service providers procuring equipment for captive service delivery.
Independent operators anchor volume in this category, with onshore operators expanding most quickly as pure-play unconventional specialists consolidate acreage.
Technology:
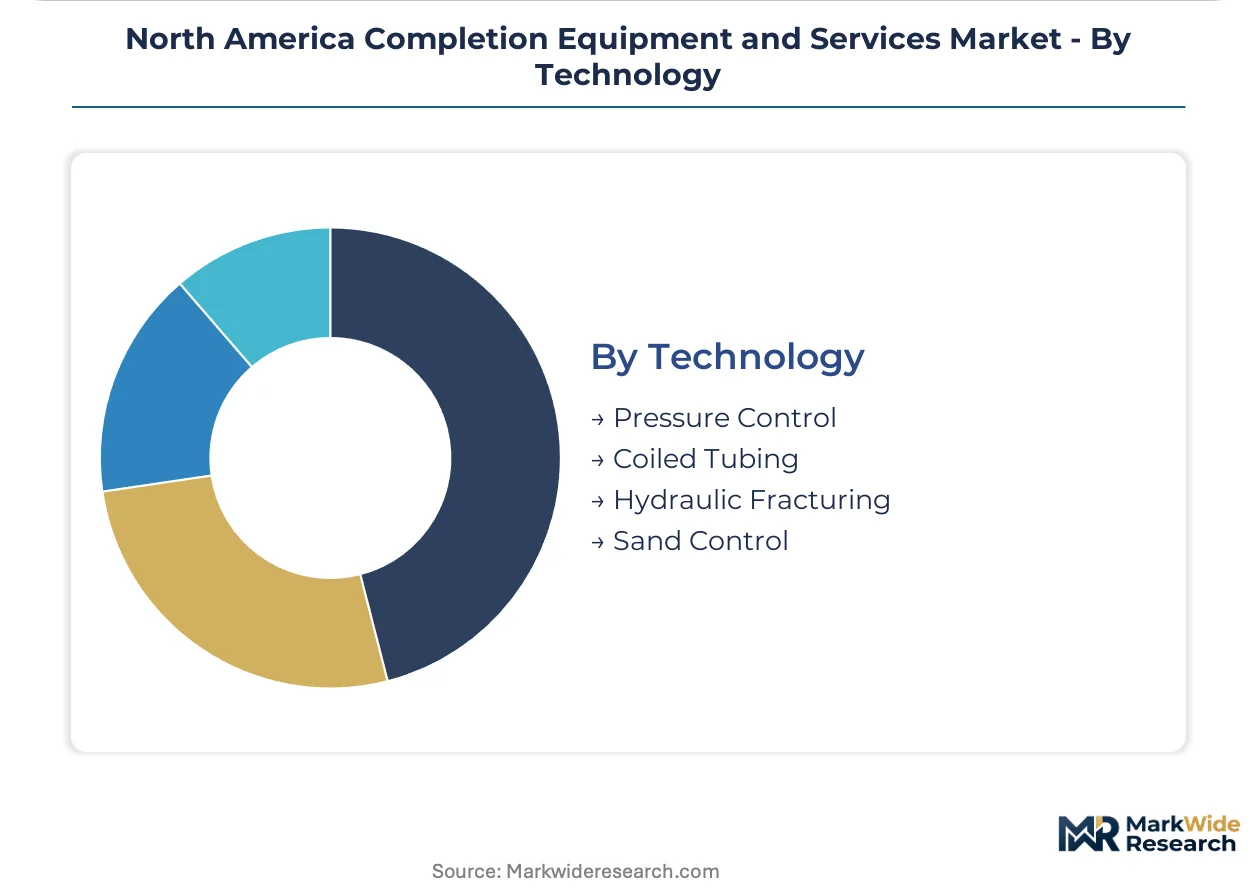
Technology adoption patterns reflect regulatory pressure and operational efficiency imperatives that favor emissions reduction and digital integration.
- Hydraulic Fracturing:Pressure-pumping technology combining high-rate fluid injection with proppant placement to create conductive fracture networks in low-permeability reservoirs. Electric frac fleet deployments powered by natural gas turbines or direct grid connection are displacing diesel units across the Permian and Eagle Ford.
- Pressure Control:Wellhead and downhole equipment systems managing annular pressure during stimulation and flowback operations. EPA reduced-emission completion mandates are retrofitting surface valve specifications and pneumatic device inventories ahead of enforcement deadlines.
- Coiled Tubing:Continuous steel conduit deployed for well intervention, cleanout, and plug milling operations.
- Sand Control:Gravel pack and screen systems preventing formation sand production in unconsolidated reservoirs.
Hydraulic fracturing holds the largest installed base, with pressure control technologies gaining traction fastest through emissions-driven equipment refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern hydraulic fracturing techniques were pioneered and scaled in the United States, with the Barnett Shale serving as the proving ground before the Permian Basin became the world's most active unconventional oilfield. This American lineage established the technical and operational templates now deployed across North American shale plays.
United States
Texas and New Mexico anchor continental activity through the Permian and Delaware Basins, where pad drilling density exceeding six wells per pad compresses completion timelines. EPA methane rules under the Clean Air Act mandate reduced-emission completions and pneumatic device retrofits, reshaping equipment specifications across the Permian. Midland-Odessa and Hobbs serve as the primary service hubs where integrated completion packages consolidate vendor relationships.
Canada
Alberta's Montney and Duvernay formations drive demand for high-pressure packers rated to 15,000 psi in sour-service conditions. The Alberta Energy Regulator and British Columbia Oil and Gas Commission impose stringent venting and fugitive emission standards that favor certified low-emission fleets. Calgary anchors the domestic service provider ecosystem, with Grande Prairie and Fort St. John forming the operational clusters for northern Montney development.
Mexico
Onshore unconventional potential in the Burgos Basin and offshore deepwater fields in the Gulf of Mexico create dual demand centers for completion services. The National Hydrocarbons Commission and ASEA environmental regulator impose offshore safety and emissions standards that align with international operator requirements. Ciudad del Carmen and Tampico serve as the primary logistics corridors for offshore completion equipment deployment.
North America Completion Equipment and Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and captive metallurgy sourcing, creating a tiered competitive structure. The vendor base clusters around integrated service providers with in-house manufacturing capabilities and specialized tool specialists with proprietary seal designs. Two archetypes dominate: vertically integrated pump-and-tool bundlers and niche specialists in high-pressure packers or expandable completion systems. Competitive moves center on long-term supply agreement anchoring and frac fleet electrification partnerships with grid operators.
Within the integrated service tier, Halliburton Company and Baker Hughes Company exemplify the bundling archetype through their combined pumping services and downhole tool manufacturing positions. Weatherford International plc occupies a specialist position in liner hanger systems and expandable technologies. These three entities represent the competitive spectrum from full vertical integration to focused component specialization.
| Leading Market Players |
|---|
| Weatherford International plc |
| National-Oilwell Varco Inc |
| Halliburton Company |
| NCS Multistage |
| Packers Plus Energy Services Inc. |
| Schlumberger Ltd. |
| Superior Energy Services Inc. |
| FTS International |
| Baker Hughes Company |
| Others |
Value Network & Pricing Analysis
Permian Basin independents with multi-well pad operations dominate procurement volume and anchor contract-based long-term offtake agreements that embed efficiency guarantees and volume commitments. This buyer concentration compresses spot market liquidity and elevates pricing power for service providers with certified low-emission fleets and captive manufacturing of high-pressure packers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates API-certified sour-service packers from conventional pressure-rated tools from reconditioned equipment. Price differentiation rests on metallurgy grade and EPA compliance certification, with high-nickel alloy scarcity widening spreads between tiers. Cost compression in standard-tier stimulation services is intensifying because operator capital discipline favors bundled efficiency over raw pumping horsepower. Independent operators exhibit highest price sensitivity, while integrated majors with ESG mandates accept premium tier premiums for electrified fleets.
Supply Chain Analysis
Regional distribution centers in Midland-Odessa and Hobbs operate hub-and-spoke patterns that position proppant and downhole tools within four-hour drive time of Permian wellsites. Manufacturing concentrates in Texas, Oklahoma, and Louisiana for pressure pumping equipment, while high-nickel metallurgy draws from specialty steel mills in Pennsylvania and Ohio. Single-source vulnerability in Northern White sand logistics from Wisconsin and Minnesota creates exposure to rail bottleneck delays. Distribution runs through company-owned service yards and third-party rental depots that stage equipment for zipper frac sequencing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America completion equipment and services market represents a late-cycle quality story where EPA methane regulations and extended-reach lateral complexity are filtering demand toward premium specifications and certified low-emission capabilities.
For Market Incumbents: Deploy captive metallurgy sourcing as the primary lever to defend margin position against specialty alloy scarcity and switching cost erosion. Incumbents should consolidate wireline service capacity in the Delaware Basin where tractor-conveyed diagnostics command premium pricing, while retrofitting legacy frac fleets to certified low-emission specifications ahead of enforcement deadlines. This dual move counters emerging electric fleet specialists and regulatory compliance fragmentation. For New Entrants and Emerging Players: Enter via orphaned well plugging service lines where state-level bonding reforms in Texas and New Mexico are redirecting capacity toward abandonment markets. The most penetrable white space sits in P&A tooling and plug-and-abandonment diagnostics for marginal well operators facing bonding threshold increases. A go-to-market angle anchored through regulatory compliance partnerships with state environmental agencies accelerates contract visibility. For Investors and Strategic Acquirers: Integrated oilfield service providers with pumping and manufacturing positions are the most active acquirer in this space, targeting specialist packer manufacturers with proprietary seal designs. Long-term viability over the next decade hinges on emissions technology integration and digital wellsite architecture capabilities. The signal to watch is the pace of electric frac fleet deployment commitments from Permian operators with stated net-zero targets.| Strategic Initiative | Industry Significance |
|---|---|
| Frac Fleet Electrification | Grid-tied and natural-gas-powered pumping equipment reduces diesel logistics costs and EPA compliance exposure. |
| Integrated Plug-and-Perf Bundling | Single-vendor accountability for downhole tools and pumping services compresses procurement cycles and wellsite complexity. |
| Orphaned Well Plugging Capacity | State bonding reforms redirect service capacity toward P&A tooling demand and abandonment market expansion. |
| Real-Time Diagnostics Integration | Wireline services embedding live pressure monitoring command premium pricing in extended-reach laterals. |
| High-Nickel Metallurgy Sourcing | Captive supply of sour-service alloys creates switching costs and defends margin pools in premium packer segments. |
Research Methodology
Direct dialogue with completion engineering directors, frac fleet operations managers, procurement leads at Permian independents, and regulatory compliance officers at state environmental agencies grounded qualitative findings. Secondary validation drew from EPA enforcement dockets, Texas Railroad Commission permitting records, SEC 10-K filings of publicly traded service providers, and EIA drilling productivity reports. Bottom-up well count and rig activity data triangulated against top-down service revenue estimates to anchor volume assumptions.
Bottom-up modeling of stimulation, wireline, and cementing service lines across the projection horizon segmented by pressure rating tier, emissions certification status, and end-user operator type. CAGRs were derived from historical rig efficiency trends and assumed pad drilling density trajectories. Industry-specific forecast inputs included zipper frac adoption rates and electric fleet conversion timelines.
The model holds under stable regulatory enforcement timelines and continued operator capital discipline; deviation in EPA rulemaking acceleration or proppant logistics disruption would shift service capacity allocation and pricing trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Global Oil Line Corrosion Inhibitors Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
Mud Balance Market
Oil & Gas
Oil Storage Terminal Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
Drilling Services Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
Geothermal Drilling Market
Oil & Gas
Global LNG Regasification Terminals Market
Oil & Gas
Oil Hose Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
Upstream Services Market
Oil & Gas
Oil and Gas Downhole Cables Market
Oil & Gas
South America Oil and Gas Storage Tank Market
Oil & Gas
United States Liner Hanger System Market