
 Oil Tank Rotating Stacker Market | 2026-2036
Oil Tank Rotating Stacker Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Tank Rotating Stacker Market Analytics
Aftermarket service revenue is fragmenting across original equipment providers and third-party refurbishment specialists. Alfa Laval leverages its heat-transfer equipment installed base to cross-sell stacker maintenance contracts. Baker Hughes Co. anchors its position through integrated digital monitoring packages for rotating machinery. Kinder Morgan competes by controlling terminal infrastructure where stacker procurement decisions concentrate.
An oil tank rotating stacker is a heavy-duty material handling machine engineered to position, lift, and transfer cylindrical storage tanks or drum containers within petroleum terminals and bulk liquid facilities, typically rated for loads exceeding 50 tons with 360-degree slewing capability via planetary gearboxes. Its primary commercial purpose centers on eliminating crane dependency during tank farm construction, maintenance turnaround cycles, and modular storage expansion projects. Automatic stacker configurations command premium positioning in high-throughput terminals where labor minimization drives ROI calculations, while hydraulic system technology retains dominance in legacy installations though electrical drive adoption accelerates among net-zero committed operators. Bulk storage terminals represent the most structurally concentrated end-user segment, with integrated terminal operators bundling stacker procurement into multi-year capex cycles tied to storage capacity expansion.
EPA enforcement of Clean Air Act standards for fugitive emissions shapes stacker specifications through sealed bearing requirements and leak detection integration points. OSHA crane-safety alternative regulations drive demand for ground-based rotating stackers in congested tank farm environments where overhead lifting creates struck-by hazards. Stakeholders must monitor evolving carbon-border adjustment mechanisms and their downstream effects on terminal construction timing.
Market Dynamics
Hydraulic-to-electric drive conversions are compressing replacement cycles across petroleum terminals as operators face simultaneous pressure from OSHA workplace safety mandates and EPA fugitive emissions enforcement. This technology shift is restructuring supplier relationships and maintenance revenue flows.
Growth Catalysts
- OSHA crane-safety alternatives:Ground-based rotating stackers eliminate struck-by hazards in congested tank farm environments where overhead lifting restrictions now apply.
- Texas and Louisiana terminal corridors:Bulk storage capacity expansion along Gulf Coast refining clusters bundles stacker procurement into multi-year capex cycles.
- Automated material handling fleets:Refinery operators deploy automatic stacker configurations to minimize labor inputs and accelerate turnaround cycle completion.
Market Restraints
- Specialized planetary gearbox supply:European and Japanese precision gear manufacturers control critical slewing drive component availability.
- High-voltage electrical infrastructure:Terminal electrification requirements impose capital burdens that delay hydraulic system replacement timelines.
- Legacy hydraulic technician pools:Skilled maintenance labor concentration in mature installations slows electric drive adoption despite regulatory pressure.
Strategic Opportunities
- Modular storage expansion projects:Tank farm construction methodologies increasingly specify rotating stackers for cylindrical tank positioning without crane dependency.
- Digital monitoring convergence:Integrated condition monitoring platforms combine vibration analysis with thermal imaging for predictive maintenance contracts.
- Carbon-border adjustment preparation:Net-zero committed terminal operators in Rotterdam and Singapore accelerate specifications for electrified equipment ahead of trade mechanism implementation.
Industry Challenges
- Sealed bearing certification timelines:EPA Clean Air Act compliance requires extended validation protocols for leak detection integration points.
- Legacy system interoperability:Electric drive retrofits must interface with existing terminal control architectures without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Tank Rotating Stacker Market |
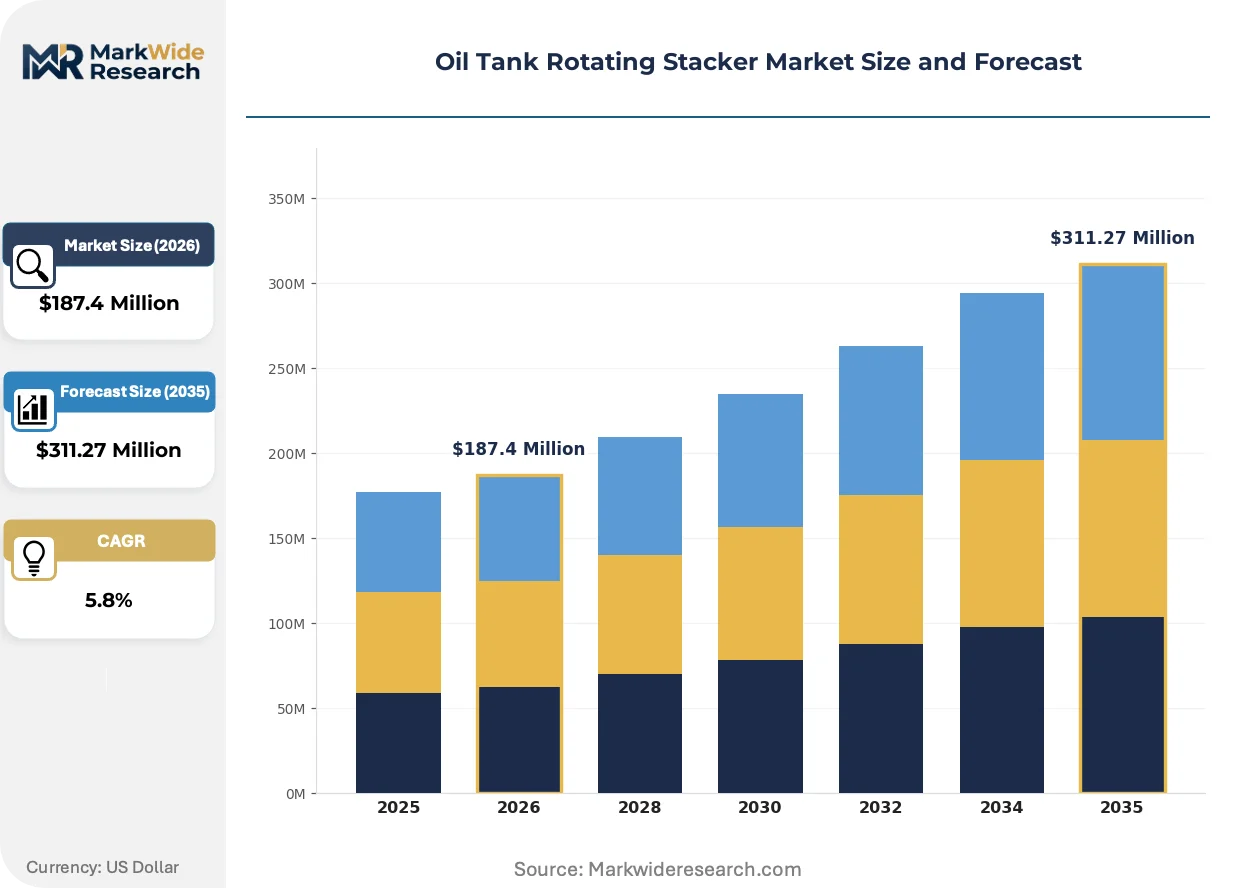
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Stacker, Manual Stacker, Semi-Automatic Stacker, Mobile Stacker End User: Oil & Gas Industry, Petrochemical Companies, Bulk Storage Terminals, Refineries Technology: Hydraulic System, Electrical Drive, Pneumatic System, Mechanical Drive Application: Loading, Unloading, Storage, Transportation |
| Companies Covered | Alfa Laval AB, Atlas Copco AB, General Electric Co, Baker Hughes Co., Pentair PLC, Kinder Morgan, Vopak, Oiltanking, Jungheinrich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Tank Rotating Stacker Market Evolving Landscape
Electrification and digitalization are converging to redefine stacker specifications, with regulatory compliance now inseparable from technology selection. Equipment buyers increasingly bundle automation and monitoring capabilities into base procurement requirements.
Permanent magnet synchronous motor technology is migrating from auxiliary systems to main hoist and slewing drives in heavy-duty stacker applications. Integrated terminal operators in the Netherlands and Singapore specify these systems for net-zero committed facilities. The shift is compressing hydraulic component aftermarket revenue while expanding electrical drive supplier margins.
EPA enforcement of Clean Air Act fugitive emissions standards shapes sealed bearing specifications and leak detection integration requirements. Terminal engineering teams must redesign lubrication systems and containment protocols. Bulk storage operators in Texas and Louisiana face the most immediate compliance timelines given inspection frequency increases.
Service contract unbundling separates refurbishment specialists from original equipment maintenance agreements. Third-party providers now compete for stacker overhaul work previously captive to installation vendors. This pattern concentrates in Gulf Coast corridors where equipment density supports independent service economies.
Oil Tank Rotating Stacker Market Segmentation
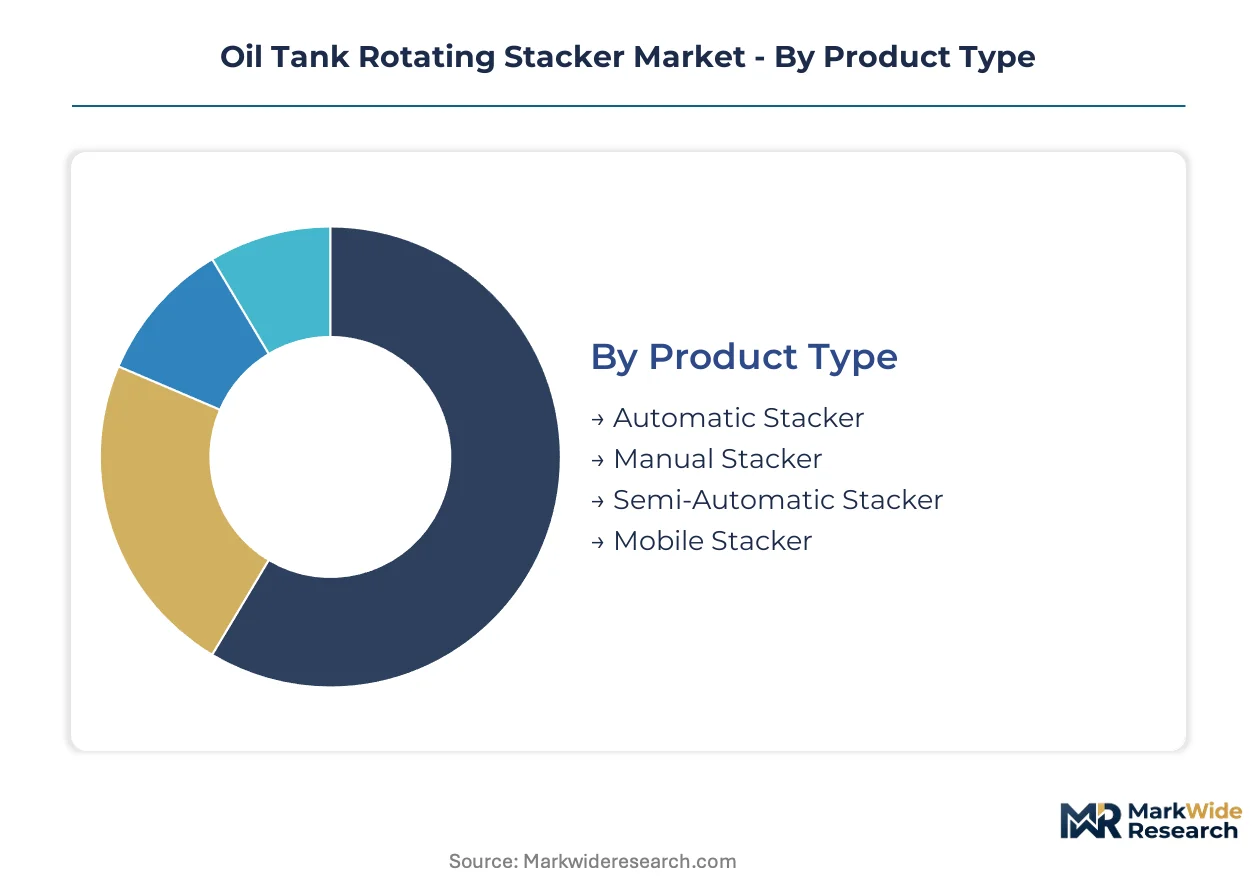
Segmentation in the oil tank rotating stacker market reveals how procurement cycles, technology refresh rates, and regulatory compliance timelines diverge across equipment configurations and operational contexts. Understanding these velocity differences enables suppliers to align inventory and service capacity with actual replacement demand.
Product Type:
Automatic stackers turn over fastest as terminal operators replace legacy units to capture labor savings, while manual configurations persist longest in low-throughput satellite facilities with constrained capex cycles.
- Automatic Stacker:These systems integrate programmable logic controllers with 360-degree slewing precision for unmanned tank positioning sequences. Demand concentrates in Texas and Louisiana terminal corridors where Kinder Morgan and integrated operators bundle automation into multi-year capacity expansions. OSHA crane-safety alternatives accelerate procurement in congested tank farms where overhead lifting restrictions eliminate traditional rigging methods.
- Manual Stacker:Operator-controlled configurations rely on direct hydraulic lever actuation without automated positioning feedback. Gulf Coast maintenance yards and secondary petroleum terminals deploy these units for intermittent turnaround support where utilization rates do not justify automation capital outlays.
- Semi-Automatic Stacker:Hybrid systems combine powered lifting with manual slew control, occupying the mid-tier for operators transitioning from hydraulic to electric drives. Refinery maintenance departments in Louisiana specify these for flexibility across varying tank diameters.
- Mobile Stacker:Self-propelled units on rubber-tired or crawler undercarriages relocate between tank farm zones without crane assistance. Modular storage expansion projects in Texas increasingly specify mobile configurations to eliminate fixed infrastructure dependencies.
Manual stackers anchor the volume base while automatic configurations gain share at the steepest rate.
End User:
Cost tier stratification separates integrated terminal operators with bundled procurement power from independent maintenance contractors purchasing on spot cycles.
- Oil & Gas Industry:Upstream exploration companies and midstream logistics providers deploy stackers for temporary storage installation at remote production sites. Bakken shale operators in North Dakota specify mobile units for rapid field assembly of cylindrical tanks.
- Petrochemical Companies:Integrated chemical manufacturers require explosion-rated stackers for tank positioning in classified hazardous zones. Texas Gulf Coast ethylene producers specify sealed bearing configurations to meet EPA fugitive emissions standards for volatile organic compound containment.
- Bulk Storage Terminals:Independent tank farm operators represent the structurally concentrated demand segment with multi-unit procurement tied to capacity expansion timelines. Louisiana terminal corridors bundle stacker acquisition into infrastructure development cycles.
- Refineries:Downstream processing facilities deploy stackers during turnaround maintenance when crude and product tanks require internal inspection or recoating. Gulf Coast refining clusters drive replacement demand as hydraulic-to-electric conversions compress technology refresh cycles.
Bulk storage terminals anchor the volume base while refinery applications expand most quickly under regulatory pressure.
Technology:
Application environment dictates drive system selection, with electrical configurations commanding premium positioning in net-zero committed facilities while hydraulic retention dominates legacy installations.
- Hydraulic System:Fluid power drives deliver high torque density for heavy tank lifting with established technician training infrastructure. Mature petroleum terminals in Louisiana maintain hydraulic fleets despite EPA emissions enforcement, constrained by high-voltage electrical infrastructure capital requirements.
- Electrical Drive:Permanent magnet synchronous motors now migrate to main hoist and slewing functions, eliminating hydraulic fluid leak paths. Rotterdam and Singapore terminal operators specify these systems for carbon-border adjustment preparation ahead of trade mechanism implementation.
- Pneumatic System:Compressed air actuation serves auxiliary functions such as brake release and locking pin engagement rather than primary lifting. Offshore platform applications favor pneumatic controls for intrinsic safety in explosive atmospheres.
- Mechanical Drive:Gear-reduction systems with electric motor prime movers occupy niche applications requiring precise positioning without hydraulic complexity. Small-diameter tank handling in specialty chemical terminals employs mechanical configurations for maintenance simplicity.
Hydraulic systems anchor the volume base while electrical drives climb the fastest as OSHA and EPA mandates accelerate replacement timelines.
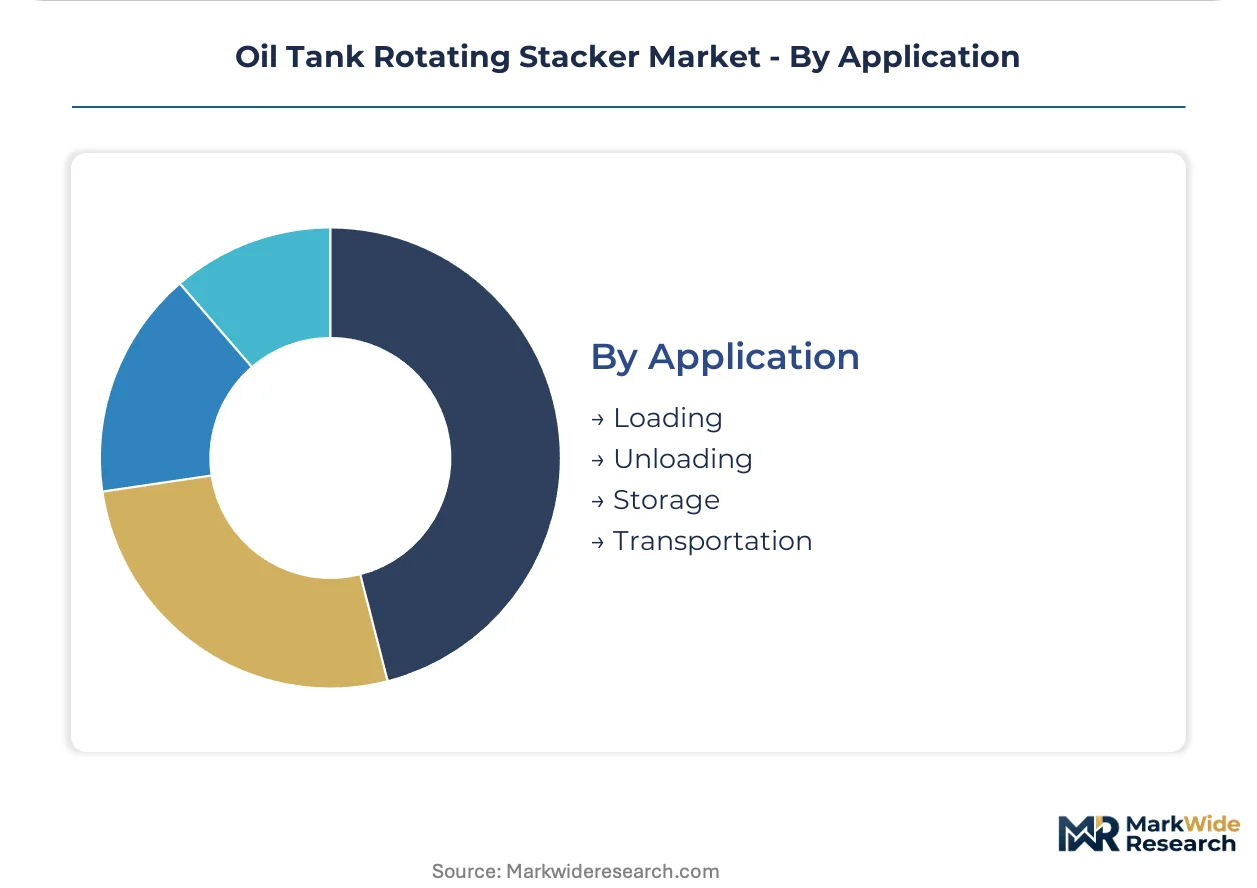
Application:
Volume concentration follows the tank farm construction cycle, with loading and unloading operations commanding higher equipment duty cycles than static storage positioning.
- Loading:Tank filling operations require stackers to position empty cylindrical vessels under pipeline connections or truck loading arms. Texas crude export terminals specify high-duty-cycle automatic stackers for continuous vessel marshaling.
- Unloading:Product discharge sequences demand precise tank alignment with pump suction connections and vapor recovery systems. Louisiana refined product terminals deploy stackers for ethanol and biodiesel tank rotation.
- Storage:Static tank positioning for long-term containment represents the baseline application with lowest equipment utilization. Secondary containment areas in mature facilities use manual stackers for occasional tank relocation.
- Transportation:Inter-modal transfer operations move tanks between rail, truck, and marine loading configurations. Houston Ship Channel logistics hubs specify mobile stackers for flexible vessel routing.
Storage applications anchor the volume base while loading operations gain share fastest as export terminal throughput expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States terminal operators deploy stackers primarily for turnaround maintenance cycles, while European buyers emphasize carbon-border adjustment readiness in electrification specifications.
United States
Gulf Coast refining clusters in Texas and Louisiana drive stacker procurement through multi-year capacity expansion timelines. EPA Clean Air Act enforcement accelerates hydraulic-to-electric conversions with sealed bearing mandates for fugitive emissions containment. Houston Ship Channel logistics hubs specify mobile configurations for flexible inter-modal tank routing.
Germany
Integrated chemical manufacturers along the Rhine corridor require explosion-rated stackers for hazardous zone tank positioning. ECHA REACH compliance shapes lubrication system specifications and containment protocol redesigns. BASF Ludwigshafen and Bayer Leverkusen facilities anchor demand for automated configurations with digital monitoring integration.
Netherlands
Rotterdam terminal operators specify permanent magnet synchronous motor systems for net-zero committed facilities ahead of EU carbon-border adjustment implementation. Port Authority infrastructure electrification programs compress replacement cycles for legacy hydraulic installations. Maasvlakte storage zones bundle stacker acquisition into automated material handling fleet expansions.
Singapore
Jurong Island petrochemical complexes prioritize electrical drive specifications for carbon-border adjustment preparation and trade mechanism alignment. Maritime and Port Authority decarbonization timelines accelerate terminal electrification requirements. Tuas industrial zone developments integrate rotating stackers into modular storage expansion methodologies.
Saudi Arabia
Downstream processing facilities in Jubail and Yanbu deploy stackers during crude and product tank maintenance turnaround cycles. Saudi Aramco localization initiatives reshape supplier relationships for rotating machinery procurement. King Salman Energy Park manufacturing zones concentrate assembly capacity for regional terminal infrastructure projects.
Oil Tank Rotating Stacker Market Competitive Landscape
Capability concentration sits with precision gearbox and electrification specialists; scale advantage sits with integrated terminal operators and diversified industrial conglomerates. The market structures around three tiers: original equipment manufacturers with heat-transfer installed bases, energy services providers with digital monitoring platforms, and infrastructure controllers with procurement decision leverage. Two competitive moves dominate: cross-selling maintenance contracts through equipment installed bases, and bundling stacker procurement into multi-year terminal capacity expansion cycles.
Within the industrial conglomerate tier, Alfa Laval AB and General Electric Co. exemplify archetypes leveraging adjacent equipment portfolios to anchor rotating machinery positions. Baker Hughes Co. occupies a specialist position among energy services providers, while Kinder Morgan represents infrastructure-controlled procurement leverage. These three entities illustrate how supplier relationships restructure around electrification transitions and aftermarket service unbundling.
| Leading Market Players |
|---|
| Alfa Laval AB |
| Atlas Copco AB |
| General Electric Co |
| Baker Hughes Co. |
| Pentair PLC |
| Kinder Morgan |
| Vopak |
| Oiltanking |
| Jungheinrich AG |
| Others |
Value Network & Pricing Analysis
Single-source dependency on European and Japanese precision gearbox manufacturers determines both pricing tier spreads and supply chain shape, concentrating premium margins in electrified configurations while compressing returns for hydraulic system providers facing extended replacement timelines.
Pricing Analysis
Long-term offtake contracts dominate procurement for integrated terminal operators like Kinder Morgan, while independent maintenance contractors purchase on spot cycles. Three-tier pricing structure across premium automatic configurations, standard semi-automatic units, and economy manual stackers reflects automation level and drive technology differentiation. Cost compression in hydraulic tiers is intensifying because EPA emissions enforcement accelerates electric conversion demand. Bulk storage terminals exhibit highest price sensitivity given capex bundling pressures, whereas net-zero committed operators in Rotterdam and Singapore show lowest sensitivity for electrified specifications.
Supply Chain Analysis
Extended payment terms from 90 to 180 days characterize supplier relationships as terminal operators stretch working capital across multi-year capacity expansions. Manufacturing concentration rests on Germany, Japan, and China for precision planetary gearboxes, permanent magnet synchronous motors, and sealed bearing assemblies. Critical input dependencies include rare-earth magnet materials, high-grade alloy steel castings, and explosion-rated electrical enclosures. Single-source vulnerability concentrates in slewing drive components from European specialists. Distribution runs through OEM direct sales for large terminal operators and regional equipment distributors serving independent maintenance contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision gearbox engineering talent and certified electrical drive integration capability anchor competitive position, with scarcity intensifying as hydraulic-to-electric conversions accelerate across Gulf Coast and European terminal corridors.
For Market Incumbents: Insulate aftermarket revenue by capturing electric drive retrofit contracts ahead of third-party refurbishment specialists, and deepen captive supply of planetary gearbox components through partnerships with Japanese precision manufacturers. Regulatory pressure from EPA emissions enforcement and OSHA crane-safety mandates threatens legacy hydraulic service margins. Vertical integration into sealed bearing certification capabilities represents the critical defensive lever. For New Entrants and Emerging Players: Secondary petroleum terminals in North Dakota Bakken shale fields present the most penetrable white-space opportunity, where mobile stacker demand for rapid field assembly outpaces established distributor coverage. Refinery maintenance departments in Louisiana seeking hybrid semi-automatic flexibility for varying tank diameters offer a second entry point. A go-to-market angle emphasizing modular storage expansion methodologies without crane dependency differentiates against incumbent positioning. For Investors and Strategic Acquirers: Digital monitoring platform specialists with integrated vibration analysis and thermal imaging capabilities represent the priority acquisition archetype for predictive maintenance contract expansion. Long-term viability over a 5-10 year window hinges on electrification transition capture and aftermarket service unbundling defense. The signal to watch is permanent magnet synchronous motor supplier consolidation as net-zero terminal commitments harden into procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Retrofit Program | Captures EPA compliance-driven replacement demand ahead of third-party competitors in Gulf Coast corridors. |
| Predictive Maintenance Platform Integration | Baker Hughes digital monitoring convergence creates recurring revenue attachment to rotating machinery installed base. |
| Sealed Bearing Certification Investment | Extended EPA validation protocols for leak detection integration points create barrier against unqualified entrants. |
| Modular Storage Partnership | Tank farm construction methodology shifts specify rotating stackers for cylindrical positioning without crane dependency. |
| Carbon-Border Adjustment Preparation | Rotterdam and Singapore terminal operators accelerate electrified equipment specifications ahead of EU trade mechanism implementation. |
Research Methodology
Desk research of customs trade databases, SEC filings from energy infrastructure operators, and terminal capacity expansion announcements preceded structured interviews with maintenance directors at Gulf Coast refineries, procurement leads from integrated terminal operators, aftermarket service heads at rotating machinery specialists, and plant engineers at petrochemical facilities. Secondary validation drew from EPA enforcement records, OSHA incident databases, and industry association technical specifications. Bottom-up equipment unit economics triangulated against top-down terminal capex cycle analysis.
Assumptions around regulatory enforcement timelines, electrification subsidy availability, and gearbox supplier capacity expansion were held fixed across baseline scenarios while terminal throughput growth rates and carbon-border adjustment implementation timing were varied in sensitivity testing. Segmentation dimensions modeled include automation level, drive technology type, end-user industry vertical, and regional regulatory cluster. CAGRs were derived from replacement cycle compression analysis and technology migration curves. Industry-specific inputs incorporated hydraulic technician pool attrition rates and high-voltage infrastructure deployment timelines.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting terminal operator capex commitments or commodity price volatility impacting storage capacity expansion timing would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology cost reduction curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Well Logging Tools Market
Oil & Gas
Libya Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Automation Market
Oil & Gas
Russia Oilfield Services Market
Oil & Gas
Downhole Equipment Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
Oil and Gas Corrosion Protection Market
Oil & Gas
Argentina Oil and Gas Upstream Market
Oil & Gas
Planned LNG Market
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
Drilling Bits Market
Oil & Gas
Underreamers Market
Oil & Gas
North America Hydraulic Fracturing Fluids Market
Oil & Gas
US Sand Control Systems Market
Oil & Gas
Hydraulic Fracturing Market
Oil & Gas
Mexico Oil and Gas Market