
 Republic of Congo Oil and Gas Market | 2026-2036
Republic of Congo Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Republic of Congo Oil and Gas Market Analytics
Offshore power generation buyers is bifurcating demand away from marine fuel purchasers as coastal electrification projects multiply. TotalEnergies leverages its deepwater Moho Nord infrastructure to sustain production volumes in the Congolese pre-salt basin. Eni competes through its focus on subsea tieback technology, while Perenco dominates marginal field rehabilitation across aging onshore assets.
The Republic of Congo Oil and Gas sector encompasses crude petroleum extraction, natural gas production, and hydrocarbon processing across onshore and offshore concessions, with crude typically measuring 25-35 API gravity and sulfur content below 0.5 percent in premium grades. The industry supplies feedstock for electricity generation, petrochemical manufacturing, and maritime bunkering across Central African trade routes. Exploration services command premium margins given the technical complexity of pre-salt geology in the Lower Congo Basin, while offshore drilling technology leads capital deployment as operators target depths exceeding 1,200 meters. Enhanced oil recovery applications show structural momentum as mature fields require pressure maintenance to offset natural decline rates.
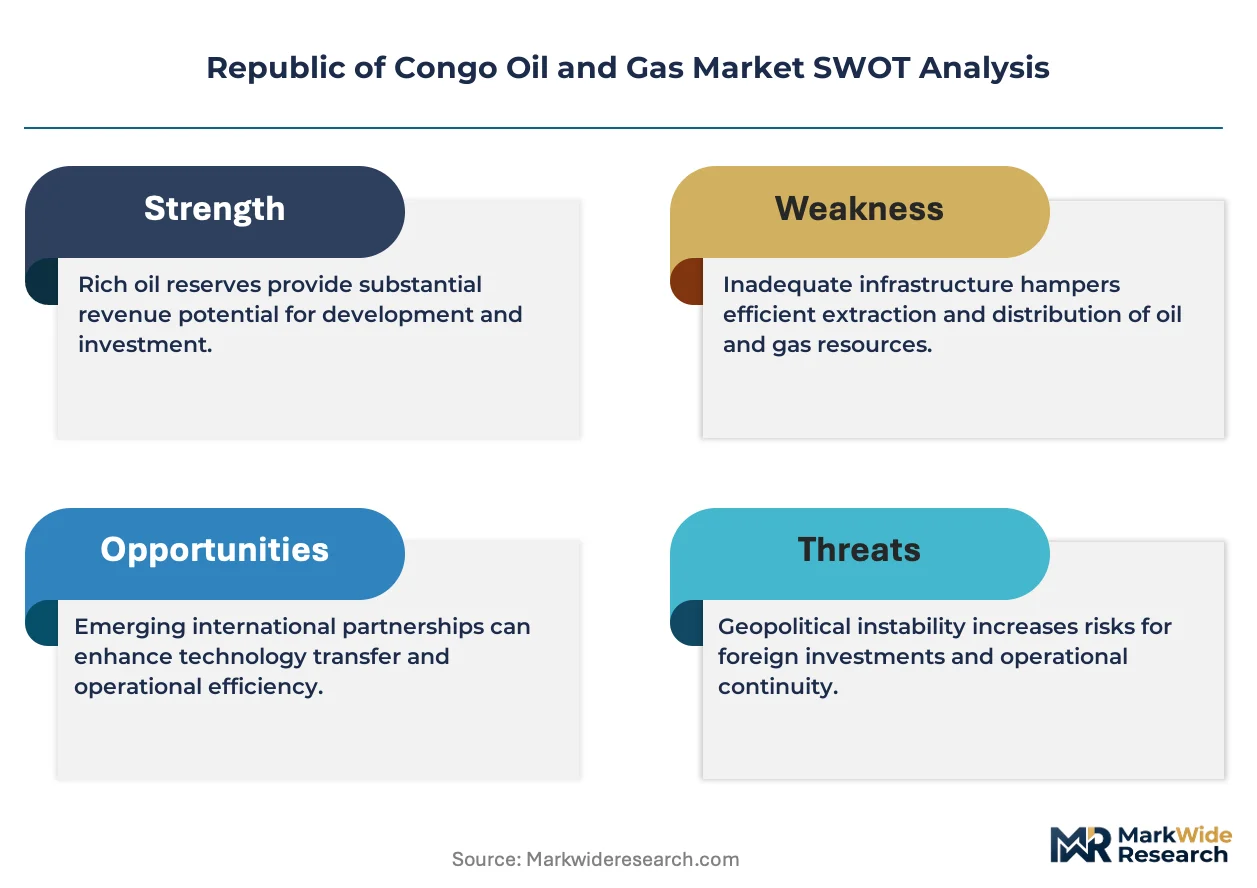
The Ministry of Hydrocarbons and the national petroleum regulator govern licensing rounds, production sharing contracts, and environmental compliance for upstream activities. The Extractive Industries Transparency Initiative framework shapes disclosure requirements that influence investor access and capital flows into Congolese projects. Stakeholders must monitor how fiscal term negotiations affect project economics as the government seeks greater state participation in new field developments.
Market Dynamics
Deepwater pre-salt exploration is redrawing the Republic of Congo's upstream economics as operators push beyond 1,200-meter depths to access untapped reservoirs in the Lower Congo Basin.
Growth Catalysts
- Extractive Industries Transparency Initiative compliance:Disclosure mandates from this framework are unlocking institutional capital flows into Congolese licensing rounds. International lenders now treat EITI adherence as a prerequisite for project finance.
- Offshore power generation demand:Coastal electrification projects in Pointe-Noire and surrounding industrial zones are creating dedicated offtake agreements for associated gas. This absorbs volumes previously flared or reinjected.
- Subsea tieback technology:Satellite field development via subsea infrastructure is slashing capital intensity for marginal discoveries. Eni's deployment of this approach across its Marine XII block demonstrates scalable economics.
Market Restraints
- Capital equipment import dependency:Subsea trees, blowout preventers, and dynamic positioning vessels must transit through congested regional logistics corridors. Lead times for critical spares routinely exceed eighteen months.
- Mature field decline rates:Aging onshore assets in the coastal basin require continuous pressure maintenance. Natural depletion outpaces reserve replacement without enhanced oil recovery investments.
- Fiscal term uncertainty:The Ministry of Hydrocarbons is renegotiating production sharing contract frameworks to secure higher state participation. Investor returns compress under evolving royalty and cost-recovery structures.
Strategic Opportunities
- Associated gas monetization:Stranded gas from offshore crude operations can feed planned methanol or fertilizer plants in Pointe-Noire. Domestic petrochemical integration captures value currently lost to flaring.
- Marginal field rehabilitation:Perenco's demonstrated success with aging onshore assets creates a playbook for additional brownfield acquisitions. Smaller independents can access production without frontier exploration risk.
- Regional bunkering hub development:The Pointe-Noire corridor sits astride Central African maritime trade routes. Low-sulfur marine fuel blending and storage infrastructure can capture transshipment demand.
Industry Challenges
- Deepwater drilling competency gaps:Pre-salt geology demands specialized geoscience interpretation and managed pressure drilling expertise. Local workforce development lags technical requirements for ultra-deepwater operations.
- Environmental compliance timelines:The national petroleum regulator's environmental impact assessment protocols extend project sanction schedules. Operators face protracted approval cycles for seismic acquisition and drilling permits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Republic of Congo Oil and Gas Market |
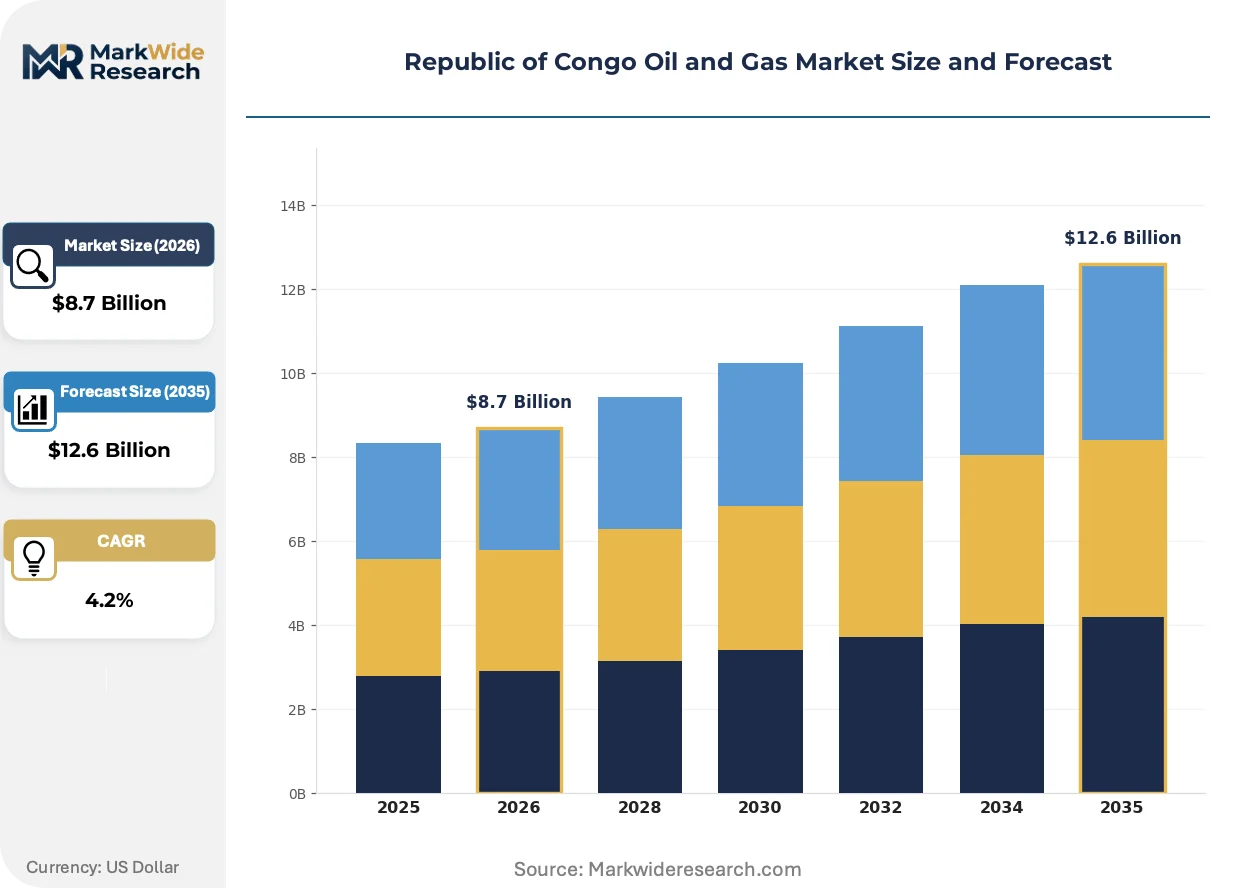
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Production, Refining, Distribution Technology: Offshore Drilling, Hydraulic Fracturing, Enhanced Oil Recovery, Gas Processing End User: Utilities, Industrial, Residential, Commercial Application: Power Generation, Petrochemicals, Marine Fuel, Heating |
| Companies Covered | SNPC, Chevron, TotalEnergies, Sinopec, Wing Wah, Eni, Trident Energy, QatarEnergy, Perenco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Republic of Congo Oil and Gas Market Evolving Landscape
Digital reservoir characterization and subsea processing architectures are compressing development timelines across the Congolese offshore, while regulatory pressure on methane emissions is forcing operational redesigns.
Subsea boosting systems are displacing conventional platform-based production infrastructure in water depths exceeding 1,000 meters. TotalEnergies and partners are deploying multiphase pumps at the seabed across Moho Nord tiebacks. This architecture eliminates surface facility capital and reduces offshore personnel exposure.
The Ministry of Hydrocarbons is tightening local content mandates for engineering, procurement, and construction contracts. Operators must now demonstrate measurable Congolese workforce participation and supplier spend to secure drilling approvals. International contractors are establishing joint ventures with domestic service firms to maintain license eligibility.
Buyers in the Pointe-Noire industrial corridor are consolidating fuel procurement through term contracts rather than spot market purchases. Cement manufacturers and mining operations are locking in marine fuel supply directly with upstream producers. This disintermediation of trading houses concentrates volume commitments and demands guaranteed delivery schedules.
Republic of Congo Oil and Gas Market Segmentation
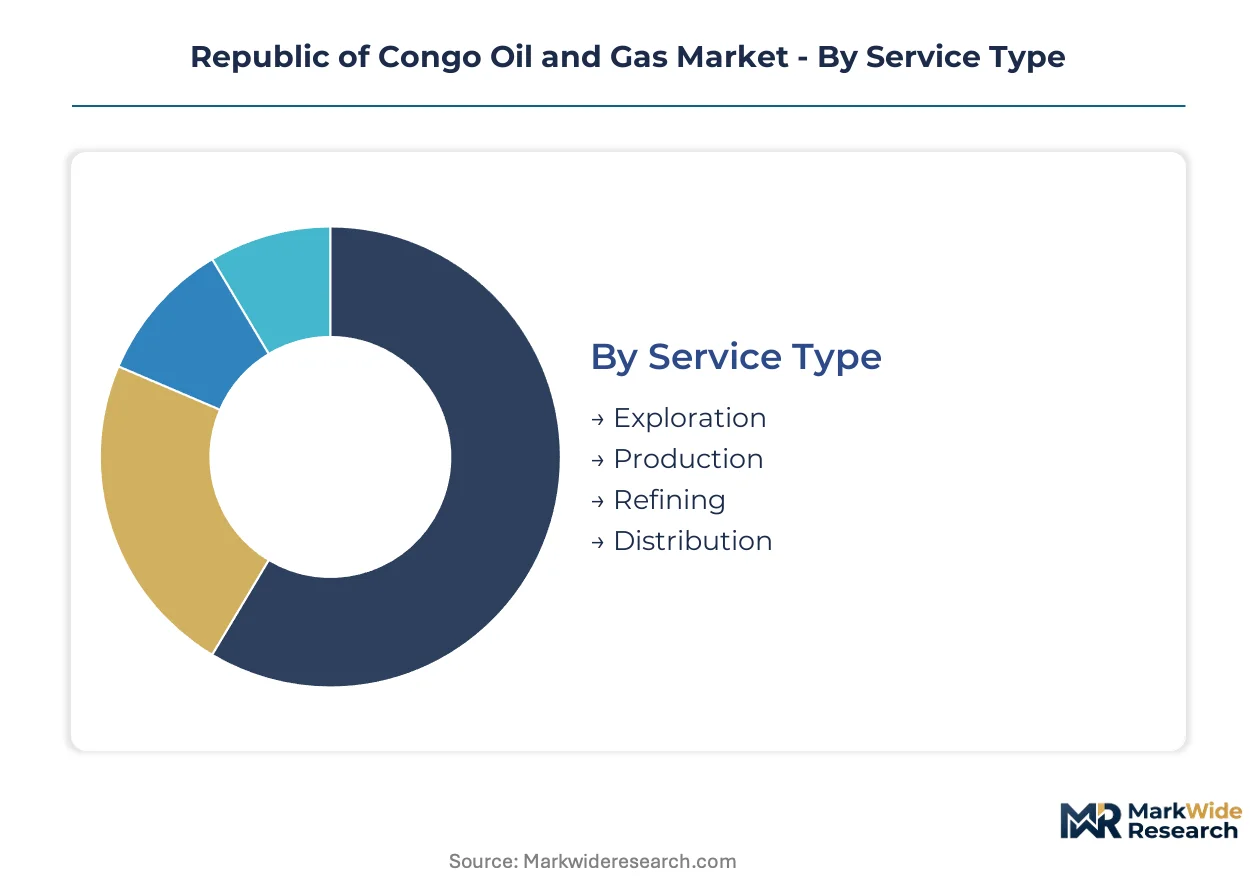
The Republic of Congo's hydrocarbon value chain fragments across four critical dimensions that determine capital allocation and contracting patterns. Service type dictates whether operators engage international majors or domestic contractors. Technology selection separates deepwater frontier projects from mature field rehabilitation. End user concentration in Pointe-Noire shapes offtake negotiations. Application mix determines whether associated gas gets flared, reinjected, or monetized.
Service Type:
Upstream services flow through production sharing contract channels, while downstream activities route through state-affiliated procurement frameworks.
- Exploration:Pre-salt seismic interpretation and wildcat drilling command premium dayrates given the Lower Congo Basin's complex salt tectonics. Demand concentrates with TotalEnergies and Eni as they probe depths beyond 1,200 meters, though fiscal term renegotiations by the Ministry of Hydrocarbons are compressing contractor margins.
- Production:Subsea tieback architectures and floating production systems sustain output from Moho Nord and Marine XII blocks. Pointe-Noire industrial corridor buyers absorb crude offtake through term contracts rather than spot purchases, locking in dedicated export schedules.
- Refining:The country's sole refinery processes domestic crude into transportation fuels and heating oil for coastal distribution. Aging infrastructure limits throughput, forcing reliance on imported refined products for interior provinces.
- Distribution:Pipeline networks and coastal bunkering terminals move hydrocarbons from offshore loading facilities to industrial end users. Marine fuel blending operations in Pointe-Noire serve Central African transshipment routes.
By volume, Production leads. By growth pace, Exploration is climbing the fastest as licensing rounds attract pre-salt investment.
Technology:
Capital intensity varies dramatically across technology tiers, with ultra-deepwater systems commanding five to eight times the per-barrel cost of mature field techniques.
- Offshore Drilling:Managed pressure drilling and dynamic positioning vessels enable operations in 1,200-meter-plus water depths. The national petroleum regulator's extended environmental approval timelines stretch rig scheduling, while equipment import dependencies through regional logistics corridors routinely push lead times past eighteen months.
- Hydraulic Fracturing:Limited application in the Republic of Congo's conventional sandstone and carbonate reservoirs. Onshore marginal fields occasionally deploy acidizing and fracturing for near-wellbore stimulation, though pre-salt carbonate formations favor matrix acidizing over proppant fracturing.
- Enhanced Oil Recovery:Waterflooding and gas injection programs sustain output from aging coastal basin fields. Perenco's rehabilitation of mature onshore assets demonstrates scalable economics for pressure maintenance investments.
- Gas Processing:Associated gas separation and treatment infrastructure feeds planned methanol and fertilizer integration in Pointe-Noire. Stranded gas monetization captures value currently lost to flaring, though domestic petrochemical demand remains insufficient to absorb all available volumes.
By capital deployed, Offshore Drilling dominates. By operational momentum, Enhanced Oil Recovery shows the steepest expansion trajectory as decline rates accelerate across mature assets.
End User:
Demand concentration patterns split between anchor industrial offtakers in Pointe-Noire and dispersed residential consumption requiring subsidized distribution networks.
- Utilities:State power generators and emerging independent producers purchase fuel oil and natural gas for coastal electrification. Offshore power generation projects are bifurcating demand away from traditional marine fuel purchasers as dedicated gas offtake agreements multiply.
- Industrial:Cement manufacturers, mining operations, and manufacturing plants in the Pointe-Noire corridor lock in term contracts directly with upstream producers. This disintermediation of trading houses concentrates volume commitments and demands guaranteed delivery schedules.
- Residential:Liquefied petroleum gas and kerosene serve household cooking and lighting needs in Brazzaville and Pointe-Noire. Subsidized pricing structures strain state finances while distribution infrastructure gaps leave interior regions underserved.
- Commercial:Retail fuel stations, logistics fleets, and construction equipment operators purchase diesel and gasoline through licensed distributors. Bunkering services for regional maritime traffic represent a growing commercial segment.
By revenue contribution, Industrial leads. By infrastructure investment requirements, Residential is expanding most quickly as rural electrification programs advance.
Application:
Application mix determines whether hydrocarbon molecules flow to export markets, domestic manufacturing, or direct combustion.
- Power Generation:Fuel oil and natural gas feed coastal power plants serving Pointe-Noire industrial demand. Associated gas absorption through dedicated offtake agreements reduces flaring intensity while securing baseload electricity supply.
- Petrochemicals:Planned methanol and fertilizer plants aim to integrate stranded gas into higher-value products. Domestic processing capacity remains nascent, leaving most feedstock exported as crude or unprocessed gas.
- Marine Fuel:Low-sulfur bunkering blends serve Central African maritime trade routes through Pointe-Noire storage and blending infrastructure. Coastal electrification projects are displacing some traditional marine fuel demand as offshore power generation scales.
- Heating:Residual fuel oil and natural gas serve industrial process heat requirements in manufacturing and mining operations. Seasonal demand fluctuations align with construction activity cycles in the coastal corridor.
By throughput volume, Power Generation leads. By value-added capture potential, Petrochemicals is gaining share fastest as integration projects advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Republic of Congo crude flows primarily to European refineries and Asian petrochemical complexes, with Pointe-Noire serving as the principal export terminal for Atlantic basin trade routes.
Pointe-Noire Industrial Corridor
Cement manufacturers and mining operations anchor fuel oil demand through direct term contracts with upstream producers. The Ministry of Hydrocarbons enforces local content mandates requiring Congolese workforce participation in engineering contracts. Offshore power generation projects along this coastal strip absorb associated gas previously destined for flaring.
Brazzaville Metropolitan Zone
Residential liquefied petroleum gas consumption drives distribution infrastructure investment in the capital region. Subsidized pricing structures strain state finances while leaving interior provinces underserved. The national petroleum regulator coordinates environmental compliance timelines for pipeline expansion projects serving this demand cluster.
Kouilou Department
Deepwater pre-salt exploration concentrates in offshore blocks where water depths exceed 1,200 meters. Extractive Industries Transparency Initiative disclosure requirements shape capital access for licensing rounds in this maritime zone. TotalEnergies and Eni operate subsea infrastructure tiebacks connecting satellite fields to central processing facilities.
Niari Valley
Onshore marginal field rehabilitation targets aging sandstone reservoirs requiring continuous pressure maintenance. Perenco's brownfield acquisition strategy demonstrates scalable economics for enhanced oil recovery investments. The Ministry of Hydrocarbons negotiates production sharing contract terms to secure higher state participation in these mature asset developments.
Republic of Congo Oil and Gas Market Competitive Landscape
Player mix skews toward integrated international majors controlling deepwater infrastructure alongside specialized independents targeting marginal field rehabilitation. Market structure concentrates upstream activity around operators with pre-salt technical capabilities and existing subsea processing assets. Two strategic archetypes dominate: capital-intensive frontier developers deploying ultra-deepwater systems, and brownfield specialists extracting residual value from aging onshore concessions. Competitive moves center on portfolio diversification into gas monetization and strategic partnerships for local content compliance.
Within the integrated major tier, TotalEnergies and Eni occupy positions defined by deepwater pre-salt access and subsea tieback deployment capabilities. Among independent operators, Perenco represents the brownfield rehabilitation archetype through its demonstrated execution on aging onshore assets. SNPC anchors the national champion position as state equity participant across licensing rounds.
| Leading Market Players |
|---|
| SNPC |
| Chevron |
| TotalEnergies |
| Sinopec |
| Wing Wah |
| Eni |
| Trident Energy |
| QatarEnergy |
| Perenco |
| Others |
Value Network & Pricing Analysis
Ultra-deepwater rig utilization rates above 85 percent concentrate bargaining power among a handful of international drilling contractors serving the Lower Congo Basin. This capacity tightness elevates dayrate floors for managed pressure drilling and dynamic positioning vessels while compressing margins for operators locked into legacy production sharing contracts.
Pricing Analysis
Current-generation subsea boosting systems command premium contract structures against prior-generation platform-based infrastructure and next-generation autonomous seabed processing architectures. Three-tier pricing structure across premium pre-salt exploration, standard deepwater development, and economy onshore rehabilitation segments reflects technical complexity and capital intensity differentials. Cost compression in the standard tier is intensifying because fiscal term renegotiations by the Ministry of Hydrocarbons are squeezing contractor recoverable costs. National oil company offtakers demonstrate lowest price sensitivity given state-mandated supply security priorities, while independent power producers in the Pointe-Noire corridor exhibit highest sensitivity due to regulated electricity tariff caps.
Supply Chain Analysis
Strategic stockpiling of subsea trees and blowout preventers dominates inventory strategy given eighteen-plus month lead times through regional logistics corridors, with just-in-time approaches limited to consumables and standard spares. Equipment fabrication concentrates in Norway, Singapore, and the United States Gulf Coast. Critical inputs include high-grade steel forgings, subsea umbilicals, and dynamic positioning systems. Single-source vulnerability for specialized geoscience interpretation services creates procurement risk. Distribution runs through Pointe-Noire port facilities and offshore loading terminals to European and Asian refinery destinations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against renewable electrification and regional LNG import substitution that threatens fuel oil demand in coastal power generation. Substitution pressure from associated gas absorption projects and cross-border hydropower interconnectors demands portfolio repositioning.
For Market Incumbents: Compound technical differentiation in pre-salt geoscience interpretation and managed pressure drilling capabilities to sustain premium dayrate capture against emerging independent contractors. Deepen backward integration into subsea equipment maintenance and local workforce training to satisfy Ministry of Hydrocarbons local content mandates and secure drilling permit continuity. Vertical integration into associated gas processing infrastructure captures value currently lost to flaring while building defensive moats against renewable substitution.
For New Entrants and Emerging Players: Lead with marginal field rehabilitation expertise targeting Niari Valley aging assets where Perenco has demonstrated scalable economics and acquisition multiples remain compressed. White-space concentration sits in brownfield enhanced oil recovery services and domestic petrochemical feedstock supply to planned methanol and fertilizer plants. Go-to-market positioning as local content compliance partners for international majors offers fastest license eligibility pathway.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subsea infrastructure operators with long-term offtake contracts to Pointe-Noire industrial corridor buyers. Long-term viability favors participants with proven pre-salt technical capabilities and existing subsea processing assets over frontier exploration pure-plays. Acquisition target archetype: brownfield specialists with demonstrated enhanced oil recovery execution and established regulator relationships. Signal to watch is fiscal term finalization speed in pending production sharing contract renegotiations.
| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Infrastructure Tieback | Eni's Marine XII deployment validates scalable satellite field economics at depths exceeding 1,000 meters. |
| Associated Gas Monetization | Stranded gas absorption into Pointe-Noire petrochemical integration reduces flaring penalties and secures domestic offtake. |
| Local Content Joint Venture | International contractors partnering with domestic service firms satisfy Ministry of Hydrocarbons workforce participation mandates. |
| Enhanced Oil Recovery Program | Perenco's pressure maintenance investments in Niari Valley demonstrate residual value extraction from mature sandstone reservoirs. |
| Regional Bunkering Hub Development | Low-sulfur marine fuel blending infrastructure captures Central African transshipment demand along Atlantic trade routes. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with upstream project managers, subsea engineering directors, Ministry of Hydrocarbons licensing officials, Pointe-Noire industrial procurement leads, and national petroleum regulator compliance officers. Secondary validation drew from Extractive Industries Transparency Initiative disclosure filings, national production sharing contract registries, customs export documentation, and offshore project development databases. Bottom-up field-level production estimates and top-down national hydrocarbon accounts were triangulated to anchor volume and value projections.
Across the analysis window, the forecasting framework models segmentation dimensions spanning service type, technology tier, end user concentration, and application mix alongside water depth categories and local content compliance status. CAGRs were derived from production trajectory modeling and capital deployment schedules rather than extrapolated historical trends. Industry-specific inputs include pre-salt exploration success rates, subsea equipment lead time distributions, and fiscal term negotiation outcome probabilities.
The analysis sits within stated boundaries; outcomes outside sustained Brent price bands and stable Ministry of Hydrocarbons regulatory posture would require recalibration. Forecasts reflect documented assumptions regarding licensing round timing and environmental approval cycle durations. Revision becomes warranted when fiscal term renegotiation outcomes cross thresholds that materially alter project return hurdles or when subsea equipment import logistics experience sustained disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Africa Oil and Gas Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
3D Printing in Oil and Gas Market
Oil & Gas
Oilfield Casing Spools Market
Oil & Gas
Canada Oil and Gas Pipeline Services Market
Oil & Gas
Drilling Services Market
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
Middle East and Africa Digital Oilfield Market
Oil & Gas
Mud Balance Market
Oil & Gas
Well Stimulation Vessels Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
Wellhead and Christmas Tree Special Parts Market
Oil & Gas
Libya Oil and Gas Upstream Market