
 Distributed Fiber Optic Sensor in Oil & Gas Market | 2026-2036
Distributed Fiber Optic Sensor in Oil & Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Fiber Optic Sensor in Oil & Gas Market Analytics
Offshore reservoir monitoring is shifting toward permanent downhole installations as operators prioritize production optimization over intermittent wireline surveys. SLB leverages its integrated drilling and completions portfolio to bundle fiber optic sensing with intelligent well systems. Halliburton sustains competitive pressure through specialized distributed acoustic sensing packages for hydraulic fracture diagnostics. Baker Hughes anchors its position with subsea fiber optic solutions tied to subsea production control networks.
Distributed fiber optic sensing deploys standard telecommunications-grade silica fibers or ruggedized cables along wellbores, pipelines, and reservoirs, using backscattered light phenomena to measure temperature, strain, and acoustic signatures continuously along the entire fiber length with spatial resolutions reaching one meter over distances exceeding fifty kilometers. The technology serves primarily to eliminate point-sensor blind spots in harsh downhole and subsea environments where electronics fail. Temperature sensing dominates current revenue contribution due to mature DTS deployment in steam-assisted gravity drainage and geothermal monitoring applications, while acoustic sensing captures the fastest expansion trajectory as operators apply distributed acoustic sensing to pipeline intrusion detection and microseismic mapping. Raman scattering technology occupies the established commercial core for thermal profiling, though Brillouin scattering systems are penetrating structural health monitoring of subsea risers and platform tendons where strain resolution demands exceed Raman capabilities.
The U.S. BSEE enforces real-time monitoring mandates for high-pressure high-temperature wells in the Gulf of Mexico, compelling operators to specify certified fiber optic systems for well integrity verification. API RP 17N and ISO 13628-7 establish qualification protocols for subsea optical cables, creating barrier-to-entry conditions for unqualified suppliers. The EU F-Gas Regulation and offshore safety directives under EASA coordination push North Sea operators toward leak detection systems where distributed fiber optic sensing displaces conventional point detectors. Stakeholders must evaluate technology roadmaps against evolving regulatory qualification requirements and subsea electrification trends that expand addressable fiber channel counts.
Market Dynamics
Subsea electrification is compressing the addressable channel count for fiber optic sensing systems as operators replace hydraulic umbilicals with all-electric production networks across deepwater developments.
Growth Catalysts
- API RP 17N qualification mandates:The U.S. BSEE enforces real-time monitoring requirements for high-pressure high-temperature wells in the Gulf of Mexico, compelling operators to specify certified fiber optic systems for well integrity verification.
- Steam-assisted gravity drainage:Canadian oil sands operators deploy distributed temperature sensing to optimize steam chamber development and reduce steam-to-oil ratios in thermal extraction operations.
- EU F-Gas Regulation:North Sea operators face phasedown requirements for synthetic greenhouse gases, accelerating displacement of conventional point detectors with distributed fiber optic leak detection systems.
Market Restraints
- Telecommunications-grade silica fiber supply:Concentration of specialty fiber manufacturing in East Asian suppliers creates vulnerability to trade friction and shipping disruptions for ruggedized cable producers.
- Brillouin scattering system cost structure:Strain resolution demands exceeding Raman capabilities require expensive coherent detection hardware that limits adoption in marginal field developments.
- Subsea installation complexity:Wet-mate optical connector qualification under ISO 13628-7 imposes extended lead times and capital intensity on permanent downhole monitoring deployments.
Strategic Opportunities
- Geothermal reservoir monitoring:Enhanced geothermal systems in Nevada and Utah present untapped demand for distributed temperature and acoustic sensing in fracture network characterization.
- CCUS plume tracking:Carbon capture and storage operators require continuous pressure and temperature monitoring for injection zone conformance and caprock integrity verification.
- Pipeline intrusion detection:Midstream operators in the Permian Basin are retrofitting existing fiber infrastructure for third-party interference monitoring and leak localization.
Industry Challenges
- Interdisciplinary skill convergence:Deployment teams must integrate optical physics expertise with petroleum engineering and subsea systems integration, creating talent scarcity in hybrid technical roles.
- Legacy SCADA integration:Brownfield installations face protocol incompatibility between proprietary fiber interrogator outputs and existing distributed control system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Fiber Optic Sensor in Oil & Gas Market |
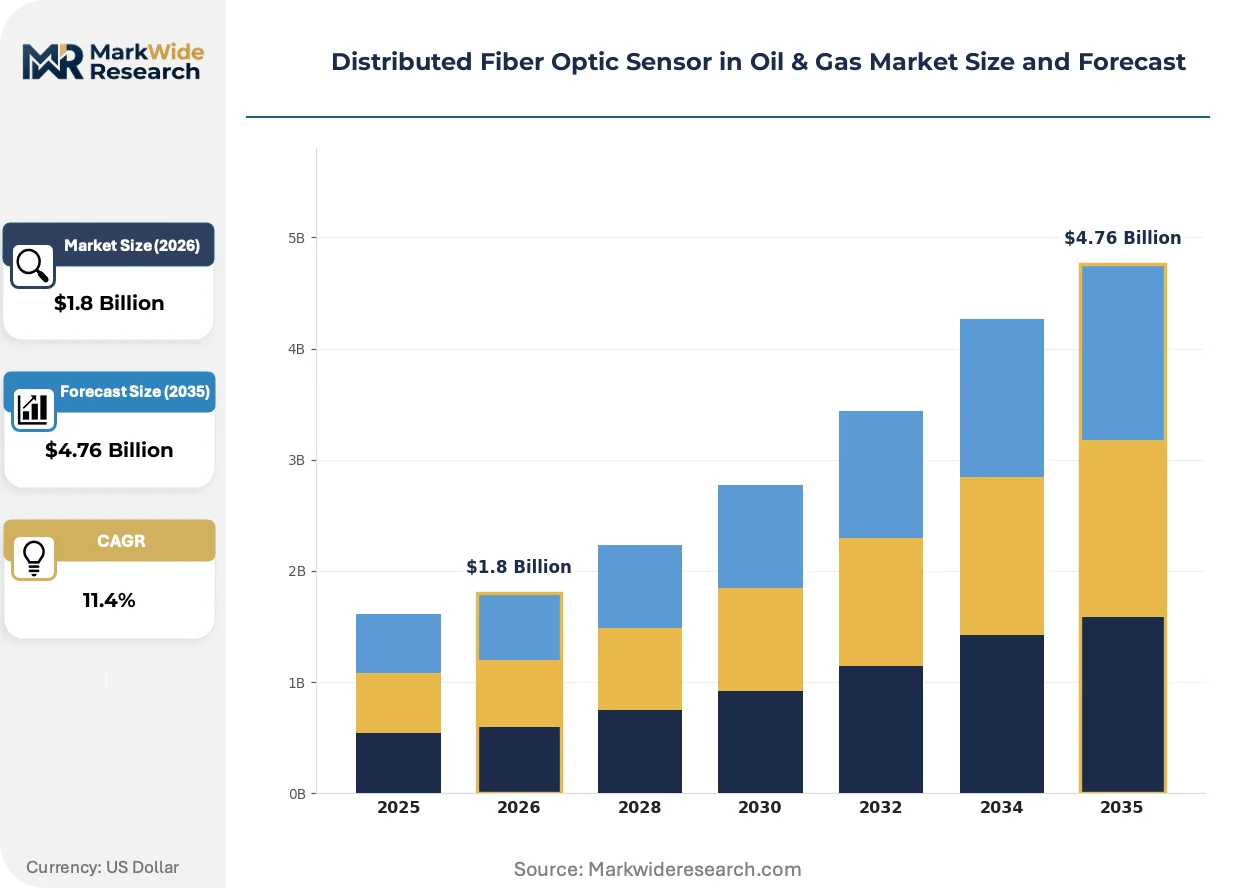
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensing, Strain Sensing, Pressure Sensing, Acoustic Sensing Installation: Onshore, Offshore, Subsea, Surface End User: Operators, Contractors, Service Providers, Asset Managers Technology: Rayleigh Scattering, Brillouin Scattering, Raman Scattering, Time-Domain Reflectometry |
| Companies Covered | SLB, Halliburton, Baker Hughes, Yokogawa Electric Corporation, Luna Innovations, OptaSense, Fotech Solutions, AP Sensing, OFS Fitel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Fiber Optic Sensor in Oil & Gas Market Evolving Landscape
Multiplexed sensing architectures are collapsing the cost per measurement point as interrogator hardware evolves toward simultaneous temperature, strain, and acoustic acquisition from single fiber deployments.
Coherent Rayleigh scattering is electrifying the microseismic monitoring segment by enabling distributed acoustic sensing with sensitivity approaching conventional geophone arrays. Permian Basin operators are retrofitting existing fiber infrastructure for real-time fracture geometry mapping during zipper frac operations. This capability is compressing the timeline between stimulation and production optimization decisions from weeks to hours.
The EU F-Gas Regulation is tightening leak detection requirements for offshore facilities under EASA coordination, mandating continuous monitoring systems that displace conventional point detectors. North Sea operators must demonstrate equivalent or superior detection sensitivity for methane and hydrogen sulfide releases. Subsea production system suppliers are bundling distributed fiber optic sensing into integrated safety system packages to meet these qualification thresholds.
Asset performance contracting is restructuring procurement relationships as operators transfer interrogator hardware ownership to service companies in exchange for guaranteed measurement availability. This model transfers obsolescence risk from capital-constrained producers to technology vendors with balance sheet capacity. The Gulf of Mexico deepwater segment shows the fastest penetration of this arrangement, with integrated service providers assuming responsibility for fiber lifecycle management and data interpretation.
Distributed Fiber Optic Sensor in Oil & Gas Market Segmentation
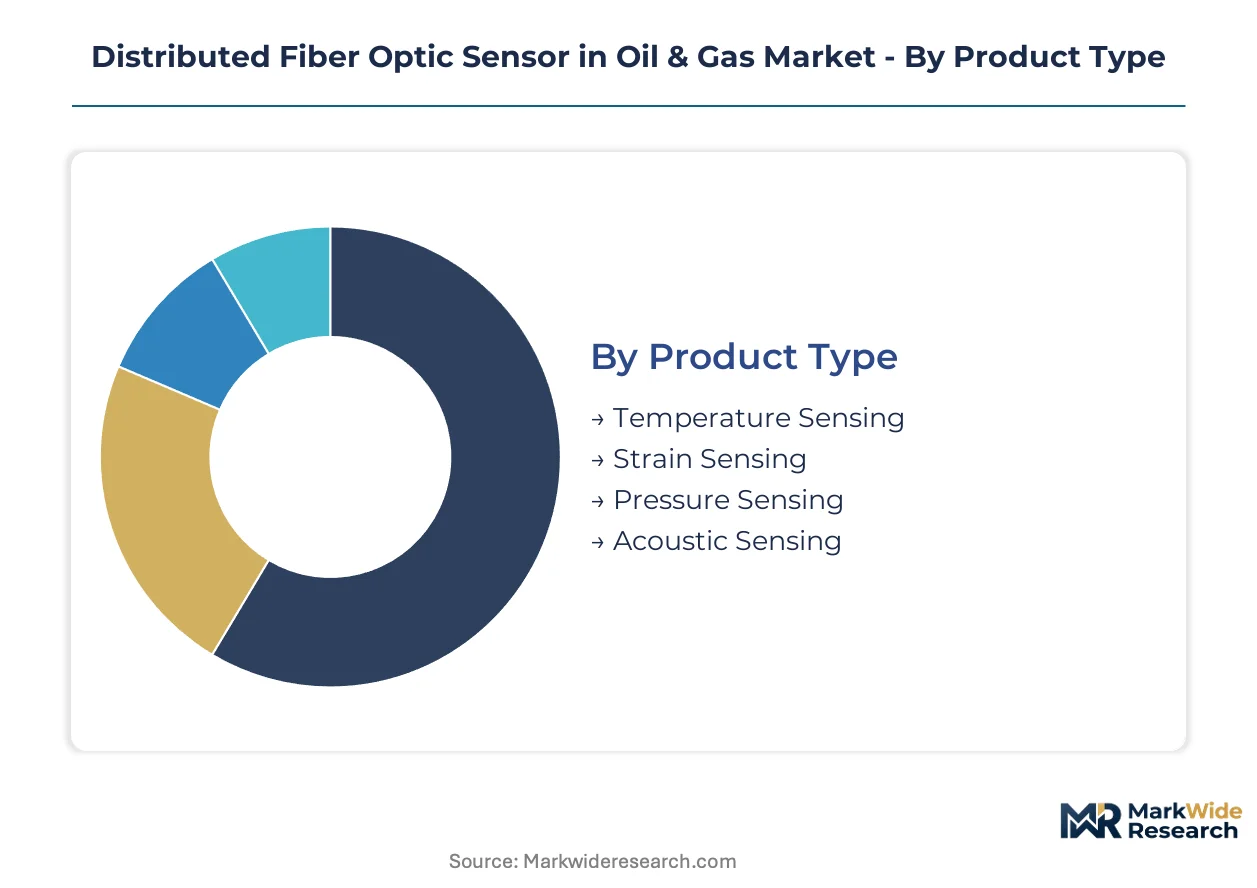
Capital allocation across sensing modalities and deployment environments determines competitive positioning in fiber optic monitoring. Operators prioritize segments offering the shortest payback periods on permanent downhole installations.
Product Type:
Temperature sensing commands the heaviest upfront interrogator investment, while acoustic sensing requires minimal incremental hardware beyond existing fiber infrastructure.
- Temperature Sensing:Raman scattering systems measure thermal gradients along wellbores with one-meter spatial resolution. Canadian oil sands operators in Alberta deploy distributed temperature sensing to optimize steam chamber geometry and reduce steam-to-oil ratios in thermal extraction.
- Acoustic Sensing:Distributed acoustic sensing captures vibration signatures through coherent Rayleigh backscatter analysis. Permian Basin operators apply this technology for real-time fracture geometry mapping during zipper frac operations, compressing optimization timelines from weeks to hours.
- Strain Sensing:Brillouin scattering systems monitor structural deformation in subsea risers and platform tendons where mechanical load verification exceeds thermal monitoring requirements.
- Pressure Sensing:Fiber Bragg grating arrays transduce downhole pressure into wavelength shifts for reservoir surveillance in high-pressure high-temperature wells.
Most installed capacity flows through temperature sensing. Expansion is steepest in acoustic sensing.
Installation:
Subsea deployments absorb capital at three to four times the intensity of surface installations due to wet-mate connector qualification and vessel spreads.
- Subsea:Permanent installations on subsea production trees require ISO 13628-7 qualified optical wet-mate connectors with extended lead times. Gulf of Mexico deepwater developments drive specification volumes as BSEE mandates real-time well integrity verification.
- Offshore:Platform-based interrogator systems monitor riser fatigue and flowline temperature profiles without subsea hardware exposure. North Sea installations accelerate under EU F-Gas Regulation leak detection requirements.
- Onshore:Land-based deployments leverage existing drilling infrastructure for cost-effective permanent monitoring in unconventional reservoirs.
- Surface:Pipeline right-of-way installations utilize telecommunications-grade fiber retrofits for third-party interference detection and leak localization.
Subsea installations carry the highest capital intensity per channel. Onshore retrofitting offers the lowest marginal deployment cost.
End User:
Procurement authority concentrates with operators holding reservoir data ownership, while service providers capture recurring revenue through asset performance contracting.
- Operators:Integrated oil companies specify fiber optic systems directly and retain raw data ownership for reservoir engineering workflows. Gulf of Mexico independents prioritize guaranteed measurement availability over capital ownership.
- Service Providers:Technology vendors assume interrogator lifecycle management under performance-based contracts, transferring obsolescence risk from capital-constrained producers.
- Contractors:Drilling and completions firms bundle fiber deployment with intelligent well system installation during initial construction phases.
- Asset Managers:Infrastructure-focused investors specify monitoring systems for pipeline networks and storage facilities under long-term concession agreements.
Operators control specification authority. Service providers are capturing the fastest-growing revenue share through contracting model innovation.
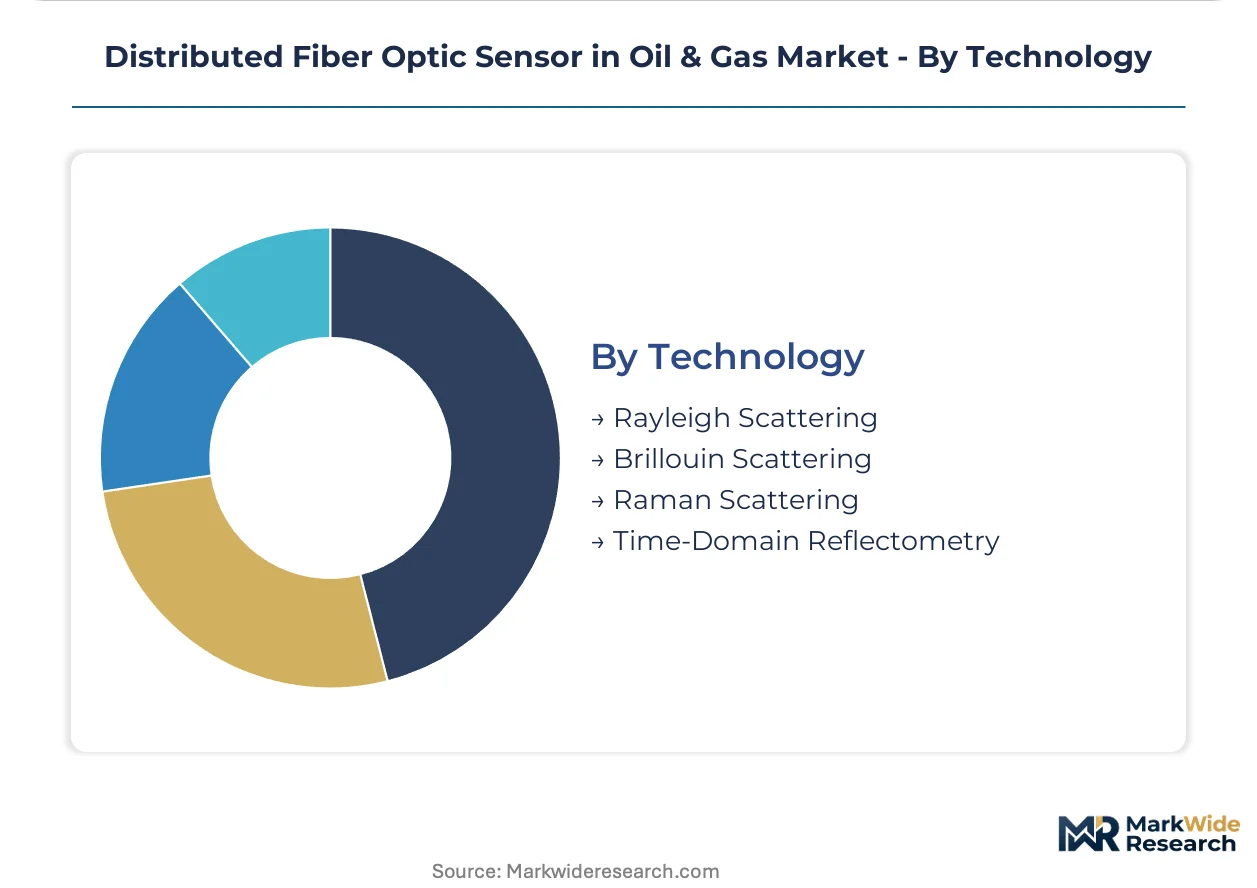
Technology:
Scattering physics selection determines hardware cost structure, with coherent detection systems demanding precision optics that limit supplier participation.
- Raman Scattering:Spontaneous Raman backscatter provides mature thermal profiling with standardized interrogator platforms. Steam-assisted gravity drainage operations in Alberta and California geothermal fields anchor commercial deployment.
- Rayleigh Scattering:Coherent detection of Rayleigh backscatter enables acoustic sensing sensitivity approaching conventional geophone arrays. Permian Basin zipper frac monitoring validates field performance.
- Brillouin Scattering:Coherent Brillouin systems measure strain and temperature simultaneously through frequency shift analysis, penetrating structural health monitoring where resolution demands exceed Raman capabilities.
- Time-Domain Reflectometry:OTDR-based systems locate fiber breaks and macro-bending losses for installation verification and maintenance troubleshooting.
Raman scattering dominates installed base. Rayleigh scattering methods are climbing the fastest as acoustic applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping capital deployment as operators migrate monitoring investments toward jurisdictions with explicit fiber optic qualification mandates. The cost-of-compliance gap between prescriptive regimes and permissive environments now exceeds installation economics for deepwater projects.
United States
Gulf of Mexico deepwater developments absorb the majority of subsea fiber optic capital as BSEE enforcement tightens well integrity verification requirements. The API RP 17N qualification protocol creates certified supplier lists that exclude unqualified bidders. Houston anchors the engineering ecosystem where SLB, Halliburton, and Baker Hughes coordinate subsea system integration.
Norway
North Sea electrification projects drive demand for all-electric subsea production networks with embedded fiber monitoring channels. The country's Petroleum Safety Authority mandates continuous leak detection that displaces conventional point sensors. Stavanger and Bergen host the subsea technology clusters where Equinor specifications set regional procurement standards.
United Kingdom
North Sea decommissioning schedules accelerate fiber retrofitting for late-life asset integrity monitoring before platform removal. The EU F-Gas Regulation applies post-Brexit through retained law, compelling methane detection system upgrades. Aberdeen concentrates service provider engineering centers for subsea intervention campaigns.
Canada
Alberta oil sands operators deploy distributed temperature sensing across steam-assisted gravity drainage pads to optimize steam chamber development. Provincial regulators enforce thermal efficiency reporting that rewards real-time monitoring adoption. Calgary anchors the thermal extraction technology supply chain where service providers bundle fiber systems with production optimization contracts.
Brazil
Pre-salt carbonate developments require high-pressure high-temperature monitoring solutions as Petrobras drills increasingly complex wells. The national petroleum regulator ANP mandates well integrity documentation that favors permanent fiber installations. Rio de Janeiro hosts the subsea engineering ecosystem where local content requirements shape supplier selection.
Distributed Fiber Optic Sensor in Oil & Gas Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated oilfield service providers controlling specification authority while component suppliers capture manufacturing economics. The vendor base concentrates around three strategic archetypes: full-service energy technology conglomerates with bundled offerings, pure-play fiber sensing specialists with interrogator hardware expertise, and telecommunications cable manufacturers extending into ruggedized oilfield variants. Consolidation pressure intensifies as operators reduce supplier counts through integrated service contracts. Technology licensing agreements and asset performance contracting represent the dominant competitive moves for securing recurring revenue streams.
Among the full-service archetype, SLB, Halliburton, and Baker Hughes occupy positions that exemplify integrated portfolio strategies. SLB anchors the drilling-through-production integration vector. Halliburton sits within the completions and intervention specialization tier. Baker Hughes represents the subsea systems and rotating equipment convergence point. These three entities structure competitive dynamics through bundled procurement offerings that collapse standalone component markets into comprehensive service agreements.
| Leading Market Players |
|---|
| SLB |
| Halliburton |
| Baker Hughes |
| Yokogawa Electric Corporation |
| Luna Innovations |
| OptaSense |
| Fotech Solutions |
| AP Sensing |
| OFS Fitel |
| Others |
Value Network & Pricing Analysis
API RP 17N certification tiers bifurcate procurement into qualified and unqualified supplier pools, concentrating pricing power with interrogator vendors holding BSEE-approved hardware while compressing margins for commodity cable producers serving non-mandated installations. This divergence manifests in supply chain configurations where certified component sourcing concentrates through Houston and Stavanger engineering clusters, while unqualified manufacturers face exclusion from Gulf of Mexico deepwater specifications.
Pricing Analysis
Direct-to-operator contracting eliminates distributor margins for asset performance arrangements, while project-based transactional pricing persists for capital-owned installations. Price differentiation rests on API certification tier and wet-mate connector qualification status, with BSEE-mandated hardware commanding substantial premiums over standard offshore variants. Pricing pressure stems from subsea electrification reducing addressable fiber channel counts per development. Independent operators in the Gulf of Mexico exhibit highest price sensitivity, prioritizing guaranteed measurement availability over capital ownership.
Supply Chain Analysis
Brazil's local-content mandates under ANP regulations reshape sourcing patterns, compelling Petrobras suppliers to establish Rio de Janeiro manufacturing footprints for pre-salt project participation. Specialty fiber drawing concentrates in Japan, Germany, and the United States, while ruggedized cable armoring feeds from South Korean and Chinese metalworking facilities. Raw material dependencies include high-purity silica preforms, hermetic sealing alloys, and fluoropolymer coatings. Single-source vulnerability concentrates in coherent detection laser modules. Distribution runs through integrated service providers bundling interrogator hardware with lifecycle management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in acoustic sensing applications where coherent Rayleigh interrogators displace conventional geophone arrays, capturing value from Permian Basin zipper frac optimization demand while production cost curves flatten through semiconductor laser commoditization.
For Market Incumbents: Deepen backward integration into specialty fiber preform manufacturing to secure supply continuity against East Asian trade friction. Lock in BSEE certification maintenance through sustained R&D investment in high-temperature optical packaging. Defensive positioning requires absorbing wet-mate connector qualification lead times through inventory pre-positioning, countering emerging pure-play specialists with faster deployment cycles. For New Entrants and Emerging Players: Geothermal developers in Nevada and Utah present an underserved buyer archetype with monitoring requirements unmet by incumbent oilfield service bundling. CCUS plume tracking applications offer penetrable white space where regulatory monitoring mandates precede established supplier relationships. Go-to-market execution should emphasize interrogator-as-a-service contracting, transferring capital burden from project developers to technology vendors. For Investors and Strategic Acquirers: Consolidation pressure builds where coherent detection hardware expertise concentrates in fragmented specialist firms lacking scale for integrated service contracting. Long-term viability favors vendors with balance sheet capacity to assume asset performance obligations across multi-decade offshore field lifecycles. Acquisition target archetype: pure-play fiber sensing specialists with proven API RP 17N qualification and established Equinor or Petrobras specifications. Signal to watch: BSEE expansion of real-time monitoring mandates to marginal HPHT well categories.| Strategic Initiative | Industry Significance |
|---|---|
| API RP 17N Certification Investment | BSEE enforcement creates qualified supplier lists excluding uncertified competitors from Gulf of Mexico procurement. |
| Coherent Detection Hardware Acquisition | Rayleigh scattering sensitivity gains displace geophone arrays in Permian Basin fracture mapping applications. |
| Asset Performance Contracting Expansion | Operators transfer interrogator obsolescence risk to vendors with balance sheet capacity for lifecycle management. |
| Geothermal Monitoring Market Entry | Enhanced geothermal systems in Nevada and Utah present untapped demand for distributed temperature and acoustic sensing. |
| CCUS Plume Tracking Capability Buildout | Carbon storage operators require continuous pressure and temperature monitoring for injection zone conformance verification. |
Research Methodology
Multiple input streams — primary interviews with subsea systems engineers, fiber optic interrogator product managers, and BSEE regulatory compliance officers; secondary validation through API standards documentation, BSEE enforcement bulletins, and Petrobras technical specifications; plus customs trade data on specialty fiber imports — were reconciled through bottom-up installation tracking and top-down operator capital expenditure triangulation.
Data-stream reconciliation across sensing modality, deployment environment, and end-user procurement authority dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installation volume trajectories and unit economics modeling across Raman, Rayleigh, and Brillouin scattering technology categories. Forecast inputs incorporated subsea electrification channel count compression, EU F-Gas Regulation leak detection mandate timing, and thermal extraction steam-to-oil ratio optimization adoption curves.
Underlying measurement precision varies by segment; subsea installations with disclosed operator names carry tighter precision than speculative pre-salt developments. Forecasts reflect assumptions on regulatory mandate expansion, coherent detection cost curves, and trade policy continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle-East and Africa Frac Stack Market
Oil & Gas
Azerbaijan Oil and Gas Downstream Market
Oil & Gas
APAC Oil and Gas Automation Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
Downhole Drilling Tools Market
Oil & Gas
Europe Oilfield Equipment Rental Services Market
Oil & Gas
North America Coiled Tubing Services Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Crown Block Market
Oil & Gas
Oil Country Tubular Goods (OCTG) Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Oil and Gas Storage Market