
 Asthma Device Market | 2026-2036
Asthma Device Market Size, Share, and Industry Trends Forecast 2026-2036
Asthma Device Market Outlook
Connected inhaler subscription services that bundle sensors, apps, and clinician dashboards is restructuring how pharmaceutical firms monetize respiratory care. AstraZeneca leverages its digital health partnerships to anchor patient adherence programs across European markets. GlaxoSmithKline dominates the maintenance inhaler segment through manufacturing scale and long-standing formulary relationships. Teva Pharmaceuticals differentiates via generic complex-device portfolios that compete on price in emerging markets.
Asthma devices comprise metered-dose inhalers, dry-powder inhalers, soft-mist systems, nebulizers, spacers, and peak flow meters engineered to deliver bronchodilators or corticosteroids with particle sizes between one and five microns for optimal lower-airway deposition. Their primary purpose centers on controlling chronic airway inflammation and reversing acute bronchospasm in reversible obstructive pulmonary conditions. Smart inhalers incorporating Bluetooth connectivity and dose-capture technology represent the fastest-expanding technology segment as payers demand adherence documentation. Dry powder inhalers occupy the largest product-type position due to their propellant-free design and compatibility with lactose carrier formulations, though soft-mist devices are gaining share among elderly patients who struggle with hand-breath coordination.
The FDA's Center for Devices and Radiological Health oversees connected inhaler premarket submissions, while the EMA's MDR framework imposes stricter clinical evidence requirements for reusable electronic components. BIS certification in India and CDSCO registration timelines shape market entry sequencing for multinational manufacturers. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as these determine whether connected-device premiums convert to sustainable revenue streams or remain cost centers.
Market Dynamics
Connected inhaler ecosystems are restructuring asthma device economics by shifting revenue from hardware sales toward adherence-data subscriptions and remote monitoring reimbursements.
Growth Catalysts
- Homecare Migration:Hospital-to-home transitions in chronic respiratory management are expanding device deployment outside clinical settings. Reimbursement codes for remote patient monitoring in the United States validate this channel shift.
- EMA MDR Compliance:Stricter clinical evidence requirements for reusable electronic components are accelerating investment in durable, high-quality connected inhaler platforms that command premium positioning.
- Soft-Mist Coordination:Elderly populations struggling with hand-breath synchronization are driving demand for propellant-free delivery systems that reduce technique-dependent dosing failures.
Market Restraints
- Lithium Supply Concentration:Battery chemistry for connected inhaler sensors depends on processing capacity concentrated in East Asian supply chains, creating input vulnerability.
- FDA Premarket Burden:Center for Devices and Radiological Health submission requirements for Bluetooth-enabled inhalers extend development timelines and compress returns on digital health investments.
- Nebulizer Substitution:Acute care settings retain preference for jet and mesh nebulization in severe exacerbations, limiting maintenance inhaler penetration in hospital discharge protocols.
Strategic Opportunities
- Indian CDSCO Pathways:Accelerated registration timelines for quality-certified devices create first-mover advantage in a market with rising asthma prevalence and expanding insurance coverage.
- AI-Enabled Dose Optimization:Machine learning integration with peak flow data and environmental triggers represents unoccupied white space in personalized bronchodilator timing.
- Direct-to-Patient Subscription:Bypassing traditional pharmacy distribution through sensor-app-clinician bundles captures adherence data value that wholesale channels forfeit.
Industry Challenges
- Embedded Firmware Expertise:Convergence of medical device validation with consumer electronics development cycles requires talent pools that traditional respiratory manufacturers lack.
- Legacy Inhaler Integration:Retrofitting Bluetooth sensors onto existing MDI and DPI form factors without disrupting established manufacturing lines demands capital-intensive production reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asthma Device Market |
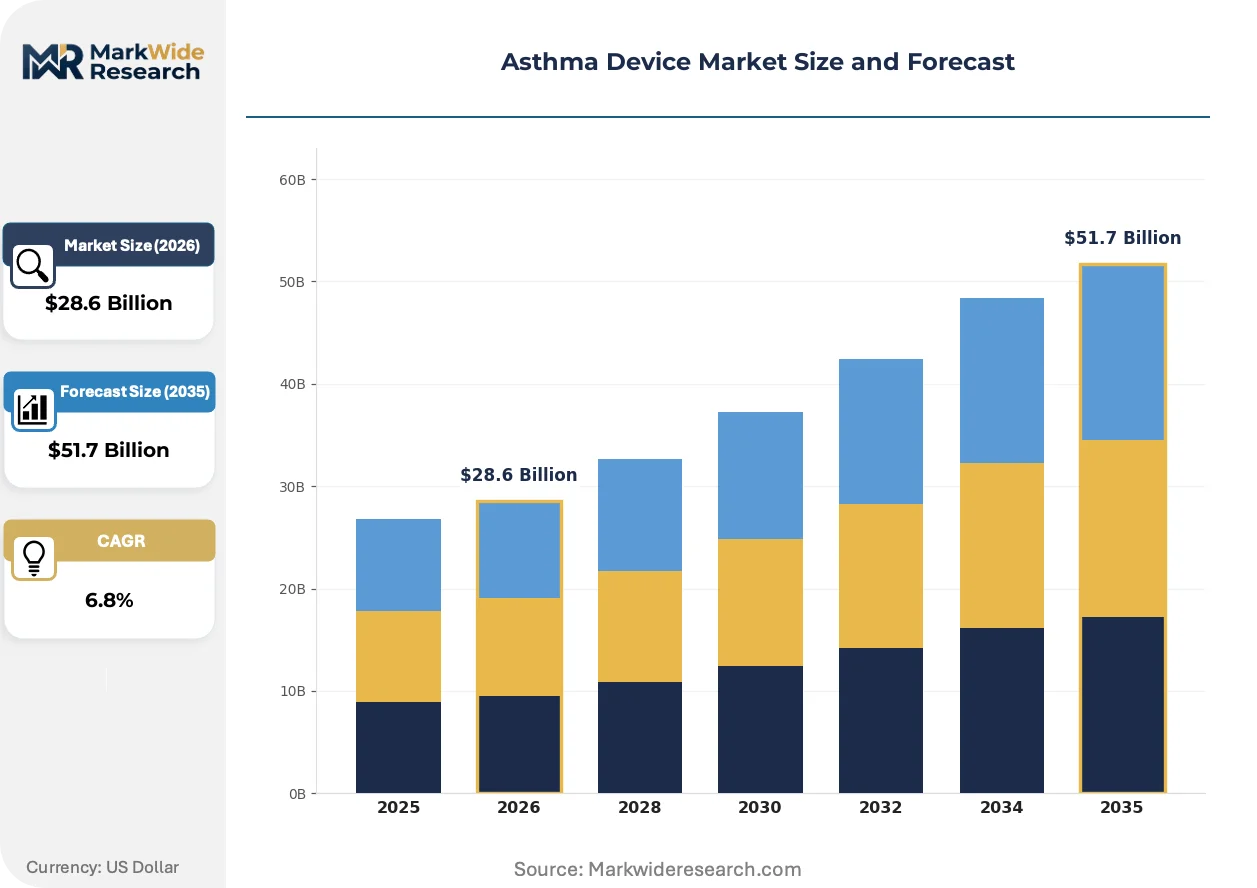
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
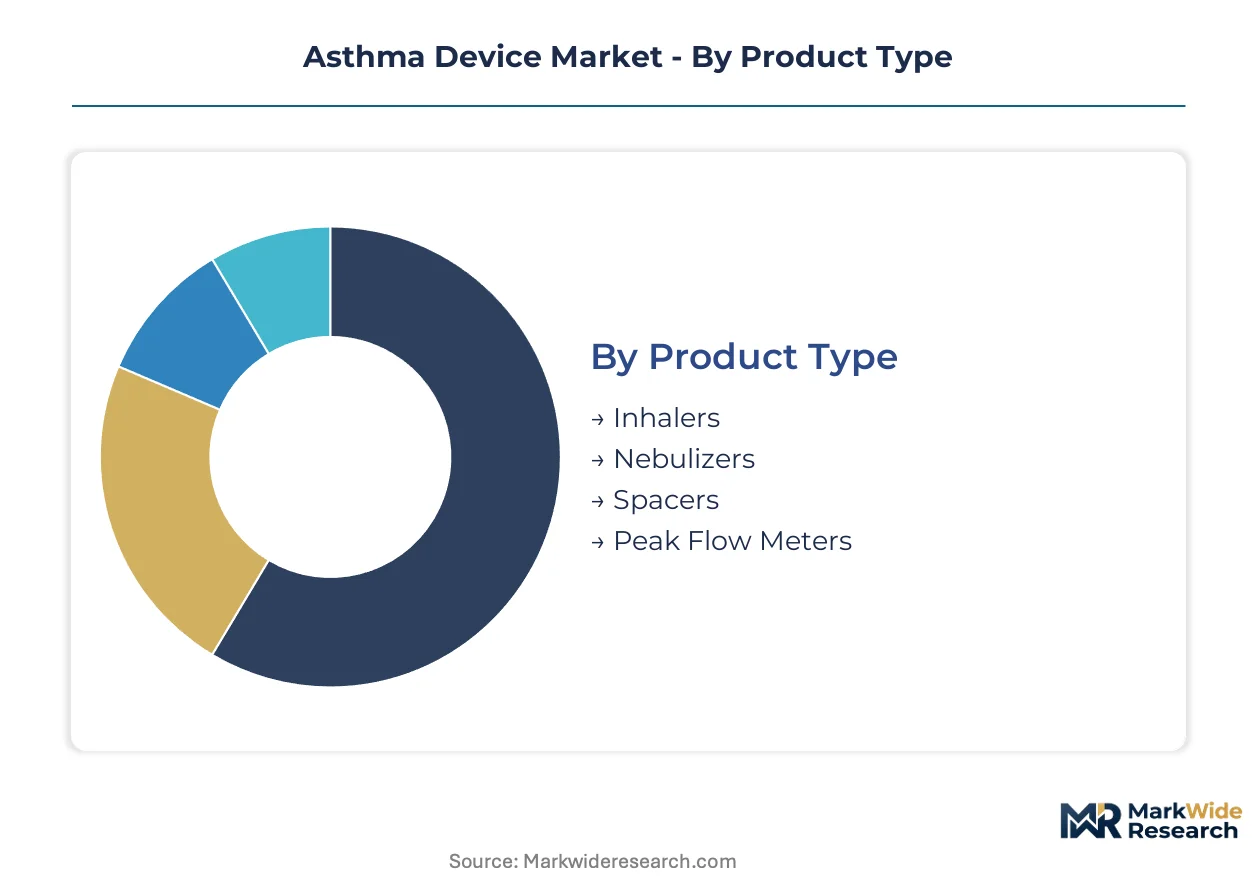
| Segmentation | Product Type: Inhalers, Nebulizers, Spacers, Peak Flow Meters Technology: Dry Powder, Metered Dose, Soft Mist, Smart Inhalers End User: Pediatrics, Adults, Elderly, Healthcare Providers Application: Chronic Management, Emergency Relief, Preventive Care, Monitoring |
| Companies Covered | GlaxoSmithKline, AstraZeneca, Koninklijke Philips, Cipla, Boehringer Ingelheim, Teva Pharmaceuticals, ResMed, Merck, Chiesi Farmaceutici, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asthma Device Market Strategic Shifts
Digital biomarker capture and propellant chemistry advances are converging to redefine how asthma control is measured, monetized, and delivered across care settings.
Bluetooth-enabled dose-capture technology is decentralizing asthma management authority from pulmonology clinics toward primary care networks and patient self-monitoring. Community health centers in the United States are deploying these systems to reduce specialist referral bottlenecks. The structural consequence is compressing the interval between symptom onset and therapeutic adjustment from weeks to hours.
REACH restrictions on fluorinated greenhouse gases are forcing reformulation of pressurized metered-dose inhaler propellants across European manufacturing. Transition costs are concentrating among legacy HFA-227a dependent portfolios. Dry powder and soft-mist alternatives are capturing displaced volume as pharmaceutical sponsors accelerate lactose-carrier and aqueous solution development programs.
Outcome-based contracting between payers and device manufacturers is replacing traditional unit purchase arrangements in United States commercial insurance segments. Risk-sharing agreements tie reimbursement to documented adherence thresholds and reduced exacerbation rates. This shift is most visible in Medicare Advantage plans integrating remote monitoring into chronic care management billing codes.
Asthma Device Market Segmentation
Device segmentation in respiratory care determines reimbursement pathways, manufacturing scale requirements, and regulatory submission strategies. Technology differentiation separates premium-connected systems from commodity hardware, while end-user demographics dictate dose-delivery specifications and patient-interface design priorities.
Product Type:
Delivery mechanism architecture defines particle deposition efficiency, portability constraints, and maintenance protocols across patient environments.
- Inhalers:Pressurized metered-dose and dry-powder systems dominate prescription volumes through compact form factors compatible with daily carry. Hand-breath coordination requirements limit efficacy among elderly populations in Japan and Germany, driving demand for breath-actuated alternatives.
- Nebulizers:Jet and mesh systems convert liquid bronchodilators into respirable aerosols for patients unable to execute proper inhaler technique. Acute care settings in the United States retain nebulizer preference for severe exacerbation management despite higher per-dose cost versus handheld alternatives.
- Spacers:Valved holding chambers improve lung deposition for MDI users by eliminating hand-breath synchronization demands. Pediatric prescriptions in France and the United Kingdom increasingly bundle spacers with initial corticosteroid inhaler dispensing.
- Peak Flow Meters:Mechanical and digital devices quantify expiratory flow rates for home-based asthma action plan implementation. Primary care networks in Australia deploy these for remote symptom triage between specialist appointments.
Inhalers lead on scale; smart-connected variants lead on momentum.
Technology:
Propellant chemistry and electronic integration differentiate device tiers across regulatory jurisdictions and reimbursement codes.
- Dry Powder:Breath-activated systems eliminate propellant dependence through micronized drug-lactose blends. EMA REACH compliance pressures on fluorinated greenhouse gases accelerate European adoption of HFA-free alternatives.
- Metered Dose:Pressurized systems using HFA-134a or HFA-227a propellants retain formulary dominance through established clinical evidence bases. Reformulation costs concentrate among legacy portfolios as F-Gas Regulation deadlines approach.
- Soft Mist:Aqueous solution mechanical pumps generate slow-moving aerosol clouds requiring minimal patient coordination. Elderly patient populations in Germany and Italy drive fastest volume expansion for this mechanically-driven category.
- Smart Inhalers:Bluetooth-enabled dose-capture sensors integrated with clinician dashboards transform adherence documentation into reimbursable remote monitoring. FDA Center for Devices and Radiological Health premarket requirements extend development timelines but validate premium positioning in United States Medicare Advantage contracts.
Dry powder leads on scale; smart inhalers gain share fastest.
End User:
Physiological development stage and care setting determine device specification requirements and distribution channel selection.
- Pediatrics:Face mask attachments, reduced dose volumes, and gamified adherence applications characterize device design for patients under twelve. School-based asthma management programs in the United States drive institutional procurement of nebulizer systems.
- Adults:Working-age patients prioritize portable form factors compatible with occupational environments and travel patterns. Employer-sponsored health plans in Japan subsidize connected inhaler subscriptions through chronic disease management carve-outs.
- Elderly:Arthritic hand limitations and cognitive load constraints demand simplified actuation mechanisms and caregiver notification features. National health service formularies in the United Kingdom increasingly restrict reimbursement to breath-coordination-independent systems for patients over seventy-five.
- Healthcare Providers:Hospitals, clinics, and emergency departments specify devices based on sterilization protocols, multi-patient durability, and electronic health record integration requirements.
Adults lead on scale; elderly leads on momentum.
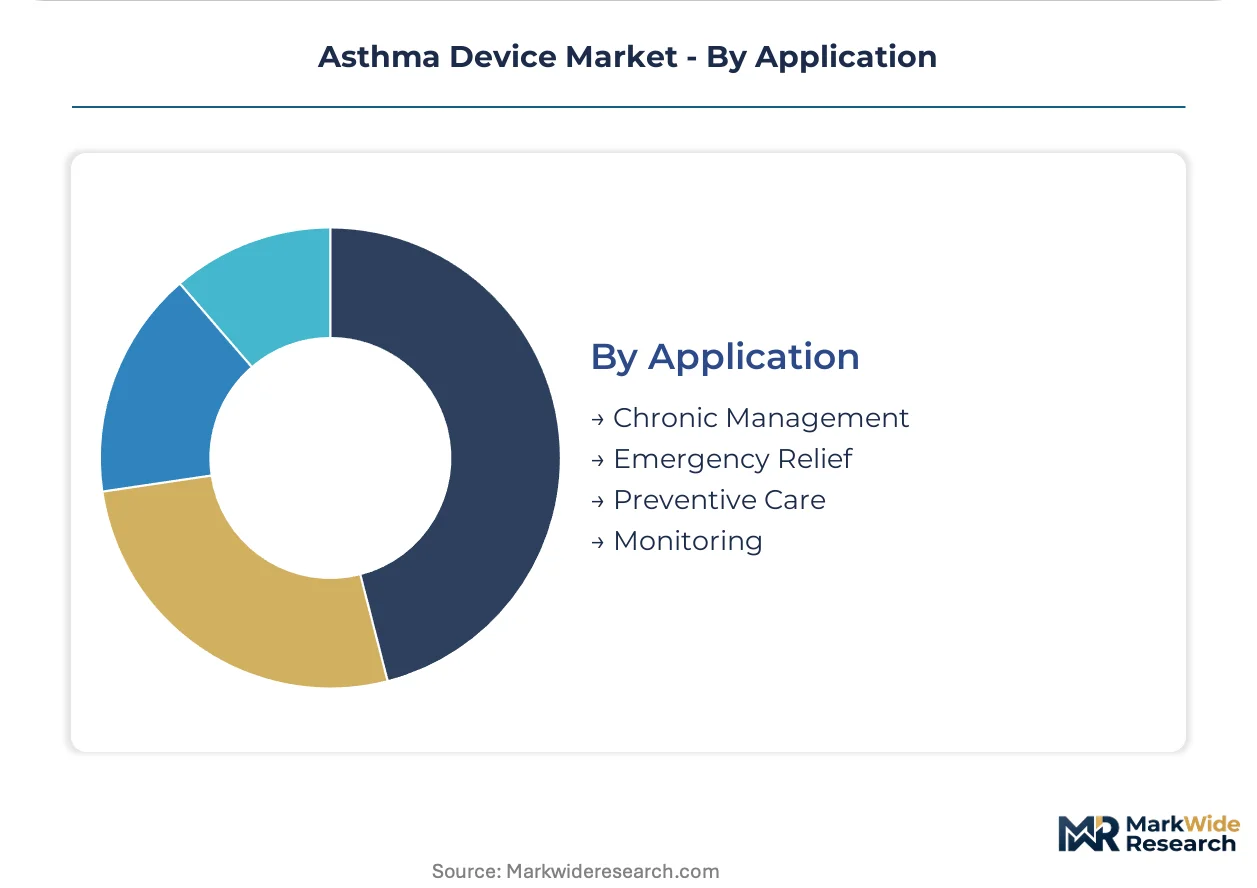
Application:
Clinical objective determines dosing frequency, therapeutic agent selection, and monitoring intensity across care pathways.
- Chronic Management:Daily corticosteroid maintenance therapy requires consistent deposition patterns and adherence verification. Outcome-based contracts between United States payers and manufacturers tie reimbursement to documented controller medication persistence rates.
- Emergency Relief:Short-acting beta-agonist rescue therapy demands rapid bronchodilation with minimal technique dependency. Emergency department discharge protocols in Canada increasingly substitute nebulized albuterol with breath-actuated inhaler plus spacer combinations.
- Preventive Care:Pre-exercise bronchodilation and allergen-triggered prophylaxis utilize on-demand dosing with portable devices. Athletic programs in Australian schools stock reliever inhalers with spacers for field-side access.
- Monitoring:Digital biomarker capture through peak flow tracking and symptom logging enables predictive exacerbation alerts. Primary care networks in Germany deploy these systems to reduce pulmonology referral bottlenecks.
Chronic management leads on scale; monitoring leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement frameworks reward connected inhaler adherence documentation more generously than Germany's statutory health insurance system, creating divergent penetration rates for smart delivery systems across these two high-income markets.
United States
Medicare Advantage chronic care management billing codes and commercial insurer outcome-based contracts accelerate smart inhaler deployment. FDA Center for Devices and Radiological Health premarket requirements for Bluetooth-enabled systems extend development timelines but validate premium positioning. The Boston-Cambridge corridor concentrates digital health startups partnering with pharmaceutical sponsors on remote monitoring platforms.
Germany
Elderly populations struggling with hand-breath coordination drive soft-mist inhaler demand in statutory health insurance formularies. EMA MDR compliance requirements for reusable electronic components impose stricter clinical evidence standards than legacy device frameworks. The Rhine-Ruhr industrial belt hosts manufacturing facilities transitioning HFA-dependent pressurized metered-dose portfolios toward propellant-free alternatives under REACH F-Gas Regulation deadlines.
India
Rising asthma prevalence in urban centers and expanding private health insurance coverage create demand for affordable dry-powder devices. CDSCO accelerated registration timelines for quality-certified products enable faster market entry than historical regulatory pathways. The Mumbai-Pune pharmaceutical cluster anchors domestic manufacturing of lactose-carrier formulations and breath-actuated inhaler mechanisms for regional export.
Japan
Employer-sponsored chronic disease management carve-outs subsidize connected inhaler subscriptions for working-age adults. METI standards for medical device software interoperability shape domestic platform requirements for Bluetooth dose-capture systems. The Osaka-Kobe medical technology corridor concentrates electronics manufacturers supplying sensor components to respiratory device assemblers.
United Kingdom
National Health Service formularies increasingly restrict reimbursement to breath-coordination-independent systems for patients over seventy-five. MHRA post-Brexit regulatory autonomy maintains alignment with EMA MDR frameworks while streamlining domestic approval pathways. The Cambridge-London life sciences corridor hosts clinical trial networks validating digital biomarker integration with primary care asthma management protocols.
Asthma Device Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-origin firms dominating maintenance therapy portfolios while electronics-integrated system suppliers capture connected device premiums. The vendor base concentrates among respiratory-dedicated divisions of diversified healthcare conglomerates and mid-scale device specialists with regional manufacturing footprints. Three archetypes define competitive positioning: vertically integrated pharmaceutical-device combinations, standalone digital health platform developers, and generic complex-device price competitors. Strategic moves center on outcome-based payer contracting and backward integration into sensor component supply.
Within the pharmaceutical-device combination tier, GlaxoSmithKline and AstraZeneca exemplify vertically integrated positioning spanning molecule development through delivery system manufacturing. Teva Pharmaceuticals occupies a distinct archetype as a generic complex-device specialist competing on manufacturing scale in emerging markets. Koninklijke Philips represents the electronics-healthcare convergence model, anchoring connected respiratory monitoring platforms through its medical technology division.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AstraZeneca |
| Koninklijke Philips |
| Cipla |
| Boehringer Ingelheim |
| Teva Pharmaceuticals |
| ResMed |
| Merck |
| Chiesi Farmaceutici |
| Others |
Value Chain & Pricing Dynamics
Medicare Advantage outcome-based contracting in the United States is forcing device manufacturers to absorb adherence-verification costs into subscription pricing, compelling supply chain reconfiguration toward sensor-integrated production lines and compressing margins on legacy hardware-only portfolios.
Pricing Analysis
Capacity additions in China's sensor component ecosystem are reshaping price floors for Bluetooth-enabled dose-capture modules. Pricing stratifies across premium connected systems, standard breath-actuated devices, and economy dry-powder alternatives, with FDA premarket certification tiers and manufacturing scale as primary differentiation drivers. Cost compression in the standard tier is intensifying because Indian CDSCO-accelerated pathways enable generic complex-device competition. Pediatric and elderly segments demonstrate highest price sensitivity due to reimbursement formula limitations, while Medicare Advantage chronic care management carve-outs show lowest sensitivity for documented adherence solutions.
Supply Chain Analysis
Freight cost volatility from East Asian electronics hubs to European assembly plants is elevating landed costs for lithium-ion sensor batteries and Bluetooth module chipsets. Component manufacturing concentrates in China, South Korea, and Japan, with final device assembly anchored in Germany, India, and the United States. Raw material dependencies span pharmaceutical-grade lactose carriers, HFA propellant alternatives, and medical-device-certified lithium cells. Single-source vulnerability in rare earth magnet supply for soft-mist mechanical pumps creates exposure. Distribution runs through pharmaceutical wholesale networks in developed markets and direct-to-hospital procurement in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The asthma device market functions as a stable compounder anchored by irreversible homecare migration and chronic disease management reimbursement expansion across high-income health systems.
For Market Incumbents: Anticipate substitution pressure from generic complex-device manufacturers in India and CDSCO-accelerated entrants by securing backward integration into sensor component supply. Defensive priorities center on outcome-based payer contracting capabilities and EMA MDR-compliant reusable electronic platform durability. Capacity expansion in the Mumbai-Pune pharmaceutical cluster preserves emerging market margin structure against price competitors. For New Entrants and Emerging Players: Capture the elderly patient segment in Germany and Italy where hand-breath coordination failures create soft-mist inhaler demand that incumbent portfolios underserve. The most penetrable white space sits in AI-enabled dose optimization integrating peak flow data with environmental trigger algorithms. Direct-to-patient subscription models bypassing traditional pharmacy distribution offer the clearest go-to-market angle for adherence-data monetization. For Investors and Strategic Acquirers: Asymmetric upside sits with standalone digital health platform developers possessing FDA premarket submission experience and clinician dashboard integration capabilities. Long-term viability over the extended investment horizon favors archetypes with recurring revenue from remote monitoring reimbursements rather than transactional hardware sales. The signal to watch is Medicare Advantage plan expansion of chronic care management billing codes for connected inhaler adherence documentation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Submission | Bluetooth-enabled dose-capture systems require CDRH validation for Medicare Advantage reimbursement eligibility. |
| EMA MDR Compliance Pathway | Reusable electronic components face stricter clinical evidence standards than legacy device frameworks in Europe. |
| Hospital System Partnership | Community health centers in the United States deploy connected inhalers to reduce pulmonology referral bottlenecks. |
| Software Companion Development | Gamified adherence applications differentiate pediatric device portfolios and improve controller medication persistence. |
| Reimbursement Strategy | Remote patient monitoring coding integration determines whether connected-device premiums convert to sustainable revenue. |
Study Parameters
Direct dialogue with regulatory affairs specialists, hospital procurement managers, GPO contracts directors, and biomedical engineers grounded the qualitative foundation, cross-referenced against FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement code updates, and hospital procurement contract repositories. Bottom-up manufacturer shipment estimates triangulated with top-down payer expenditure analysis across the analysis window.
Segment-level value outputs reflect modeled projections across device type, technology tier, end-user demographic, and application purpose, with CAGRs derived from historical volume trajectories and regulatory event timing. Forecast inputs incorporated REACH F-Gas Regulation compliance deadlines, CDSCO registration pathway velocity, and Medicare Advantage chronic care management billing code expansion patterns.
Underlying measurement precision varies by segment; smart inhaler and connected monitoring categories carry tighter precision than commodity nebulizer and spacer estimates due to reimbursement code volatility. Forecasts reflect documented assumptions about regulatory timeline adherence and payer policy continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Insulin Storage Devices Market
Medical Devices
Global Voice Prosthesis Devices Market
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Enteral Feeding Devices Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Pneumology Digital Stethoscope Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Laryngoscopes Market
Medical Devices
Automated Insulin Delivery Device Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Canada Varicose Vein Treatment Devices Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
US External Counterpulsation Devices Market
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market
Medical Devices
Global Medical Kiosk Market
Medical Devices
Global Surgical Microscopes Market