
 Australia Flexible Office Space Market | 2026-2036
Australia Flexible Office Space Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Flexible Office Space Market Outlook
Hybrid-work skill redistribution is redrawing tenant demand patterns across Australian central business districts. Hub Australia leverages its design-led community programming to sustain premium occupancy in Melbourne and Sydney. Servcorp anchors its competitive position through backward integration into proprietary IT infrastructure and concierge systems. WeWork navigates restructuring headwinds while maintaining scale advantages in Brisbane and Perth submarkets.
Flexible office space denotes commercially operated work environments offering short-duration occupancy agreements, shared amenities, and modular fit-outs typically ranging from individual desks to multi-floor suites, purpose-built for enterprises seeking capital-light real estate exposure. Coworking spaces and serviced offices dominate transaction volume, with private offices capturing disproportionate margin pools from legal and consulting tenants. Membership plans and short-term rentals are expanding fastest among startups and SMEs, while long-term lease structures retain share among large corporations seeking cost certainty without balance-sheet property commitments.
TGA workplace health guidelines intersect with state-level WorkSafe Australia requirements to shape ventilation, density, and ergonomic standards across flexible office portfolios. The Australian Building Codes Board's National Construction Code revisions directly influence refurbishment economics and accessibility compliance for operators. The Australian Competition and Consumer Commission's oversight of lease term transparency affects contract structuring and tenant switching costs. Stakeholders must monitor how impending state-based planning law amendments around commercial-to-residential conversion rights reshape supply availability in inner-urban corridors.
Market Dynamics
The Australian Building Codes Board's National Construction Code revisions are forcing a wholesale retrofit cycle across flexible office portfolios, compressing operator margins while accelerating compliance-driven capital deployment.
Growth Catalysts
- Transit-oriented development clusters:Melbourne's inner-northern precincts concentrate demand where rail infrastructure supports hybrid commuting patterns. Density bonuses in these corridors accelerate flexible lease uptake.
- WorkSafe Australia ventilation mandates:Post-pandemic density standards create retrofit demand that operators convert into premium positioning. Compliance investments differentiate incumbent portfolios.
- Technology sector normalization:Enterprise tenants in Sydney and Melbourne are expanding satellite footprints as hybrid policies stabilize. This segment drives multi-floor suite absorption.
Market Restraints
- Construction input volatility:Steel and glazing cost swings distort refurbishment economics for heritage building conversions. Operators face margin compression on fixed-price fit-out contracts.
- Landlord concentration in Sydney CBD:A handful of institutional owners control prime grade-A stock, limiting operator negotiating leverage on lease terms.
- Regulatory friction from ACCC:The Australian Competition and Consumer Commission's lease transparency requirements increase contract complexity and tenant switching facilitation.
Strategic Opportunities
- Brisbane submarket underpenetration:Relative to Sydney and Melbourne, flexible stock per capita remains sparse. Early movers capture price-setting power before supply catches demand.
- Commercial-to-residential conversion rights:Impending state planning law amendments may release inner-urban stock. Operators with conversion capabilities access supply others cannot.
- Building management system convergence:Integration of IoT sensors with energy optimization platforms enables outcome-based service pricing. This technology pairing differentiates premium offerings.
Industry Challenges
- Building certification timeline compression:The Australian Building Codes Board's phased implementation creates overlapping compliance windows. Operators must sequence retrofits without displacing occupied revenue.
- Workplace health guideline fragmentation:TGA guidance intersects unevenly with state WorkSafe requirements. Multi-state operators face duplicated compliance investment.
- Legacy lease integration:Traditional commercial tenants carry break-option timing that conflicts with flexible operator revenue models. Portfolio acquisitions require complex lease restructuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Flexible Office Space Market |
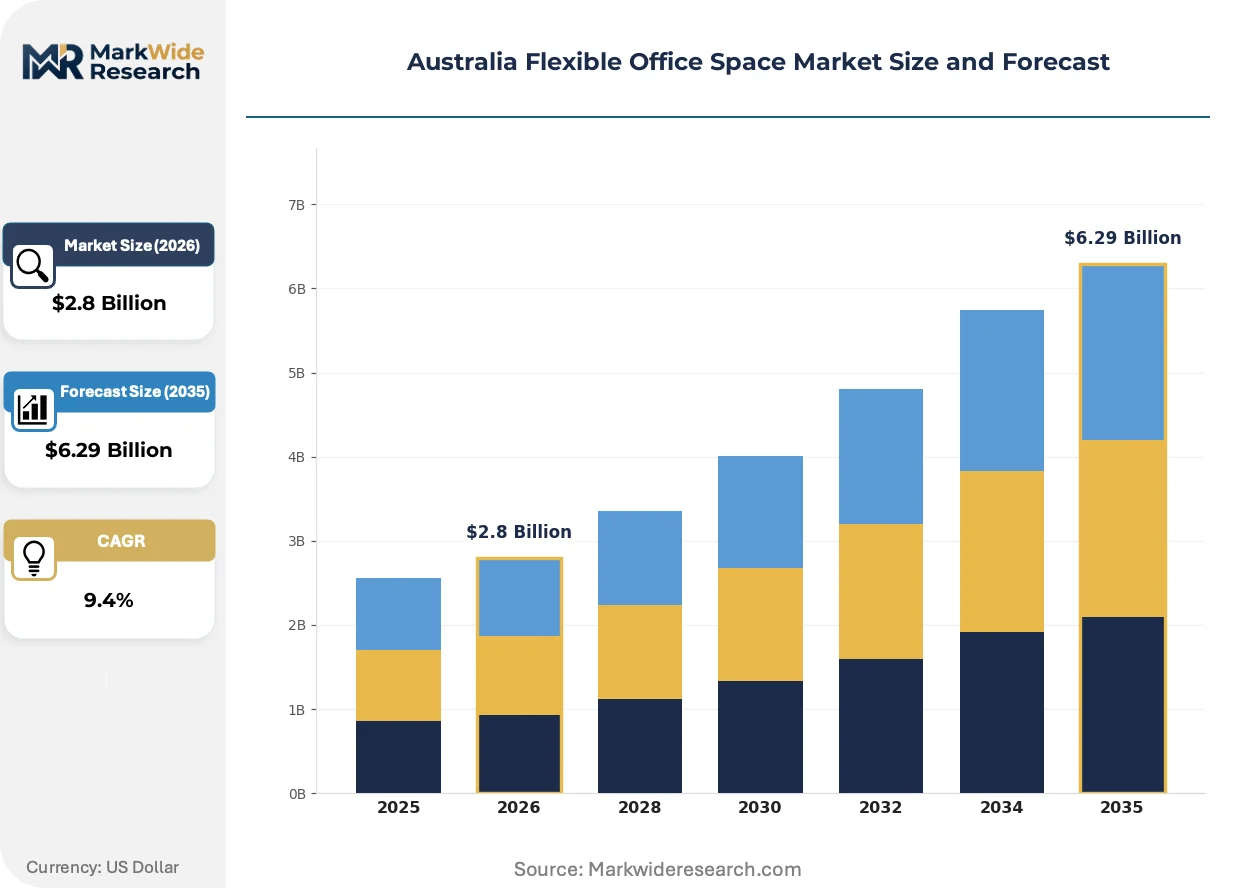
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Office Type: Coworking Spaces, Hot Desking, Private Offices, Serviced Offices Usage Model: Short-Term Rentals, Long-Term Leases, Pay-As-You-Go, Membership Plans Facility Size: Small Scale, Medium Scale, Large Scale, Enterprise Level Client Sector: Startups, SMEs, Large Corporations, Freelancers |
| Companies Covered | Servcorp, Flexible Workspace Australia (FWA), Hub Australia, Tank Stream Labs, The Commons, IWG PLC, WeWork, DeskSpace, interoffice Australia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Flexible Office Space Market Strategic Shifts
Sensor-integrated workspace management is actively fragmenting how operators price occupancy, shifting from per-desk to utilization-based models that align revenue with actual consumption patterns.
Smart building platforms are fragmenting the traditional landlord-operator boundary. These systems capture real-time occupancy, air quality, and energy data. Large corporate tenants now demand API access to this infrastructure. The technology is fragmenting lease negotiations into data-access clauses separate from square-meterage terms.
The Australian Building Codes Board's National Construction Code 2022 energy efficiency standards are mandating minimum performance thresholds for commercial retrofits. These rules compress payback periods for high-specification HVAC and glazing investments. Operators in Melbourne and Sydney are responding by clustering premium stock in buildings that exceed baseline requirements.
Enterprise procurement teams are consolidating vendor relationships across property portfolios. This behavior concentrates contract value with multi-city operators capable of standardized service delivery. The shift is most visible among legal and consulting tenants seeking consistent workplace experience across Sydney, Melbourne, and Brisbane locations.
Australia Flexible Office Space Market Segmentation
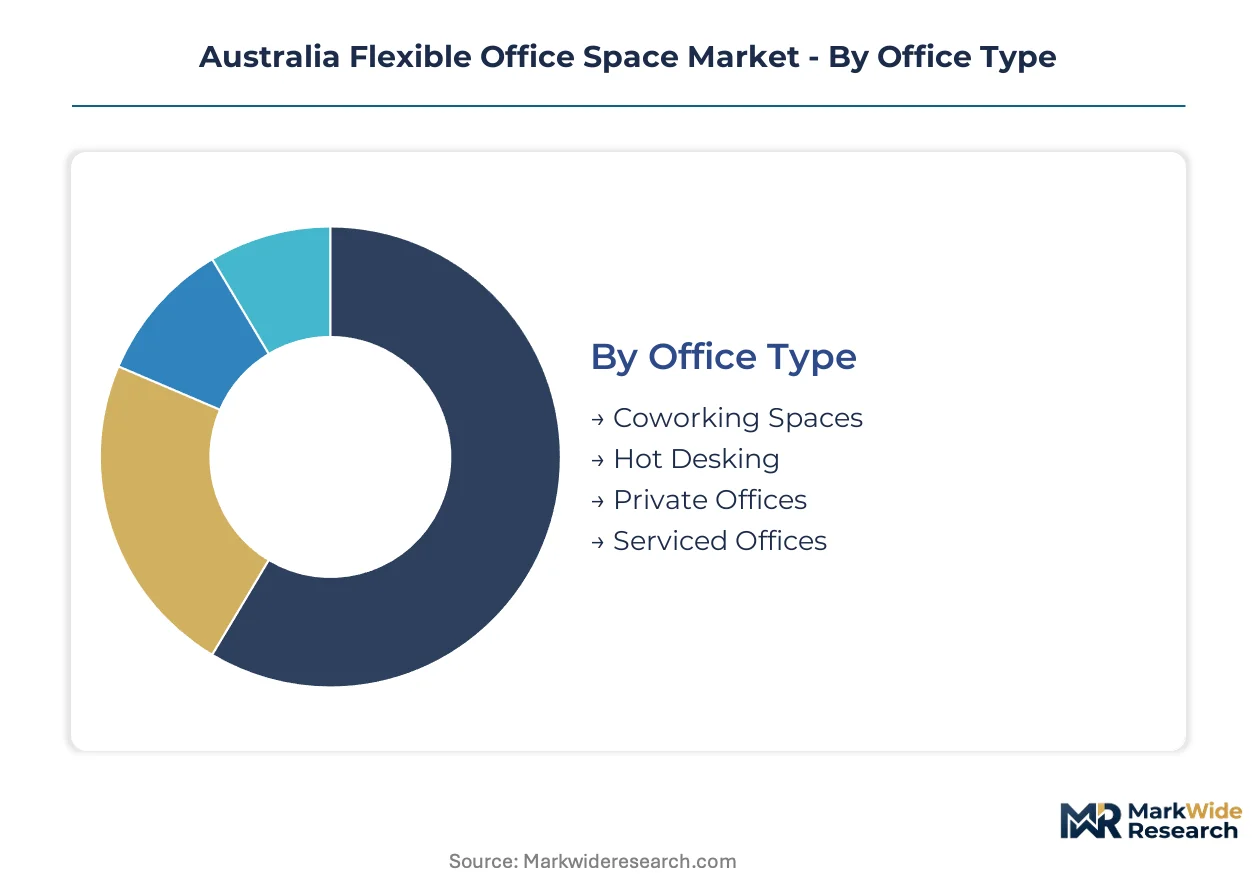
Segmentation in the Australia Flexible Office Space Market reveals how distinct tenant profiles and operational models channel capital toward specific product configurations. Understanding these divisions illuminates where operators deploy retrofit investment and which contract structures absorb compliance cost inflation.
Office Type:
Coworking spaces and private offices flow through different distribution channels—direct-to-enterprise sales versus platform-mediated discovery—shaping how operators price and provision each format.
- Private Offices:Enclosed suites with dedicated access control and customizable branding accommodate legal and consulting tenants requiring confidentiality. Melbourne's CBD and inner-northern precincts concentrate this demand as professional services firms establish satellite locations under hybrid work policies.
- Coworking Spaces:Open-plan environments with shared amenities and community programming target collaboration-intensive users. Sydney's technology corridor drives multi-floor absorption as enterprise tenants normalize distributed team structures.
- Serviced Offices:Fully fitted suites with reception and administrative support cater to immediate occupancy needs. Hub Australia and Servcorp dominate this channel through proprietary infrastructure integration.
- Hot Desking:Unassigned seating with hourly or daily access prioritizes capital efficiency over permanence. Freelancers and itinerant workers populate this tier, particularly in transit-adjacent Melbourne submarkets.
Private offices dominate installed base. Coworking spaces are where expansion concentrates.
Usage Model:
Contract duration correlates directly with tenant size—enterprise procurement teams favor longer commitments while startups optimize for optionality.
- Long-Term Leases:Multi-year agreements with fixed monthly obligations provide cost certainty for large corporations avoiding balance-sheet property exposure. Technology sector tenants in Sydney and Melbourne anchor this segment as hybrid policies stabilize.
- Membership Plans:Tiered subscriptions bundling access hours, amenities, and community events attract recurring revenue from scaling ventures. This format climbs fastest among SMEs seeking flexibility without per-transaction friction.
- Short-Term Rentals:Weekly or monthly agreements accommodate project-based teams and interim workspace needs. Demand spikes during commercial-to-residential conversion windows when traditional supply constricts.
- Pay-As-You-Go:Pure consumption pricing with no base commitment serves sporadic users. The Australian Competition and Consumer Commission's transparency requirements increase contract complexity for this model.
Long-term leases dominate installed base. Membership plans are where expansion concentrates.
Facility Size:
Scale tier determines capital intensity and retrofit sequencing under Australian Building Codes Board compliance timelines.
- Enterprise Level:Multi-floor or whole-building configurations with dedicated infrastructure support corporate headquarters relocation. Large corporations in Sydney CBD absorb this stock despite landlord concentration limiting operator leverage.
- Large Scale:200-500 desk environments balancing community density with operational control. Melbourne's transit-oriented development clusters concentrate this format where rail infrastructure supports hybrid commuting.
- Medium Scale:50-200 desk operations optimizing amenity spend per member. Brisbane submarket underpenetration creates price-setting opportunity before supply catches demand.
- Small Scale:Under 50 desk micro-locations in secondary corridors. Startups and freelancers populate this tier, particularly where WorkSafe Australia ventilation mandates have already been satisfied.
Enterprise level dominates installed base. Medium scale is where expansion concentrates.
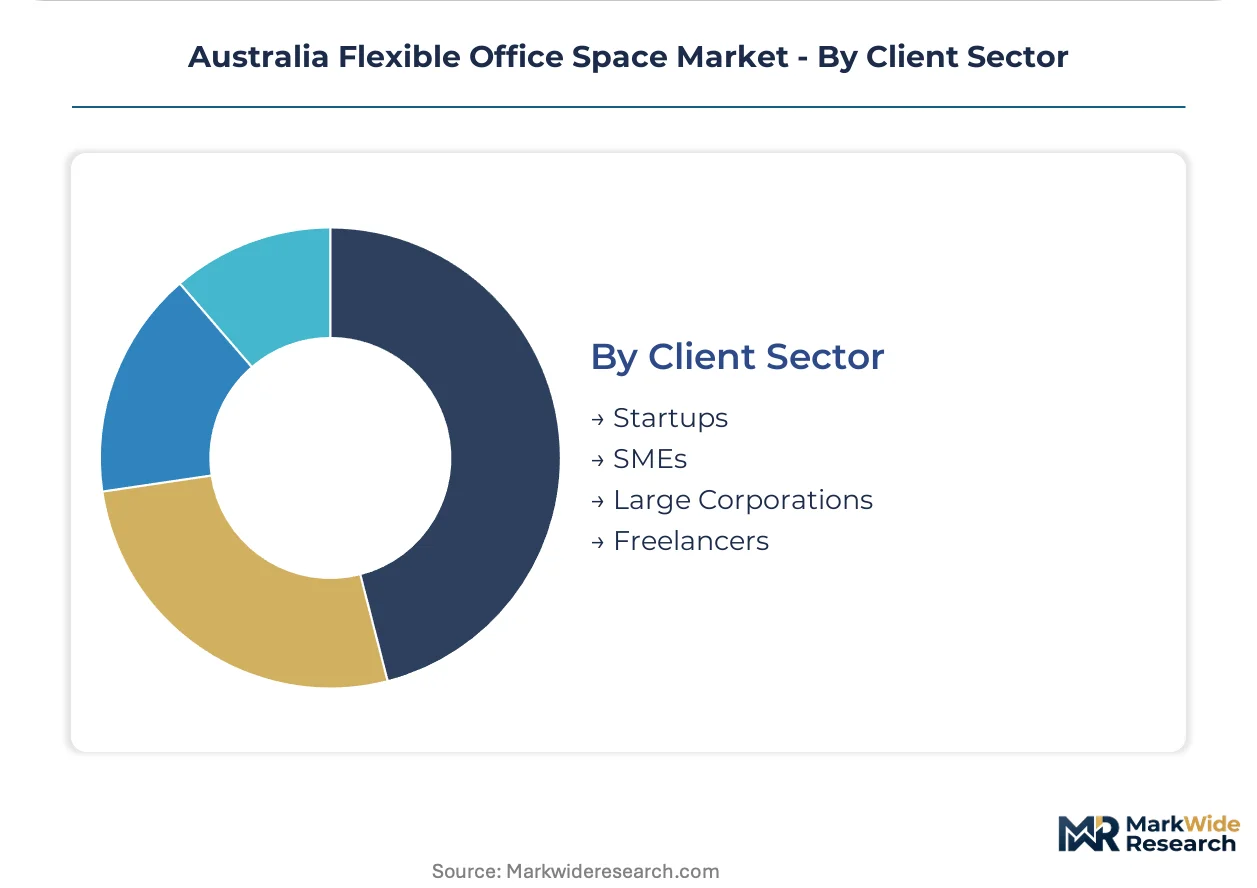
Client Sector:
Sector concentration shapes service packaging—legal tenants demand compliance infrastructure while technology tenants prioritize API-accessible building systems.
- Large Corporations:Enterprise procurement teams consolidating vendor relationships across property portfolios. This segment drives standardized service delivery requirements spanning Sydney, Melbourne, and Brisbane.
- SMEs:Mid-sized entities seeking professional environment without facility management overhead. Membership plans and short-term rentals are expanding fastest among this group.
- Startups:Venture-backed ventures prioritizing burn-rate flexibility and network effects. Hot desking and pay-as-you-go formats align with their capital-light real estate exposure preference.
- Freelancers:Independent professionals with sporadic workspace needs. Melbourne's inner-northern precincts concentrate this demand where density bonuses accelerate flexible lease uptake.
Large corporations dominate installed base. SMEs are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Sydney CBD where institutional landlords control prime grade-A stock, while Melbourne's inner-northern precincts offer operators greater negotiating leverage on lease terms. This asymmetry shapes capital deployment patterns across Australian metropolitan markets.
New South Wales
Technology sector tenants anchor demand in Sydney's CBD and technology corridor as hybrid policies stabilize. The Australian Building Codes Board's National Construction Code revisions compress retrofit timelines for heritage building conversions. Barangaroo and North Sydney clusters absorb multi-floor enterprise suites as procurement teams consolidate vendor relationships.
Victoria
Transit-oriented development in Melbourne's inner-northern precincts concentrates flexible lease uptake where rail infrastructure supports hybrid commuting. WorkSafe Australia ventilation mandates create compliance-driven retrofit demand that operators convert into premium positioning. The CBD and Richmond-Cremorne corridor dominate professional services absorption.
Queensland
Flexible stock per capita remains sparse relative to southern states, creating price-setting opportunity for early movers. State planning law amendments around commercial-to-residential conversion rights may reshape inner-urban supply availability. Brisbane's Fortitude Valley and South Bank clusters show accelerating membership plan uptake among scaling ventures.
Western Australia
Resource sector satellite offices drive intermittent demand spikes in Perth's central business district. The Australian Competition and Consumer Commission's lease transparency requirements increase contract complexity for sporadic users. Subiaco and West Perth submarkets concentrate small-scale operations serving project-based teams.
Australia Flexible Office Space Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Australian flexible office space market. Incumbents with proprietary infrastructure integration command premium positioning, while asset-light operators compete on membership accessibility and community programming. The market structure tiers into design-led community specialists, backward-integrated service platforms, and scale-driven multi-city networks. Dominant competitive moves include portfolio diversification across submarkets and strategic partnerships with institutional landlords for conversion-capable stock.
Within the design-led tier, Hub Australia exemplifies community-programming differentiation, while Servcorp anchors the backward-integrated service archetype through proprietary IT infrastructure. WeWork occupies a position representing scale-driven network effects across Brisbane and Perth submarkets despite broader restructuring headwinds. These three players collectively illustrate how distinct capability configurations map to separate competitive vectors in the market.
| Leading Market Players |
|---|
| Servcorp |
| Flexible Workspace Australia (FWA) |
| Hub Australia |
| Tank Stream Labs |
| The Commons |
| IWG PLC |
| WeWork |
| DeskSpace |
| interoffice Australia |
| Others |
Value Chain & Pricing Dynamics
Ninety-day fit-out lead times for heritage building conversions concentrate pricing power with operators holding forward-contracted construction capacity. This inventory compression amplifies margin pressure on fixed-price refurbishment agreements while rewarding incumbents with captive project pipelines.
Pricing Analysis
The customization-premium spread between configured-to-order private offices and standard coworking memberships exceeds three-to-one in Sydney CBD. Subscription-tiered pricing dominates, with price differentiation resting on ventilation certification grade and API-accessible building system integration. Pricing pressure stems from steel and glazing cost volatility distorting refurbishment economics. Startups and freelancers exhibit highest price sensitivity, while legal and consulting tenants absorb premium positioning for confidentiality infrastructure.
Supply Chain Analysis
Inventory compression in construction materials extends lead times for HVAC and glazing systems sourced from China, Germany, and domestic Australian manufacturers. Raw material dependencies center on structural steel, low-emissivity glazing, and IoT sensor hardware. Single-source vulnerability concentrates in proprietary building management system platforms. Distribution runs through direct operator-procurement relationships with tier-one fit-out contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible office operators face substitution pressure from enterprise tenants internalizing satellite workspace provision through landlord direct leases, compressing the addressable market for third-party intermediation.
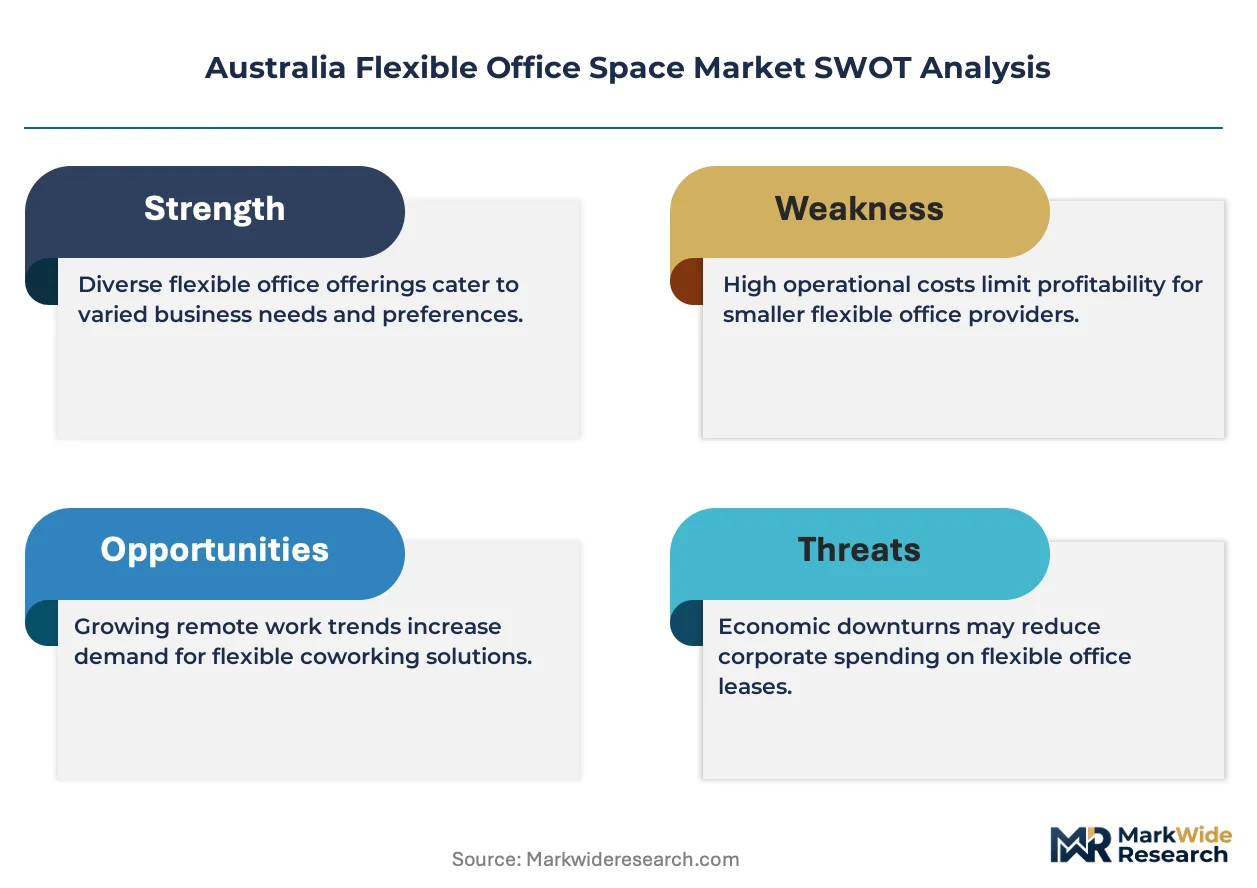
For Market Incumbents: Fortify portfolio positioning by accelerating backward integration into proprietary HVAC and sensor infrastructure before Australian Building Codes Board compliance windows tighten. Lock multi-year construction partnerships to defend against input cost volatility. Prioritize lease restructuring capabilities for legacy commercial acquisitions. For New Entrants and Emerging Players: Differentiate on medium-scale format density in Brisbane submarkets where flexible stock per capita trails southern states. Target membership plan uptake among scaling ventures in Fortitude Valley. Pursue transit-adjacent sites ahead of state planning law amendments releasing commercial-to-residential conversion stock. For Investors and Strategic Acquirers: Carve-out targets emerge from institutional landlords seeking to monetize underperforming CBD assets through operator joint ventures. Five-to-ten year viability hinges on conversion-capable stock access. Monitor WorkSafe Australia ventilation mandate enforcement intensity as inflection indicator for retrofit capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Infrastructure | Captive HVAC and IT systems defend margin compression from Australian Building Codes Board compliance cycles. |
| Geographic Expansion into Underpenetrated Submarkets | Brisbane and Perth clusters offer price-setting power before supply catches technology sector demand normalization. |
| Conversion-Capable Portfolio Acquisition | State planning law amendments around commercial-to-residential rights unlock supply others cannot access. |
| Enterprise Procurement Consolidation Partnership | Multi-city standardized service delivery captures legal and consulting tenant vendor rationalization. |
| Sensor-Integrated Utilization Pricing Launch | Outcome-based models align revenue with actual consumption patterns, fragmenting traditional per-desk structures. |
Study Parameters
A spread of perspectives from flexible office operators, institutional landlord asset managers, tenant procurement leads, and WorkSafe Australia compliance officers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against Australian Bureau of Statistics construction input data, Australian Building Codes Board regulatory filings, and state-level planning authority amendment registers. Bottom-up desk absorption modeling triangulated against top-down metropolitan market sizing.
Segmentation dimensions modeled include office type, usage model, facility scale, and client sector across the projection horizon. CAGRs derived from historical lease commencement velocity, retrofit investment sequencing, and technology sector employment growth patterns. Forecast inputs incorporated transit-oriented development pipeline density and ventilation mandate enforcement timelines.
The analysis sits within stated boundaries; outcomes outside hybrid work policy stabilization or construction input cost normalization would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation pacing and tenant preference stickiness. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
United States Office Real Estate Market
Office Real Estate
Asia Pacific Flexible Office Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
China Flexible Office Space Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
Latin America Office Real Estate Market
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
North America Office Real Estate Market
Office Real Estate
India Flexible Office Space Market
Office Real Estate
Global Office Space Market
Office Real Estate
France Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Brokerage Market
Office Real Estate
South Korea Office Real Estate Market
Office Real Estate
Canada Flexible Office Space Market