
 China Flexible Office Space Market | 2026-2036
China Flexible Office Space Market Size, Share, and Industry Trends Forecast 2026-2036
China Flexible Office Space Market Outlook
Composite flooring and modular partition systems are expanding as replacements for fixed concrete builds in new flexible office fit-outs. Ucommune leverages its technology platform to manage distributed space inventory across multiple Chinese cities. IWG anchors its position through long-term lease arbitrage in prime commercial districts. KrSpace differentiates by embedding venture capital services directly into its coworking locations.
Flexible office space denotes commercially leased environments with movable infrastructure, typically featuring demountable walls, shared amenity zones, and IT bandwidth exceeding standard office specifications. These configurations allow enterprises to adjust square footage without capital-intensive renovation cycles. Serviced offices command the largest revenue pool due to premium pricing and bundled facility management, while coworking spaces attract the highest volume of new memberships from startups and freelancers. Pay-as-you-go models are gaining traction among corporates piloting hybrid work arrangements, though long-term leases still capture the majority of enterprise spending.
MIIT's broadband infrastructure mandates and SAMR's commercial lease disclosure rules shape operator compliance costs and tenant transparency expectations. GB standards for building fire safety and ventilation directly constrain facility design choices in converted properties. Stakeholders must monitor how municipal land-use policies in Shenzhen and Hangzhou treat short-term commercial tenancies versus traditional Class-A leases.
Market Dynamics
MIIT's broadband infrastructure mandates and SAMR's commercial lease disclosure rules are compressing operator compliance timelines while elevating tenant transparency expectations across tier-one Chinese cities.
Growth Catalysts
- Dual carbon goals:Beijing's carbon neutrality targets accelerate demand for retrofit-ready buildings with demountable walls and energy-efficient HVAC systems.
- Technology startups:Venture-backed firms in Shanghai and Hangzhou prioritize membership-based workspaces over traditional Class-A leases.
- Streamlined registration:NMPA's simplified business licensing frameworks reduce setup friction for satellite offices and project-based teams.
Market Restraints
- Prime rent volatility:Commercial landlords in Beijing and Shenzhen impose steep renewal premiums that compress operator margins.
- GB fire safety standards:National building codes mandate costly sprinkler and ventilation upgrades in converted industrial properties.
- Long-term lease arbitrage:IWG and established operators lock prime inventory through multi-year contracts, limiting new entrant access.
Strategic Opportunities
- Greater Bay Area expansion:Shenzhen and Guangzhou present underpenetrated demand from cross-border fintech and logistics firms.
- Pay-as-you-go models:Corporate hybrid work pilots favor flexible day-pass arrangements over fixed desk commitments.
- 5G-IoT convergence:MIIT's infrastructure rollout enables smart building management platforms that differentiate premium offerings.
Industry Challenges
- Facility management talent scarcity:Operators struggle to recruit technicians certified in GB-compliant fire suppression and HVAC systems.
- Legacy system integration:Enterprise tenants demand API connectivity with existing ERP and access control platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Flexible Office Space Market |
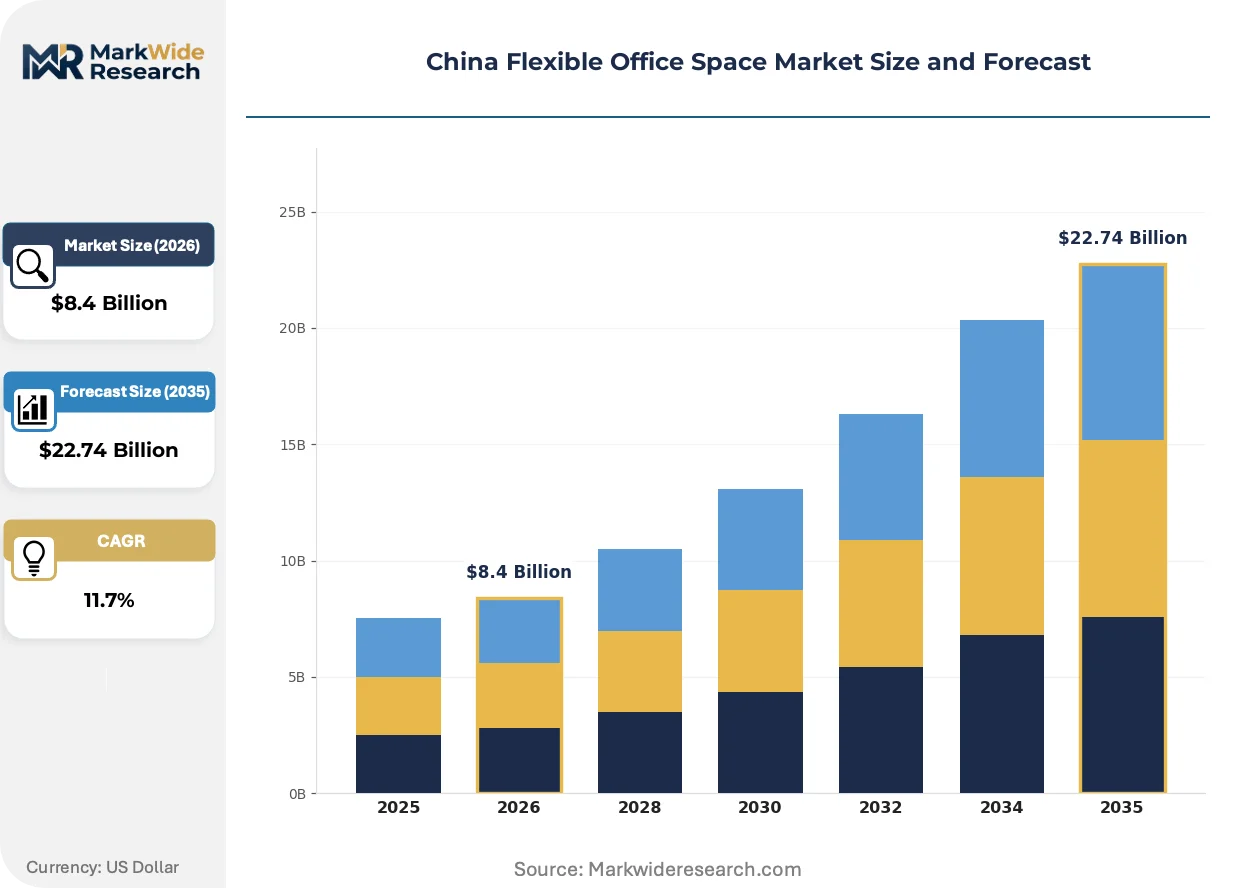
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Office Type: Serviced Offices, Coworking Spaces, Executive Suites, Hot Desking Customer Type: Startups, Freelancers, Small Enterprises, Corporates Service Model: Membership-Based, Short-Term Lease, Long-Term Lease, Pay-As-You-Go Facility Size: Small Spaces, Medium Spaces, Large Spaces, Customizable Layouts |
| Companies Covered | Spaces, CEO SUITE, Ucommune, KrSpace, The Executive Centre, International Workplace Group (IWG), Servcorp, MyDream+, Regus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Flexible Office Space Market Strategic Shifts
Technology platforms and policy mandates are restructuring how flexible office inventory is managed, priced, and consumed across Chinese commercial real estate.
Modular partition systems are electrifying fit-out economics for operators converting aging industrial stock into serviced offices. Property developers in Hangzhou and Chengdu specify demountable wall assemblies that slash renovation cycles from months to weeks. This compression is electrifying operator capacity to reconfigure floor plates between enterprise and startup tenant mixes within single lease periods.
SAMR's commercial lease disclosure rules mandate standardized contract terms and fee transparency across all flexible workspace agreements. The regulation eliminates hidden service charges that previously obscured true occupancy costs. Tier-one city operators now compete on stated pricing clarity rather than negotiated exceptions, compressing margin structures industry-wide.
Corporate real estate teams are unbundling headquarters commitments into distributed satellite strategies. Multinationals in the Yangtze River Delta now procure workspace through centralized procurement platforms that aggregate usage across multiple cities. This aggregation is displacing location-by-location lease negotiations and favoring operators with unified technology stacks spanning Beijing, Shanghai, and Shenzhen.
China Flexible Office Space Market Segmentation
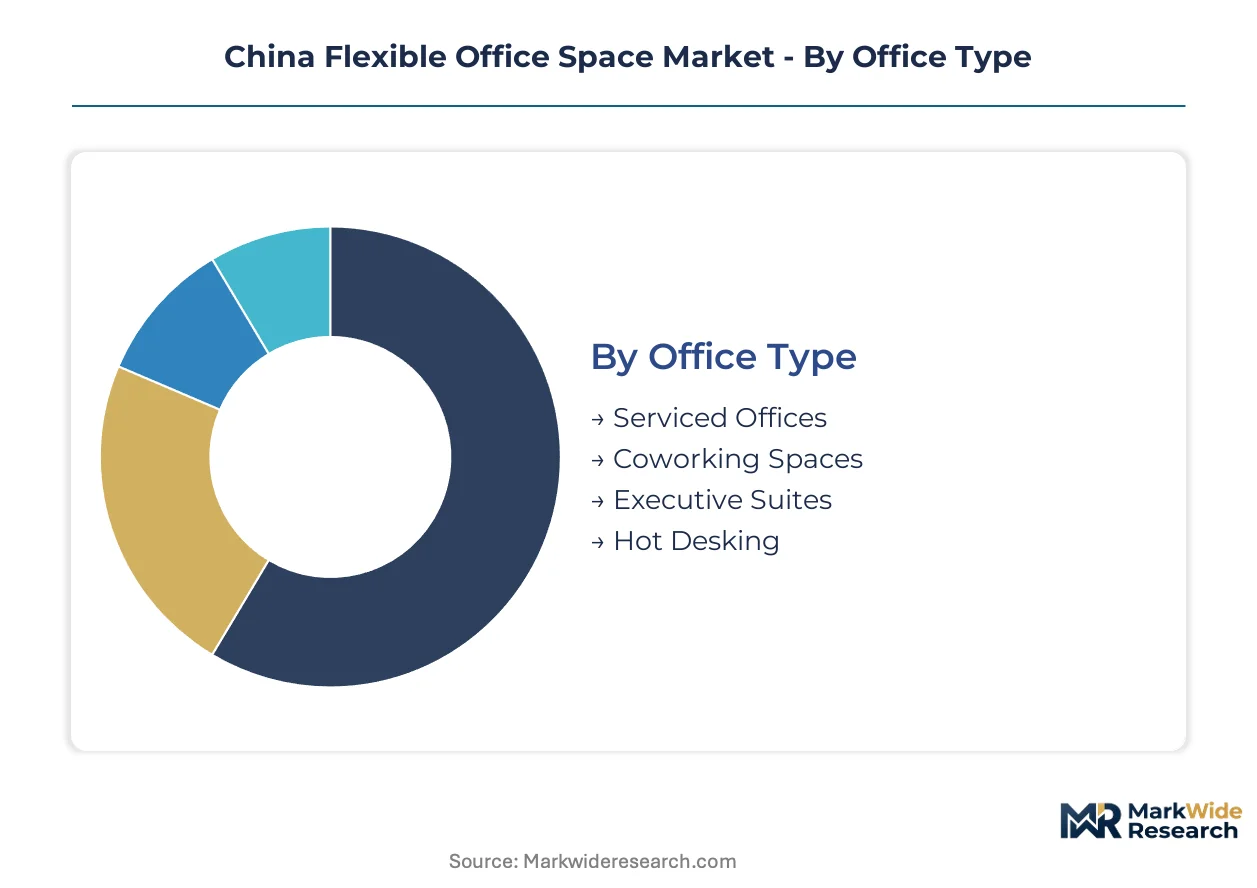
Segmentation in China's flexible office space market determines operator compliance burdens and capital deployment strategies. MIIT's broadband mandates and GB fire safety standards apply unevenly across office configurations and customer profiles.
Office Type:
GB fire safety certification requirements vary sharply across office configurations, with sprinkler density and ventilation specifications scaling with occupancy density and lease duration.
- Serviced Offices:Fully managed environments with bundled reception, IT infrastructure, and facility management under single contracts. Beijing and Shanghai corporates favor these for satellite offices due to NMPA's streamlined registration pathways for established business addresses. GB-compliant HVAC and fire suppression systems elevate upfront capital requirements.
- Coworking Spaces:Membership-driven environments emphasizing shared amenities and community programming. Hangzhou and Shenzhen technology startups concentrate demand here, attracted by demountable wall systems that permit rapid reconfiguration. MIIT's broadband infrastructure mandates ensure connectivity parity with traditional Class-A stock.
- Executive Suites:Premium private offices with dedicated support staff and enhanced privacy specifications. Small enterprises in Guangzhou's financial districts drive uptake.
- Hot Desking:Unassigned seating accessed through day passes or hourly arrangements. Freelancers and project-based teams in Chengdu favor this model for cost minimization.
Leading the category by volume: Coworking Spaces. Growing fastest: Hot Desking.
Customer Type:
Cost tier stratification separates premium enterprise contracts from volume-driven startup memberships, with pricing elasticity varying across customer sophistication levels.
- Startups:Venture-backed firms prioritizing membership flexibility over lease security. Yangtze River Delta technology clusters generate concentrated demand.
- Freelancers:Individual operators seeking day-pass access and community infrastructure. Cost sensitivity drives preference for peripheral district locations.
- Small Enterprises:Established businesses with 10-50 employees requiring satellite presence. Greater Bay Area logistics and fintech firms expand most quickly in this segment.
- Corporates:Multinationals unbundling headquarters commitments into distributed procurement strategies. Centralized platforms now aggregate usage across Beijing, Shanghai, and Shenzhen.
Volume leadership: Corporates. Steepest expansion trajectory: Small Enterprises.
Service Model:
Application logic determines contract structure, with enterprise ERP integration requirements favoring long-term arrangements and pilot programs adopting consumption-based alternatives.
- Membership-Based:Monthly or annual subscriptions granting access to network locations. Ucommune's technology platform manages distributed inventory across multiple cities under this structure.
- Short-Term Lease:Three-to-twelve month commitments with limited customization rights. Project-based teams in Shenzhen's cross-border trade sector favor this flexibility.
- Long-Term Lease:Multi-year contracts with fit-out allowances and branding permissions. IWG anchors market position through prime commercial district arbitrage.
- Pay-As-You-Go:Day-pass or hourly billing without recurring obligations. Corporate hybrid work pilots in Shanghai accelerate adoption of this model.
Dominant by revenue: Long-Term Lease. Gaining share fastest: Pay-As-You-Go.
Facility Size:
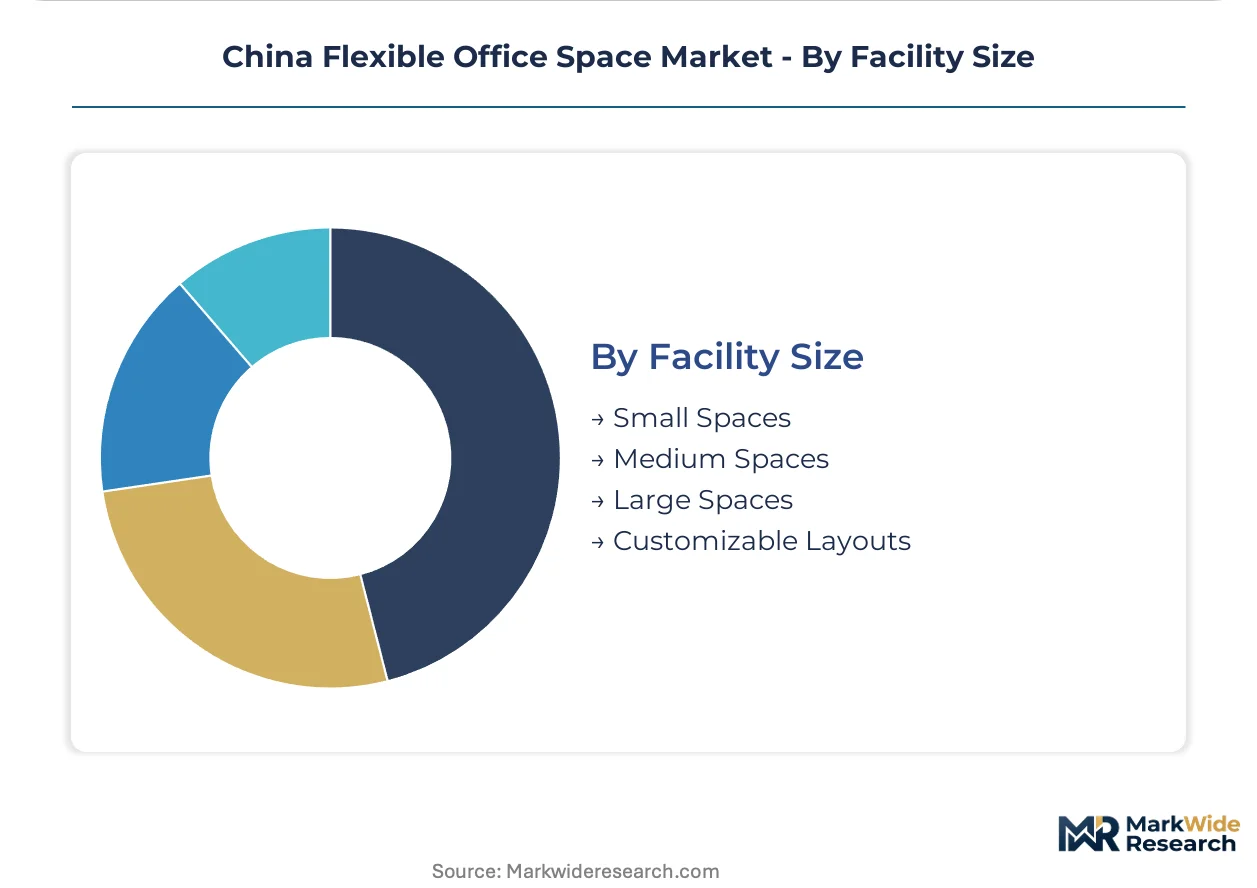
Supply concentration in tier-one city cores favors medium and large configurations, while peripheral districts accommodate smaller footprints.
- Small Spaces:Under 500 square meter configurations targeting freelancers and micro-teams. Hangzhou's converted industrial properties specialize in this scale.
- Medium Spaces:500-2,000 square meter floor plates serving small enterprises with growth trajectories. Chengdu operators report strongest occupancy in this band.
- Large Spaces:Exceeding 2,000 square meters with dedicated amenity zones and multiple tenant configurations. Beijing and Shanghai prime districts concentrate this inventory.
- Customizable Layouts:Demountable partition systems permitting rapid reconfiguration between open and cellular plans. Modular electrification from composite flooring suppliers enables this flexibility.
Highest revenue concentration: Large Spaces. Climbing the fastest: Customizable Layouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's coastal economic corridors where technology clusters and policy incentives intersect. MIIT's digital infrastructure mandates and NMPA's streamlined registration frameworks accelerate workspace uptake across metropolitan hubs.
Yangtze River Delta
Shanghai anchors serviced office demand from multinational procurement platforms aggregating distributed workspace. MIIT's broadband infrastructure mandates ensure connectivity parity with Class-A commercial stock. Hangzhou technology startups drive coworking membership growth in converted industrial zones.
Greater Bay Area
Shenzhen's cross-border fintech and logistics firms generate underpenetrated demand for flexible satellite offices. SAMR's commercial lease disclosure rules compress margin structures while elevating pricing transparency. Guangzhou financial districts concentrate executive suite uptake among small enterprises.
Beijing-Tianjin-Hebei
Venture-backed technology firms prioritize membership-based workspaces over traditional leases in Beijing's core districts. Dual carbon goals accelerate retrofit-ready building specifications with demountable wall systems. Tianjin's logistics corridors host project-based teams favoring short-term lease arrangements.
Sichuan-Chongqing
Chengdu freelancers and micro-teams favor hot desking configurations in peripheral district locations. GB fire safety standards mandate costly sprinkler upgrades in converted properties. Chongqing's emerging technology clusters attract medium-space operators reporting strongest occupancy in the 500-2,000 square meter band.
China Flexible Office Space Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with established operators leveraging long-term lease arbitrage while technology-enabled platforms capture startup volume. The vendor base clusters around three strategic archetypes: network-scale platforms managing distributed inventory, prime-district operators securing multi-year commercial contracts, and venture-integrated providers embedding financial services into physical locations. Dominant competitive moves include technology platform development for centralized procurement and modular fit-out systems enabling rapid space reconfiguration.
Within the network-scale tier, Ucommune leverages its technology platform to manage distributed space inventory across multiple Chinese cities. IWG anchors market position through long-term lease arbitrage in prime commercial districts. KrSpace exemplifies the venture-integrated archetype by embedding capital services directly into coworking locations.
| Leading Market Players |
|---|
| Spaces |
| CEO SUITE |
| Ucommune |
| KrSpace |
| The Executive Centre |
| International Workplace Group (IWG) |
| Servcorp |
| MyDream+ |
| Regus |
| Others |
Value Chain & Pricing Dynamics
Composite flooring and modular partition systems flow from upstream material suppliers through three distinct pricing tiers, with demountable wall assemblies commanding premium positioning against fixed concrete builds in tier-one city fit-outs. Labor costs for GB-certified fire suppression technicians anchor margin pressure across all tiers, compressing operator economics in converted industrial properties.
Pricing Analysis
Volume leadership sits with long-term lease contracts capturing enterprise spending, while pay-as-you-go models sacrifice margin for membership growth among hybrid work pilots. Pricing stratifies across premium serviced offices with bundled facility management, standard coworking memberships, and economy hot-desking day passes. Cost compression in the economy tier intensifies because SAMR's disclosure rules eliminated hidden service charges that previously padded operator margins. Freelancers in Chengdu and peripheral districts exhibit highest price sensitivity; multinationals procuring through centralized platforms show lowest elasticity due to bundled ERP integration requirements.
Supply Chain Analysis
Single-source vulnerability sits with demountable wall system manufacturers concentrated in Guangdong and Zhejiang provinces, where composite flooring suppliers feed fit-out contractors serving Beijing and Shanghai operators. Raw material dependencies span aluminum framing extrusions, acoustic insulation panels, and IoT-enabled access control hardware. Logistics chokepoints emerge from GB fire safety certification bottlenecks that delay converted property deployments. Distribution runs through operator-managed technology platforms that aggregate inventory visibility across distributed city networks, displacing traditional broker-mediated lease transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
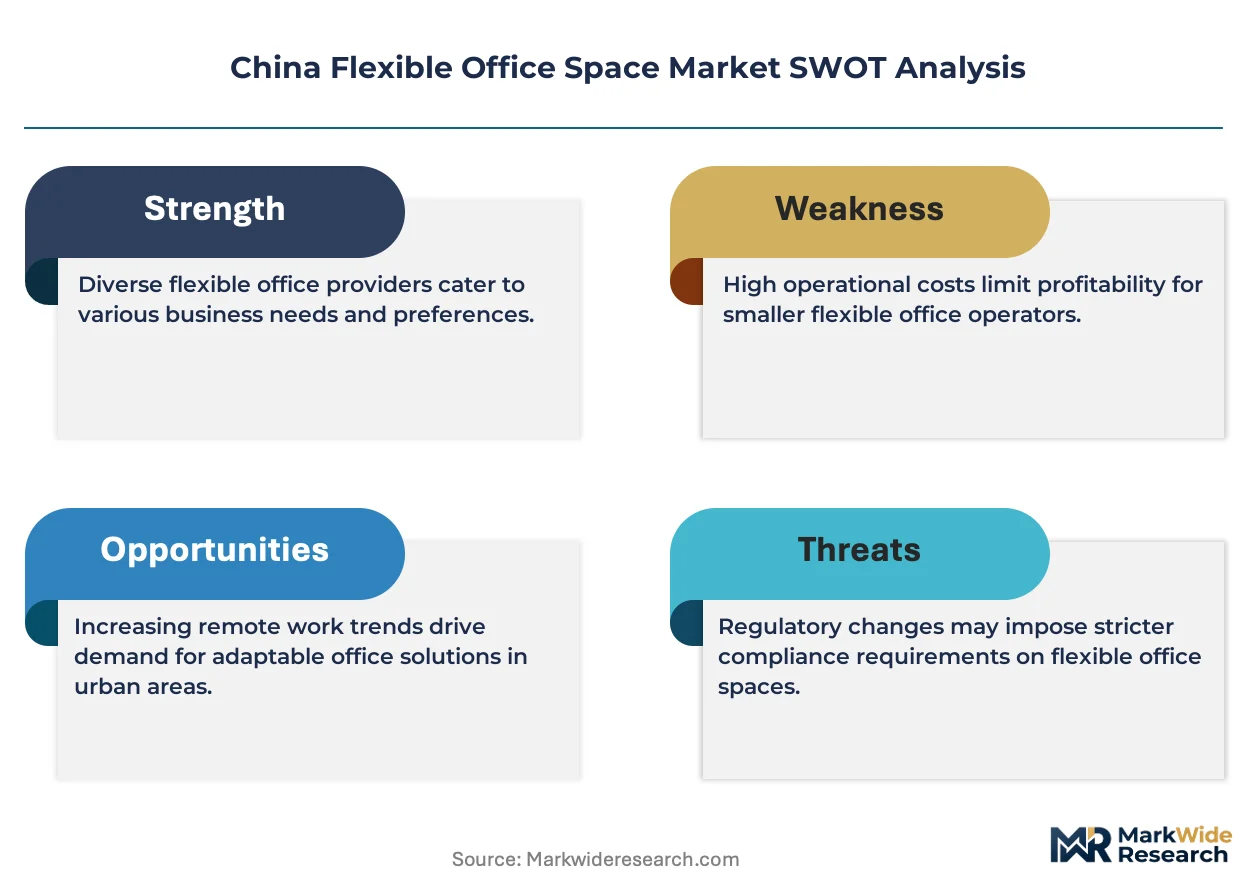
This market is a vertical-integration race. Players are pursuing upstream control over modular fit-out manufacturing to compress renovation cycles and defend margin position against prime rent volatility.
For Market Incumbents: Extend technology platform capabilities into predictive space utilization analytics, locking enterprise procurement teams into centralized dashboard dependencies. Secure multi-year lease arbitrage in Beijing and Shanghai prime districts before municipal land-use policies tighten short-term commercial tenancy permissions. Vertical integration into in-house GB-certified facility management training programs addresses technician scarcity threatening service quality consistency.
For New Entrants and Emerging Players: Cross-border fintech and logistics firms in Shenzhen and Guangzhou represent underserved buyer archetypes with satellite office demand outpacing incumbent inventory deployment. White-space targets concentrate in medium-space configurations of 500-2,000 square meters with customizable layouts, where Chengdu and Chongqing occupancy runs strongest. Go-to-market positioning should emphasize 5G-IoT convergence enabled by MIIT infrastructure rollout, differentiating smart building management against legacy operator offerings.
For Investors and Strategic Acquirers: Municipal land-use policy shifts in Shenzhen and Hangzhou treating short-term commercial tenancies is the leading indicator that regulatory arbitrage windows are narrowing for pure lease-arbitrage models. Long-term viability favors technology-enabled platforms with distributed inventory management capabilities spanning multiple city clusters. Acquisition target archetype: operators with captive modular fit-out supply chains and established GB compliance protocols. Watch for SAMR enforcement actions on lease disclosure violations as signal of margin compression acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fit-Out Manufacturing Integration | Backward integration into demountable wall production compresses renovation cycles from months to weeks for operators. |
| 5G-IoT Smart Building Platform Deployment | MIIT infrastructure mandates enable differentiated offerings with predictive HVAC and access control management. |
| GB Fire Safety Certification Investment | Captive technician training programs address talent scarcity constraining converted property deployment timelines. |
| Cross-Border Fintech Satellite Office Expansion | Greater Bay Area underpenetration creates first-mover positioning before IWG and Ucommune scale presence. |
| Enterprise Procurement Platform Partnership | Centralized dashboard integration locks multinational real estate teams into recurring subscription structures. |
Study Parameters
Multi-period observation of operator inventory deployment, membership pricing trajectories, and municipal land-use policy filings anchored the trend analysis, supplemented by interviews with flexible office operators, commercial real estate procurement managers at multinational corporations, GB-certified facility management technicians, and modular fit-out manufacturers. Secondary validation drew from SAMR commercial lease disclosure filings, MIIT broadband infrastructure mandate documents, NMPA business registration statistics, and municipal planning bureau records in Beijing, Shanghai, Shenzhen, and Hangzhou. Bottom-up aggregation of operator-level capacity and membership data triangulated against top-down commercial real estate absorption estimates across the analysis window.
Input-output matrices modeled square footage supply against segmented demand across office type, customer profile, service model, and facility size dimensions. CAGRs were derived from regression analysis of historical absorption rates projected through policy scenario weighting. Forecast inputs incorporated dual carbon goal retrofit timelines, 5G-IoT infrastructure deployment schedules, and cross-border fintech firm formation rates in the Greater Bay Area.
Revisions become necessary when MIIT mandates accelerate broadband infrastructure rollout beyond baseline assumptions, or when SAMR enforcement actions materially alter lease disclosure compliance costs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Flexible Office Market
Office Real Estate
Bahrain Flexible Office Space Market
Office Real Estate
India Office Real Estate Market
Office Real Estate
Global Office Space Market
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
North America Office Real Estate Market
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
Saudi Arabia Flexible Office Space Market
Office Real Estate
China Office Real Estate Market
Office Real Estate
Office Real Estate Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
Italy Office Real Estate Market
Office Real Estate
Japan Office Real Estate Market
Office Real Estate
India Co-Working Office Spaces Market