
 Canada Flexible Office Space Market | 2026-2036
Canada Flexible Office Space Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Flexible Office Space Market Outlook
Asset-light leasing models with short-term contracts and revenue-sharing clauses is fragmenting competitive dynamics across Canadian flexible office space. WeWork leverages its global brand infrastructure to sustain presence in Toronto and Vancouver despite prior restructuring. iQ Offices anchors its position through premium private office configurations in downtown Toronto. Industrious differentiates via hospitality-forward service tiers targeting mid-market corporate clients.
Flexible office space denotes commercially operated workspace delivered through variable-term contracts rather than traditional multi-year leases, typically incorporating shared amenities, IT infrastructure, and reception services. The physical environment relies on modular partition systems, enterprise-grade fiber connectivity, and cloud-based access control to enable rapid reconfiguration of floor plates. Private offices command premium pricing within the product type dimension while hot desking serves as the volume entry point for freelancers and early-stage ventures. Corporates within the end user dimension are shifting procurement toward hybrid membership plans that blend dedicated desks with on-demand meeting room access.
Health Canada's indoor air quality guidelines intersect with municipal building codes in Toronto, Vancouver, and Calgary to elevate ventilation and density standards for shared workspaces. The Competition Bureau's scrutiny of lease terms and cancellation policies shapes operator pricing transparency and contract flexibility. Stakeholders must monitor how provincial commercial tenancy legislation evolves to address license-versus-lease classification disputes that determine tenant protections and operator liability exposure.
Market Dynamics
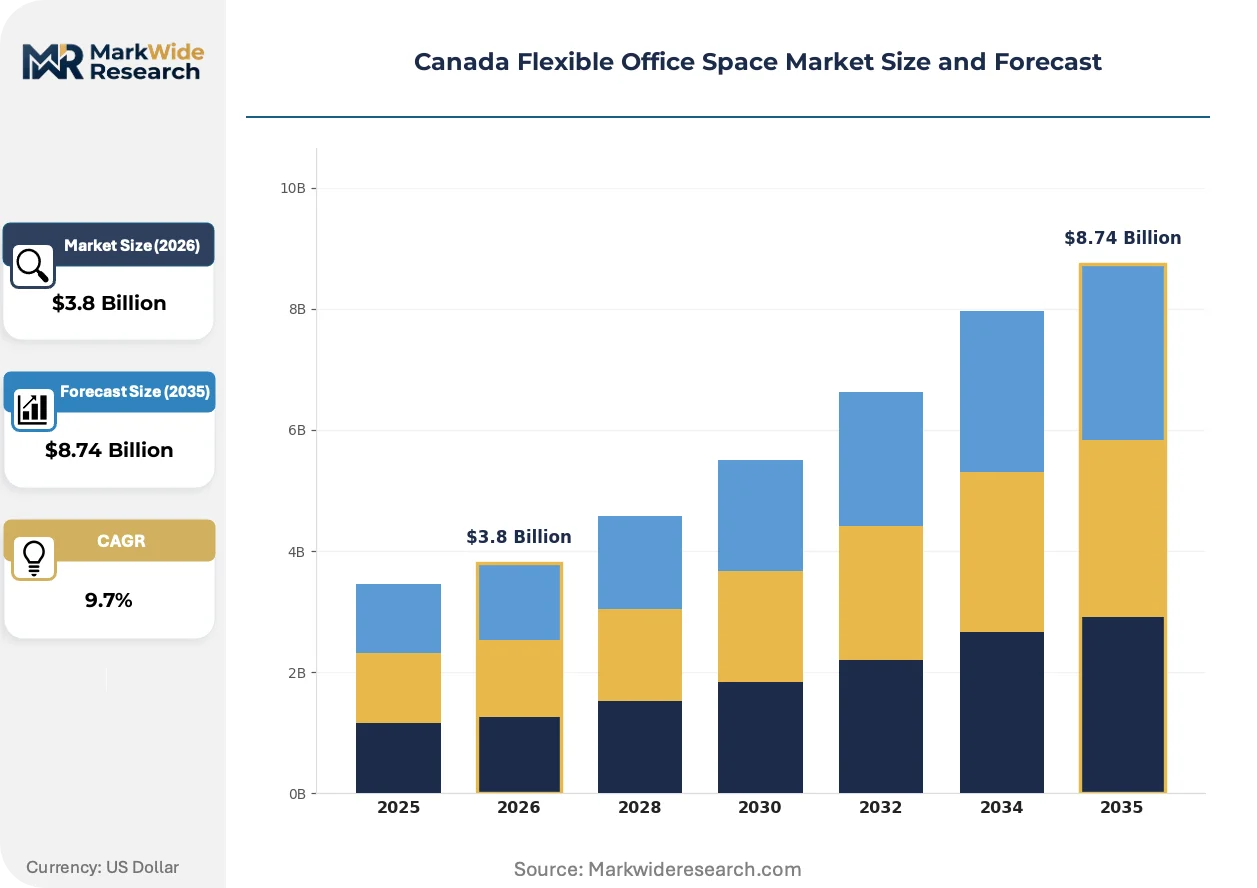
Canada's flexible office space market is undergoing fundamental restructuring as asset-light leasing models with short-term contracts and revenue-sharing clauses fragment traditional competitive dynamics. Municipal zoning reforms across Toronto, Vancouver, and Calgary are accelerating commercial-to-office conversions while technology startups drive membership-based workspace adoption.
Growth Catalysts
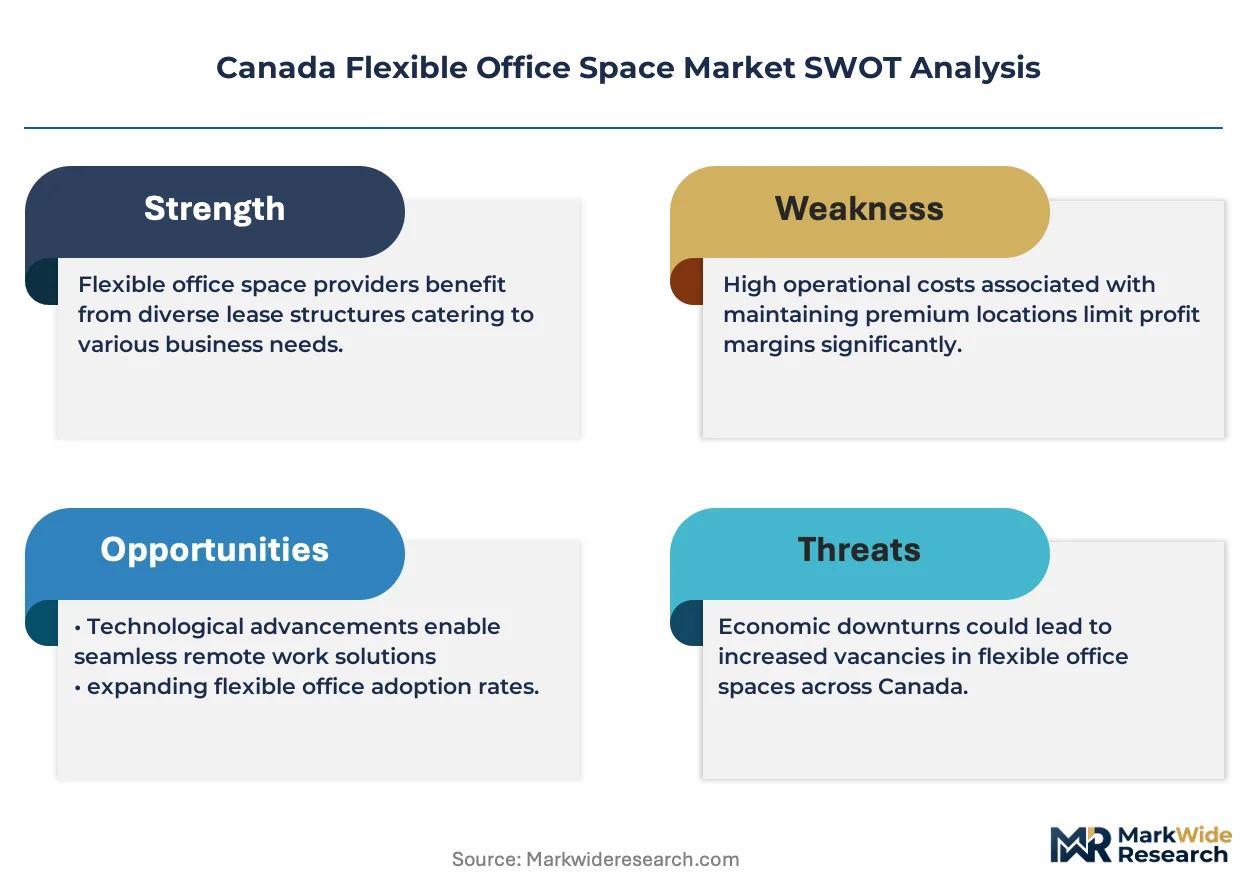
- Toronto Municipal Zoning Reform:Eased commercial-to-office conversion rules are unlocking underutilized retail and industrial inventory for flexible workspace deployment.
- Hybrid Membership Plans:Corporate procurement teams are blending dedicated desks with on-demand meeting room access, expanding addressable demand beyond traditional leaseholders.
- Cloud-Based Access Control:Enterprise-grade fiber connectivity and modular partition systems enable rapid floor plate reconfiguration, reducing operator capex cycles.
Market Restraints
- License-Versus-Lease Classification Disputes:Provincial commercial tenancy legislation uncertainty creates tenant protection and operator liability exposure across Ontario, British Columbia, and Alberta.
- Ventilation Infrastructure Retrofit Costs:Health Canada indoor air quality guidelines intersecting with Toronto and Vancouver building codes require substantial HVAC upgrades in aging commercial stock.
- Competition Bureau Scrutiny:Regulatory examination of cancellation policies and lease term transparency constrains pricing flexibility and contract structure innovation.
Strategic Opportunities
- Calgary Downtown Core Revitalization:Vacancy rates in Calgary's commercial district create acquisition and conversion opportunities at depressed asset valuations.
- Hospitality-Forward Service Tiers:Premium amenity packages targeting mid-market corporate clients represent underserved positioning between WeWork's volume play and iQ Offices' luxury focus.
- Enterprise-Grade Fiber + Modular Systems Convergence:Integrated technology infrastructure reduces per-seat IT deployment costs and accelerates tenant onboarding timelines.
Industry Challenges
- Facilities Management Talent Scarcity:Specialized expertise in multi-tenant HVAC optimization and density-compliant space planning remains concentrated among established operators.
- Modular Partition System Integration:Legacy commercial buildings require structural assessment and floor load verification before rapid reconfiguration systems can deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Flexible Office Space Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Desking, Dedicated Desks, Private Offices, Meeting Rooms End User: Startups, Freelancers, Corporates, Remote Teams Service Type: Membership Plans, Pay-as-you-go, Virtual Offices, Coworking Spaces Technology: High-Speed Internet, Video Conferencing, Cloud Storage, Smart Office Solutions |
| Companies Covered | Workhaus, TCC Canada, International Workplace Group plc, Industrious, Vast Coworking Group, Spaces, iQ Offices, CBRE Group, WeWork, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Flexible Office Space Market Strategic Shifts
Workspace technology and regulatory frameworks are actively compressing traditional leasing structures while reshaping how Canadian operators configure and monetize floor plates. Three interconnected developments are driving this transformation.
Cloud-based access control integrated with enterprise-grade fiber connectivity is collapsing the distinction between physical security and IT infrastructure deployment. Technology startups across Vancouver's Yaletown corridor are adopting these converged systems fastest, enabling same-day provisioning that previously required two-week hardware installation cycles.
Health Canada's indoor air quality guidelines are tightening ventilation and density standards for shared workspaces in coordination with Toronto and Vancouver municipal building codes. Operators must now demonstrate compliant HVAC performance before occupancy permits issue, compressing project timelines and elevating mechanical engineering costs in retrofit scenarios.
Corporate real estate teams are unbundling after-sales service expectations from base membership fees, demanding à-la-carte meeting room credits and reception support rather than all-inclusive packages. This consumption-pattern shift is most visible among financial services tenants in downtown Toronto's financial district, where procurement teams negotiate usage-based terms that transfer utilization risk to operators.
Canada Flexible Office Space Market Segmentation
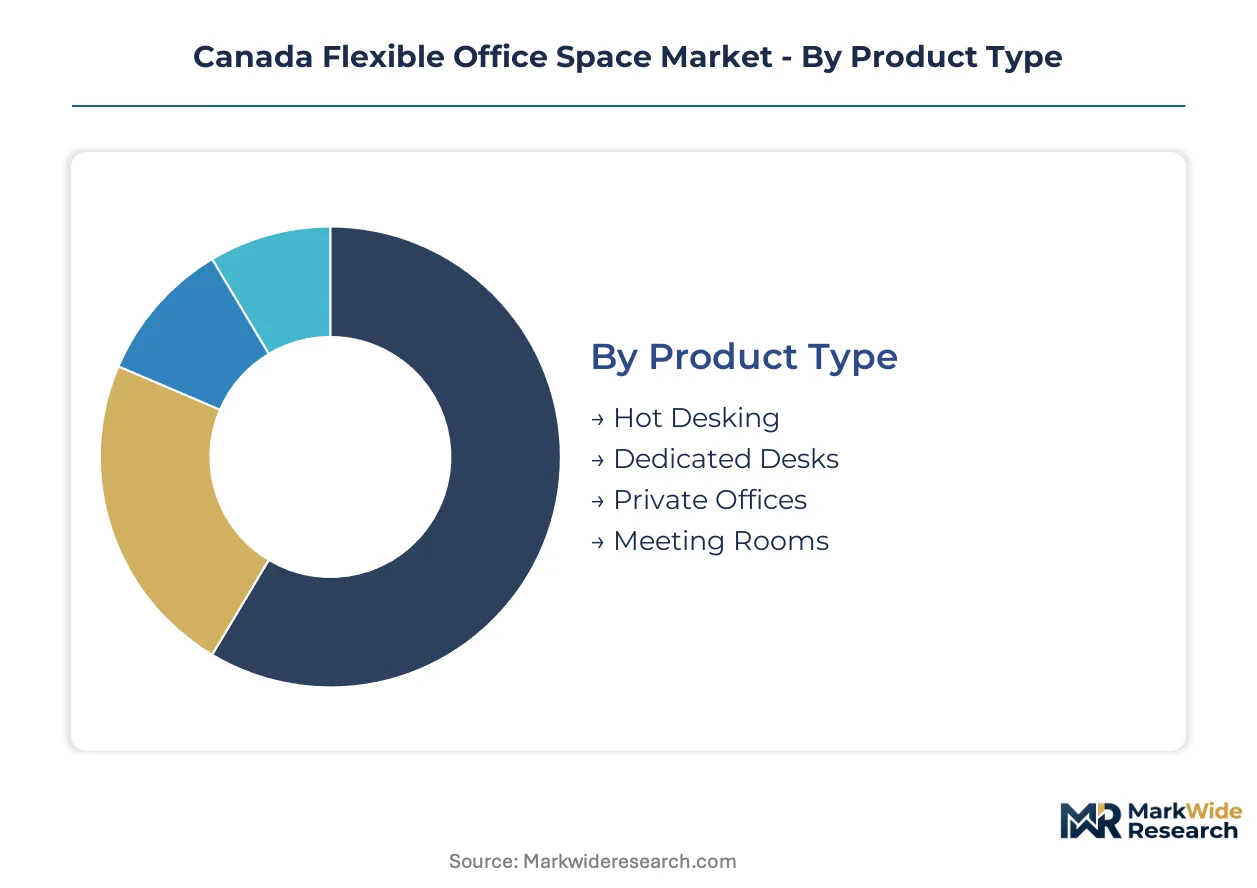
Segmentation in Canada's flexible office space market reveals divergent operational economics across product configurations and end-user profiles. Cycle times vary dramatically from same-day hot desk turnover to multi-year corporate commitments, shaping capital deployment and revenue recognition patterns for operators nationwide.
Product Type:
Turnover velocity separates these segments sharply, with hourly-rate products cycling in minutes while dedicated configurations lock in monthly recurring revenue streams.
- Hot Desking:Unassigned seating in open floor plates with first-come-first-claim protocols and minimal storage provisions. Demand concentrates among freelancers in Vancouver's Yaletown corridor where technology startups prioritize cost minimization over permanence.
- Dedicated Desks:Reserved workstations with personal storage and 24/7 access credentials. Toronto's financial district corporates drive procurement here, seeking hybrid membership plans that blend fixed presence with meeting room flexibility.
- Private Offices:Enclosed suites with lockable doors and customizable branding.
- Meeting Rooms:Bookable conference and huddle spaces with AV integration.
Hot desking anchors the volume base while private offices gain share at the steepest rate.
End User:
Procurement sophistication creates tiered service expectations, from self-serve app bookings to negotiated enterprise agreements with bespoke amenity packages.
- Startups:Venture-backed companies with scaling headcount and unpredictable space needs. Calgary's downtown core revitalization attracts these users through depressed asset valuations and flexible license terms.
- Corporates:Established enterprises with 50+ employees seeking satellite locations or headquarters alternatives. Health Canada indoor air quality compliance requirements dominate their site selection criteria in Toronto and Vancouver.
- Freelancers:Independent contractors and solo practitioners.
- Remote Teams:Distributed company employees seeking occasional collaboration hubs.
Freelancers generate the highest transaction frequency while corporates deliver the most stable annual contract value.
Service Type:
Revenue model selection determines utilization risk allocation between operator and tenant, with fixed subscriptions contrasting against consumption-variable alternatives.
- Membership Plans:Recurring monthly or annual subscriptions bundling workspace access with amenities. Technology startups across Toronto accelerate adoption here, drawn to predictable budgeting and community programming.
- Coworking Spaces:Community-oriented environments emphasizing networking events and shared resources. Vancouver's Yaletown tech corridor hosts the densest concentration, with municipal zoning reforms easing commercial-to-office conversions.
- Pay-as-you-go:Usage-based billing without ongoing commitment.
- Virtual Offices:Business address and reception services without physical workspace.
Membership plans dominate revenue composition while pay-as-you-go expands most quickly among occasional users.
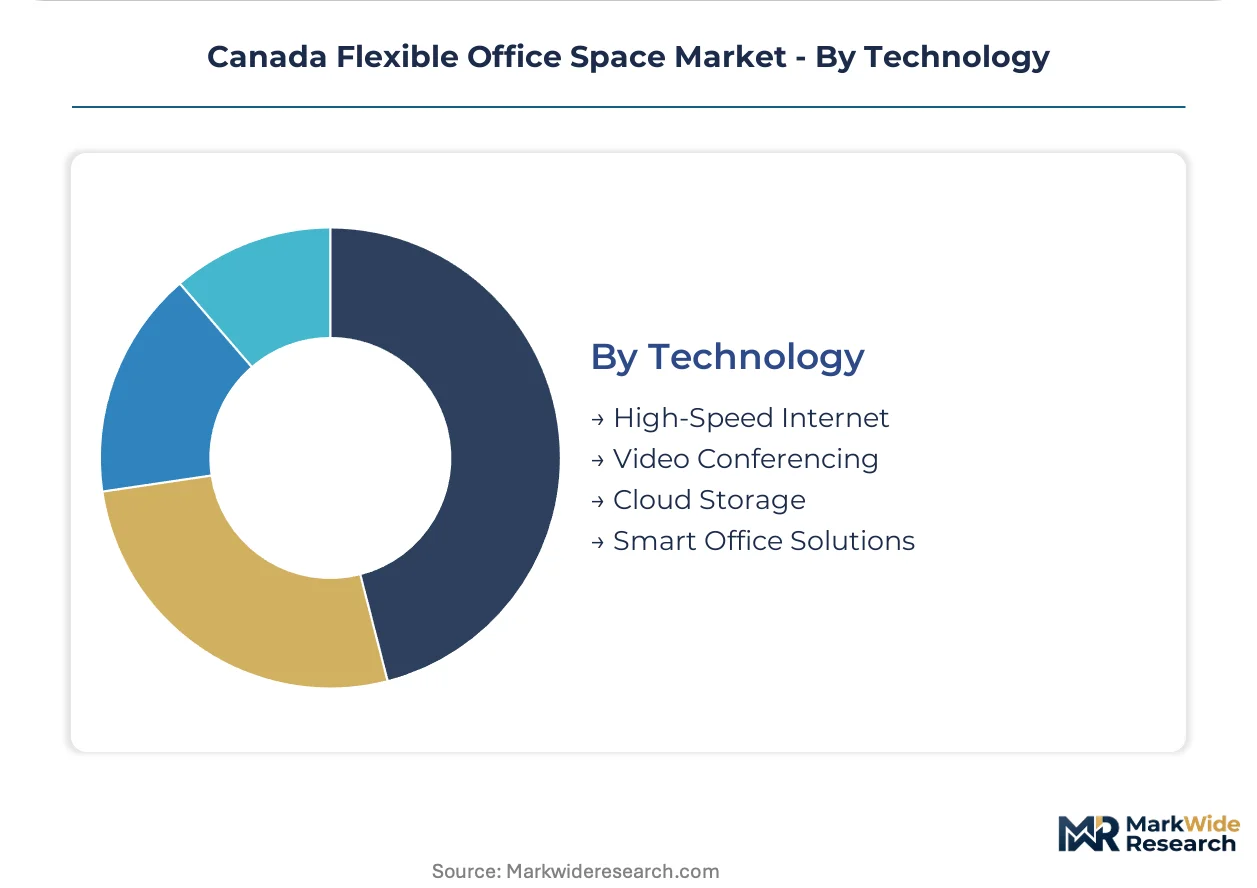
Technology:
Infrastructure deployment costs and upgrade cycles differentiate these segments, with some requiring continuous capital reinvestment while others amortize over longer horizons.
- High-Speed Internet:Enterprise-grade fiber connectivity with redundant pathways and SLA-backed uptime guarantees. Cloud-based access control convergence in Calgary and Toronto enables same-day tenant provisioning that previously required extended installation timelines.
- Smart Office Solutions:Integrated environmental controls, occupancy sensors, and predictive maintenance systems. Competition Bureau scrutiny of contract transparency shapes how operators bundle these capabilities into base versus premium tiers.
- Video Conferencing:Dedicated AV equipment and acoustic treatment for hybrid collaboration.
- Cloud Storage:Secure data repositories with enterprise compliance certifications.
High-speed internet represents table stakes across all configurations while smart office solutions climb the fastest as a differentiation vector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Vancouver's Yaletown corridor exceeds Toronto's financial district by roughly fifteen percent, reflecting tighter supply constraints and higher amenity expectations among technology tenants. This asymmetry shapes operator site selection priorities across Canadian metropolitan markets.
Ontario
Toronto's financial district anchors enterprise demand for hybrid membership plans blending dedicated desks with meeting room flexibility. Health Canada's indoor air quality guidelines intersect with municipal building codes to elevate ventilation standards for shared workspaces. Technology startups concentrate in downtown Toronto's King Street corridor, accelerating adoption of cloud-based access control systems.
British Columbia
Vancouver's Yaletown tech corridor drives premium pricing for private office configurations with enterprise-grade fiber connectivity. Municipal zoning reforms eased commercial-to-office conversion rules, unlocking underutilized retail inventory. Competition Bureau scrutiny of lease term transparency shapes operator contract structures across Greater Vancouver.
Alberta
Calgary's downtown core revitalization creates acquisition opportunities at depressed asset valuations for flexible workspace operators. Provincial commercial tenancy legislation uncertainty regarding license-versus-lease classification creates tenant protection disputes. Technology startups and remote teams populate the Beltline district, drawn by flexible license terms and reduced occupancy costs.
Quebec
Montreal's Mile End technology cluster sustains demand for membership-based workspace models among venture-backed companies. Municipal zoning in Plateau-Mont-Royal facilitates commercial-to-office conversions for smaller-scale operators. Freelancers and creative industry tenants concentrate in Griffintown, prioritizing community-oriented coworking environments over corporate amenities.
Canada Flexible Office Space Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in facility management and modular partition supply. The Canada flexible office space market exhibits tiered fragmentation, with global brand infrastructure operators, premium private office specialists, and hospitality-forward service providers occupying distinct competitive positions. Three strategic archetypes dominate: volume-scale membership platforms, luxury-positioned private office operators, and mid-market corporate-focused service tiers. Consolidation through asset acquisition and revenue-sharing partnership structures represents the primary competitive vectors as operators seek geographic density.
Within the premium-tier vector, iQ Offices anchors positioning through downtown Toronto private office configurations. WeWork occupies the volume-scale membership platform archetype despite prior restructuring, leveraging global brand recognition in Toronto and Vancouver. Industrious exemplifies the hospitality-forward service tier targeting mid-market corporate clients with differentiated amenity packages. These three operators collectively represent the strategic positioning spectrum available to new entrants assessing market entry points.
| Leading Market Players |
|---|
| Workhaus |
| TCC Canada |
| International Workplace Group plc |
| Industrious |
| Vast Coworking Group |
| Spaces |
| iQ Offices |
| CBRE Group |
| WeWork |
| Others |
Value Chain & Pricing Dynamics
The Trans-Canada Highway freight corridor carries HVAC equipment and modular partition systems from Ontario manufacturing hubs to Calgary and Vancouver deployment sites, with fuel surcharges and driver scarcity compressing margins for operators while amplifying price spreads between premium private offices and volume hot-desking tiers.
Pricing Analysis
Corporate real estate teams anchor pricing negotiations through hybrid membership plans that unbundle amenities from base workspace fees. Three-tier pricing structure across premium, standard, and economy levels separates iQ Offices' luxury private suites from Industrious' hospitality-forward mid-market positioning and WeWork's volume membership base. Cost compression in the hot-desking tier is intensifying because municipal zoning reforms are accelerating supply entry across Toronto and Vancouver. Freelancers in Vancouver's Yaletown corridor exhibit the highest price sensitivity, while financial services tenants in downtown Toronto's financial district absorb premium markups for Health Canada-compliant ventilation certification.
Supply Chain Analysis
Export-control restrictions on enterprise-grade fiber networking equipment from US and Chinese suppliers are constraining rapid-deployment infrastructure for Canadian operators. Component sourcing draws from Mexico for modular partition manufacturing, the United States for cloud-based access control systems, and domestic Canadian fabricators for custom millwork. Single-source vulnerability concentrates in enterprise fiber connectivity hardware subject to cross-border tariff exposure. Distribution runs through national facility management contractors who bundle installation with ongoing HVAC optimization services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent operators must defend against substitution from remote-work technology platforms and distributed home-office stipends that erode demand for physical workspace membership.
For Market Incumbents: Pre-empt margin erosion by securing exclusive municipal zoning partnerships in Toronto and Vancouver before commercial-to-office conversion rules liberalize further. Acquire specialized HVAC engineering talent to differentiate on Health Canada indoor air quality compliance. Vertical integration into cloud-based access control deployment reduces per-seat IT costs and accelerates tenant onboarding timelines against WeWork's global infrastructure.
For New Entrants and Emerging Players: Establish a beachhead in Calgary's downtown core revitalization zone where depressed asset valuations and provincial license-versus-lease uncertainty have deterred established operators. Target mid-market corporate clients underserved between iQ Offices' premium positioning and WeWork's volume play. Lead with hospitality-forward service tiers featuring à-la-carte amenity structures that transfer utilization risk from tenants.
For Investors and Strategic Acquirers: Boutique operators with Health Canada pre-certified ventilation infrastructure and established municipal occupancy permits in Toronto or Vancouver represent the most defensible acquisition targets. Long-term viability hinges on enterprise client retention as hybrid work patterns stabilize. Watch for inflection signals in provincial commercial tenancy legislation that clarifies license-versus-lease classification and reduces operator liability exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Municipal Zoning Partnership | Exclusive commercial-to-office conversion rights in Toronto unlock underutilized retail inventory before competitors. |
| HVAC Certification Investment | Health Canada pre-compliance accelerates occupancy permitting and commands premium pricing from corporate tenants. |
| Enterprise Fiber Integration | Cloud-based access control convergence reduces provisioning timelines from weeks to same-day activation. |
| Hospitality Service Tier Launch | Mid-market positioning between luxury private offices and volume coworking captures underserved corporate procurement. |
| Calgary Asset Acquisition | Depressed downtown valuations create conversion opportunities at basis levels unavailable in Toronto or Vancouver. |
Study Parameters
Desk research of municipal zoning filings, Health Canada indoor air quality guidelines, and Competition Bureau regulatory notices preceded structured interviews with flexible office space operators, commercial real estate brokers, corporate facilities managers, and HVAC engineering consultants. Secondary validation drew from provincial commercial tenancy legislation databases, municipal building permit records, and industry association membership data. Bottom-up tenant demand estimates and top-down market sizing triangulated to produce volume and value outputs.
Assumptions regarding municipal zoning reform timelines, enterprise hybrid work adoption curves, and ventilation infrastructure retrofit cost trajectories were held fixed across baseline scenarios while sensitivity analysis varied these inputs. Segmentation modeling incorporated product type configurations, end-user procurement sophistication tiers, service type revenue models, and technology infrastructure deployment patterns. CAGRs were derived from trend extrapolation calibrated against historical absorption rates in Toronto and Vancouver submarkets.
Stress conditions across interest rate environments, remote work technology substitution rates, and provincial regulatory clarification timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about membership plan pricing stability and corporate real estate budget allocations. Material shifts in Health Canada ventilation standards or Competition Bureau contract transparency mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
India Flexible Office Space Market
Office Real Estate
Saudi Arabia Real Estate Brokerage Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
Office Real Estate Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Qatar Co-Working Office Spaces Market
Office Real Estate
United Kingdom Co-Working Office Spaces Market
Office Real Estate
Saudi Arabia Co-Working Office Spaces Market
Office Real Estate
Australia Co-Working Office Spaces Market
Office Real Estate
North America Office Real Estate Market
Office Real Estate
Europe Flexible Office Market
Office Real Estate
Saudi Arabia Flexible Office Space Market
Office Real Estate
Japan Office Real Estate Market
Office Real Estate
China Office Real Estate Market
Office Real Estate
Global Office Space Market
Office Real Estate
Bahrain Co-Working Office Space Market