
 India Flexible Office Space Market | 2026-2036
India Flexible Office Space Market Size, Share, and Industry Trends Forecast 2026-2036
India Flexible Office Space Market Foresight
Multi-source workspace procurement is consolidating as enterprises abandon rigid long-term leases for portfolio flexibility. Awfis Space Solutions dominates tier-one city penetration with asset-light franchise models. Smartworks anchors large-campuses-for-enterprises strategy across NCR and Bangalore. IndiQube differentiates through tech-integrated managed offices targeting mid-market IT services firms.
Flexible office space denotes commercially operated work environments offering short-tenure occupancy with shared infrastructure, typically provisioning 70-150 square feet per seat with integrated IT, F&B, and facility management. These spaces serve organizations seeking capital-efficiency in real estate without compromising workforce productivity or employer brand. Co-working spaces lead volume absorption yet private offices within managed environments capture disproportionate margin pools as enterprises prioritize security and customization. Serviced offices sustain steady uptake among consulting and legal sectors requiring immediate plug-and-play infrastructure with reception and secretarial support.
The Ministry of Commerce and Industry's Startup India initiative reduces compliance burden for workspace operators serving registered ventures, while municipal corporations in Delhi, Mumbai, and Hyderabad enforce fire safety and building code certifications that filter sub-scale operators. The Securities and Exchange Board of India governs REIT structures that increasingly channel institutional capital into grade-A flexible office assets. Stakeholders must track how state-level rental tenancy law reforms alter landlord-operator revenue-sharing structures and tenant eviction protections.
Market Dynamics
Enterprise real estate procurement is consolidating around hybrid workforce policies, compressing average lease tenures from five years to under eighteen months as occupiers prioritize capital flexibility over fixed asset control.
Growth Catalysts
- SEBI Startup Listing Norms:Relaxed disclosure requirements for emerging companies have unlocked institutional capital flows into co-working expansion, enabling operator scale-up across tier-one cities.
- IT Services Sector:Mid-market technology services firms are absorbing private managed offices at accelerated rates, prioritizing plug-and-play infrastructure over build-to-suit development timelines.
- Maharashtra Enterprise Corridor:Mumbai-Pune concentration of consulting and legal sector demand sustains premium occupancy rates for serviced offices with integrated reception and secretarial support.
Market Restraints
- Grade-A Supply Concentration:Institutional capital through REIT structures channels predominantly into Mumbai, Bengaluru, and Delhi NCR, leaving tier-two cities capital-starved for quality inventory.
- Municipal Certification Friction:Delhi, Mumbai, and Hyderabad corporations enforce divergent fire safety and building code standards, fragmenting operator compliance costs across jurisdictions.
- Long-Term Lease Substitution:Traditional commercial landlords in prime micro-markets are introducing flexible terms directly, eroding pure-play operator pricing power.
Strategic Opportunities
- Hyderabad Life Sciences Cluster:Genome Valley and surrounding research parks present underpenetrated demand for compliance-ready lab-flex space with controlled environment capabilities.
- Startup India Incentive Stack:Reduced compliance burden for registered ventures creates margin expansion for operators serving certified startup cohorts with bundled regulatory support.
- Smart Building Convergence:Integration of IoT occupancy sensors with access control systems is enabling dynamic pricing models that capture previously unrealized yield from peak-hour demand.
Industry Challenges
- Facilities Management Talent Scarcity:Operators face acute shortages of certified building managers capable of maintaining enterprise-grade uptime SLAs across distributed portfolios.
- State Tenancy Law Divergence:Pending rental reforms in Maharashtra, Karnataka, and Telangana create uncertainty around landlord-operator revenue-sharing structures and tenant eviction protections.
- Integration Complexity:Enterprise clients demand seamless connection with legacy ERP and identity management systems, stretching operator IT engineering capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Flexible Office Space Market |
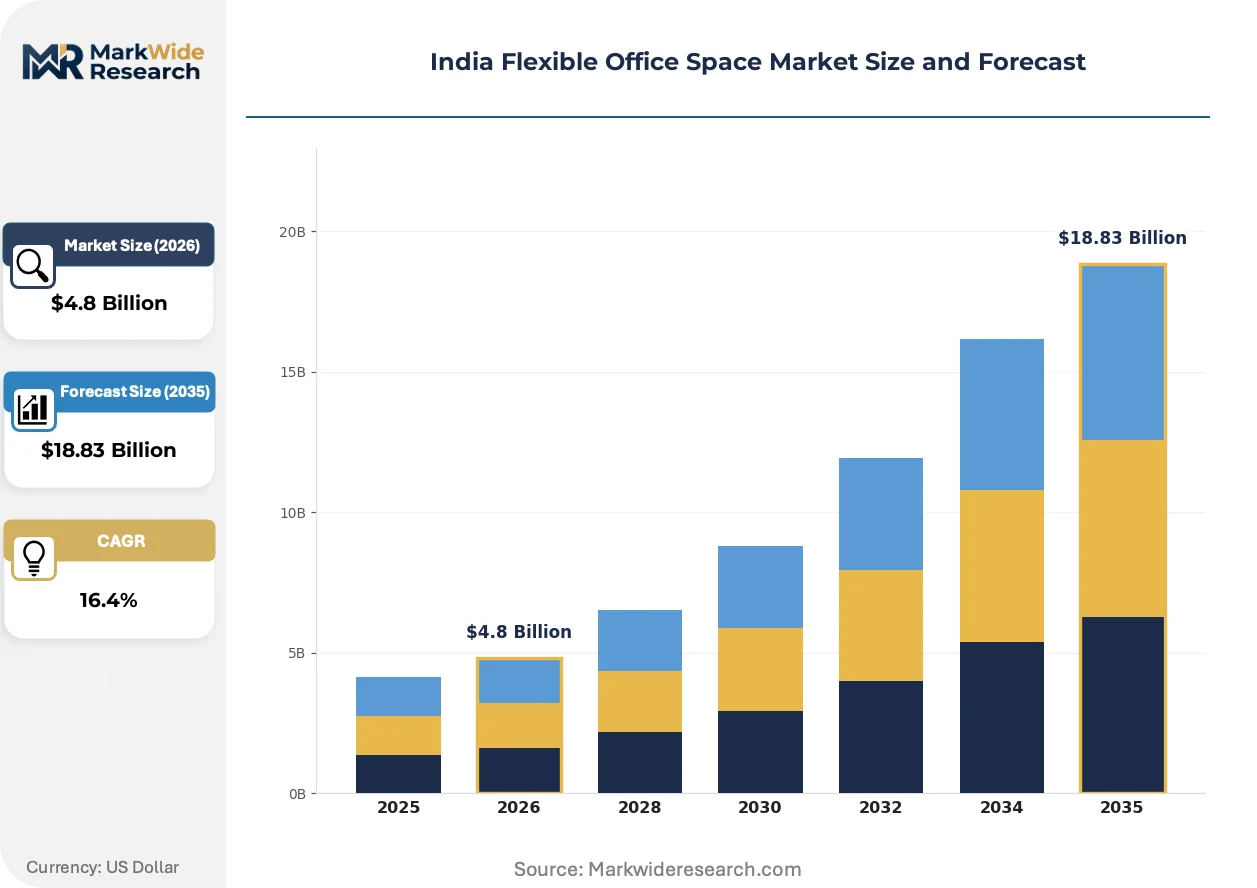
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.83 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Co-working Spaces, Serviced Offices, Virtual Offices, Hot Desking End User: Startups, Freelancers, SMEs, Enterprises Service Type: Membership Plans, Dedicated Desks, Private Offices, Meeting Rooms Pricing Model: Monthly Subscription, Pay-per-use, Annual Plans, Flex Pricing |
| Companies Covered | WeWork, Awfis Space Solutions, Smartworks, IndiQube, Simpliwork Offices, CoWrks, 91Springboard, The Hive, BHIVE Workspace, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Flexible Office Space Market Shifts & Advancements
Workspace technology stacks are converging around unified platform architectures that collapse previously separate building, IT, and employee experience systems into single-vendor deployments.
Integrated workplace management platforms are unifying access control, desk booking, and environmental monitoring into single-pane dashboards. Large enterprise occupiers in Bengaluru and Mumbai are mandating these systems for portfolio-wide deployments. This consolidation is compressing vendor margins while elevating data interoperability standards that lock out point-solution providers.
SEBI's evolving REIT guidelines are expanding eligible asset classes to include stabilized flexible office portfolios with three-year operating histories. Institutional sponsors are restructuring existing co-working assets to meet yield stability thresholds. Operators with concentrated Mumbai and Delhi NCR exposure are prioritizing longer-tenure enterprise contracts to qualify for inclusion.
Occupiers are unbundling space procurement from bundled service contracts, separating real estate, IT infrastructure, and F&B into discrete vendor relationships. Consulting and financial services firms in the Mumbai-Pune corridor are leading this disaggregation, driving operators to compete on pure space economics rather than amenity premiums. This pattern is most visible among firms with centralized procurement functions and established vendor management capabilities.
India Flexible Office Space Market Segmentation
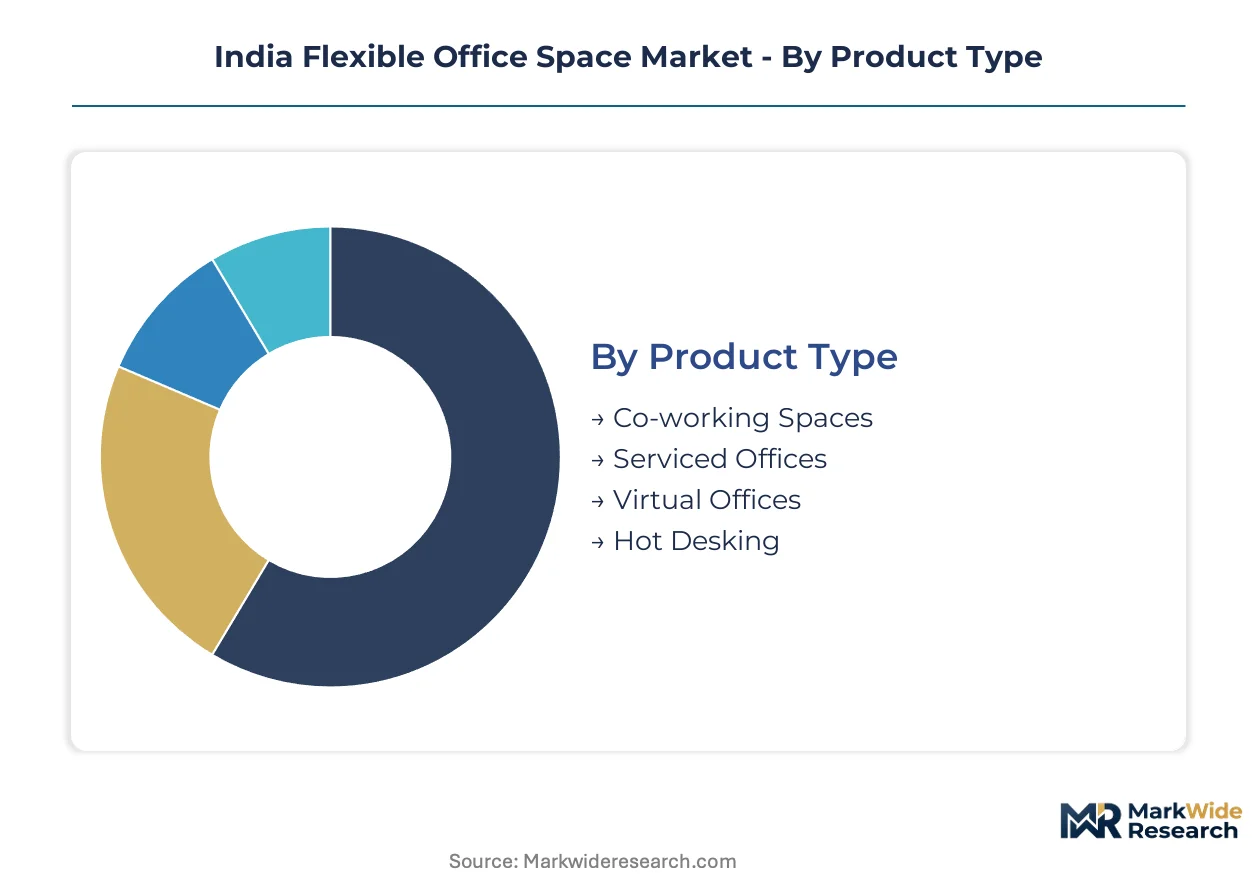
Flexible office space procurement varies sharply by organization size, tenure preference, and infrastructure requirements. Understanding these segment boundaries clarifies where operators can extract premium yields versus where volume throughput dominates economics.
Product Type:
Volume absorption concentrates in shared environments while margin pools sit with enclosed, customizable infrastructure.
- Co-working Spaces:Open-plan environments with 70-150 square feet per seat provisioning shared IT, F&B, and facility management. Demand clusters among Bengaluru technology startups seeking capital-efficient real estate without employer brand compromise. SEBI's relaxed startup listing norms have accelerated operator scale-up in this segment.
- Serviced Offices:Plug-and-play private suites with integrated reception and secretarial support, commanding premium occupancy in the Mumbai-Pune corridor. Consulting and legal sectors sustain uptake here due to immediate infrastructure requirements and client-facing imperatives.
- Virtual Offices:Address registration and mail handling services without physical occupancy, serving distributed teams requiring commercial credibility.
- Hot Desking:Unassigned daily seat access through mobile booking platforms, capturing intermittent workspace demand from gig-economy professionals.
Mature deployment sits with Serviced Offices. Newer deployment is concentrated in Co-working Spaces.
End User:
Customer type determines contract structure, with large occupiers extracting customization concessions and smaller users accepting standardized terms.
- Enterprises:Organizations with 500+ employees procuring private managed offices through centralized real estate functions, mandating unified workplace management platforms and ERP integration. These clients are unbundling space from bundled service contracts in the Mumbai-Pune corridor.
- SMEs:Mid-market firms prioritizing plug-and-play infrastructure over build-to-suit development timelines, absorbing private offices at accelerated rates across Delhi NCR and Bangalore.
- Startups:Registered ventures leveraging Startup India compliance reductions, creating margin expansion for operators serving certified cohorts with bundled regulatory support.
- Freelancers:Individual professionals accessing membership plans and hot desking arrangements, price-sensitive and churn-prone.
Contract sophistication concentrates with Enterprises. Volume expansion is accelerating fastest among Startups.
Service Type:
Physical enclosure level directly correlates with security requirements and pricing power.
- Private Offices:Enclosed suites with dedicated access control and customization rights, capturing disproportionate margin pools as enterprises prioritize security and brand expression. Operators with concentrated Mumbai and Delhi NCR exposure prioritize longer-tenure contracts here to qualify for REIT inclusion.
- Dedicated Desks:Assigned seating within shared environments, bridging individual permanence with communal infrastructure economics.
- Meeting Rooms:Bookable conference and collaboration spaces, increasingly provisioned with IoT occupancy sensors enabling dynamic yield capture from peak-hour demand.
- Membership Plans:Tiered access packages bundling multiple service types, standardizing procurement for smaller occupiers.
Security-sensitive deployment sits with Private Offices. Technology-integrated deployment is expanding most quickly in Meeting Rooms.
Pricing Model:
Tenure commitment and predictability trade off against flexibility premiums in operator revenue recognition.
- Monthly Subscription:Recurring fixed fees for defined service tiers, dominating SME and startup procurement with predictable cash flow for operators.
- Annual Plans:Prepaid commitments securing rate locks and priority access, preferred by enterprises with budget certainty requirements.
- Pay-per-use:Consumption-based charging for actual occupancy hours, aligning costs with hybrid workforce policies compressing average lease tenures.
- Flex Pricing:Dynamic rate adjustment based on real-time demand signals and occupancy sensors, emerging as operators integrate smart building convergence.
Established billing sits with Monthly Subscription. Algorithmic deployment is climbing the fastest in Flex Pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial real estate development across India concentrates in five state-level corridors where SEBI-regulated capital flows and municipal building codes shape operator expansion trajectories.
Maharashtra
Mumbai-Pune enterprise demand sustains premium occupancy for serviced offices with integrated reception infrastructure. The state's municipal corporations enforce divergent fire safety certifications that fragment compliance costs. Consulting and legal sector clusters in Mumbai's Bandra-Kurla Complex command immediate plug-and-play workspace procurement.
Karnataka
Bengaluru technology startups absorb co-working space at accelerated rates following hybrid work policy stabilization. The state's participation in Startup India reduces compliance burden for operators serving registered ventures. Electronic City and Whitefield micro-markets concentrate mid-market IT services firm demand for tech-integrated managed offices.
Telangana
Hyderabad's Genome Valley life sciences cluster presents underpenetrated demand for compliance-ready lab-flex environments. State-level rental tenancy law reforms create uncertainty around landlord-operator revenue-sharing structures. HITEC City and Gachibowli sub-markets anchor enterprise-grade private office absorption.
Delhi-NCR
Large-campuses-for-enterprises strategies concentrate in Gurugram and Noida as occupiers mandate unified workplace management platforms. Municipal corporations enforce building code standards that filter sub-scale operators. Aerocity and Cyber Hub micro-markets sustain premium pricing for security-sensitive enclosed suites.
Tamil Nadu
Chennai's automotive and electronics manufacturing base generates ancillary demand for flexible project offices and engineering collaboration spaces. State industrial policy incentives for IT/ITES sectors attract operator franchise expansion. OMR and Guindy industrial corridors concentrate SME-grade workspace procurement.
India Flexible Office Space Market Competitive Landscape
Global majors compete with regional champions across capital structure and asset ownership models, producing a tiered competitive field. Asset-light franchise operators dominate tier-one city penetration while REIT-structured sponsors concentrate grade-A inventory in Mumbai and Delhi NCR. Three archetypes define the field: global platform licensors, domestic scale operators, and specialized managed office providers. Consolidation through portfolio acquisitions and landlord-operator joint ventures represents the dominant competitive movement.
Within the domestic scale operator tier, Awfis Space Solutions exemplifies asset-light expansion through franchise partnerships, while Smartworks anchors large-campus enterprise delivery. IndiQube occupies a position bridging mid-market specialization with technology integration. These three entities collectively represent how Indian operators are responding to enterprise demands for shorter lease tenures and unified platform architectures.
| Leading Market Players |
|---|
| WeWork |
| Awfis Space Solutions |
| Smartworks |
| IndiQube |
| Simpliwork Offices |
| CoWrks |
| 91Springboard |
| The Hive |
| BHIVE Workspace |
| Others |
Supply & Pricing Matrix
REIT-structured sponsors with concentrated Mumbai and Delhi NCR exposure enforce pricing discipline through yield stability thresholds, compressing operator margins while elevating capital barriers for sub-scale entrants. This ownership pattern feeds directly into supply chain decisions, as institutional capital channels predominantly into grade-A assets with three-year operating histories, starving tier-two cities of quality inventory.
Pricing Analysis
Service-bundling differentiation separates operators competing on pure space economics from those capturing amenity premiums. Three-tier pricing structure across enterprise-grade private offices, mid-market managed suites, and startup-focused co-working seats reflects security certification levels and customization rights. Cost compression in the co-working tier is intensifying because traditional commercial landlords are introducing flexible terms directly, eroding pure-play pricing power. Startups and freelancers exhibit highest price sensitivity, while enterprises with centralized procurement functions extract rate locks through annual prepaid commitments.
Supply Chain Analysis
Single-source vulnerability sits with facilities management talent pools certified for enterprise-grade uptime SLAs across distributed portfolios. Grade-A supply concentrates in Maharashtra, Karnataka, and Telangana, drawing from construction materials, IoT sensor hardware, and integrated workplace management software. Supply chain risk centers on municipal certification friction, as Delhi, Mumbai, and Hyderabad corporations enforce divergent fire safety and building code standards. Distribution runs through landlord-operator joint ventures and franchise partnerships that dominate tier-one city penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
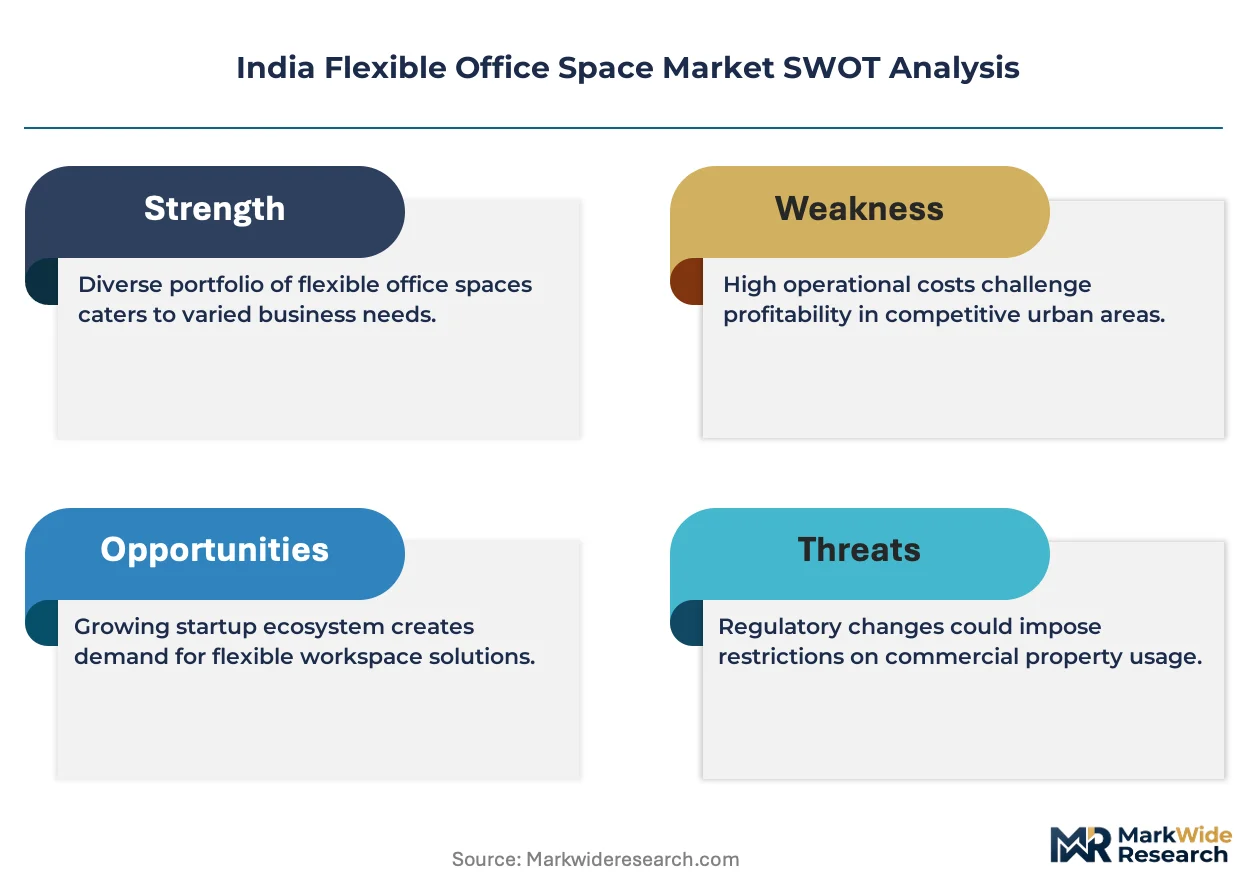
SEBI's evolving REIT guidelines function as a cost-of-compliance moat, filtering sub-scale operators unable to meet yield stability thresholds while rewarding sponsors with three-year operating histories and concentrated grade-A exposure.
For Market Incumbents: Extend large-campus enterprise delivery capabilities in Gurugram and Noida to capture unbundled procurement demand from consulting and financial services firms. Deepen landlord-operator joint venture structures to defend against traditional commercial landlords introducing flexible terms directly. Prioritize longer-tenure enterprise contracts to qualify for REIT inclusion and lock out emerging franchise competitors. For New Entrants and Emerging Players: Municipal corporations in tier-two cities present partnership opportunities for operators willing to navigate fragmented compliance costs. Hyderabad's Genome Valley life sciences cluster offers the most penetrable white-space target for compliance-ready lab-flex space with controlled environment capabilities. Position through state industrial policy incentives and bundled regulatory support for Startup India registered ventures. For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-light franchise operators with proven tier-one city penetration in Bengaluru and Mumbai. The five-to-ten year viability window rewards sponsors restructuring existing co-working assets to meet SEBI yield stability thresholds. Watch state-level rental tenancy law reforms in Maharashtra, Karnataka, and Telangana as the signal for landlord-operator revenue-sharing structure clarity.| Strategic Initiative | Industry Significance |
|---|---|
| REIT Qualification Restructuring | SEBI's expanded eligible asset classes unlock institutional capital for stabilized flexible office portfolios. |
| Smart Building Convergence | IoT occupancy sensor integration enables dynamic pricing models capturing peak-hour demand yield. |
| State Tenancy Law Navigation | Pending reforms in Maharashtra, Karnataka, and Telangana reshape landlord-operator revenue-sharing certainty. |
| Enterprise Platform Unification | Single-pane dashboards consolidating access control and desk booking lock out point-solution providers. |
| Lab-Flex Capability Buildout | Genome Valley and surrounding research parks demand compliance-ready controlled environment workspaces. |
Research Methodology
Independent corroboration across workspace operator executives, enterprise real estate procurement directors, and municipal corporation building officials underwrites the qualitative findings. Primary fieldwork with franchise partners, REIT sponsors, and facilities management certification bodies combined with secondary validation from SEBI regulatory filings, municipal building code databases, and Startup India registration records. Bottom-up absorption estimates triangulate against top-down capital flow analysis.
Rate-of-change decomposition across the analysis window segments volume and value by product type, end user organization size, service enclosure level, and pricing model commitment structure. CAGRs derive from enterprise lease tenure compression patterns, hybrid workforce policy adoption curves, and institutional capital allocation shifts into grade-A assets. Industry-specific forecast inputs include IT services sector headcount expansion and SEBI REIT guideline evolution timelines.
Caveats apply where state-level rental tenancy law reforms or municipal certification standard harmonization could materially shift the outlook. Forecasts reflect assumptions about hybrid work policy stabilization and institutional capital flow continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
Italy Office Real Estate Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
United States Office Real Estate Market
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
North America Flexible Office Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
Office Real Estate Market
Office Real Estate
China Flexible Office Space Market
Office Real Estate
Australia Co-Working Office Spaces Market
Office Real Estate
Europe Office Real Estate Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
North America Office Real Estate Market