
 United Kingdom Office Real Estate Market | 2026-2036
United Kingdom Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Office Real Estate Market Analytics
Minimum Energy Efficiency Standards is broadening the cost-of-entry calculus for landlords across England and Wales. British Land leverages its in-house sustainability team to retrofit legacy assets ahead of regulatory deadlines. Derwent London anchors its portfolio strategy around central London clusters where MEES compliance yields rental premiums. Savills competes through advisory services that quantify green capex against regulatory risk.
United Kingdom office real estate encompasses commercial buildings designed for administrative, professional, and service-sector operations, typically constructed with steel or reinforced concrete frames, floor plates of 8,000 to 20,000 square feet, and Building Research Establishment Environmental Assessment Method ratings that determine marketability. The primary commercial purpose is to generate rental income through lease contracts while providing environments that support knowledge-worker productivity and corporate identity. Co-working spaces and serviced offices are capturing the fastest-growing share of new lettings as occupiers prioritize flexibility over fixed commitments. Traditional offices still dominate total stock volume but face structural pressure on margins where lease lengths shorten and tenant improvement allowances expand.
The Building Safety Regulator enforces stricter accountability for higher-risk building standards under the Building Safety Act, while the Financial Conduct Authority shapes disclosure requirements for real estate investment trusts and institutional capital allocation. Local planning authorities across Greater London, Birmingham, and Manchester apply increasingly granular sustainability conditions that filter development pipeline viability. Stakeholders must monitor how evolving energy performance certificates and embodied carbon thresholds reshape asset obsolescence timelines and refinancing assumptions.
Market Dynamics
The Minimum Energy Efficiency Standards are compressing asset obsolescence timelines across England and Wales. Landlords now face binary outcomes: retrofit to Grade A sustainability or accept stranded capital as tenant demand concentrates in compliant stock.
Growth Catalysts
- MEES 2027 Threshold:The regulatory mandate requiring EPC Band C minimums is accelerating capital deployment into retrofit programs ahead of enforcement deadlines.
- Life Sciences Clustering:Oxford and Cambridge knowledge corridors are pulling specialized laboratory-office hybrid demand from pharmaceutical and biotech tenants.
- Flexible Lease Structures:Co-working operators are capturing tenant preference for short-term commitments, expanding their share of gross absorption in London and Manchester.
Market Restraints
- Construction Cost Inflation:Steel and concrete input volatility is eroding development feasibility margins on speculative office schemes.
- Debt Market Contraction:Commercial mortgage availability from UK clearing banks has tightened, constraining refinancing options for value-add strategies.
- Hybrid Work Normalization:Occupiers are rightsizing footprints by 15-30% compared to 2019 baselines, structurally reducing aggregate demand intensity.
Strategic Opportunities
- West Midlands Regeneration:Birmingham's Big City Plan infrastructure commitments are opening development corridors with lower land basis than London comparables.
- Building Safety Act Compliance Services:The Building Safety Regulator's accountability framework is creating advisory revenue streams for technical due diligence providers.
- Embodied Carbon Disclosure:CSRD-aligned reporting requirements are differentiating assets with verified whole-life carbon assessments, commanding rental premiums.
Industry Challenges
- Retrofit Skill Shortage:Qualified building surveyors and MEP engineers with deep refurbishment experience are in acute supply deficit across the South East.
- Planning Permission Delays:Local authority capacity constraints in Greater London are extending determination timelines to 18-24 months, freezing capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Office Real Estate Market |
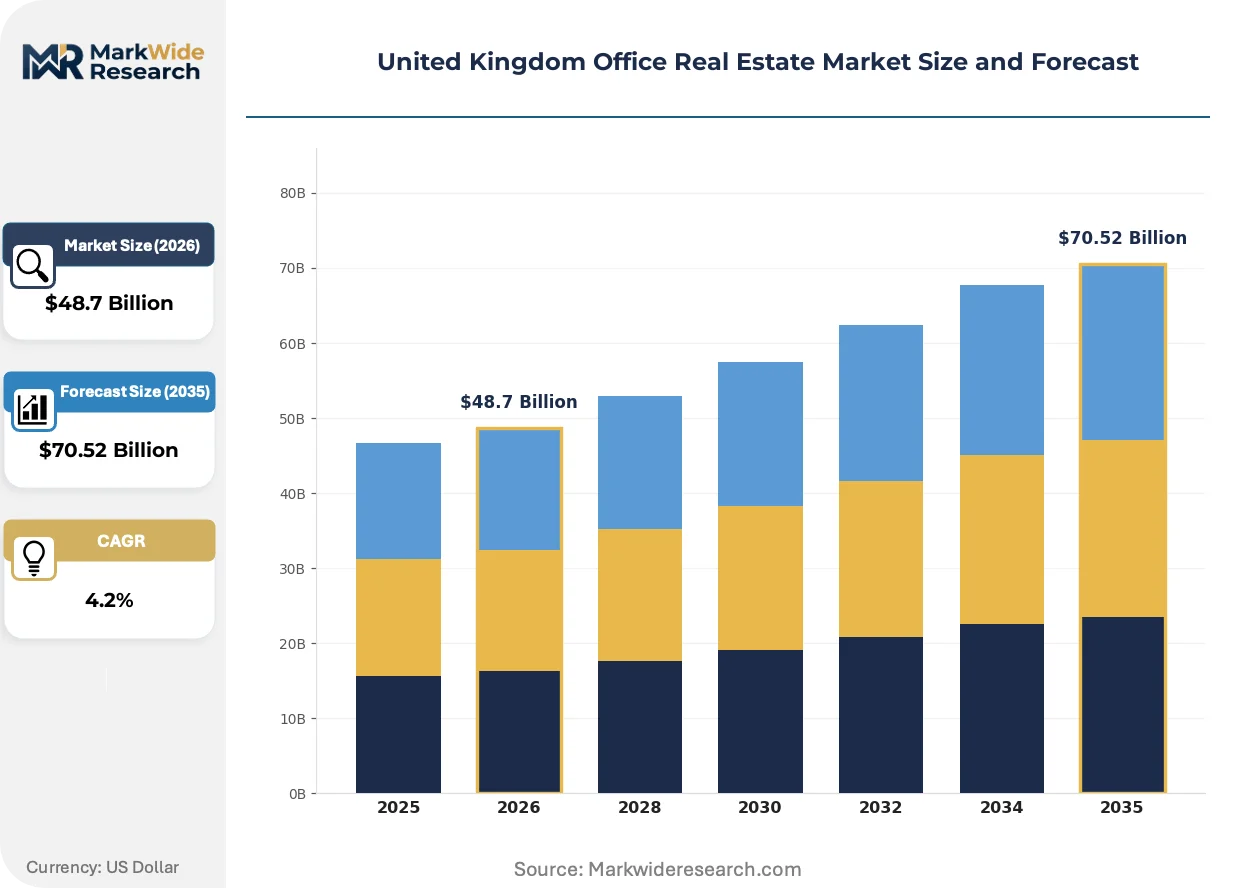
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $70.52 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Co-working Spaces, Traditional Offices, Business Centers, Executive Suites Client Type: Startups, SMEs, Corporates, Freelancers Lease Type: Short-term Leases, Long-term Leases, Flexible Contracts, Subleases Service Type: Full-service Offices, Managed Offices, Virtual Offices, Serviced Offices |
| Companies Covered | CBRE, Jones Lang LaSalle, Savills, Knight Frank, Cushman & Wakefield, Landsec, British Land, Derwent London, Great Portland Estates, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Office Real Estate Market Evolving Landscape
Smart building infrastructure is rewiring how office assets compete for tenant retention. The convergence of operational technology with sustainability reporting is creating new performance benchmarks that separate investable stock from obsolescing inventory.
Internet of Things sensor networks are decentralizing building management from centralized BMS architectures to edge-computing nodes. Mid-market landlords in Manchester and Birmingham are piloting these systems to reduce energy intensity without full-scale refurbishment. The technology is decentralizing capital planning decisions, allowing phased upgrades rather than lump-sum redevelopment.
The Building Safety Act establishes the Building Safety Regulator as the enforcement authority for higher-risk residential and commercial structures. Dutyholder accountability now extends through design, construction, and occupation phases. Commercial office developers in London are responding by front-loading technical assurance costs into pre-construction budgets.
Tenant experience platforms are displacing traditional property management interfaces as the primary occupier touchpoint. Flexible workspace providers are bundling these digital services into membership fees, while institutional landlords retrofit legacy assets with app-based amenity access. This shift is most pronounced in London's West End and City fringe submarkets where tenant retention determines valuation stability.
United Kingdom Office Real Estate Market Segmentation
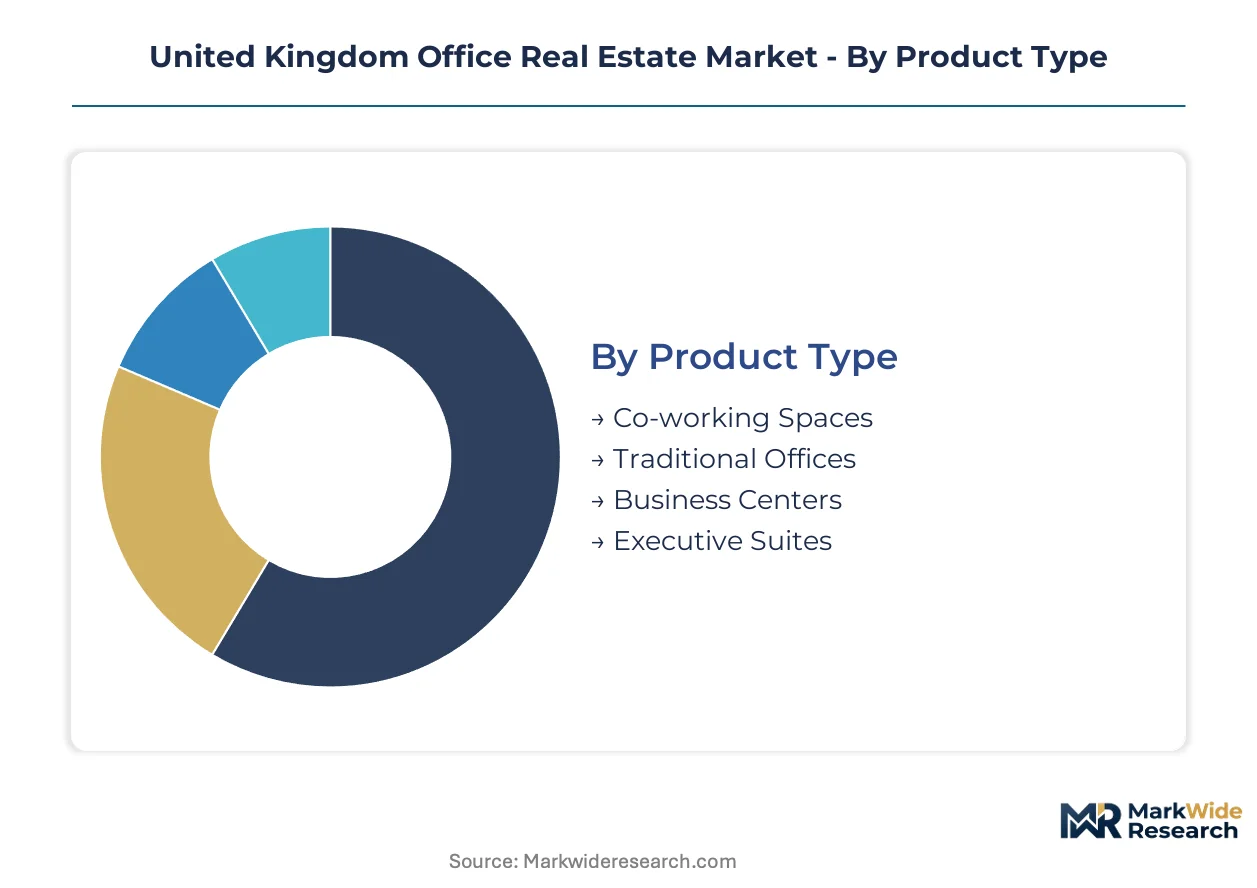
Segmentation reveals how capital deployment and tenant procurement strategies diverge across the United Kingdom office real estate landscape. Landlords must align product configuration with lease structure and service intensity to capture differentiated rental premiums.
Product Type:
Capital intensity varies sharply across product categories, with full-scale redevelopment of traditional offices demanding substantially higher upfront commitment than fit-out-heavy flexible formats.
- Co-working Spaces:Operators fit out shell-and-core space with modular furniture, high-density networking infrastructure, and shared amenity zones. Demand concentrates among technology sector tenants in London and Manchester seeking month-to-month scalability without covenant exposure.
- Traditional Offices:These assets require reinforced concrete or steel frames with floor plates spanning 8,000 to 20,000 square feet and Building Research Establishment Environmental Assessment Method ratings that determine marketability. Corporates in the South East prioritize Grade A sustainable stock to satisfy Minimum Energy Efficiency Standards compliance mandates.
- Business Centers:Hybrid formats combining dedicated suites with shared reception and meeting facilities serve professional services firms needing client-facing infrastructure without full-floor commitments.
- Executive Suites:Premium private offices with concierge-level services target senior executives and boutique advisory practices in London's West End and City fringe submarkets.
Most installed capacity flows through Traditional Offices. Expansion is steepest in Co-working Spaces.
Client Type:
Tenant credit quality and lease duration preferences segment procurement risk profiles for United Kingdom landlords.
- Startups:Venture-backed technology companies in Cambridge and Oxford knowledge corridors favor short-term flexible contracts with minimal capital expenditure exposure.
- SMEs:Regional professional services firms across Birmingham and Manchester seek managed offices balancing cost control with branded presence.
- Corporates:Multinational occupiers drive demand for long-term leased Grade A space with embedded sustainability credentials and building safety act compliance assurance.
- Freelancers:Independent consultants and creative professionals sustain virtual office and hot-desking demand in secondary United Kingdom cities.
Corporates anchor rental income stability. Startups are expanding most quickly.
Lease Type:
Contract structure determines revenue predictability and refinancing collateral value for United Kingdom office assets.
- Short-term Leases:Agreements under 24 months dominate co-working and serviced office formats, requiring landlords to absorb higher tenant turnover costs and void risk.
- Long-term Leases:Five-to-ten-year covenants with rent review mechanisms remain standard for institutional-grade traditional offices in London and the South East.
- Flexible Contracts:Membership-based arrangements with all-inclusive pricing capture occupiers prioritizing operational agility over balance-sheet control.
- Subleases:Corporate tenants with excess capacity lease surplus space to third parties, creating secondary market liquidity in oversupplied submarkets.
Long-term Leases dominate institutional portfolios. Flexible Contracts are gaining share fastest.
Service Type:
Service intensity tiers separate premium-margined offerings from commoditized space provision across United Kingdom office markets.
- Full-service Offices:Landlords deliver comprehensive property management, reception, cleaning, and maintenance bundled into headline rents, prevalent in prime London districts.
- Managed Offices:Customized fit-out and dedicated facilities management support mid-market corporates seeking branded environments without capital deployment.
- Virtual Offices:Mailing address, call handling, and meeting room access packages serve remote-first businesses maintaining professional registration presence.
- Serviced Offices:Plug-and-play accommodation with shared infrastructure and immediate availability targets rapid market entry and project-based occupancy.
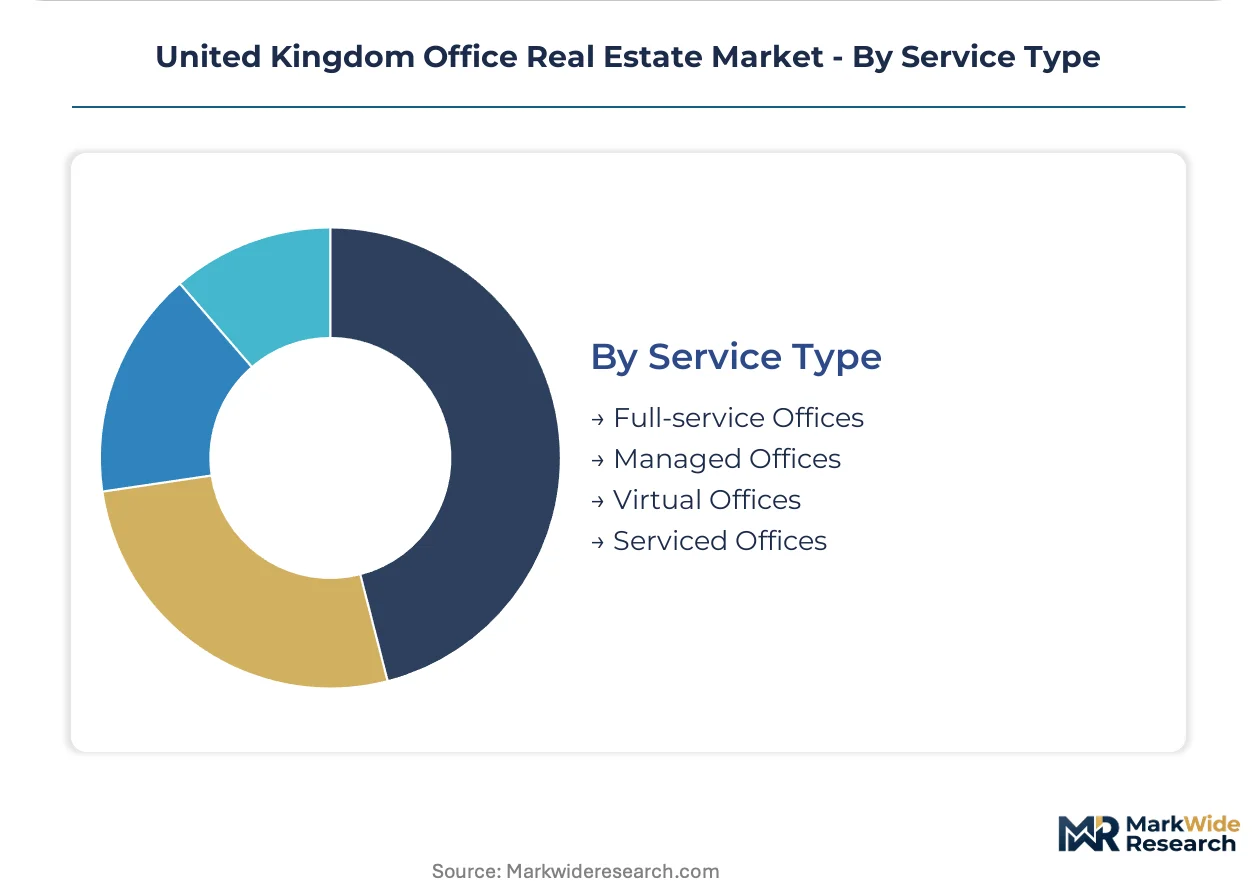
Full-service Offices command the deepest market penetration. Managed Offices show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Knowledge-worker clustering across Greater London, the Midlands, and Northern England anchors regional demand patterns. Technology sector expansion and life sciences clustering drive sub-market differentiation. Regulatory enforcement of energy efficiency and building safety standards varies in intensity across England, Scotland, and Wales.
Greater London and the South East
Financial services and technology sector tenants dominate Grade A absorption in the City and West End. The Greater London Authority applies granular sustainability conditions through the London Plan that filter development viability. Canary Wharf and King's Cross knowledge clusters attract multinational corporates seeking MEES-compliant stock with embedded smart building infrastructure.
West Midlands
Professional services firms and advanced manufacturing occupiers drive demand in Birmingham's central business district. Birmingham City Council's Big City Plan infrastructure commitments accelerate development corridor activation. The Colmore Row and Snow Hill districts attract regional headquarters seeking lower land basis than London comparables.
North West England
Technology sector tenants and media companies expand footprints across Manchester's Spinningfields and Northern Quarter districts. Manchester City Council applies progressive planning frameworks that prioritize brownfield regeneration over greenfield release. The Oxford Road corridor anchors life sciences and university spin-out demand.
Scotland
Financial services and energy sector occupiers sustain Edinburgh's office market while Glasgow attracts shared services and back-office functions. The Scottish Government's energy efficiency regulations run parallel to MEES with earlier enforcement timelines. Edinburgh's Exchange District and Glasgow's International Financial Services District concentrate institutional-grade development activity.
Wales
Public sector and professional services tenants anchor Cardiff's office demand with limited speculative development pipeline. Welsh Government planning policy emphasizes city center regeneration and sustainable transport linkages. Cardiff Bay and the central business district attract regional office requirements from legal and insurance sectors.
United Kingdom Office Real Estate Market Competitive Landscape
The competitive structure tilts toward integrated real estate services platforms with advisory, investment management, and development capabilities. Listed property companies and private equity-backed platforms compete for prime development sites and standing asset acquisitions. Two strategic archetypes dominate: diversified REITs with in-house retrofit capabilities, and advisory-led platforms monetizing technical due diligence expertise. Competitive moves concentrate on portfolio recycling into sustainable stock and advisory service expansion into building safety compliance.
Among London-focused REITs with central district concentrations, Derwent London, British Land, and Great Portland Estates exemplify the premium-tier landlord archetype. These entities occupy positions where MEES compliance and building safety assurance command rental premiums. Advisory and transaction service providers including CBRE, Jones Lang LaSalle, and Savills anchor the professional services tier, offering capital deployment guidance that quantifies green capex against regulatory risk. The competitive dynamic separates entities with captive development pipelines from those dependent on third-party construction delivery.
| Leading Market Players |
|---|
| CBRE |
| Jones Lang LaSalle |
| Savills |
| Knight Frank |
| Cushman & Wakefield |
| Landsec |
| British Land |
| Derwent London |
| Great Portland Estates |
| Others |
Value Network & Pricing Analysis
Grade A sustainable office premiums versus secondary stock discounts bifurcate United Kingdom capital deployment, with MEES-compliant assets commanding rental escalations that justify green capex while non-compliant buildings face accelerated value erosion and restricted financing access.
Pricing Analysis
Bundled full-service contracts dominate prime London districts where landlords package property management, reception, and maintenance into headline rents, while unbundled flexible formats in Manchester and Birmingham separate space costs from amenity fees. Price differentiation rests on BREEAM certification tiers and embedded smart building infrastructure rather than location alone. Cost compression in secondary stock is intensifying because tenant demand concentrates in compliant assets, forcing distressed repricing of aging inventory. SMEs and regional professional services firms exhibit highest price sensitivity, whereas multinational corporates absorbing long-term leases prioritize sustainability credentials over nominal rent levels.
Supply Chain Analysis
Dual-sourcing requirements from institutional investors and REITs mandate multi-contractor qualification for steel frame fabrication, MEP systems, and façade engineering to mitigate completion risk on retrofit programs. Manufacturing concentration centers on China for steel and glazing components, Germany for precision HVAC equipment, and domestic United Kingdom fabricators for structural concrete elements. Raw material dependencies span structural steel, low-carbon concrete, and high-performance glazing systems. Single-source vulnerability in qualified MEP engineering talent across the South East constrains project velocity. Distribution runs through tiered general contracting hierarchies with specialist subcontractor networks feeding regional development clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom office real estate market functions as a regulatory compounder where MEES 2027 enforcement deadlines concentrate capital into retrofit pipelines ahead of obsolescence cliffs.
For Market Incumbents: Deepen in-house sustainability capabilities to capture retrofit premiums before regulatory deadlines strand non-compliant assets. Acquire qualified building surveyors and MEP engineers to address acute skill shortages constraining project delivery. Expand technical assurance services into Building Safety Act compliance to monetize regulatory complexity as advisory revenue. For New Entrants and Emerging Players: Enter via Birmingham's Big City Plan corridors where land basis discounts versus London create development feasibility at lower capital intensity. Target West Midlands regeneration zones with speculative Grade A schemes ahead of infrastructure completion. Pursue joint venture structures with established contractors to overcome single-source vulnerability in qualified construction labor. For Investors and Strategic Acquirers: Consolidation pressure builds where retrofit skill shortages and capital intensity barriers prevent smaller landlords from achieving MEES compliance independently. Frame five-to-ten-year viability around portfolio exposure to 2027 EPC Band C thresholds and subsequent embodied carbon disclosure requirements. Monitor planning permission determination timelines across Greater London local authorities as inflection indicator for development pipeline velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit Program Acceleration | MEES 2027 deadlines compress asset obsolescence timelines across England and Wales. |
| Smart Building Infrastructure Deployment | IoT sensor networks in Manchester and Birmingham reduce energy intensity without full-scale redevelopment. |
| Life Sciences Cluster Development | Oxford and Cambridge knowledge corridors pull specialized laboratory-office hybrid demand from pharmaceutical tenants. |
| Flexible Lease Structure Expansion | Co-working operators capture tenant preference for short-term commitments in London and Manchester. |
| Technical Assurance Service Buildout | Building Safety Regulator accountability frameworks create advisory revenue for due diligence providers. |
Research Methodology
Coverage spans Greater London, the West Midlands, North West England, Scotland, and Wales, with primary inputs from each region combined with secondary validation. Interviews with asset managers at listed REITs, development directors at major contractors, planning officers at Greater London and Manchester authorities, and sustainability consultants at advisory firms informed demand and supply-side dynamics. Secondary sources include MHCLG planning statistics, UK Finance lending data, BREEAM certification registers, and local authority development pipeline disclosures. Bottom-up project-level data triangulates against top-down regional absorption estimates.
Granularity-level modeling disaggregates volume and value outputs by product type, client segment, lease structure, and service intensity tier across the projection horizon. CAGRs derive from regression analysis against macroeconomic indicators, regulatory enforcement schedules, and construction cost indices. Industry-specific forecast inputs capture technology sector employment growth in knowledge corridors and pharmaceutical R&D expansion in Oxford-Cambridge arc.
Inputs from MHCLG and UK Finance were available through the study window; gaps in real-time construction cost inflation data introduce uncertainty bands around development feasibility margins. Forecasts reflect assumptions regarding MEES enforcement rigor, hybrid work stabilization patterns, and debt market liquidity conditions. Deviation in Bank of England policy rate trajectory or local authority planning capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Australia Co-Working Office Spaces Market
Office Real Estate
Japan Office Real Estate Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
Saudi Arabia Real Estate Brokerage Market
Office Real Estate
France Office Real Estate Market
Office Real Estate
Flexible Office Market
Office Real Estate
United States Office Real Estate Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
Bahrain Flexible Office Space Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
China Flexible Office Space Market
Office Real Estate
South Korea Office Real Estate Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
India Office Real Estate Market
Office Real Estate
Office Real Estate Market
Office Real Estate
Asean Office Real Estate Market