
 France Office Real Estate Market | 2026-2036
France Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
France Office Real Estate Market Foresight
The capital-intensity gap between institutional landlords and mid-tier developers is collapsing as energy retrofit mandates require uniform compliance spending. Gecina leverages its Paris-centric Grade A portfolio to sustain premium lease rates across Île-de-France. BNP Paribas Real Estate anchors its competitive position through integrated asset management and development capabilities. Covivio differentiates by dominating mixed-use schemes that blend office, residential, and hospitality functions.
France office real estate comprises commercial buildings designed for professional services occupancy, typically featuring floor plates exceeding 500 square meters, HVAC systems meeting RE2020 thermal performance thresholds, and structured cabling supporting dense digital infrastructure. High-Rise Towers in La Défense and central Paris command the deepest tenant queues and highest effective rents. Shared Workspaces represent the fastest-expanding Property Type segment as hybrid work patterns reshape corporate footprint strategies. Grade A Building Classification assets capture disproportionate capital flows as institutional investors prioritize energy efficiency credentials and long-dated income visibility.
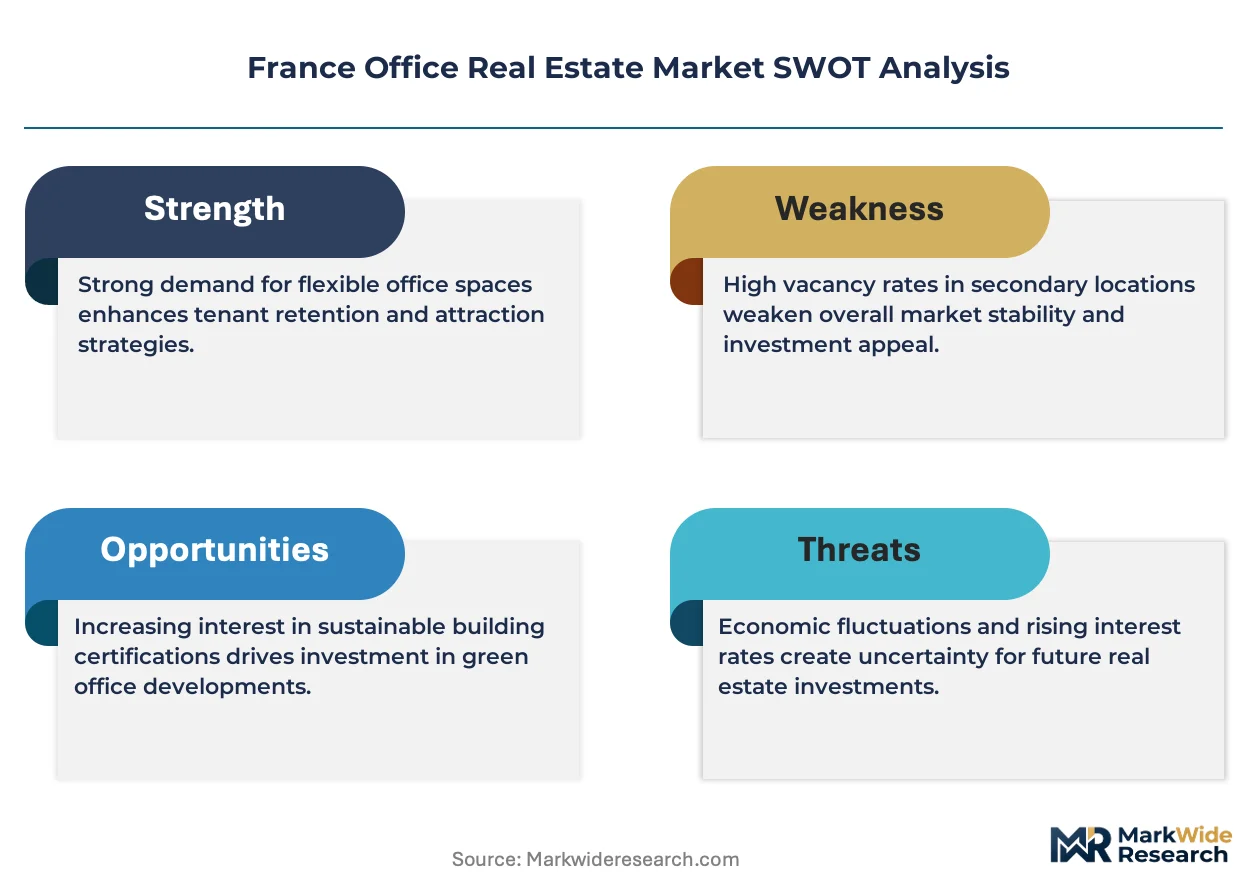
France's RE2020 building code, enforced by the Ministry of Ecological Transition, mandates progressive carbon performance thresholds for new construction and major renovations. The CSRD disclosure framework, administered by the AMF, requires listed landlords to report embodied carbon and energy consumption metrics, redirecting capital toward certified sustainable assets. Stakeholders must monitor regulatory tightening on operational carbon limits and assess whether retrofit timelines align with lease rollover schedules.
Market Dynamics
France's RE2020 building code is compressing retrofit timelines against lease rollover schedules, forcing landlords to front-load capital expenditure before regulatory deadlines harden. This structural pressure is redistributing competitive advantage toward institutional owners with balance-sheet capacity to absorb synchronized compliance costs.
Growth Catalysts
- RE2020 Thermal Performance Mandates:The Ministry of Ecological Transition's escalating carbon thresholds for major renovations are accelerating capital deployment into energy-efficient building systems across Île-de-France.
- Technology Tenant Expansion:Consulting and digital services firms are consolidating footprints in Paris's central business district and La Défense corridor, driving absorption of Grade A floor plates.
- Hybrid Work Normalization:Corporations are rightsizing traditional leases while expanding shared workspace commitments, reshaping demand toward flexible occupancy structures.
Market Restraints
- Construction Input Cost Volatility:Steel and HVAC equipment price instability is compressing development margins on new Grade A supply in Lyon and Marseille secondary markets.
- Mid-Tier Developer Capital Constraints:Smaller landlords face asymmetric compliance burdens against institutional competitors, creating portfolio concentration risk in aging suburban stock.
- Interest Rate Sensitivity:Debt-dependent acquisition strategies face refinancing pressure as European Central Bank policy transmits into French commercial real estate lending spreads.
Strategic Opportunities
- Underpenetrated Lyon Secondary Market:Technology sector migration from saturated Paris corridors creates absorption potential for speculative Grade A development in Part-Dieu and Confluence districts.
- CSRD Disclosure Framework:The AMF's mandatory embodied carbon reporting requirements are redirecting institutional capital toward pre-certified sustainable assets with verified energy performance data.
- Mixed-Use Zoning Convergence:Municipal planning reforms enabling office-residential-hospitality combinations unlock yield compression through diversified income streams in peripheral Île-de-France nodes.
Industry Challenges
- Retrofit Execution Timeline Compression:Landlords must synchronize RE2020 compliance work with lease expirations, creating vacancy risk and tenant relocation cost negotiations.
- Building Systems Integration Complexity:Legacy HVAC infrastructure requires phased replacement to avoid operational disruption, extending project durations and contractor coordination overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Office Real Estate Market |
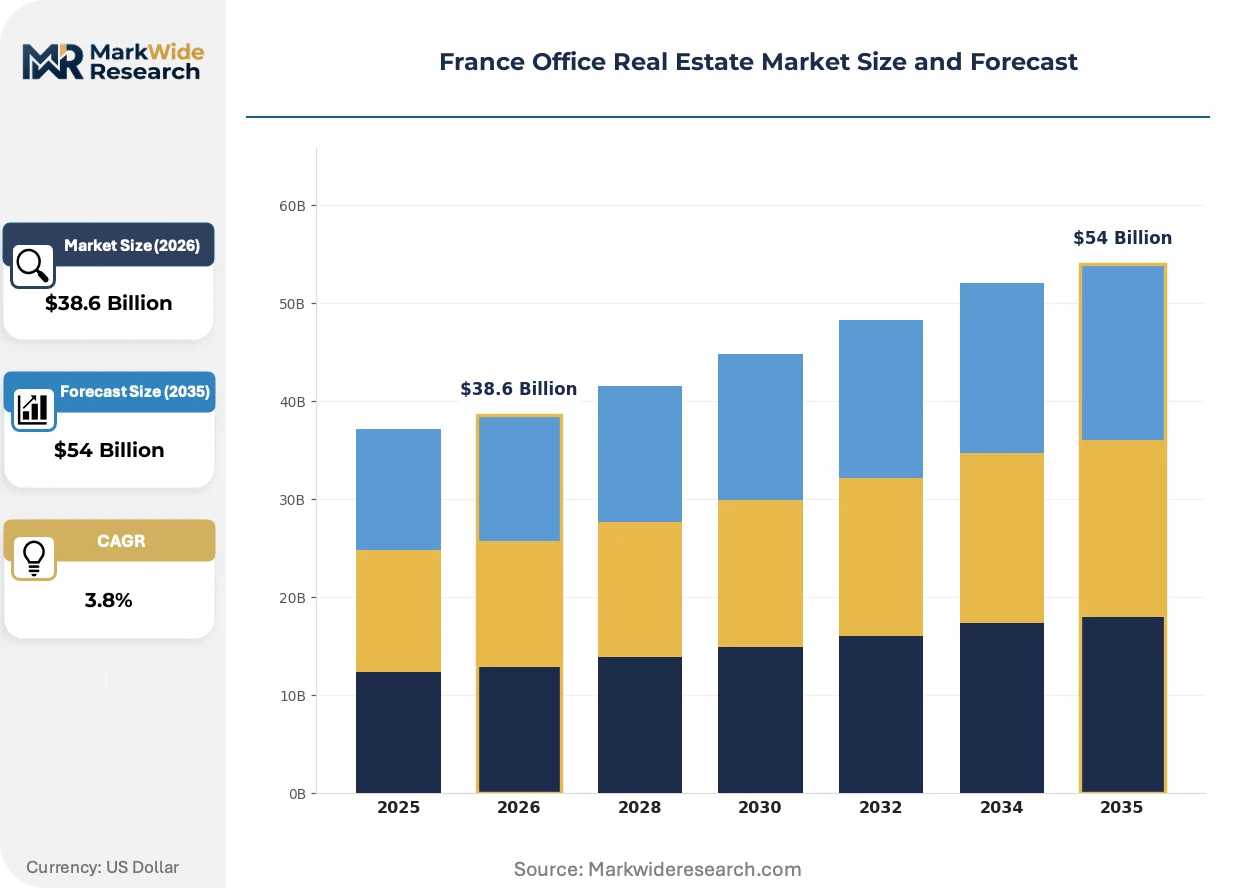
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: High-Rise Towers, Business Parks, Shared Workspaces, Boutique Offices Lease Duration: Short-Term, Medium-Term, Long-Term, Flexible Agreements Tenant Type: Startups, Consulting Firms, Financial Services, Creative Agencies Building Classification: Grade A, Grade B, Heritage Buildings, Renovated Spaces |
| Companies Covered | CBRE, BNP Paribas Real Estate, Cushman & Wakefield, JLL, Knight Frank, Gecina, Covivio, Unibail-Rodamco-Westfield, Icade, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Office Real Estate Market Shifts & Advancements
Digital infrastructure densification and environmental performance verification are converging to redefine asset competitiveness. Landlords now compete on measurable carbon credentials and technology-ready building systems rather than location alone.
Smart building management platforms integrating real-time energy monitoring with predictive maintenance algorithms are displacing conventional facility management contracts. Institutional owners in La Défense and central Paris are deploying these systems across portfolios to capture operational efficiency premiums. The technology is compressing property management cost structures while generating tenant-facing sustainability data required by CSRD disclosures.
France's RE2020 regulatory framework, enforced through the Ministry of Ecological Transition, is mandating progressive operational carbon limits for buildings exceeding specific renovation thresholds. The regulation is redirecting development capital toward deep retrofit projects that achieve BBCA or E+C- certification levels. Assets in Paris's central business district face the most acute compliance pressure given concentration of institutional ownership and public disclosure requirements.
Tenant procurement of office space is fragmenting toward shorter-dated, flexible contracts with embedded expansion options. Corporate real estate teams are unbundling traditional ten-year leases into core-and-flex strategies combining owned headquarters with serviced workspace memberships. This behavioral shift is most visible among technology and consulting verticals operating across Paris, Lyon, and emerging Bordeaux clusters.
France Office Real Estate Market Segmentation
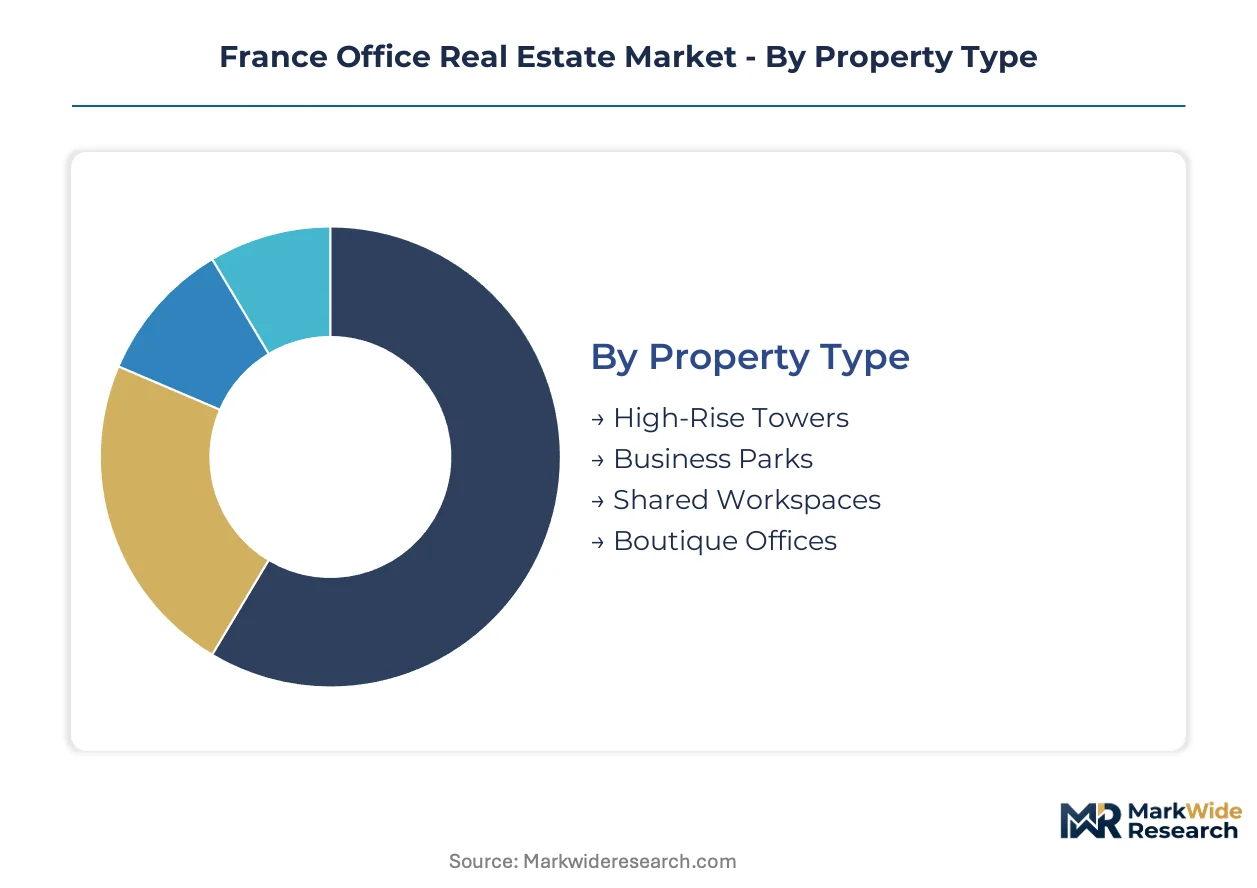
France office real estate segmentation reveals how tenant procurement channels fragment across property types and lease structures. Channel-mix dynamics determine which segments capture institutional capital versus corporate direct leasing.
Property Type:
High-Rise Towers flow through institutional investment channels and sovereign wealth fund allocations, while Shared Workspaces distribute via platform aggregators and flexible space operators.
- High-Rise Towers:These assets feature floor plates exceeding 2,000 square meters with centralized HVAC and redundant digital infrastructure. Demand concentrates in La Défense and central Paris, where technology and consulting tenants queue for Class A space with RE2020-ready energy systems.
- Shared Workspaces:Modular fit-outs with hot-desking density above 10 workstations per 100 square meters characterize this segment. Paris and Lyon absorption is climbing fastest as hybrid work patterns normalize corporate real estate strategies.
- Business Parks:Peripheral Île-de-France locations with surface parking ratios and standardized building envelopes serve back-office functions for financial services tenants.
- Boutique Offices:Smaller floor plates in converted residential or light industrial buildings attract creative agencies seeking distinctive address credentials in Marseille and Bordeaux.
By volume, High-Rise Towers lead. By growth pace, Shared Workspaces is ahead.
Lease Duration:
Cost-tier stratification separates capital-intensive long-term commitments from operational expenditure models favored by venture-backed tenants.
- Long-Term:Ten-to-fifteen-year leases with fixed escalations and renewal options dominate Grade A tower transactions. Institutional landlords in Paris CBD prefer these structures for income visibility matching liability durations.
- Flexible Agreements:Month-to-month or annual memberships with embedded expansion clauses characterize this segment. Technology sector procurement in Lyon and emerging Bordeaux clusters is expanding most quickly through this channel.
- Medium-Term:Three-to-five-year contracts with break options balance commitment flexibility for established consulting firms scaling headcount.
- Short-Term:Project-based occupancy under twelve months serves film production, event management, and seasonal professional services in Cannes and Nice.
Long-Term leases generate the highest revenue per square meter. Flexible Agreements are gaining share fastest among new tenant acquisitions.
Tenant Type:
Application-specific requirements drive divergent spatial configurations across professional service verticals.
- Consulting Firms:These tenants demand high-density benching layouts with client-facing meeting suites and 24/7 access credentials. Paris CBD and La Défense absorption concentrates here as strategy and technology advisory practices expand.
- Financial Services:Trading floors, compliance-grade security zones, and disaster recovery redundancy define specifications. Established banking tenants anchor long-term lease rolls in central Paris towers.
- Creative Agencies:Open studio configurations with natural light penetration and exposed structural elements predominate. Marseille and Lyon conversions of industrial heritage stock serve this demand.
- Startups:Growth-contingent expansion rights and minimal capital expenditure requirements shape procurement. Incubator-linked spaces in Station F and Part-Dieu cluster this activity.
Consulting Firms command the highest effective rents per workstation. Startups are expanding their aggregate footprint most rapidly.
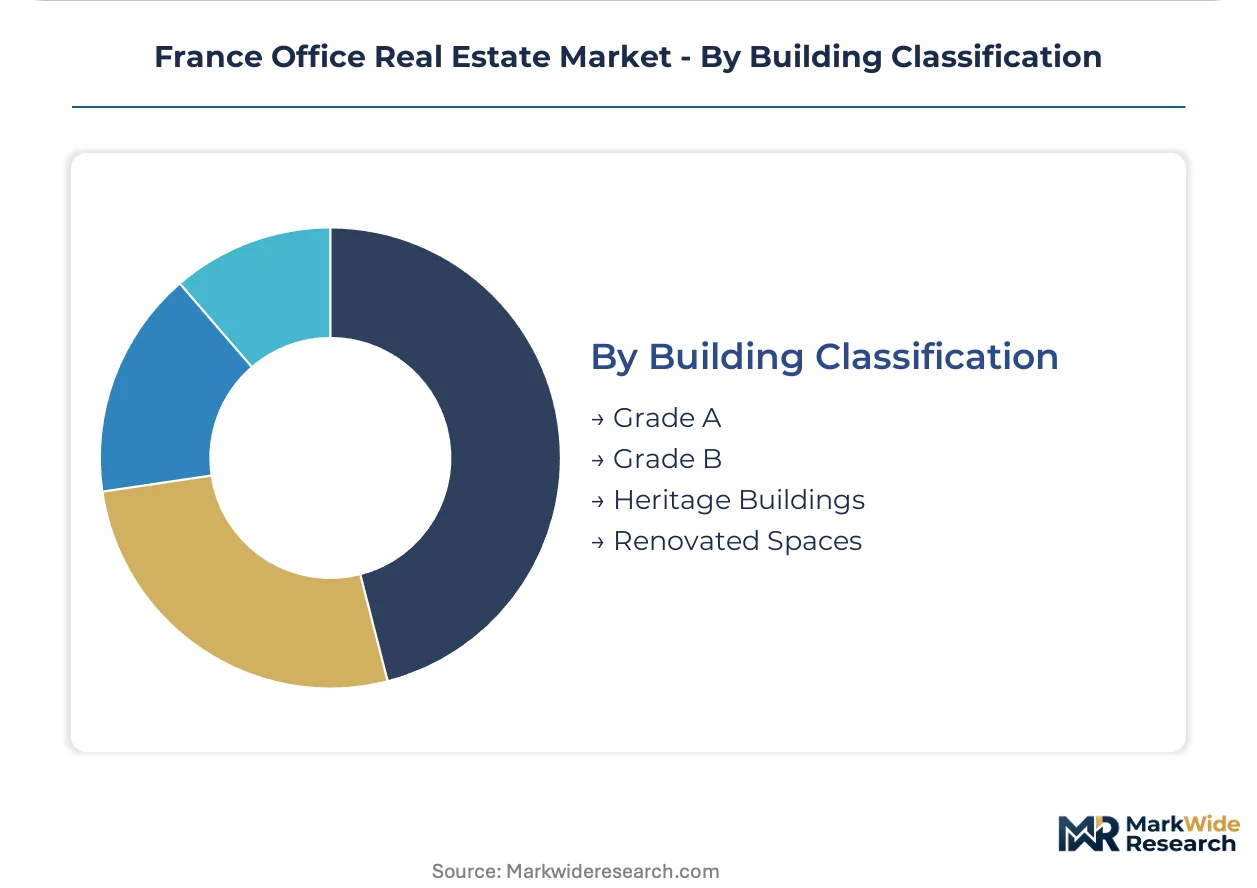
Building Classification:
Margin structure separates premium-certified assets from value-positioned alternatives in capital deployment decisions.
- Grade A:RE2020-compliant envelopes with smart building management systems and BREEAM or HQE certification attract institutional capital. Île-de-France concentration of these assets intensifies as retrofit timelines compress.
- Renovated Spaces:Deep retrofit projects achieving BBCA or E+C- labels reposition aging stock. Lyon and Marseille secondary markets see speculative development targeting this classification.
- Grade B:Functional but non-certified buildings with legacy mechanical systems serve price-sensitive tenants in peripheral locations facing regulatory obsolescence risk.
- Heritage Buildings:Monument historique protections constrain modification scope while offering distinctive address value for law firms and private equity advisors in central Paris.
Grade A assets capture disproportionate capital flow. Renovated Spaces are climbing the fastest as RE2020 deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France commands effective rents nearly double those in Lyon, while Marseille and Bordeaux trade at steeper discounts despite accelerating tenant interest. This pricing-power asymmetry reflects concentration of institutional capital and regulatory compliance capacity in the Paris basin.
Île-de-France
Technology and consulting tenants dominate absorption in Paris CBD and La Défense, with RE2020 retrofit mandates compressing timelines for Grade A stock. The Ministry of Ecological Transition enforces escalating carbon thresholds that favor landlords with balance-sheet capacity for synchronized compliance spending. La Défense corridor sees deepest tenant queues for High-Rise Towers with smart building management systems.
Auvergne-Rhône-Alpes
Technology sector migration from saturated Paris corridors drives speculative Grade A development in Lyon's Part-Dieu and Confluence districts. Regional planning authorities align zoning reforms with national RE2020 standards to attract institutional development capital. Lyon secondary market captures consulting firm expansion seeking cost arbitrage against Paris rents.
Provence-Alpes-Côte d'Azur
Film production and seasonal professional services sustain Short-Term lease demand in Cannes and Nice, while back-office functions cluster in Marseille's converted industrial heritage stock. Municipal authorities in Marseille prioritize creative agency attraction through adaptive reuse incentives for Boutique Office conversions. Aix-en-Provence corridor sees emerging interest from hybrid-work satellite offices.
Nouvelle-Aquitaine
Bordeaux clusters attract startup procurement through incubator-linked spaces, with Station F-style programming expanding from Paris. Regional development agencies coordinate with Bpifrance to channel capital toward mixed-use schemes blending office and residential functions. The metropolitan area captures technology tenant interest seeking quality-of-life arbitrage against Paris congestion.
Hauts-de-France
Peripheral Business Parks serve price-sensitive back-office functions for financial services tenants, though regulatory obsolescence risk concentrates in aging suburban stock. Regional planning reforms enable office-residential-hospitality combinations to unlock yield compression through diversified income streams. Lille metropolitan area anchors cross-border demand from Belgian corporate tenants.
France Office Real Estate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the France office real estate market. Institutional landlords with Paris-centric Grade A portfolios sustain premium lease rates through RE2020 compliance capacity, while mid-tier developers face asymmetric capital constraints. Three archetypes dominate: integrated asset managers with development capabilities, pure-play landlords with concentrated urban portfolios, and mixed-use specialists blending office with residential and hospitality functions. Competitive moves center on portfolio retrofit synchronization with lease rollover schedules and acquisition of pre-certified sustainable assets.
Among integrated service providers, CBRE, JLL, and BNP Paribas Real Estate occupy positions spanning brokerage, asset management, and development advisory. These firms exemplify the convergence of transaction execution with long-term portfolio management mandates that institutional investors increasingly demand. Their archetype represents the shift toward bundled service models that capture value across the investment lifecycle rather than discrete transaction fees.
| Leading Market Players |
|---|
| CBRE |
| BNP Paribas Real Estate |
| Cushman & Wakefield |
| JLL |
| Knight Frank |
| Gecina |
| Covivio |
| Unibail-Rodamco-Westfield |
| Icade |
| Others |
Supply & Pricing Matrix
Long-term lease structures with fixed escalation clauses lock in revenue visibility for institutional landlords while capping tenant exposure to cyclical rent spikes. This contract architecture concentrates pricing power with Grade A asset owners in Île-de-France who control scarce RE2020-compliant inventory.
Pricing Analysis
The customization-premium spread between fitted tenant improvements and shell-and-core delivery widens effective rent differentials across Paris CBD towers. Grade A assets with smart building systems and BREEAM certification command substantial premiums over renovated spaces with legacy mechanical infrastructure. Pricing pressure stems from mid-tier landlords discounting suburban stock to retain tenants facing RE2020 compliance deadlines. Financial services tenants exhibit lowest price sensitivity given security and redundancy requirements, while back-office functions in peripheral Business Parks negotiate aggressively on rate.
Supply Chain Analysis
France and Germany anchor HVAC equipment and building automation system manufacturing for commercial retrofit projects. Steel fabrication draws from Belgian and Luxembourg mills, while glazing and facade systems rest on Italian and Spanish suppliers. Single-source vulnerability concentrates in smart building management platforms dominated by narrow vendor pools. Distribution runs through specialized MEP contractors coordinated by general developers on major renovation schemes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as RE2020 retrofit mandates force synchronized capital deployment into energy-efficient building systems before regulatory deadlines harden.
For Market Incumbents: Fortify balance-sheet capacity to absorb front-loaded compliance spending ahead of lease rollovers. Accelerate acquisition of pre-certified sustainable assets to capture institutional capital flows redirected by CSRD disclosure requirements. Deepen contractor relationships with MEP specialists to secure scarce retrofit execution capacity. For New Entrants and Emerging Players: Lead with speculative Grade A development in Lyon's Part-Dieu and Confluence districts where technology tenant migration from Paris creates absorption gaps. Target consulting firm expansion seeking cost arbitrage against saturated central Paris corridors. Anchor go-to-market positioning through incubator-linked programming that mirrors Station F's tenant cultivation model. For Investors and Strategic Acquirers: Mixed-use specialists with office-residential-hospitality zoning permissions present asymmetric upside as municipal planning reforms unlock yield compression through diversified income streams. Long-term viability hinges on alignment between retrofit completion timelines and lease expiration schedules. Watch for inflection in ECB policy transmission into French commercial real estate lending spreads.| Strategic Initiative | Industry Significance |
|---|---|
| Deep Retrofit Execution | RE2020 compliance mandates synchronize capital deployment with lease rollover schedules across Île-de-France portfolios. |
| Smart Building Platform Integration | Predictive maintenance algorithms displace conventional facility management contracts in La Défense towers. |
| Mixed-Use Zoning Capture | Peripheral Île-de-France nodes unlock yield compression through office-residential-hospitality combinations. |
| Pre-Certified Asset Acquisition | CSRD disclosure requirements redirect institutional capital toward verified energy performance data. |
| Flexible Workspace Expansion | Hybrid work normalization reshapes corporate procurement toward core-and-flex occupancy structures. |
Research Methodology
A spread of perspectives from asset managers, development directors, tenant procurement leads, and MEP contractors converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against AMF regulatory filings, Ministry of Ecological Transition compliance databases, and institutional investor portfolio disclosures. Bottom-up lease roll analysis and top-down capital flow tracking triangulated market sizing across the projection horizon.
Segmentation dimensions modeled include property type, lease duration structure, tenant vertical, and building classification tier. CAGRs derive from trend extrapolation of absorption rates, rent growth patterns, and capital deployment velocity calibrated to regulatory milestone schedules. Forecast inputs incorporate RE2020 compliance timeline phasing and ECB policy transmission effects on commercial mortgage spreads.
The analysis sits within stated boundaries; outcomes outside sustained technology tenant expansion or accelerated regulatory tightening would require recalibration. Forecasts reflect assumptions about hybrid work permanence and institutional capital allocation preferences. Recalibration cycles align with material shifts in ECB monetary policy and RE2020 enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
United Kingdom Flexible Office Space Market
Office Real Estate
United Kingdom Co-Working Office Spaces Market
Office Real Estate
Australia Flexible Office Space Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
China Flexible Office Space Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
Global Office Space Market
Office Real Estate
Latin America Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Brokerage Market
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
United States Office Real Estate Market
Office Real Estate
North America Office Real Estate Market
Office Real Estate
Flexible Office Market
Office Real Estate
Asia Pacific Flexible Office Market