
 North America Office Real Estate Market | 2026-2036
North America Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Office Real Estate Market Analytics
The capital-intensity divergence between trophy-asset developers and value-add renovators is redrawing competitive boundaries in North American office development. Brookfield Properties leverages its global capital platform to anchor mega-projects in gateway cities. SL Green Realty Corp. specializes in Manhattan's concentrated trophy inventory, sustaining premium positioning through selective development. Colliers International Group Inc. competes across service layers, extending advisory reach into secondary markets where institutional capital seeks yield.
North America office real estate comprises income-producing commercial buildings designed for professional services, typically constructed with steel or reinforced concrete frames, curtain wall envelopes, and floor plates spanning fifteen thousand to forty thousand square feet to accommodate open-plan and cellular layouts. The primary commercial purpose centers on generating rental yield through long-dated lease contracts to corporate tenants. Class A properties command the deepest institutional capital pools, while co-working spaces represent the fastest-evolving segment as operators navigate enterprise contract structures. Green certification and smart building features increasingly determine financing access, with LEED-rated assets attracting preferential lending terms from major banks.
The US Environmental Protection Agency and Department of Energy shape building performance standards through ENERGY STAR certification requirements, while Canadian provincial regulators enforce escalating carbon intensity limits on commercial structures. The Inflation Reduction Act's clean energy tax credits directly alter developer pro formas, tilting new construction toward electrified systems and away from fossil fuel heating. Stakeholders must monitor how municipal zoning reforms in Dallas, Austin, and Vancouver reshape permissible density and parking ratios before committing development capital.
Market Dynamics
The Inflation Reduction Act's clean energy tax credits are compressing developer underwriting timelines while forcing capital reallocation toward electrified building systems and away from conventional fossil fuel infrastructure across North American office construction.
Growth Catalysts
- IRA Clean Energy Provisions:Federal tax credits for electrified HVAC and solar integration reduce effective construction costs for Class A developments in Dallas and Austin corridors.
- Enterprise Hybrid Stabilization:Technology and financial services firms are signing longer-dated leases as floorplate requirements settle into predictable patterns.
- Green Financing Preference:Major commercial banks now extend preferential lending terms to LEED-certified assets, accelerating certification uptake among institutional developers.
Market Restraints
- Steel and Concrete Input Volatility:Reinforced concrete frame costs fluctuate with regional aggregate supply constraints, compressing margins on mid-rise developments.
- Suburban Obsolescence Risk:Secondary metro office stock in legacy business parks faces accelerated functional depreciation as tenant preferences concentrate in transit-adjacent submarkets.
- Zoning Density Caps:Municipal parking ratio minimums in Texas and Ontario jurisdictions limit achievable density on constrained urban parcels.
Strategic Opportunities
- Vancouver Carbon Compliance:British Columbia's escalating carbon intensity limits create first-mover advantage for developers with electrified system expertise.
- Smart Building Convergence:Integration of IoT sensor networks with predictive maintenance platforms opens premium rent positioning in Toronto's financial district.
- Secondary Market Yield Migration:Institutional capital is deploying into Nashville and Raleigh-Durham office submarkets as gateway city cap rates compress.
Industry Challenges
- Electrified Systems Integration:Mechanical contractor capacity for heat pump and thermal storage installation lags project pipeline demands in Texas metros.
- Utility Interconnection Queues:Grid upgrade timelines for high-load electrified buildings extend certificate of occupancy schedules by 8-14 months in high-growth corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Office Real Estate Market |
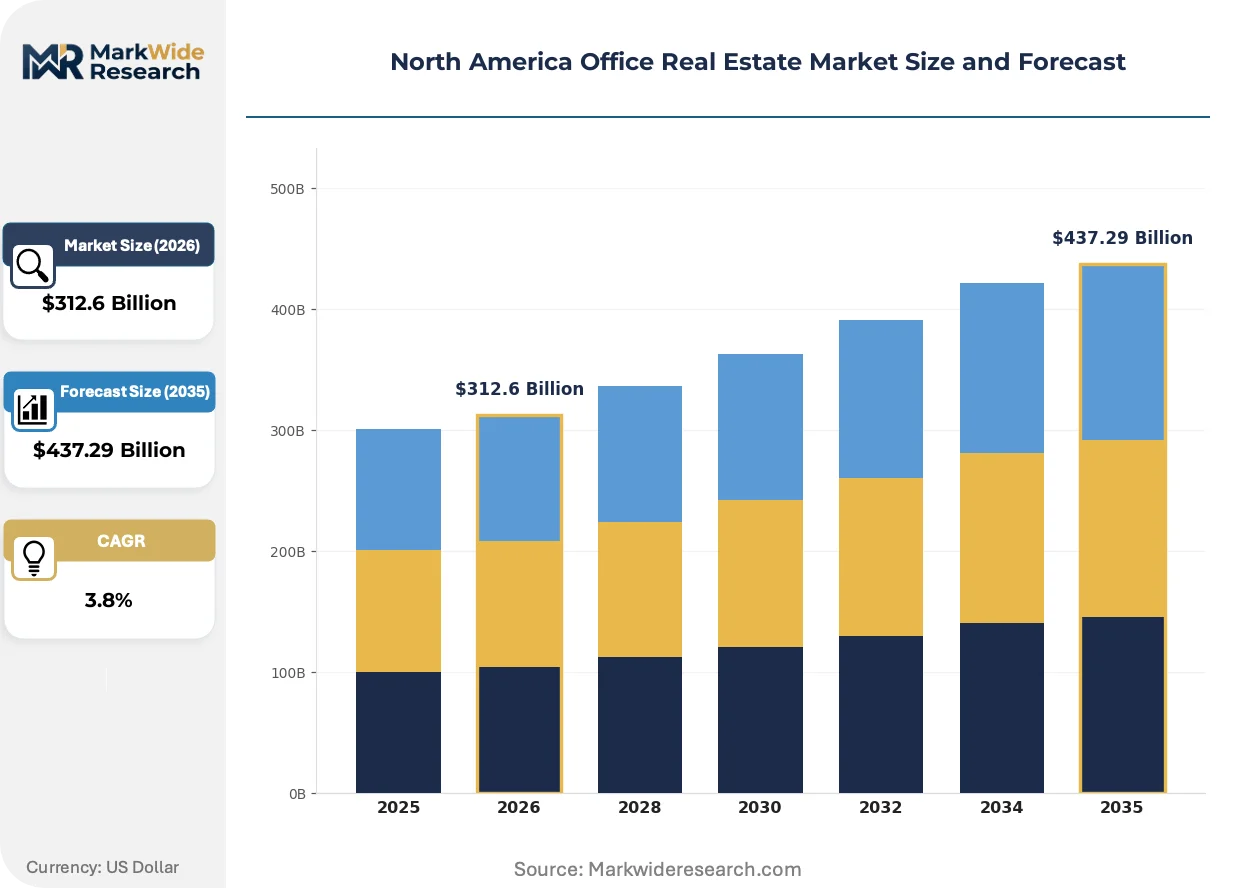
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $437.29 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Class A, Class B, Class C, Co-working Spaces, Business Parks Lease Structure: Gross Lease, Net Lease, Modified Gross Lease, Percentage Lease, Full-Service Lease End User: Tech Startups, Financial Firms, Legal Practices, Consulting Agencies, Educational Institutions Building Features: Green Certification, Smart Building, LEED, Energy Efficient, High-Speed Internet |
| Companies Covered | CBRE Group Inc., JLL, Cushman & Wakefield, Colliers International Group Inc., BXP, Inc., SL Green Realty Corp., Brookfield Properties, Vornado Realty Trust, Newmark Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Office Real Estate Market Evolving Landscape
Building automation and energy management systems are converging with tenant experience platforms, compressing the traditional separation between operational technology and workplace amenities.
Digital twin platforms for predictive facilities management are miniaturizing deployment costs through cloud-native architectures. Mid-size property managers in Chicago and Denver are adopting these tools at accelerating pace. The technology is miniaturizing the capital barrier between institutional-grade smart building capabilities and value-add renovation projects.
The Inflation Reduction Act's 179D deduction expansion is reshaping developer energy modeling requirements. Commercial building owners must now document hourly energy performance to capture full incentive value. Class B repositioning projects in Houston and Phoenix are most affected, with engineering consultants retooling service offerings to meet granular compliance demands.
Enterprise tenants are unbundling traditional landlord service packages and procuring workplace experience amenities through specialized third-party vendors. Property managers in Manhattan and Toronto are losing direct control over fitness, conferencing, and food service offerings. This disintermediation is most visible in technology sector leases, where tenant improvement allowances increasingly flow to vendor ecosystems rather than base building upgrades.
North America Office Real Estate Market Segmentation
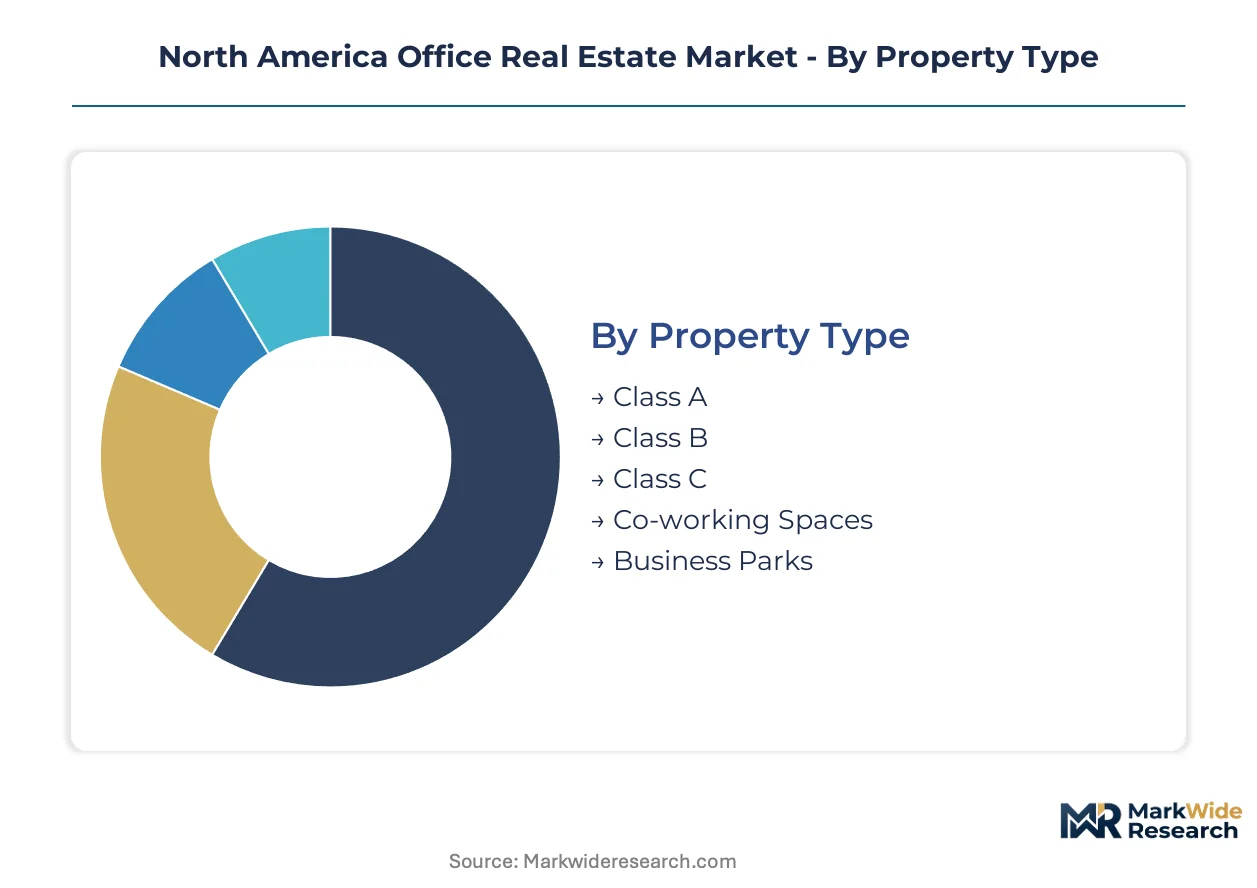
Segmentation in North American office real estate reveals how capital allocation, tenant preferences, and regulatory compliance intersect across distinct property tiers and lease structures. Understanding these divisions exposes where institutional investors concentrate exposure versus where value-add operators pursue repositioning opportunities.
Property Type:
Premium rent multiples cluster in trophy assets with transit connectivity and modern amenity stacks, while yield-focused capital targets stabilized secondary properties.
- Class A:Steel or reinforced concrete frame structures with curtain wall envelopes, floor plates of fifteen thousand to forty thousand square feet, and institutional ownership profiles. Demand concentrates in Toronto's financial district and Texas metro corridors where tech and financial services tenants compete for limited trophy inventory.
- Co-working Spaces:Flexible lease term operators providing furnished suites and shared amenities through enterprise contract structures. Growth accelerates in Dallas and Austin as hybrid work models stabilize and corporations seek satellite locations without long-dated lease commitments.
- Class B:Mid-tier assets with functional obsolescence in HVAC or facade systems, often candidates for capital-light renovation to capture rent spreads.
- Class C:Older stock in secondary submarkets, typically trading at discount to replacement cost and attracting local owner-operators.
- Business Parks:Suburban multi-tenant campuses with surface parking dominance, facing accelerated functional depreciation as tenant preferences shift toward transit-adjacent locations.
The dominant share belongs to Class A, while Co-working Spaces is closing the gap fastest.
Lease Structure:
Tenant credit quality and operating expense exposure determine which contract forms institutional landlords will accept.
- Net Lease:Tenant assumes property tax, insurance, and maintenance obligations, creating bond-like cash flow profiles favored by REIT investors. Prevalence rises in Texas business parks where credit tenants seek operational control.
- Full-Service Lease:Landlord bundles base rent with operating expenses, common in Class A towers where professional management adds value through economies of scale. Dominant structure in Manhattan and Toronto financial district towers.
- Gross Lease:Landlord absorbs all operating costs, typical in short-term arrangements or markets with predictable expense loads.
- Modified Gross Lease:Hybrid structure splitting expense responsibilities, common in mid-rise developments with metered utility exposure.
- Percentage Lease:Rent tied to tenant sales volume, rare in pure office but emerging in mixed-use ground-floor retail components.
Net Lease commands the deepest institutional capital pools, while Modified Gross Lease is gaining traction fastest among mid-market assets.
End User:
Tenant industry concentration shapes submarket rent trajectories and building feature requirements.
- Tech Startups:Rapidly scaling firms prioritizing flexible footprints, open-plan layouts, and proximity to talent pools. Physical footprint expansion concentrates in Austin and Dallas corridors as hybrid models stabilize.
- Financial Firms:Banks, asset managers, and insurers requiring secure infrastructure, trading floor specifications, and prestige addresses. Lease demand clusters in Toronto's financial district and Manhattan's concentrated trophy inventory.
- Legal Practices:Partnership structures favoring cellular office layouts and client-facing amenity requirements.
- Consulting Agencies:Project-based staffing models driving demand for hot-desking ratios and airport-accessible submarkets.
- Educational Institutions:Universities and training operators seeking satellite campuses, often in secondary markets with parking abundance.
Financial Firms retain the largest leased footprint, while Tech Startups is expanding most quickly.
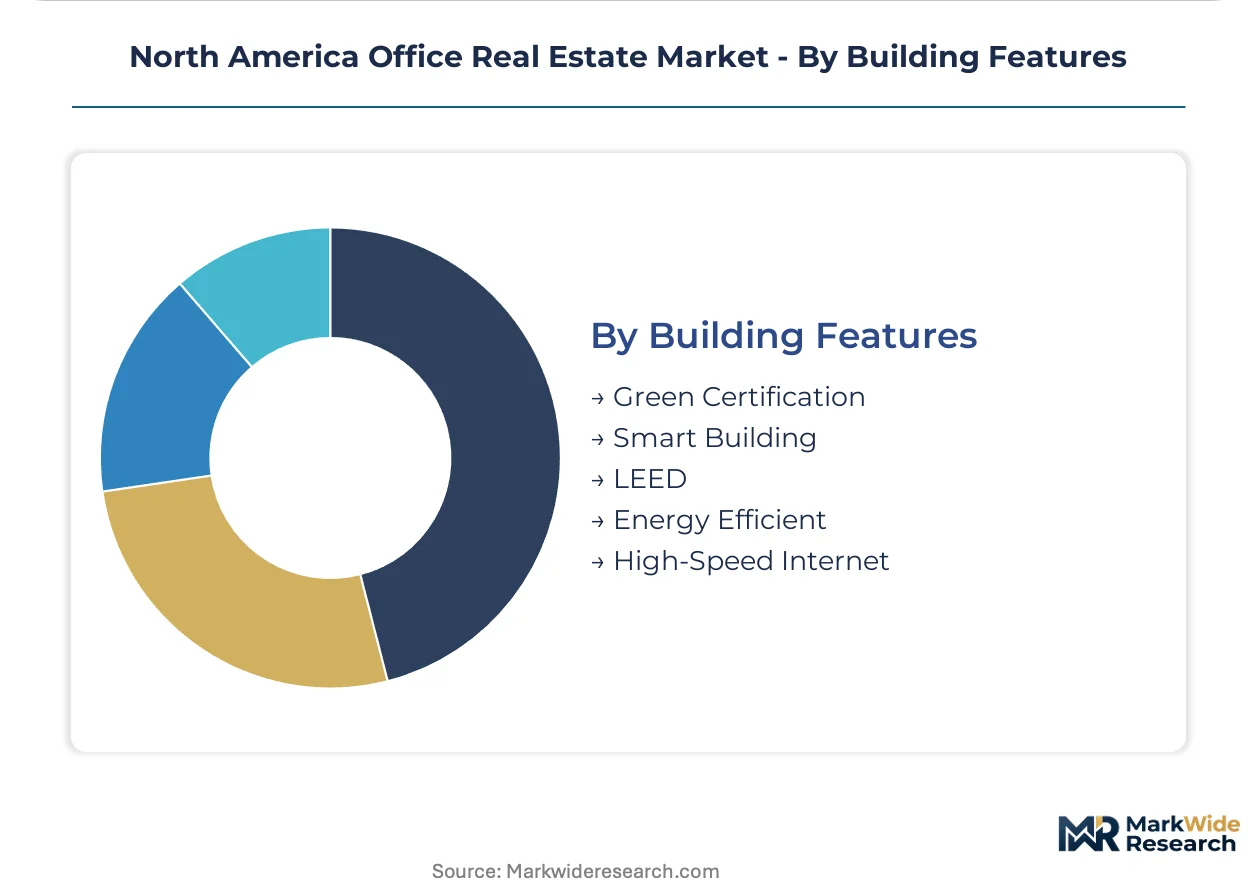
Building Features:
Financing access and tenant attraction increasingly depend on verified performance credentials rather than aesthetic claims.
- LEED:Third-party green building certification with escalating requirements for energy performance documentation. The Inflation Reduction Act's 179D deduction expansion forces hourly energy modeling for full incentive capture, particularly affecting Class B repositioning projects in Houston and Phoenix.
- Smart Building:IoT sensor networks integrated with predictive maintenance platforms and tenant experience applications. Adoption accelerates in Toronto's financial district where premium rent positioning rewards operational transparency.
- Green Certification:Broad category including ENERGY STAR, BREEAM, and regional programs, with major commercial banks extending preferential lending terms to verified assets.
- Energy Efficient:Performance-based descriptors without third-party verification, common in value-add marketing materials.
- High-Speed Internet:Fiber connectivity and redundant telecommunications infrastructure, now table stakes for Class A competitiveness.
LEED holds the widest financing preference, while Smart Building is climbing the fastest as IoT deployment costs miniaturize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across North American office submarkets. Trophy assets in transit-connected districts command premium rents with minimal price sensitivity, while secondary suburban stock faces steep discounting pressure as tenant preferences concentrate in amenity-rich urban cores.
United States
Tech and financial services tenants drive absorption in Dallas and Austin corridors as hybrid work models stabilize floorplate requirements. The Inflation Reduction Act's 179D deduction expansion accelerates electrified HVAC retrofits in Houston and Phoenix Class B repositioning projects. Manhattan's concentrated trophy inventory sustains institutional capital deployment despite broader market uncertainty.
Canada
Financial firms and consulting agencies cluster in Toronto's financial district, competing for limited LEED-certified smart building stock. British Columbia's escalating carbon intensity limits under provincial regulation create compliance-driven renovation demand in Vancouver. Calgary's downtown office core faces elevated vacancy as energy sector tenants right-size footprints and migrate to flight-to-quality assets.
Mexico
Nearshoring manufacturing investment generates satellite office demand for professional services in Monterrey and Guadalajara. Federal energy efficiency standards for commercial buildings remain less stringent than US or Canadian equivalents, limiting green certification penetration. Mexico City's Polanco and Santa Fe districts attract multinational corporate regional headquarters seeking cost-advantaged Class A space.
North America Office Real Estate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in North American office real estate. Trophy-asset developers with global capital platforms anchor mega-projects in gateway cities, while value-add renovators pursue repositioning opportunities in secondary markets. Service-layer specialists compete across advisory, leasing, and property management functions. Dominant competitive moves include portfolio diversification into mixed-use developments and strategic partnerships with institutional capital seeking yield in stabilized assets.
Within the integrated developer tier, Brookfield Properties and SL Green Realty Corp. exemplify contrasting geographic concentration strategies. CBRE Group Inc., JLL, and Cushman & Wakefield occupy positions across the service-layer spectrum, representing the advisory and transaction archetype that extends competitive reach into secondary markets where institutional capital deployment accelerates.
| Leading Market Players |
|---|
| CBRE Group Inc. |
| JLL |
| Cushman & Wakefield |
| Colliers International Group Inc. |
| BXP, Inc. |
| SL Green Realty Corp. |
| Brookfield Properties |
| Vornado Realty Trust |
| Newmark Group Inc. |
| Others |
Value Network & Pricing Analysis
Eighteen-month utility interconnection queues in Texas metros compress developer underwriting timelines while amplifying pricing power for mechanical contractors with heat pump installation capacity. This lead-time bottleneck concentrates cost premiums in electrified Class A developments, tilting developer procurement toward pre-qualified installer networks and away from spot-market contracting.
Pricing Analysis
After-sales service revenue from predictive maintenance contracts and IoT platform subscriptions drives lifetime value capture in smart building deployments. Three-tier pricing structure across trophy assets with full amenity stacks, standard Class A with baseline certification, and value-add repositioning projects reflects financing access differentiation, with LEED-rated assets commanding preferential lending terms from major commercial banks. Cost compression in Class B renovation tiers is intensifying because engineering consultants must retool hourly energy modeling capabilities to capture Inflation Reduction Act 179D deductions. Enterprise tenants exhibit lowest price sensitivity for transit-connected trophy inventory, while local owner-operators in secondary markets face acute margin pressure.
Supply Chain Analysis
Steel mill capacity constraints in the US Midwest and Mexican border zones create chokepoints for reinforced concrete frame procurement in Dallas and Austin corridors. Structural steel, curtain wall glazing, and electrified HVAC components draw from concentrated North American manufacturing bases, with heat pump and thermal storage equipment sourcing from established US and Canadian supplier networks. Single-source vulnerability runs through mechanical contractor capacity for electrified system installation, where certified installer pools lag project pipeline demands. Distribution runs through integrated developer procurement platforms and specialized construction material distributors serving institutional capital deployment corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American office real estate is approaching a platform-economics inflection as building automation systems converge with tenant experience applications, with interoperability between IoT sensor networks and third-party amenity vendors reshaping competitive control points.
For Market Incumbents: Consolidate mechanical contractor relationships and electrified system installation capacity to secure project pipeline execution in Texas metros. Lock in pre-qualified installer networks before interconnection queue bottlenecks widen, and deepen backward integration into energy modeling consultancy capabilities to capture Inflation Reduction Act compliance premiums.
For New Entrants and Emerging Players: Anchor in Vancouver's carbon compliance-driven renovation market, where British Columbia's escalating carbon intensity limits create first-mover advantage for developers with electrified system expertise. Target mid-size property managers in Chicago and Denver for digital twin platform deployment, using cloud-native architectures to miniaturize capital barriers against institutional-grade competitors.
For Investors and Strategic Acquirers: Long-term, this sits as a yield-compression play because institutional capital migration into secondary markets accelerates as gateway city cap rates tighten. Focus acquisition screening on stabilized Class A assets with LEED certification and smart building infrastructure in Nashville and Raleigh-Durham corridors. Monitor utility interconnection queue lengths as the signal for development timeline risk and achievable return thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrified HVAC Retrofit Program | Captures Inflation Reduction Act 179D deductions in Houston and Phoenix Class B repositioning projects. |
| Smart Building Platform Integration | Compresses operational technology and tenant amenity convergence in Toronto's financial district towers. |
| Mechanical Contractor Capacity Lock | Secures heat pump installation bandwidth ahead of eighteen-month utility interconnection queues in Texas metros. |
| Carbon Compliance Specialization | Builds first-mover positioning under British Columbia's escalating commercial building intensity limits. |
| Secondary Market Yield Migration | Deploys institutional capital into Nashville and Raleigh-Durham as gateway city trophy asset pricing tightens. |
Research Methodology
Desk research of municipal zoning filings, ENERGY STAR certification databases, and Inflation Reduction Act guidance documents preceded structured interviews with trophy asset developers, mechanical contractors, property management executives, and institutional capital deployment officers. Primary fieldwork across Dallas, Austin, Toronto, and Vancouver corridors combined with secondary validation from EPA building performance standards, provincial carbon intensity regulations, and commercial bank green lending policy disclosures. Bottom-up project pipeline tracking and top-down capital flow analysis enabled triangulation across the analysis window.
Variance decomposition across lease structure types, building certification tiers, and regional regulatory frameworks shaped the analytical approach throughout the forecast period. Segmentation dimensions modeled include property class, end-user industry concentration, and electrified system penetration rates. CAGRs were derived from lease absorption velocity, development pipeline conversion ratios, and capital deployment trajectory patterns. Forecast inputs incorporated hybrid work floorplate stabilization assumptions and green financing preference shifts among major commercial banks.
Underlying assumptions cover tenant preference persistence for transit-adjacent locations, municipal zoning reform timelines in Texas and Ontario, and mechanical contractor capacity expansion rates, with deviation risk concentrated in utility interconnection queue extensions and steel input cost volatility. Practitioners should keep alternative scenarios live as Federal energy credit guidance and provincial carbon compliance thresholds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
India Office Real Estate Market
Office Real Estate
Qatar Co-Working Office Spaces Market
Office Real Estate
United States Office Real Estate Market
Office Real Estate
Saudi Arabia Co-Working Office Spaces Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
Japan Office Real Estate Market
Office Real Estate
Bahrain Flexible Office Space Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
United Kingdom Flexible Office Space Market
Office Real Estate
Europe Office Real Estate Market
Office Real Estate
Asia Pacific Flexible Office Market
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
China Flexible Office Space Market
Office Real Estate
Asia Pacific Office Real Estate Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
Global Office Space Market