
 Australia Facility Management Market | 2026-2036
Australia Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Facility Management Market Analysis
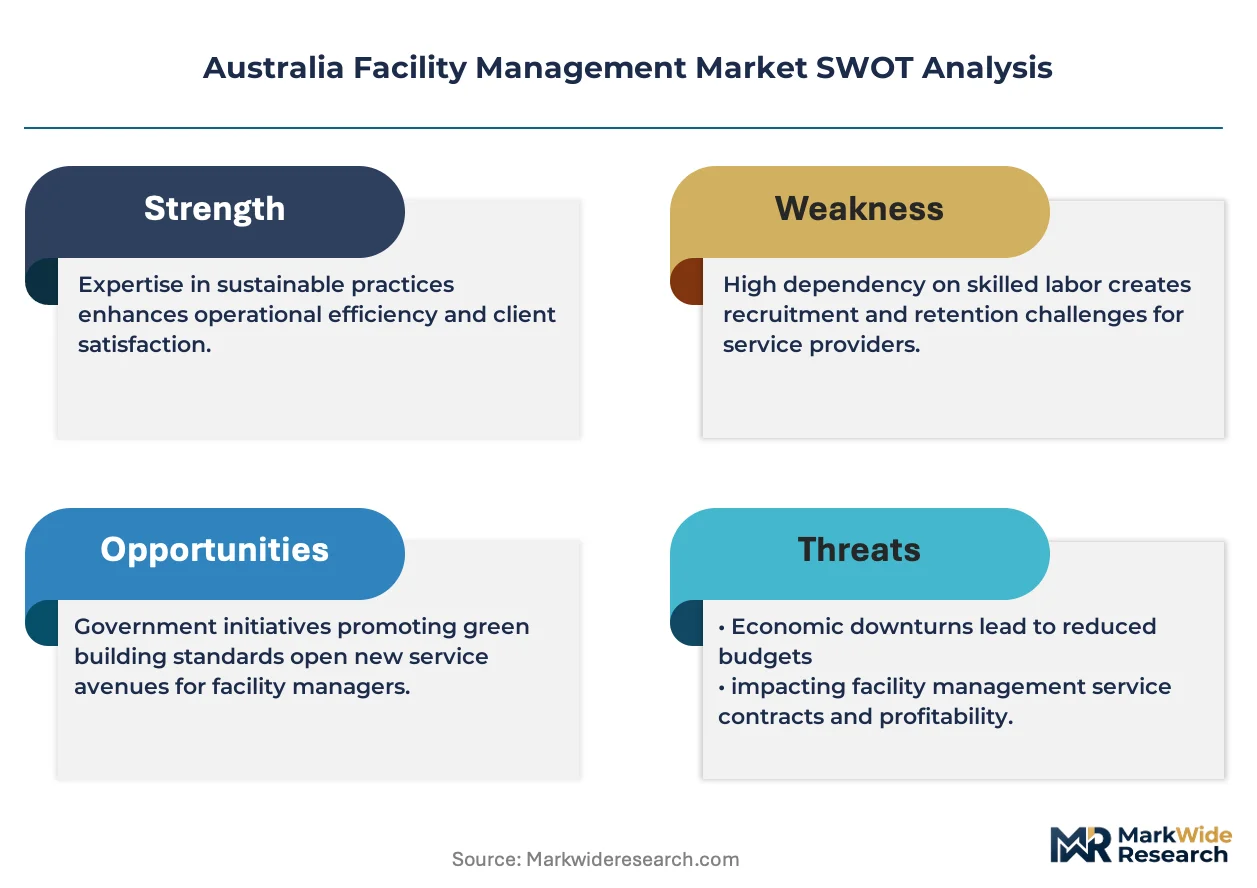
Sustainable materials are rebalancing facility economics as low-VOC coatings and recycled steel framing replace conventional construction inputs across commercial retrofits. CBRE Group leverages its integrated platform to capture bundled maintenance and energy contracts. ISS Australia anchors its position through specialized healthcare cleaning protocols. Sodexo Facilities Management Services differentiates via technology-enabled food and facilities convergence.
Facility management encompasses the coordinated delivery of hard services such as HVAC maintenance, electrical systems upkeep, and structural repairs alongside soft services including cleaning, security, and space planning to ensure operational continuity of built assets. The discipline relies on computerized maintenance management systems to schedule preventive tasks and track asset lifecycle performance across property portfolios. Cleaning and maintenance services dominate current revenue pools due to their non-discretionary nature and recurring contract structures. Smart building solutions and IoT devices represent the fastest-expanding technology segment as owners pursue real-time energy optimization and predictive equipment diagnostics. Healthcare facilities and educational institutions form the most resilient end-user verticals, driven by stringent hygiene mandates and extended operational hours.
TGA building material standards, the National Construction Code administered by the Australian Building Codes Board, and state-level Work Health and Safety regulations collectively shape service specifications and contractor accreditation requirements. Compliance with these frameworks determines market access for providers bidding on government and institutional contracts. Stakeholders must assess how impending energy performance disclosure mandates will reshape competitive positioning between integrated platforms and specialized operators.
Market Dynamics
Energy performance disclosure mandates from the Australian Building Codes Board are compressing service contract timelines and forcing asset owners toward integrated facility platforms that bundle compliance, maintenance, and retrofit coordination.
Growth Catalysts
- National Construction Code updates:Tighter building performance standards are mandating predictive HVAC maintenance and real-time energy monitoring across commercial portfolios in New South Wales and Victoria.
- Healthcare outsourcing expansion:Hospital networks are extending bundled service contracts to cover specialized cleaning, waste management, and clinical equipment maintenance under single-provider arrangements.
- IoT sensor deployment:Smart building solutions are enabling predictive equipment diagnostics that reduce unplanned downtime across educational and institutional facilities.
Market Restraints
- Skilled technician shortages:Licensed electricians and HVAC specialists are concentrated in Sydney and Melbourne, creating service delivery gaps in Queensland and Western Australia.
- Compliance cost escalation:Work Health and Safety accreditation requirements and TGA building material standards are extending contractor onboarding timelines by 40-60 days.
- Subcontractor dependence:Tier-one facility management platforms rely on fragmented regional cleaning and security subcontractors, creating quality consistency risks.
Strategic Opportunities
- Perth commercial retrofits:Western Australia's aging office stock presents white space for integrated energy-performance contracting as disclosure mandates expand beyond eastern states.
- Technology convergence:Computerized maintenance management systems are merging with food service logistics platforms in healthcare and education verticals.
- State-level green procurement policies:Victorian and New South Wales government purchasing frameworks are prioritizing low-VOC materials and recycled steel framing in public building contracts.
Industry Challenges
- CMMS integration complexity:Legacy asset registers in institutional portfolios resist data migration to cloud-based predictive maintenance platforms.
- Certification bottlenecks:Facility management professionals seeking Certified Facility Manager credentials face 18-24 month qualification timelines that outpace contract staffing needs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Facility Management Market |
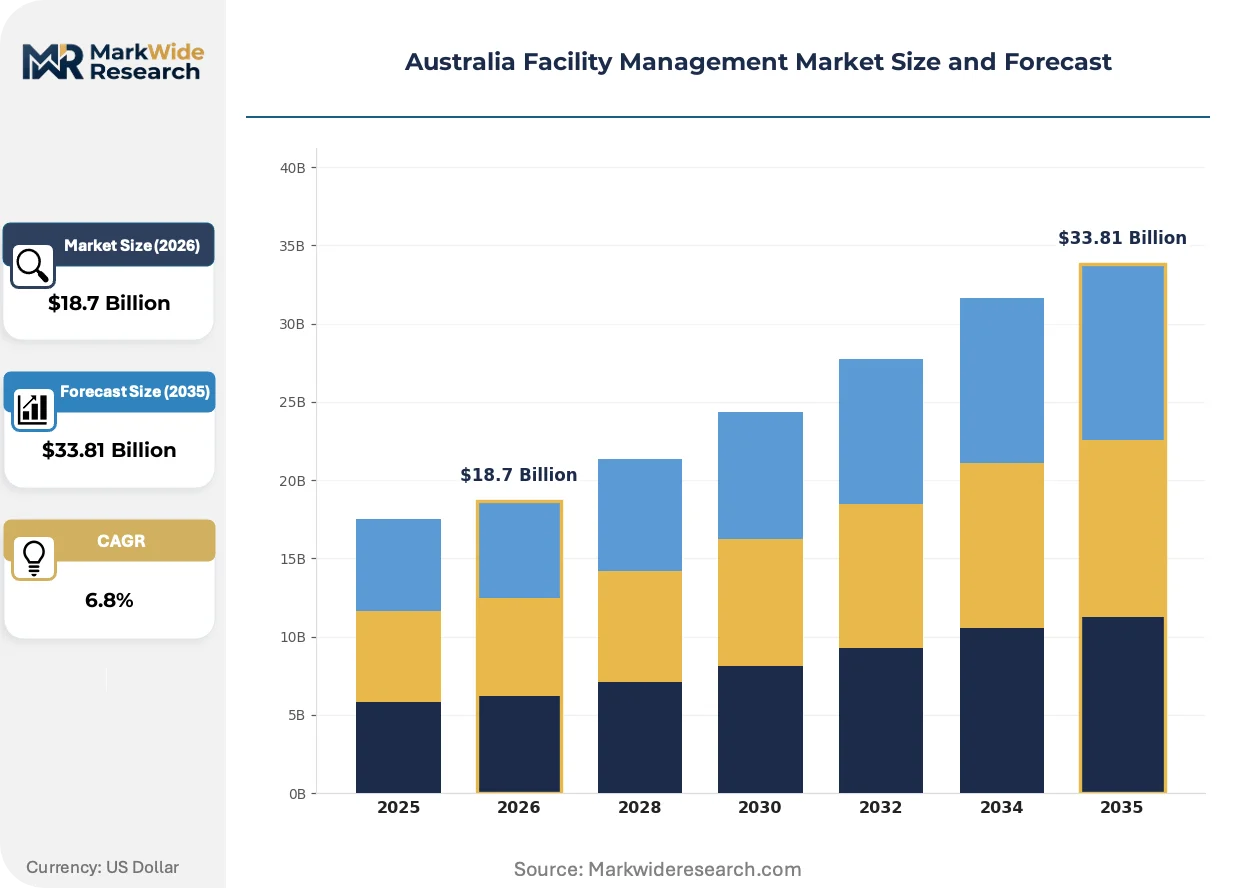
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Maintenance, Security, Space Management End User: Healthcare Facilities, Educational Institutions, Office Buildings, Retail Outlets Technology: Smart Building Solutions, IoT Devices, Energy Management Systems, CMMS Offering: Integrated Solutions, Consulting Services, Outsourced Management, Software Platforms |
| Companies Covered | CBRE Group, ISS Australia, Sodexo Facilities Management Services, Ventia Services Group, JLL Limited, Cushman and Wakefield, Serco Facilities Management, Vinci Facilities Limited, Compass Group Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Facility Management Market Emerging Trajectories
Predictive analytics and sensor networks are compressing the traditional reactive maintenance model. Three developments are restructuring how facility services are procured, delivered, and priced across Australian commercial and institutional assets.
Digital twin technology is consolidating asset lifecycle management by creating virtual replicas of building systems that simulate HVAC, electrical, and structural performance under varying load conditions. Major hospital networks and university campuses in Victoria are deploying these platforms to synchronize preventive maintenance schedules with actual equipment degradation curves. The technology is consolidating vendor relationships as owners demand single-platform accountability for both physical maintenance and digital asset modeling.
The Australian Building Codes Board's trajectory toward mandatory energy performance disclosure is tightening operational standards for commercial buildings over 1,000 square meters. Asset owners must now commission independent energy audits and publicly report NABERS ratings, creating compliance service demand that favors integrated facility platforms over specialized operators. Institutional investors with Sydney and Melbourne office holdings are responding by embedding energy performance clauses into property management agreements.
Consolidated service procurement is replacing fragmented single-service contracts as institutional buyers seek unified accountability. Healthcare networks and educational institutions are unbundling cleaning, security, and maintenance from separate vendors into single integrated agreements with outcome-based pricing. This pattern is most visible across New South Wales public hospital clusters and Victorian university precincts, where procurement teams are compressing vendor panels from 15-20 suppliers to 3-4 integrated platforms.
Australia Facility Management Market Segmentation
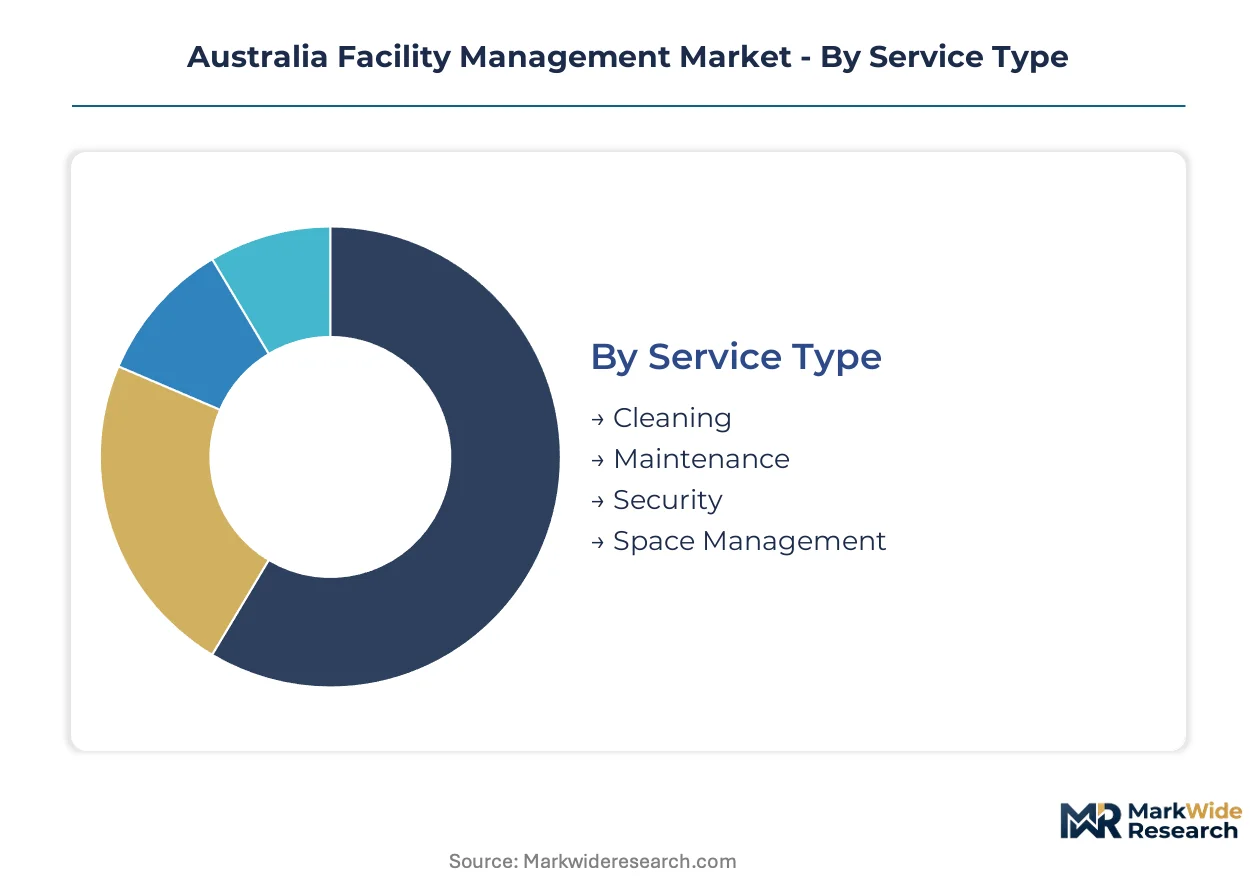
Facility management procurement patterns in Australia diver sharply between high-frequency, low-margin recurring services and capital-intensive technology deployments. Understanding these segment dynamics reveals where contract bundling creates pricing power versus where specialization defends margins.
Service Type:
Cleaning and maintenance command volume dominance through mandatory daily execution, while security and space management extract premium pricing through regulatory complexity and talent scarcity.
- Cleaning:Non-discretionary daily execution across healthcare and education verticals creates the largest revenue pool. Hospital networks in New South Wales and Victoria are consolidating cleaning contracts into bundled facility agreements with specialized hygiene protocols.
- Maintenance:Predictive HVAC and electrical upkeep is displacing reactive break-fix models as NABERS disclosure mandates tighten. Asset owners in Sydney and Melbourne commercial towers now embed energy-performance clauses directly into maintenance contracts.
- Security:Licensed personnel requirements and integrated access control systems defend margins in government and institutional settings.
- Space Management:Post-occupancy optimization and flexible workspace reconfiguration serves corporate headquarters and university campuses seeking utilization efficiency.
Today's leader: Cleaning. Tomorrow's challenger: Maintenance.
End User:
Healthcare and education verticals demonstrate recession-resistant contract structures, while office and retail exposure ties performance to commercial real estate cycles.
- Healthcare Facilities:Stringent TGA hygiene mandates and 24/7 operational requirements create the most defensible contract terms. Hospital networks are extending single-provider agreements to cover clinical equipment maintenance, waste management, and specialized cleaning under unified accountability.
- Educational Institutions:Extended operational hours across university campuses and K-12 facilities drive demand for integrated hard and soft service bundling. Victorian and New South Wales public school procurement frameworks favor vendors offering CMMS-enabled asset lifecycle management alongside daily operations.
- Office Buildings:NABERS rating pressures and tenant experience competition are compressing management fees while demanding technology integration.
- Retail Outlets:High churn rates and seasonal demand volatility favor short-term, flexible service arrangements over long-term integrated contracts.
Healthcare anchors current profitability; education offers the steepest expansion trajectory as public sector procurement consolidates vendor panels.
Technology:
Deployment economics separate sensor hardware commoditization from software platform recurring revenue, with integration complexity determining vendor stickiness.
- Smart Building Solutions:Digital twin platforms and unified building automation systems command enterprise-scale deployments across major hospital networks and university precincts in Victoria.
- IoT Devices:Predictive equipment diagnostics and real-time energy monitoring sensors are expanding fastest across educational facilities seeking to reduce unplanned HVAC downtime.
- Energy Management Systems:NABERS compliance automation and demand response integration serves commercial office owners facing mandatory disclosure requirements.
- CMMS:Cloud-based preventive maintenance scheduling encounters resistance from legacy asset registers in institutional portfolios with decades of paper-based records.
IoT hardware scales volume fastest; CMMS platforms capture the most enduring customer lifetime value through data lock-in.
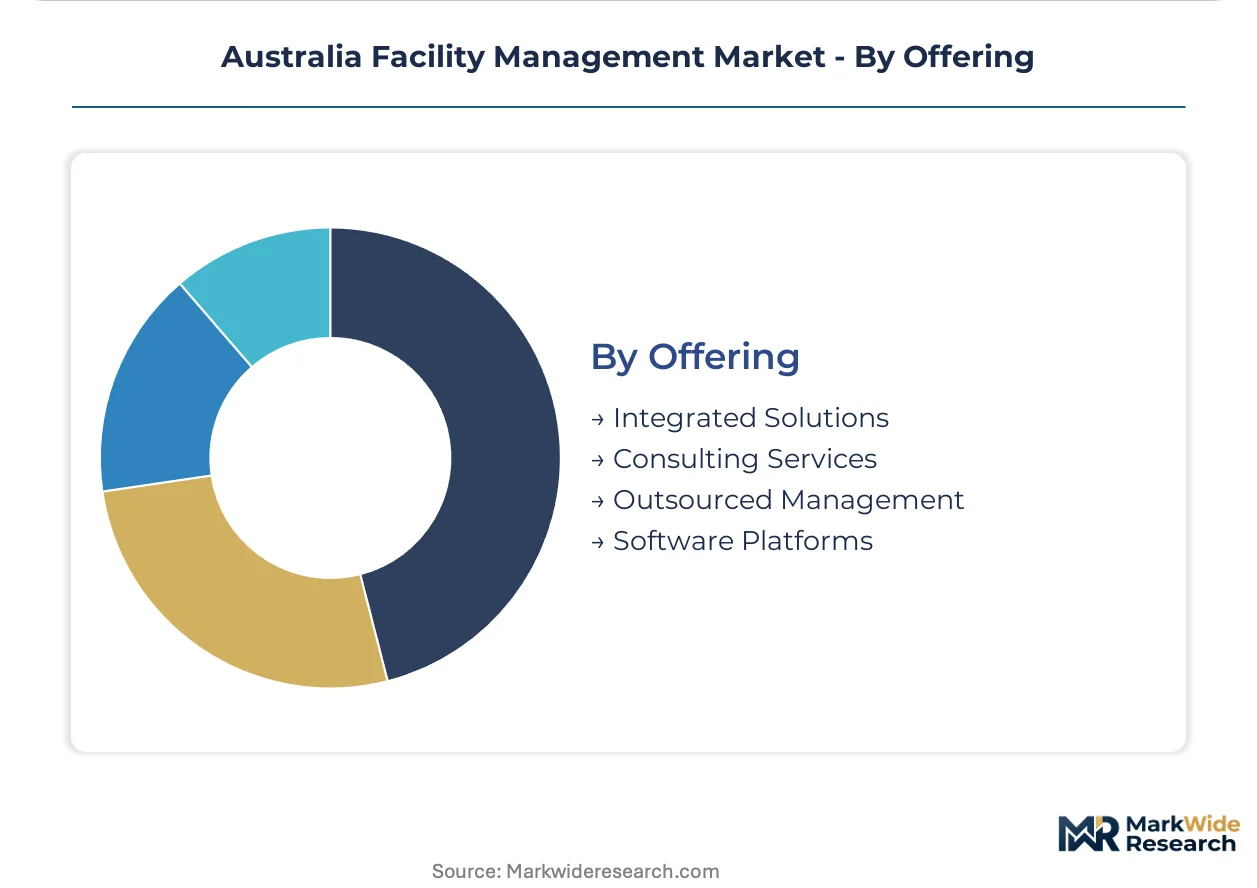
Offering:
Procurement patterns reveal a structural shift from transactional consulting engagements toward outcome-based integrated contracts with embedded technology.
- Integrated Solutions:Single-accountability bundling of hard services, soft services, and compliance management is winning major government and institutional tenders. New South Wales public hospital clusters have compressed vendor panels from 15-20 suppliers to 3-4 integrated platforms.
- Outsourced Management:Full facility operations transfer with KPI-linked pricing dominates healthcare and education verticals seeking to convert fixed costs to variable structures.
- Consulting Services:Strategic advisory on energy retrofit planning and NABERS optimization serves asset owners preparing for disclosure mandate expansion.
- Software Platforms:Standalone CMMS and energy analytics subscriptions compete against integrated vendors bundling software with service delivery.
Integrated solutions own the premium tier; software platforms face margin pressure as larger vendors bundle technology at cost.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New South Wales and Victoria concentrate the majority of Australia's facility management contract value through dense commercial office stock and expanding healthcare infrastructure. State-level procurement consolidation and mandatory energy disclosure mandates are redistributing service demand across Australia's eastern seaboard.
New South Wales
Sydney's commercial tower density and public hospital network expansion drive integrated service bundling. The state's Building Sustainability Index compliance requirements are accelerating predictive maintenance adoption across CBD office portfolios. Western Sydney health precincts are consolidating cleaning, security, and clinical equipment maintenance under single-provider frameworks.
Victoria
Melbourne's university campuses and government office stock sustain long-term integrated contracts with embedded technology clauses. Victorian government green procurement policies prioritize low-VOC materials and recycled steel framing in public building tenders. Major hospital networks in the inner suburbs are deploying digital twin platforms to synchronize preventive maintenance with equipment degradation curves.
Queensland
Brisbane's aging commercial stock and emerging healthcare infrastructure present retrofit opportunities as disclosure mandates expand. The state's Work Health and Safety accreditation requirements extend contractor onboarding timelines, favoring established integrated platforms over specialized entrants. South East Queensland education precincts are piloting IoT-enabled predictive HVAC diagnostics to reduce unplanned downtime.
Western Australia
Perth's isolated location and skilled technician shortages create service delivery gaps that integrated energy-performance contractors are targeting. The state's mining-linked commercial property cycles favor flexible contract structures over long-term bundled agreements. Government office retrofits in the Perth CBD are embedding NABERS compliance automation into facility management specifications.
South Australia
Adelaide's smaller commercial market sustains regional specialist operators alongside national platform subsidiaries. State government procurement frameworks are consolidating vendor panels for public school maintenance and cleaning services. The Tonsley innovation precinct is testing smart building convergence between facility operations and food service logistics platforms.
Australia Facility Management Market Vendor Landscape
Global majors compete with regional champions across service bundling capabilities and technology integration depth. The market exhibits tiered concentration where three to four integrated platforms capture major government and institutional tenders, while specialized operators defend margins in single-service niches. Strategic archetypes include integrated hard-soft service bundlers, technology-enabled compliance specialists, and regional cleaning-security subcontractors. Competitive moves center on procurement panel consolidation and predictive maintenance platform deployment.
Among global-originated integrated platforms, CBRE Group and JLL Limited exemplify the bundled service archetype through their property management lineage. ISS Australia and Sodexo Facilities Management Services occupy positions combining specialized vertical expertise with scale advantages. Ventia Services Group represents the infrastructure-focused regional champion model. These named entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| CBRE Group |
| ISS Australia |
| Sodexo Facilities Management Services |
| Ventia Services Group |
| JLL Limited |
| Cushman and Wakefield |
| Serco Facilities Management |
| Vinci Facilities Limited |
| Compass Group Inc. |
| Others |
Supply Flow & Price Mechanics
Horizontal integration across cleaning, security, and maintenance service lines anchors pricing power for Tier-one facility management platforms bidding on Australian government and institutional contracts. This consolidation pattern concentrates vendor relationships in Sydney and Melbourne while compressing margins for regional subcontractors in Queensland and Western Australia who lack bundled service capabilities.
Pricing Analysis
Input-cost pass-through from licensed technician wages and TGA-compliant material sourcing shapes contract pricing across the Australian facility management market. Outcome-based pricing structures with KPI-linked performance clauses dominate healthcare and education verticals, while spot-market hourly rates persist in retail and flexible office segments. Price differentiation rests on certification tier — CFM-credentialed teams command premium positioning over uncertified regional operators. Pricing pressure stems from procurement panel consolidation in New South Wales and Victoria, where vendor compression from 15-20 suppliers to 3-4 integrated platforms intensifies competitive bidding. Small commercial office owners in Perth and Adelaide exhibit highest price sensitivity due to thinner operational budgets and NABERS compliance cost burdens.
Supply Chain Analysis
Direct-to-institution channels handle major hospital network and university campus demand, while subcontractor networks service fragmented commercial office portfolios across state capitals. Geographic supply concentration centers on New South Wales and Victoria, where skilled technician pools and TGA-certified material distributors cluster in Sydney and Melbourne. Raw material dependencies include low-VOC coating systems, recycled steel framing, and IoT sensor hardware imported from China, South Korea, and Germany. Supply chain risk manifests in single-source vulnerability for specialized healthcare cleaning chemicals and predictive maintenance software licenses. Distribution runs through national integrated platforms with captive subcontractor panels, supplemented by regional specialist operators in South Australia and Western Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian facility management functions as a geographic-arbitrage play where Perth and Brisbane operators capture eastern-state margin premiums without matching Sydney-Melbourne compliance cost structures. Western Australia's lagging NABERS mandate timeline creates a 24-36 month window for integrated platforms to establish energy-performance contracting before disclosure requirements tighten.
For Market Incumbents: Acquire predictive maintenance software assets and digital twin platform capabilities to defend against technology-enabled entrants unbundling compliance services. Consolidate regional subcontractor relationships in Queensland and Western Australia to close service delivery gaps created by skilled technician shortages. Anchor defensive positioning through CFM certification investment and captive supply of TGA-compliant materials.
For New Entrants and Emerging Players: CMMS-native workflow automation serves as the technology-first wedge for penetrating South Australian and Queensland education precincts with legacy paper-based asset registers. Target Perth commercial retrofits as the most penetrable geography, where aging office stock and delayed energy disclosure mandates create white space for integrated energy-performance contracting. Lead go-to-market through NABERS compliance automation bundled with basic maintenance services.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional cleaning-security subcontractors face quality consistency risks and 40-60 day onboarding delays from Work Health and Safety accreditation requirements. Long-term viability favors integrated platforms with captive technology stacks and bundled service contracts in healthcare and education verticals. Watch Victorian and New South Wales government green procurement policy expansion as the inflection signal for recycled material and low-VOC specification mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | CBRE Group and JLL Limited embed IoT diagnostics to capture NABERS compliance bundling. |
| Healthcare Service Integration | ISS Australia extends specialized cleaning protocols into clinical equipment maintenance contracts. |
| Subcontractor Network Consolidation | Tier-one platforms acquire regional cleaning operators to close Queensland and Western Australia coverage gaps. |
| Digital Twin Asset Modeling | Victorian hospital networks deploy virtual building replicas to synchronize preventive maintenance schedules. |
| Green Procurement Certification | Sodexo Facilities Management Services aligns food-facilities convergence with Victorian low-VOC material mandates. |
Methodological Framework
Multiple input streams — facility management contract databases, TGA building material compliance filings, and state-level procurement framework documents — were reconciled with primary fieldwork across the Australian market. Interviews with hospital network procurement directors, university campus operations managers, commercial property asset managers, and integrated platform account executives supplied operational validation. Secondary sources included Australian Building Codes Board regulatory updates, NABERS rating disclosure datasets, Work Health and Safety accreditation records, and state government tender databases. Bottom-up contract value aggregation and top-down market sizing triangulation anchored volume and value estimates.
Data-stream reconciliation across service type, end-user vertical, technology deployment, and regional adoption patterns structured the analytical framework. Segmentation modeling captured hard services, soft services, and integrated solutions alongside healthcare, education, office, and retail end-use categories. CAGRs were derived from trend extrapolation of contract renewal rates, outsourcing penetration trajectories, and technology substitution curves across the projection horizon. Forecast inputs incorporated NABERS mandate expansion timelines, skilled labor supply constraints, and CMMS platform adoption velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to National Construction Code amendment timing and energy performance disclosure mandate geographic expansion. Periodic stress-testing of base assumptions is recommended against regulatory acceleration scenarios and subcontractor labor market tightening.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
North America Soft Facility Management Market
Facility Management
Slovak Republic Facility Management Market
Facility Management
South Africa Facility Management Market
Facility Management
Canada Facility Management Market
Facility Management
Czech Republic Facility Management Market
Facility Management
India Integrated Facility Management Market
Facility Management
France Facility Management Market
Facility Management
New Zealand Facility Management Market
Facility Management
Africa Facility Management Market
Facility Management
Malta Facility Management Market
Facility Management
Soft Facility Management Market
Facility Management
Indonesia Facility Management Market
Facility Management
Croatia Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
Malaysia Facility Management Market