
 Indonesia Facility Management Market | 2026-2036
Indonesia Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Facility Management Market Outlook
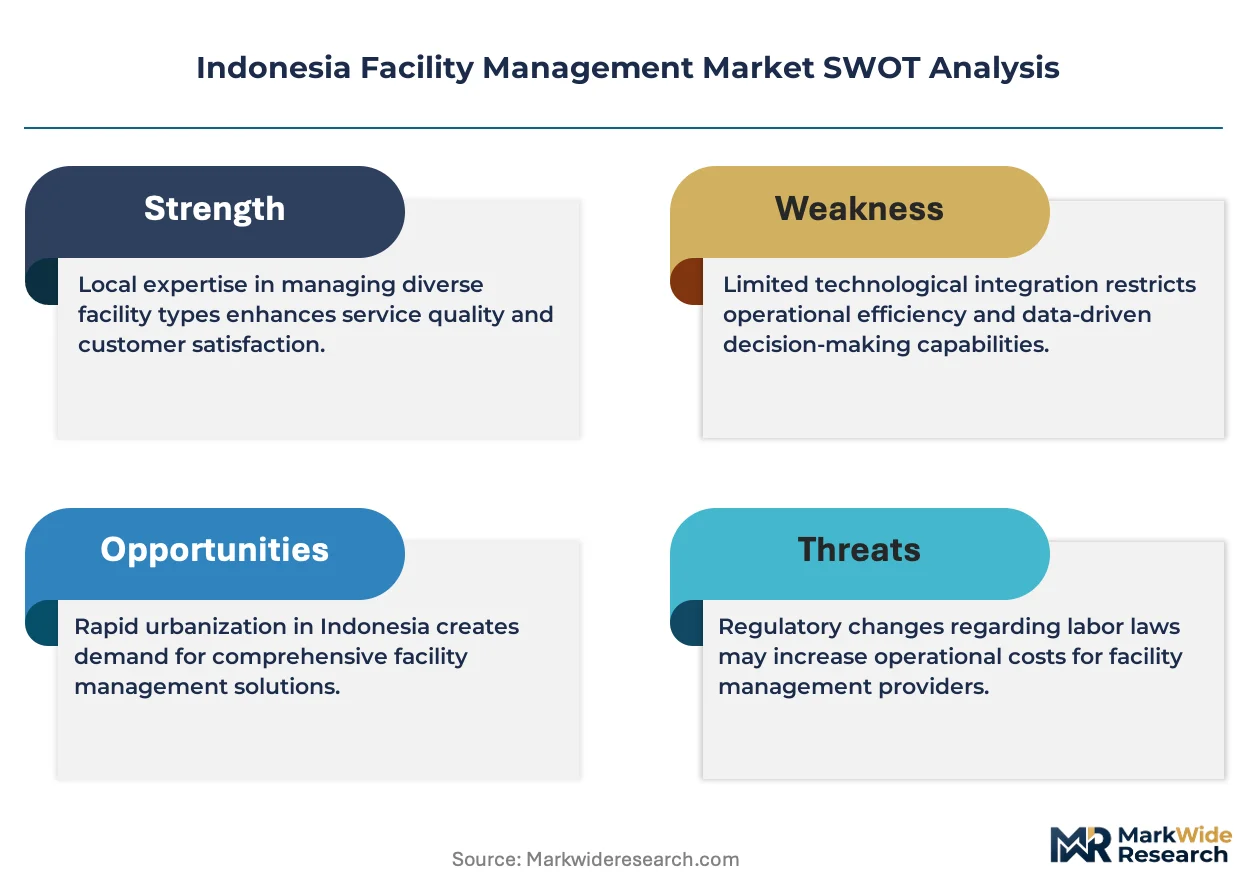
The Indonesia facility management sector is restructuring around a widening gap between premium integrated service bundles and commoditized single-service contracts. Colliers Facility Management Services leverages its property advisory heritage to anchor high-margin bundled offerings in Jakarta's Grade-A office towers. JLL Inc. competes through technology-enabled workplace solutions that differentiate its tenant-experience platform. PT Shield On Service Tbk sustains cost leadership in security staffing across industrial estates in Bekasi and Karawang.
Facility management encompasses the coordination of building infrastructure, operational support, and occupant services to ensure functional, safe, and efficient environments across commercial, industrial, and institutional assets. The discipline integrates preventive maintenance protocols, energy performance monitoring, and compliance auditing against Indonesian National Standards for building safety and fire protection. Maintenance Services leads revenue contribution due to recurring capital-expenditure cycles in aging commercial stock across Jakarta and Surabaya. Corporate Offices represents the fastest-growing end-user channel as multinational tenants mandate integrated service-level agreements aligned with global headquarters standards. Building Management Systems concentrates margin pools where vendors combine software licensing with multi-year operational contracts.
BIS certification requirements for fire safety and electrical systems shape vendor eligibility for government and premium commercial contracts. Indonesia's Ministry of Public Works and Public Housing regulations on green building standards, alongside local fire department enforcement of SNI protocols, elevate compliance costs for smaller operators. Stakeholders must monitor how IoT-enabled predictive maintenance platforms reshape procurement criteria and contract structures across Java's dominant property corridors.
Market Dynamics
Indonesia's facility management sector is bifurcating around BIS certification requirements for building safety systems, which now gate access to government and premium commercial contracts while compressing margins for uncertified operators serving mid-tier assets.
Growth Catalysts
- Green Building Standards:Indonesia's Ministry of Public Works and Public Housing regulations on green building standards mandate energy performance monitoring systems in new commercial developments, creating pull for integrated facility management platforms.
- Corporate Office SLA Convergence:Multinational tenants in Jakarta's Grade-A towers now mandate integrated service-level agreements aligned with global headquarters standards, bundling hard and soft services under single-vendor contracts.
- IoT Predictive Maintenance:Sensor-enabled building management systems are reshaping procurement criteria across Java's property corridors, replacing scheduled maintenance with condition-based protocols.
Market Restraints
- Certification Cost Burden:BIS certification requirements for fire safety and electrical systems impose fixed compliance costs that disproportionately burden smaller operators serving provincial markets.
- Skilled Labor Concentration:Certified technicians and safety engineers concentrate in Greater Jakarta, creating supply bottlenecks for facility management contracts in Sumatra and Sulawesi.
- Legacy Asset Fragmentation:Aging commercial stock across Surabaya and Bandung requires customized maintenance protocols that resist standardization, eroding economies of scale.
Strategic Opportunities
- Secondary City Penetration:Makassar and Medan exhibit underpenetrated facility management markets where first-mover vendors can establish integrated service benchmarks before competitor saturation.
- Building Management System Convergence:Software licensing bundled with multi-year operational contracts concentrates margin pools for vendors combining digital platforms with on-ground service delivery.
- Industrial Estate Expansion:Bekasi and Karawang manufacturing corridors generate demand for specialized security staffing and utilities management as Japanese and Korean manufacturers expand production footprints.
Industry Challenges
- Certification Timeline Compression:BIS audit cycles for fire protection systems extend vendor onboarding timelines, delaying contract commencement and straining working capital.
- Workforce Skill Gaps:Shortages of technicians trained in both mechanical systems and digital platform operation limit deployment of integrated service teams across multi-site corporate accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Facility Management Market |
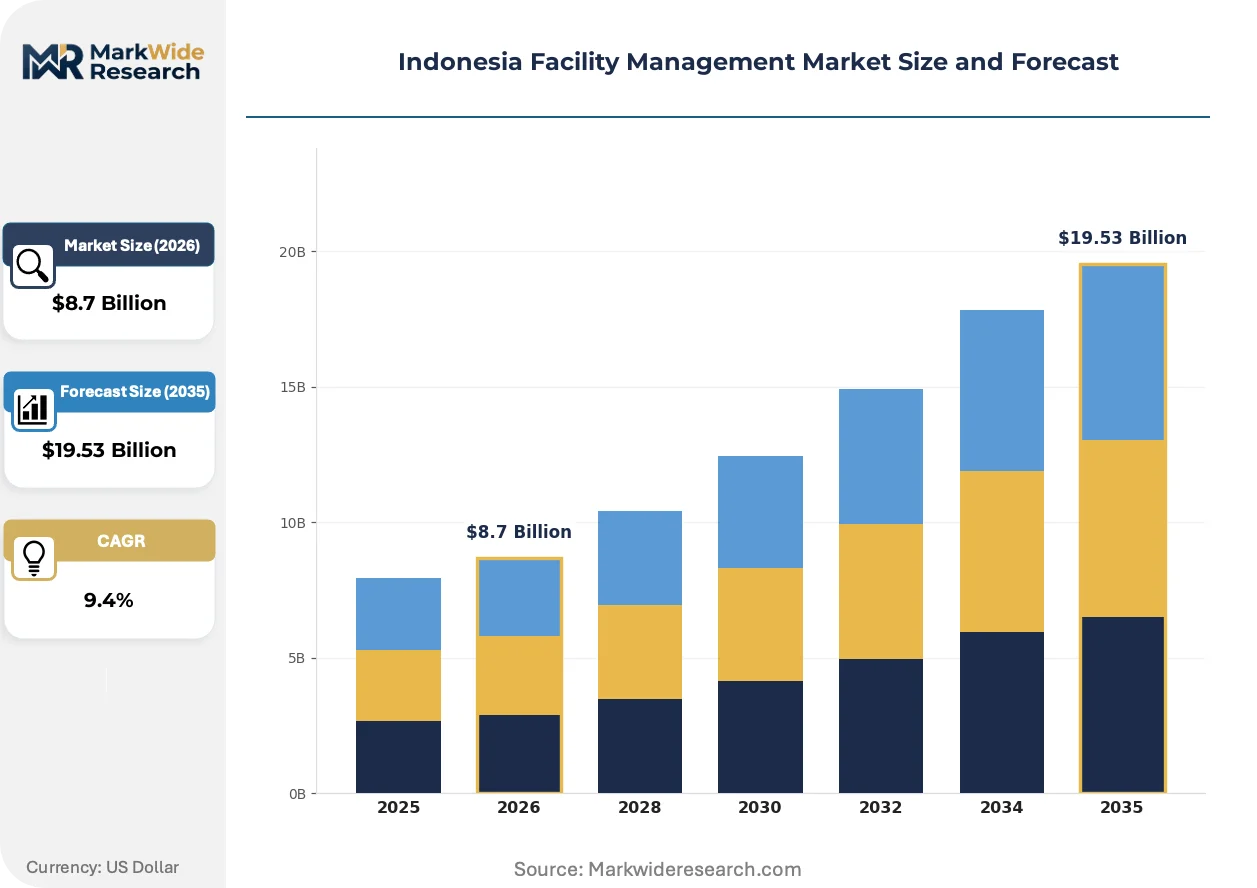
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Security Services, Maintenance Services, Landscaping Services End User: Corporate Offices, Educational Institutions, Hospitals, Retail Outlets Technology: Building Management Systems, IoT Solutions, Energy Management Software, Automated Control Systems Facility Type: Commercial Buildings, Industrial Facilities, Residential Complexes, Government Buildings |
| Companies Covered | Colliers Facility Management Services, JLL Inc., PT Shield On Service Tbk, CBRE Indonesia, PT Sodexo Motivation Solutions Indonesia, Atalian Global Services, PT Spektra Solusindo, PT Patra Jasa, ISS Facility Services Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Facility Management Market Strategic Shifts
Digital infrastructure is penetrating Indonesia's facility management stack at uneven rates, with premium commercial assets adopting sensor networks while provincial industrial facilities lag in automation investment.
Building Management Systems are converging with cloud-based analytics platforms to enable real-time energy monitoring across Jakarta's Grade-A office towers. Property managers at developments like SCBD and Thamrin Nine are deploying these integrated stacks to meet green building certification requirements. This technology convergence is compressing the traditional separation between facilities software vendors and on-ground service operators.
Indonesia's Ministry of Public Works and Public Housing has tightened enforcement of SNI fire protection protocols through coordination with local fire departments. The regulatory friction elevates compliance costs for uncertified vendors while creating procurement preference for BIS-accredited operators. Corporate office end users in Jakarta and Surabaya are now embedding certification requirements directly into tender documents.
Corporate procurement teams are consolidating vendor relationships from fragmented single-service contracts toward integrated facility management agreements. Multinational tenants in BSD City and TB Simatupang corridors now specify unified KPIs spanning cleaning, security, and mechanical maintenance. This buying-pattern shift is most visible among Japanese and Korean manufacturing firms establishing regional headquarters in Greater Jakarta.
Indonesia Facility Management Market Segmentation
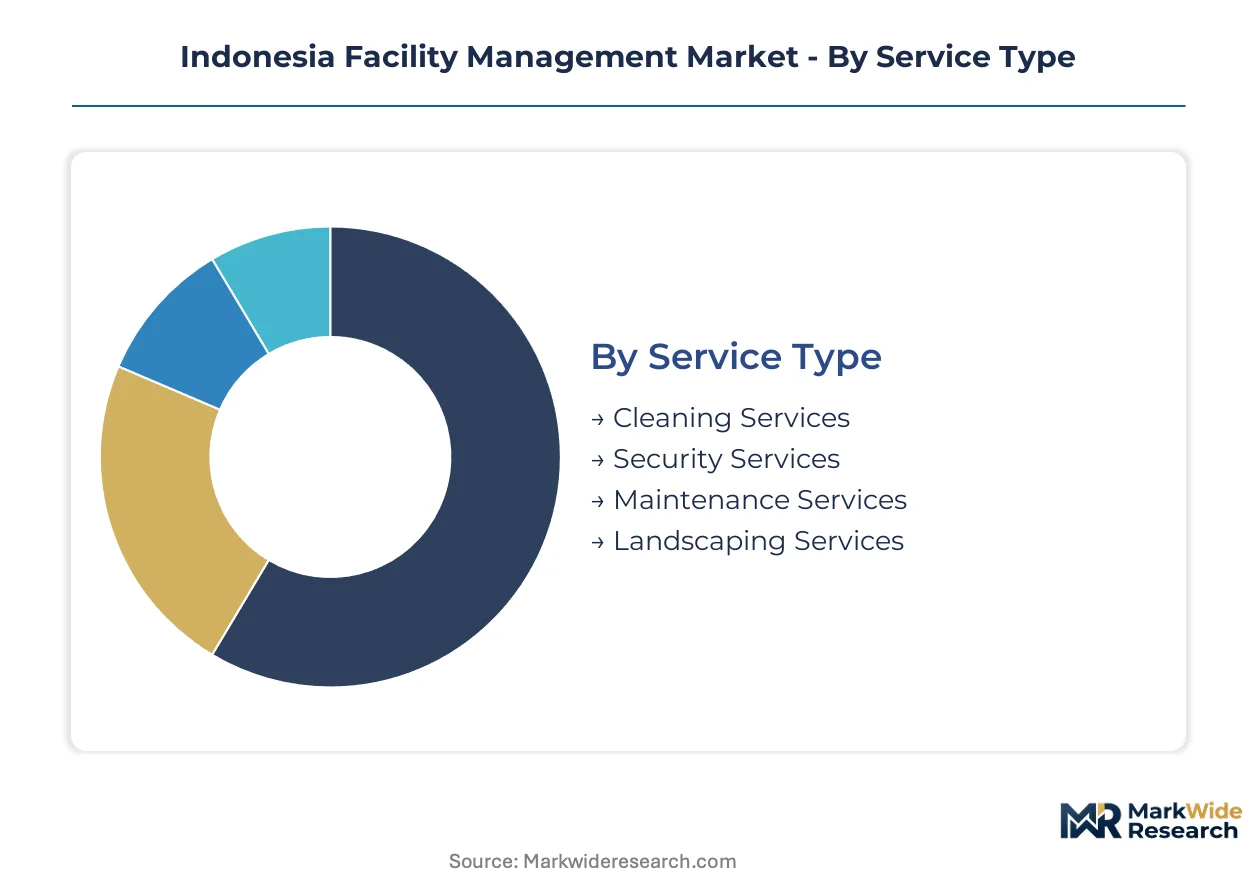
Indonesia's facility management market fragments along service sophistication and asset class lines, with Jakarta's Grade-A commercial towers pulling premium integrated bundles while provincial industrial estates absorb commoditized single-service contracts. Understanding these divides reveals where margin pools concentrate and where scale economies erode.
Service Type:
Volume concentrates in labor-intensive staffing services, while premium margin pools accrue to technology-augmented maintenance protocols.
- Maintenance Services:Encompasses preventive and corrective protocols for mechanical, electrical, and plumbing systems across aging commercial stock. Demand clusters in Jakarta and Surabaya where recurring capital-expenditure cycles in buildings over 15 years old sustain contract renewals. BIS certification requirements for fire safety and electrical systems gate vendor eligibility for premium contracts.
- Security Services:Deploys staffed guarding and access control systems, often bundled with surveillance technology in high-tenant-density assets. Bekasi and Karawang industrial corridors generate concentrated demand as Japanese and Korean manufacturers mandate integrated security-utility packages for regional headquarters.
- Cleaning Services:Labor-intensive janitorial and specialized sanitation operations serving high-traffic commercial and healthcare environments.
- Landscaping Services:Grounds maintenance and horticultural management for corporate campuses and residential estates.
Today's leader: Maintenance Services. Tomorrow's challenger: Security Services.
End User:
Multinational tenant standards reshape procurement patterns across user categories, elevating integrated service-level agreements over fragmented single-vendor arrangements.
- Corporate Offices:Grade-A towers in Jakarta's SCBD and TB Simatupang corridors drive adoption of bundled hard and soft services under unified KPI frameworks. Multinational mandates for alignment with global headquarters standards accelerate contract consolidation toward single-vendor integrated agreements.
- Hospitals:Healthcare facilities demand specialized infection control protocols and 24/7 critical systems redundancy. Indonesia's Ministry of Health regulations on medical facility safety intersect with BIS fire protection standards, elevating compliance costs and vendor qualification thresholds.
- Educational Institutions:Universities and schools require seasonal staffing flexibility and deferred maintenance programs.
- Retail Outlets:Shopping centers and storefronts prioritize high-frequency cleaning and security visibility.
Corporate Offices command current revenue share. Hospitals are climbing the fastest as healthcare infrastructure expands.
Technology:
Digital adoption bifurcates between sensor-enabled premium assets and manually operated provincial facilities, compressing procurement timelines where platforms prove ROI.
- Building Management Systems:Integrated software-hardware stacks enabling centralized control of HVAC, lighting, and access systems. Jakarta's Thamrin Nine and comparable Grade-A developments deploy these platforms to meet Ministry of Public Works green building certification requirements, bundling multi-year operational contracts with licensing fees.
- IoT Solutions:Sensor networks enabling predictive maintenance protocols that replace scheduled service intervals. Java's dominant property corridors are reshaping vendor selection criteria around condition-based monitoring capabilities.
- Energy Management Software:Analytics platforms for consumption tracking and efficiency optimization.
- Automated Control Systems:Programmable logic controllers and robotics for facility operations.
Building Management Systems anchor present margins. IoT Solutions are gaining share fastest as sensor costs decline.
Facility Type:
Asset age and tenant density determine service bundling economics, with newer commercial stock enabling standardized protocols and legacy industrial facilities requiring customized maintenance.
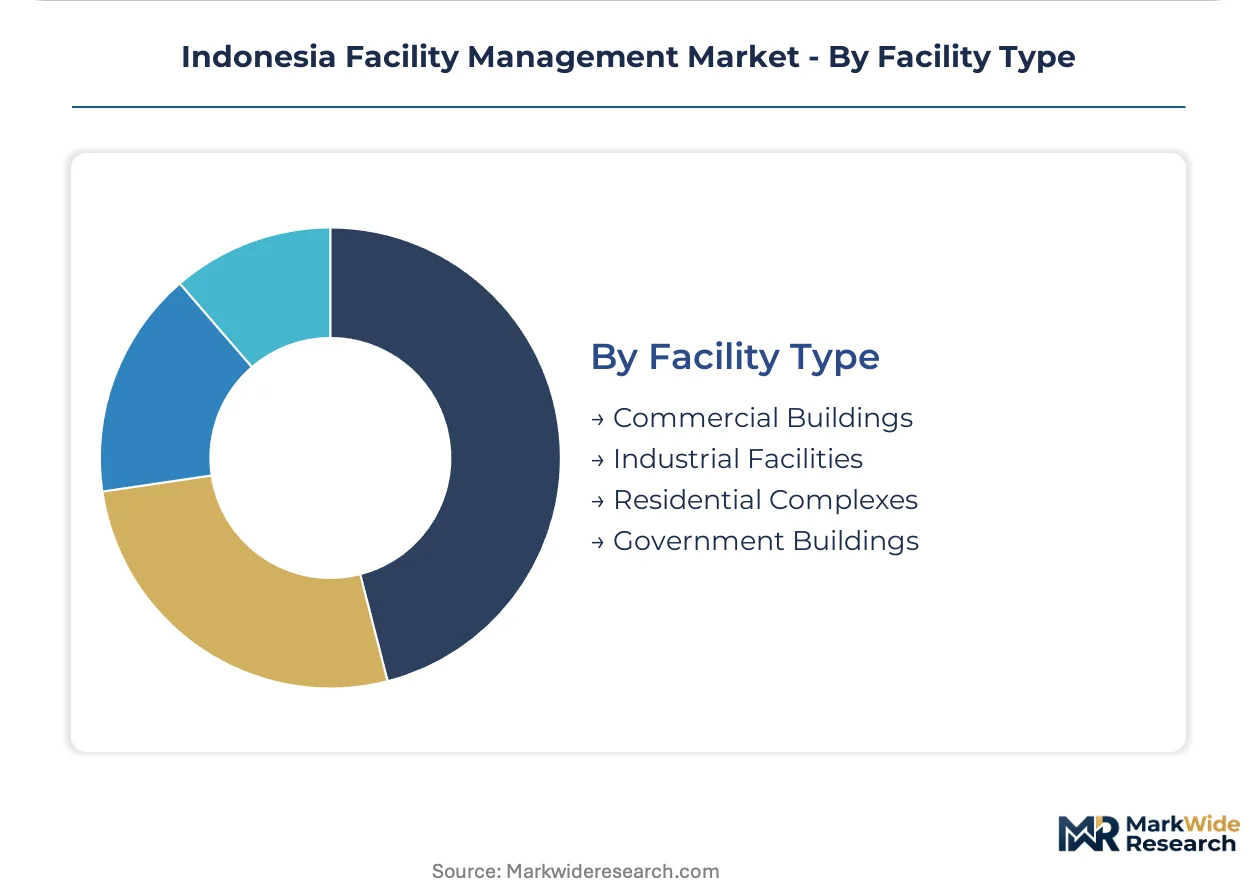
- Commercial Buildings:Office towers and mixed-use developments in Greater Jakarta sustain the deepest integrated service penetration. Green building standards enforcement through the Ministry of Public Works mandates energy performance monitoring, pulling facility management platforms into core building operations.
- Industrial Facilities:Manufacturing plants and logistics centers in Bekasi and Karawang generate specialized demand for utilities management and perimeter security. Japanese and Korean production footprint expansion sustains contract growth in these corridors.
- Residential Complexes:Apartment towers and gated communities require amenity maintenance and concierge services.
- Government Buildings:Public sector assets face extended procurement cycles and BIS certification requirements that delay vendor onboarding.
Commercial Buildings dominate current contract value. Industrial Facilities show steepest expansion trajectory as manufacturing investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified facility management technicians cluster in Greater Jakarta, creating supply bottlenecks for contracts in Sumatra and Sulawesi while elevating labor costs in secondary cities. This geographic concentration shapes service availability and pricing dynamics across the archipelago.
Java
Grade-A office towers in Jakarta's SCBD and TB Simatupang corridors drive integrated service adoption under unified KPI frameworks. Indonesia's Ministry of Public Works enforces green building standards that mandate energy performance monitoring systems in new commercial developments. Surabaya's aging commercial stock sustains recurring maintenance contracts as buildings exceed 15-year capital expenditure cycles.
Sumatra
Medan's underpenetrated facility management market offers first-mover advantages for vendors establishing integrated service benchmarks. Local fire department enforcement of SNI fire protection protocols elevates compliance costs for uncertified operators. Industrial estates in Batam generate specialized demand for security staffing and utilities management as electronics manufacturers expand production footprints.
Sulawesi
Makassar exhibits limited vendor presence relative to its commercial real estate growth trajectory. BIS certification requirements for building safety systems gate access to government contracts and premium commercial tenders. The city's emerging mixed-use developments pull basic maintenance services while integrated platforms remain scarce.
Kalimantan
Balikpapan and Samarinda sustain demand from oil and gas sector facilities requiring specialized mechanical maintenance protocols. Indonesia's Ministry of Public Works regulations on industrial facility safety intersect with sector-specific environmental compliance requirements. Mining sector expansion in East Kalimantan generates contract opportunities for perimeter security and utilities management.
Bali and Nusa Tenggara
Tourism-dependent commercial assets in Denpasar prioritize high-frequency cleaning and visible security presence over technology-enabled platforms. Regional fire safety enforcement varies across municipal jurisdictions, creating inconsistent vendor qualification thresholds. Hospitality sector recovery post-pandemic is reshaping procurement patterns toward flexible staffing arrangements.
Indonesia Facility Management Market Competitive Environment
Top-tier vendors anchor integrated service bundles in Jakarta's premium commercial towers, while mid-tier operators compete on cost leadership for provincial industrial contracts. The market structure reflects a bifurcation between technology-augmented platform providers and labor-intensive staffing specialists. Two strategic archetypes dominate: property advisory heritage firms leveraging real estate relationships, and industrial security specialists capturing manufacturing corridor contracts. Competitive moves concentrate on certification acquisition for BIS eligibility and geographic expansion into secondary cities ahead of competitor saturation.
Within the property advisory heritage tier, Colliers Facility Management Services and JLL Inc. exemplify integrated platform providers combining software licensing with multi-year operational contracts. PT Shield On Service Tbk occupies a position representing cost-focused security staffing specialists serving Bekasi and Karawang industrial corridors. These three entities collectively illustrate the competitive spectrum from premium bundled offerings to commoditized single-service arrangements.
| Leading Market Players |
|---|
| Colliers Facility Management Services |
| JLL Inc. |
| PT Shield On Service Tbk |
| CBRE Indonesia |
| PT Sodexo Motivation Solutions Indonesia |
| Atalian Global Services |
| PT Spektra Solusindo |
| PT Patra Jasa |
| ISS Facility Services Inc. |
| Others |
Value Chain & Pricing Dynamics
Multinational corporate office tenants in Jakarta's Grade-A towers anchor contract pricing through integrated service-level agreements that bundle hard and soft services under unified KPI frameworks. This buyer concentration compresses margins for single-service vendors while elevating premium pricing for BIS-certified operators capable of meeting global headquarters standards.
Pricing Analysis
Bundled integrated service contracts command premium positioning against unbundled single-service arrangements across Indonesia's facility management landscape. Price differentiation hinges on BIS certification tier and technology platform sophistication, with certified operators capturing government and premium commercial tenders. Cost compression in commoditized security staffing intensifies as PT Shield On Service Tbk and regional competitors expand Bekasi-Karawang coverage. Provincial industrial end users exhibit highest price sensitivity, while Jakarta Grade-A office tenants prioritize compliance alignment over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with China for IoT sensor hardware and South Korea for building automation control systems. Indonesia's facility management technology stack draws from Japanese mechanical components, Chinese digital infrastructure, and domestic labor pools. Tariff exposure on imported building management system hardware elevates total cost of ownership for platform-dependent vendors. Distribution runs through Jakarta-based master contractors with subcontractor networks extending to Surabaya, Medan, and Makassar.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's facility management market functions as a stable compounder, with recurring maintenance cycles in aging commercial stock and green building regulatory enforcement driving steady contract renewal velocity.
For Market Incumbents: Acquire certified technician training capacity to address skilled labor concentration in Greater Jakarta. Defensive consolidation should prioritize BIS accreditation investment ahead of fire safety audit cycle tightening, while backward integration into IoT platform development counters technology-enabled entrant pressure. For New Entrants and Emerging Players: Property developer joint ventures represent the most viable channel entry mechanism for unproven vendors. White-space concentration exists in Makassar and Medan integrated service markets, where first-mover positioning can establish benchmark contracts before competitor saturation. Target healthcare facility management as the fastest-climbing end-use segment, leveraging infection control specialization as differentiation. For Investors and Strategic Acquirers: Property advisory heritage firms are the most active acquirer in this space, consolidating regional operators to deepen Jakarta-Surabaya coverage. Long-term viability centers on technology-augmented platform providers with recurring revenue concentration. Monitor BIS certification timeline compression as the inflection signal for working capital stress among mid-tier operators.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Acquisition | Indonesia's Ministry of Public Works enforcement gates premium contract eligibility for fire safety-accredited vendors. |
| IoT Platform Integration | Sensor-enabled predictive maintenance protocols displace scheduled service intervals across Java's property corridors. |
| Secondary City Expansion | Makassar and Medan underpenetration allows first-mover vendors to establish integrated service benchmarks. |
| Technician Training Capacity Buildout | Certified mechanical and digital platform skills concentrate in Greater Jakarta, creating supply bottlenecks elsewhere. |
| Healthcare Specialization Development | Indonesia's Ministry of Health regulations intersect with BIS standards, elevating compliance barriers for generalist operators. |
Study Parameters
Bottom-up corporate office and industrial facility modeling reconciled against top-down vendor contract tracking forms the analytical core. Primary interviews with facility management directors, property asset managers, BIS certification auditors, and Ministry of Public Works enforcement officers combined with secondary validation from Indonesia's national statistics agency building permit data, Ministry of Trade import records for building automation equipment, and local fire department SNI compliance disclosure filings.
Input-output matrices mapped service-type demand against end-user facility stock across Java, Sumatra, Sulawesi, Kalimantan, and Bali-Nusa Tenggara sub-regions. Segmentation dimensions encompassed service sophistication tier, technology platform adoption stage, asset class age profile, and certification compliance level. CAGRs derived from contract renewal velocity analysis and capital expenditure cycle timing across the projection horizon. Forecast inputs incorporated green building standard enforcement trajectories and multinational tenant SLA convergence patterns.
Revisions become necessary when BIS certification timeline compression accelerates, IoT platform procurement criteria shift, or regional skilled labor migration patterns alter supply availability. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology adoption elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Europe Soft Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Latin America Facility Management Market
Facility Management
Finland Facility Management Market
Facility Management
Malta Facility Management Market
Facility Management
Austria Facility Management Market
Facility Management
GCC Facility Management Market
Facility Management
Portugal Facility Management Market
Facility Management
Malaysia Facility Management Market
Facility Management
Oman Facility Management Market
Facility Management
Romania Facility Management Market
Facility Management
India Integrated Facility Management Market
Facility Management
Singapore Facility Management Market
Facility Management
Ireland Facility Management Market
Facility Management
Spain Facility Management Market