
 Slovak Republic Facility Management Market | 2026-2036
Slovak Republic Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Slovak Republic Facility Management Market Outlook
The EU Green Deal is decoupling energy performance from simple cost bidding in Slovak FM tenders, raising compliance thresholds for new contracts. Sodexo Slovensko s.r.o. leverages its healthcare and education footprint to sustain recurring revenue streams across institutional clients. ISS Facility Services s.r.o. anchors its position through integrated security and cleaning bundles that dominate Bratislava commercial zones. CBRE Group, Inc. competes on technology-led asset advisory, differentiating its offer with building automation overlays that reduce tenant energy exposure.
Facility management encompasses the coordinated delivery of hard services (mechanical, electrical, and structural maintenance) and soft services (cleaning, security, and catering) to ensure optimal building performance across operational lifecycles. Slovak industrial facilities typically require FM providers to maintain HVAC systems within ISO 50001 energy management parameters while coordinating subcontractor networks across fragmented property ownership. Hard maintenance services command the deepest margin pools due to specialized technician scarcity and regulatory compliance burdens, while IoT Solutions within the Technology segment represents the fastest-expanding category as building automation platforms enable predictive maintenance and real-time energy monitoring across multi-site portfolios. Commercial Applications lead in contract value, though Institutional clients generate the most stable ten-year revenue visibility through public procurement frameworks.
The Ministry of Transport and Construction of the Slovak Republic enforces building energy certification aligned with EU directives, compelling FM providers to document carbon reduction pathways in every service agreement. BIS technical standards for fire safety and electrical systems create additional compliance layers that filter out undercapitalized local competitors. Stakeholders must weigh whether to build in-house energy analytics capabilities or partner with technology vendors before the next wave of public building retrofits reshapes contract specifications.
Market Dynamics
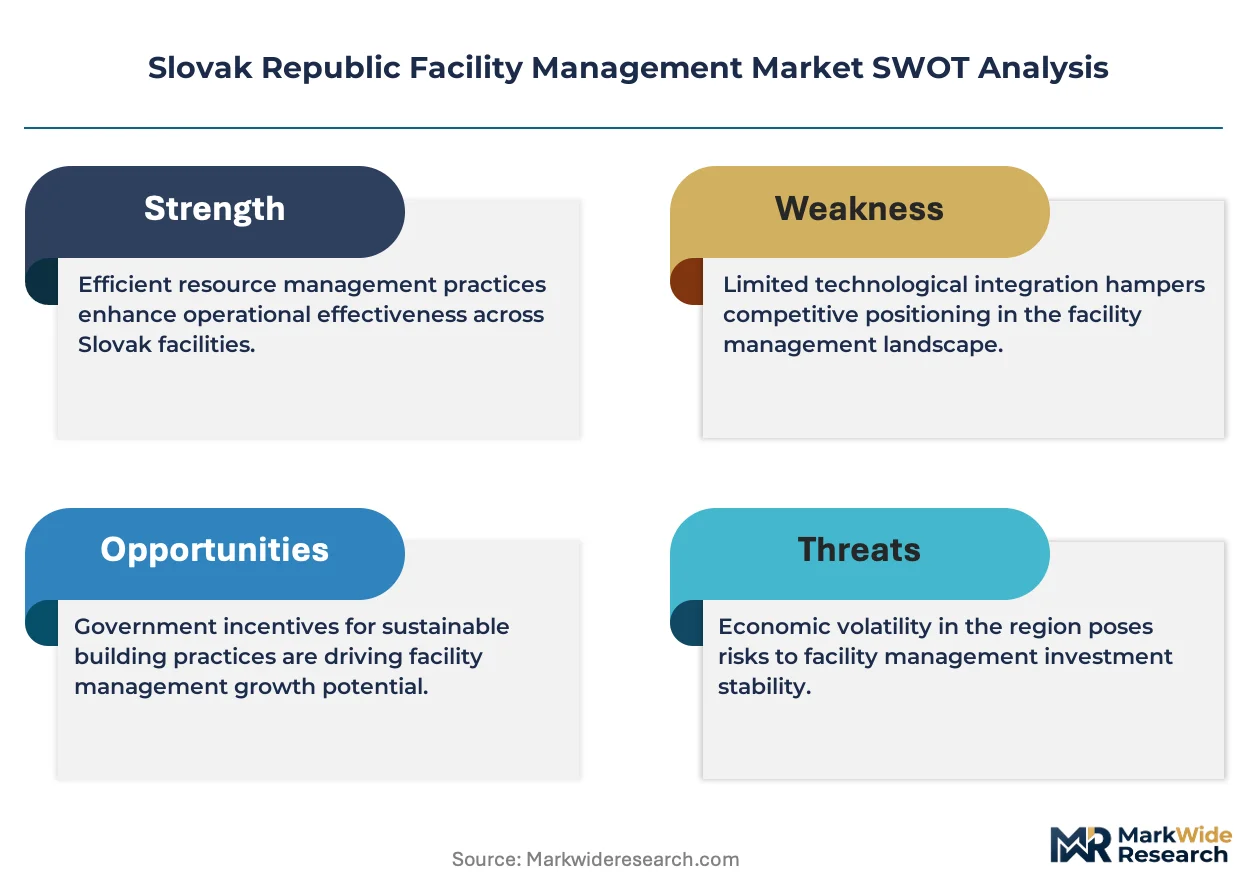
The EU Green Deal is compressing tender evaluation timelines as building energy certification requirements now mandate documented carbon reduction pathways before contract award, forcing FM providers to pre-validate compliance capabilities.
Growth Catalysts
- EU Green Deal energy performance mandates:The directive tightens building energy certification thresholds, compelling automotive manufacturing campuses in western Slovakia to outsource specialized HVAC and building automation services.
- Bratislava commercial zone concentration:Multinational tenant demand for integrated service bundles accelerates contract consolidation toward full-service providers capable of coordinating hard and soft services under single accountability.
- ISO 50001 energy management adoption:Industrial facilities require certified FM partners to maintain HVAC systems within standardized parameters, filtering out uncertified local competitors from premium contract pools.
Market Restraints
- Specialized technician scarcity:Hard maintenance services face margin pressure from limited availability of certified mechanical and electrical technicians capable of EU-compliant building system repairs.
- Fragmented property ownership:Subcontractor coordination complexity across dispersed industrial and institutional assets elevates administrative overhead and contract execution risk.
- BIS technical standard compliance costs:Fire safety and electrical system certification requirements impose capital burdens on smaller FM operators, consolidating contract access toward better-capitalized providers.
Strategic Opportunities
- Public building retrofit wave:Ministry of Transport and Construction mandates for energy efficiency upgrades create multi-year service contracts requiring integrated energy analytics and documented carbon reduction reporting.
- IoT-enabled predictive maintenance:Building automation platforms converging with real-time energy monitoring systems open premium pricing tiers for FM providers offering technology-led asset advisory.
- Trnava industrial corridor expansion:Automotive supplier clustering generates demand for multi-site portfolio management services spanning security, cleaning, and specialized industrial maintenance.
Industry Challenges
- Energy analytics capability gaps:FM providers must decide whether to build in-house carbon monitoring competencies or partner with technology vendors before retrofit contract specifications solidify.
- Legacy system integration friction:Building automation overlays face interoperability barriers with existing HVAC infrastructure, complicating deployment timelines and service level guarantees.
- Public procurement framework navigation:Institutional client contracts require specialized expertise in Slovak public tender documentation and compliance verification processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slovak Republic Facility Management Market |
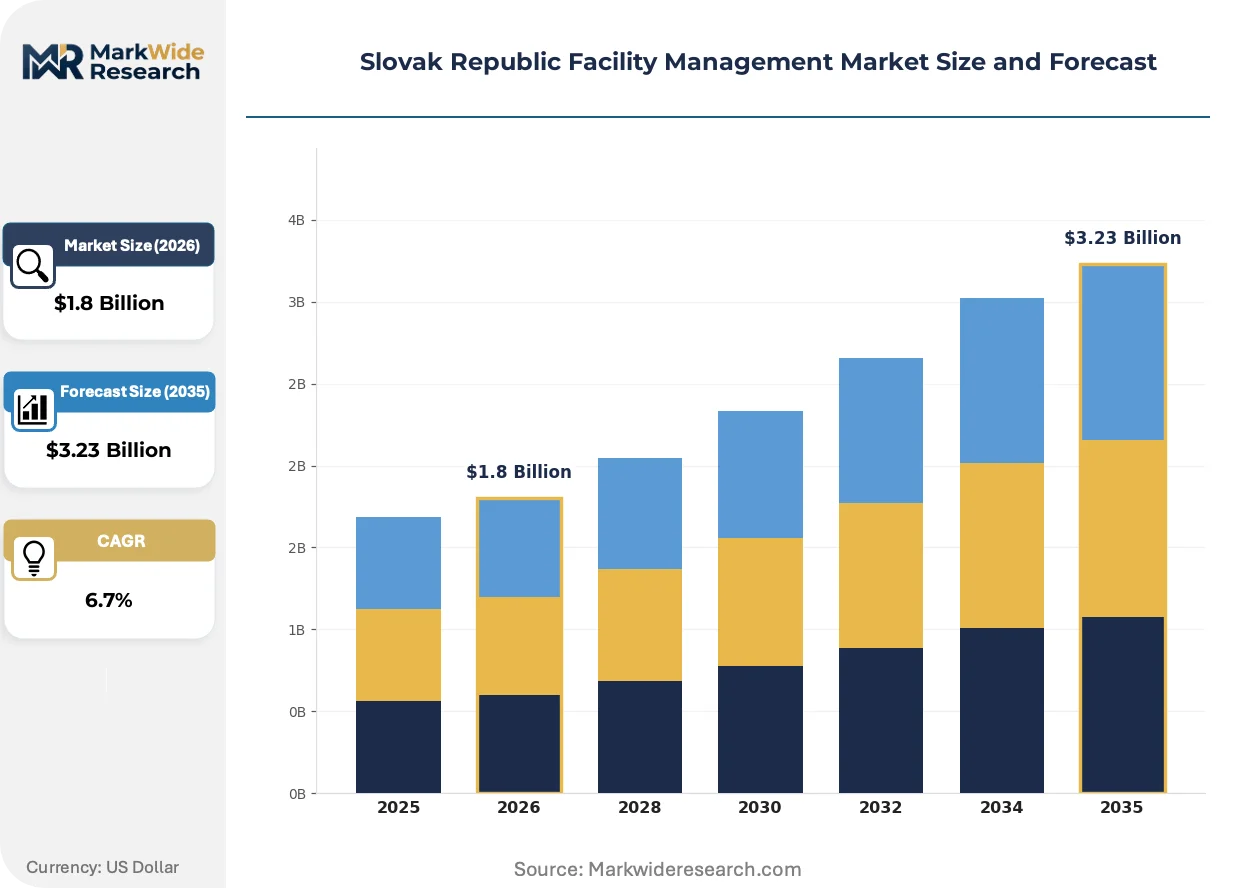
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Janitorial, Maintenance, Security, Landscaping Application: Commercial, Residential, Industrial, Institutional Client Type: Corporates, Government, NGOs, Educational Institutions Technology: IoT Solutions, Building Automation, Energy Management, BIM |
| Companies Covered | CBRE Group, Inc., Sodexo Slovensko s.r.o., ISS Facility Services s.r.o., BNP Paribas Real Estate Slovakia s.r.o., Cushman & Wakefield s.r.o., Apleona HSG s.r.o., JLL, ENGIE Services a.s., Reiwag Facility Services GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slovak Republic Facility Management Market Strategic Shifts
Building automation platforms are rewriting competitive differentiation as predictive capabilities separate technology-enabled providers from labor-dependent competitors. Three forces are compressing the window for capability investment.
IoT sensor networks are converging with cloud-based energy analytics to enable real-time HVAC performance monitoring across distributed industrial portfolios. Automotive manufacturing campuses in western Slovakia are piloting these systems at accelerated deployment schedules. This convergence is compressing acceptable response times for equipment failure detection from days to hours, resetting service level benchmarks.
The EU Green Deal's building energy certification requirements now mandate documented retrofit pathways in every public and large commercial contract. Industrial facility managers must submit carbon reduction timelines before tender award, shifting procurement evaluation toward compliance-validated providers. Bratislava commercial zones are experiencing the most acute specification tightening as multinational tenants face consolidated EU reporting obligations.
Integrated service bundling is displacing single-service contracting as multinational tenants demand unified accountability for security, cleaning, and hard maintenance outcomes. Property managers in the Trnava industrial corridor are consolidating vendor panels to reduce administrative overhead and interface complexity. This consolidation is most visible among automotive sector facilities where production continuity requirements elevate penalty exposure for service failures.
Slovak Republic Facility Management Market Segmentation
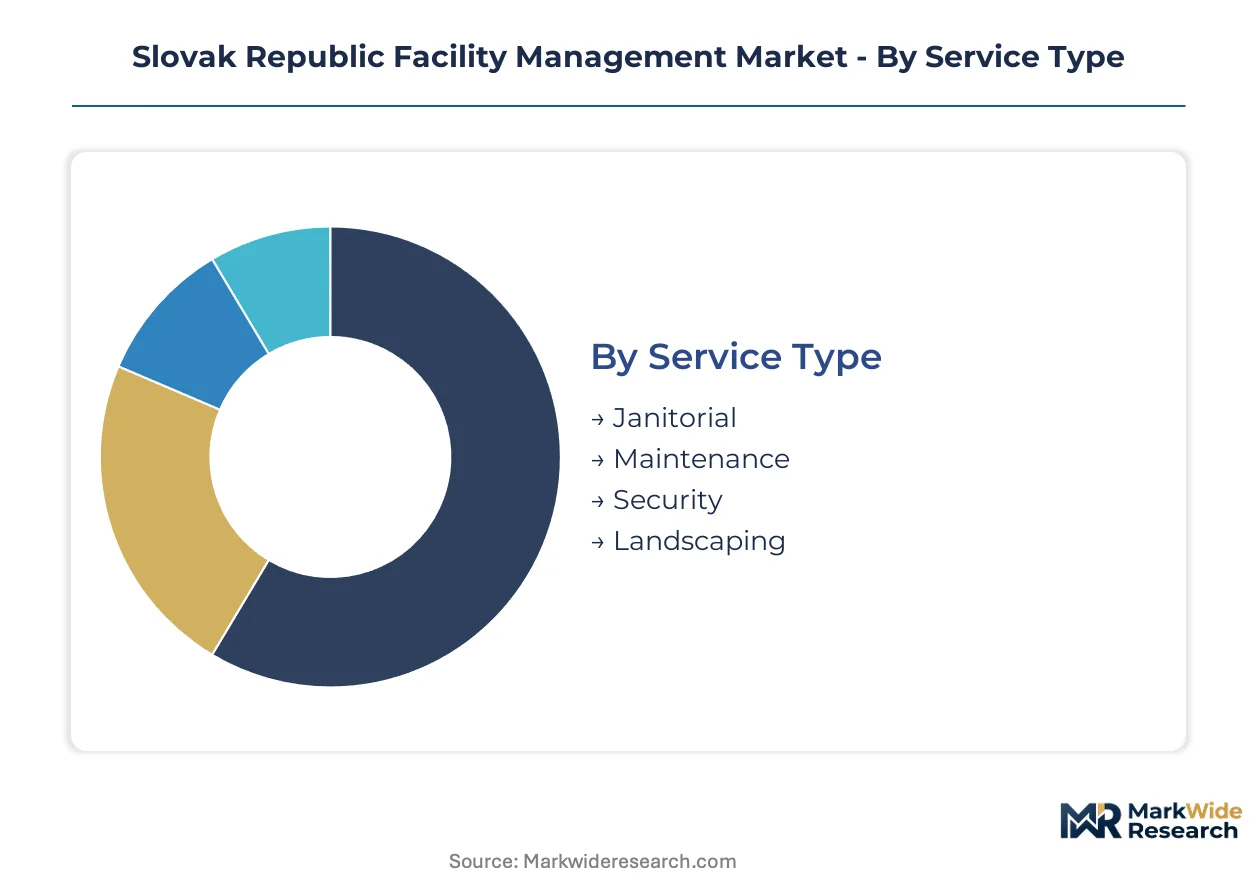
Segmentation in Slovak facility management reveals where procurement power concentrates and which service bundles command premium pricing. Contract specifications vary sharply across automotive manufacturing campuses, Bratislava commercial towers, and public institutional frameworks.
Service Type:
Upgrade cycles differ materially across hard and soft service categories, with equipment replacement timelines driving contract re-tendering frequency.
- Maintenance:Hard services encompassing HVAC, electrical, and mechanical systems require certified technicians operating under ISO 50001 energy management protocols. Automotive campuses in western Slovakia outsource these functions as EU Green Deal compliance tightens building energy certification thresholds.
- Security:Integrated security bundles combine physical guarding with access control systems and emergency response protocols. Bratislava commercial zones generate concentrated demand as multinational tenants seek single-accountability service structures.
- Janitorial:Cleaning services range from daily office maintenance to specialized industrial hygiene for manufacturing environments.
- Landscaping:Grounds maintenance and seasonal vegetation management for corporate campuses and institutional properties.
Volume placements concentrate in Maintenance; the faster expansion belongs to Security.
Application:
Margin structures diverge across application types, with industrial clients accepting premium pricing for production-critical service levels.
- Industrial:Manufacturing facilities demand 24/7 HVAC reliability and predictive maintenance systems to prevent production downtime. The Trnava automotive corridor drives contract consolidation toward full-service providers capable of coordinating multi-site portfolios.
- Commercial:Office buildings and retail centers in Bratislava prioritize integrated service bundles covering security, cleaning, and building automation under unified vendor accountability.
- Institutional:Public buildings and healthcare facilities operate under Ministry of Transport and Construction energy efficiency mandates requiring documented carbon reduction pathways.
- Residential:Property management services for multi-unit housing developments and residential complexes.
Commercial applications dominate absolute contract value; Institutional clients deliver the most stable ten-year revenue visibility through public procurement frameworks.
Client Type:
Procurement sophistication varies sharply, with government tenders imposing documentation burdens that filter out undercapitalized competitors.
- Corporates:Multinational tenants in Bratislava commercial zones drive integrated service contracting and demand real-time energy analytics reporting.
- Government:Public procurement frameworks require specialized expertise in Slovak tender documentation and BIS technical standard compliance verification.
- Educational Institutions:Universities and schools generate recurring revenue through long-term facility maintenance contracts.
- NGOs:Non-governmental organizations with specialized facility requirements and grant-funded maintenance budgets.
Government contracts carry the heaviest compliance overhead; Corporates offer the clearest path to technology-led service differentiation.
Technology:
Adoption maturity splits the provider base, with technology-enabled firms separating from labor-dependent competitors on predictive capabilities.
- IoT Solutions:Sensor networks enabling real-time equipment monitoring and automated fault detection across distributed industrial portfolios. Automotive manufacturing campuses pilot these systems at accelerated deployment schedules.
- Building Automation:Integrated control systems for HVAC, lighting, and security infrastructure. Bratislava commercial towers increasingly require these overlays to reduce tenant energy exposure and meet EU reporting obligations.
- Energy Management:Cloud-based analytics platforms documenting carbon reduction pathways for Ministry of Transport and Construction compliance.
- BIM:Building Information Modeling for facility lifecycle management and retrofit planning.
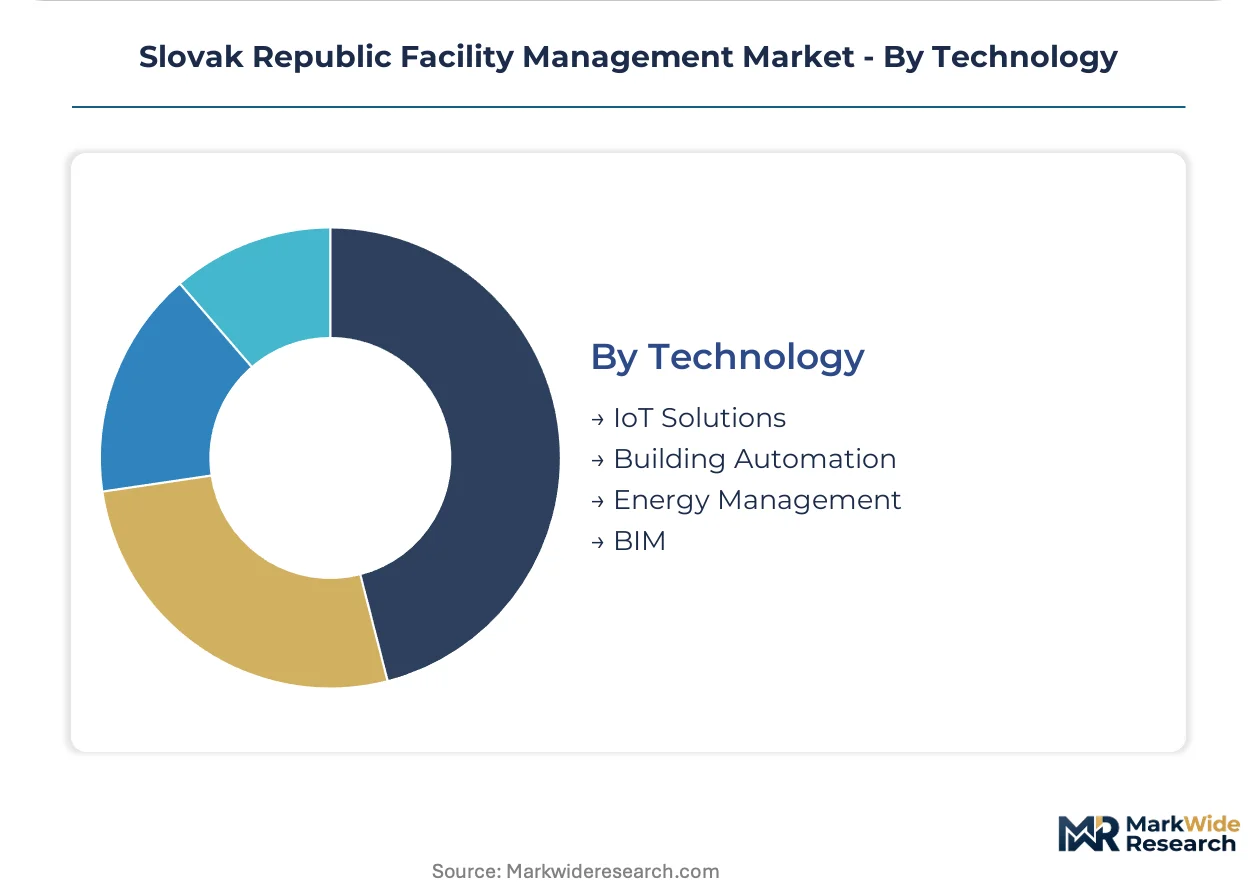
Building Automation captures the largest current deployment base; IoT Solutions are climbing the fastest as predictive maintenance resets service level benchmarks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trnava Industrial Park and Bratislava Free Trade Zone concentrate facility management demand as automotive and technology investors cluster around tax-advantaged locations. Western Slovakia's industrial corridor generates outsized contract value relative to national GDP share. EU structural funds continue channeling infrastructure investment toward the capital region and its satellite manufacturing zones.
Bratislava Region
Multinational corporate headquarters and commercial towers drive integrated service bundling across security, cleaning, and building automation. The Ministry of Transport and Construction enforces building energy certification mandates that filter uncertified providers from premium contract pools. The Petržalka business district and Eurovea Tower cluster concentrate demand for technology-enabled FM with real-time energy analytics.
Trnava Region
Automotive manufacturing campuses require 24/7 HVAC reliability and predictive maintenance systems to prevent production downtime. EU Green Deal compliance tightens building energy certification thresholds, compelling Stellantis and Volkswagen suppliers to outsource specialized facility services. The Trnava Industrial Park anchors contract consolidation toward full-service providers capable of coordinating multi-site portfolios.
Žilina Region
Kia Motors Slovakia and its supplier network generate demand for industrial maintenance services operating under ISO 50001 energy management protocols. BIS technical standards for fire safety and electrical systems create compliance layers that favor established providers over local competitors. The Žilina automotive cluster represents the northern anchor of Slovakia's manufacturing corridor.
Košice Region
U.S. Steel Košice and emerging electronics manufacturing drive demand for heavy industrial facility management and specialized maintenance services. Public procurement frameworks for regional hospitals and universities generate stable recurring revenue through long-term institutional contracts. The Košice IT Valley initiative is attracting technology sector tenants with elevated building automation requirements.
Nitra Region
Jaguar Land Rover's manufacturing presence and agricultural processing facilities create mixed demand for industrial and commercial FM services. Fragmented property ownership across smaller municipalities elevates subcontractor coordination complexity for regional providers. The Nitra agro-industrial zone remains underpenetrated by integrated service bundling relative to western regions.
Slovak Republic Facility Management Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Slovakia's facility management landscape. The market exhibits moderate consolidation around international providers with established healthcare and industrial footprints, while local operators retain share in residential and small commercial segments. Three archetypes dominate: integrated full-service platforms, technology-led asset advisors, and sector-specialized maintenance contractors. Competitive positioning hinges on M&A-driven geographic expansion and strategic partnerships with building automation technology vendors.
Within the integrated full-service tier, Sodexo Slovensko s.r.o. and ISS Facility Services s.r.o. exemplify providers leveraging healthcare and commercial footprints to sustain recurring revenue streams. CBRE Group, Inc. occupies a position among technology-led asset advisors differentiating through building automation overlays. These three anchors represent distinct competitive vectors: institutional sector depth, integrated service bundling, and technology-enabled energy advisory.
| Leading Market Players |
|---|
| CBRE Group, Inc. |
| Sodexo Slovensko s.r.o. |
| ISS Facility Services s.r.o. |
| BNP Paribas Real Estate Slovakia s.r.o. |
| Cushman & Wakefield s.r.o. |
| Apleona HSG s.r.o. |
| JLL |
| ENGIE Services a.s. |
| Reiwag Facility Services GmbH |
| Others |
Value Chain & Pricing Dynamics
Outsourced technical service networks anchor both supply positioning and pricing power in Slovak facility management, as EU Green Deal compliance requirements force automotive campuses to pay premiums for certified HVAC and building automation providers. This integration pattern concentrates margin capture among full-service operators capable of documenting carbon reduction pathways under Ministry of Transport and Construction mandates.
Pricing Analysis
Short lead-time premiums dominate contract structures, with automotive manufacturing campuses paying elevated rates for 24/7 HVAC response guarantees to prevent production downtime. Three-tier pricing structure across premium, standard, and economy levels separates ISO 50001-certified providers from uncertified local competitors, with certification tier and geographic delivery cost as primary differentiation drivers. Cost compression in standard-tier maintenance is intensifying because specialized technician scarcity limits supply elasticity. Institutional clients under public procurement frameworks exhibit highest price sensitivity, while multinational tenants in Bratislava commercial towers prioritize compliance-validated service levels over unit cost.
Supply Chain Analysis
EU domestic-content mandates for building energy certification are reshaping sourcing toward certified local technician networks and EU-registered equipment vendors. Geographic supply concentration draws from Germany, Czech Republic, and Austria for HVAC components, building automation systems, and specialized maintenance tooling. Raw material dependencies rest on copper wiring, refrigerants, and IoT sensor arrays. Single-source vulnerability runs through German building automation platform providers. Distribution runs through direct service contracts with multinational anchor tenants and public procurement frameworks for institutional clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Slovak facility management market reads as a cost-of-compliance story, where EU Green Deal building energy certification requirements create a barrier-to-entry moat that filters undercapitalized competitors and consolidates contract access toward certified providers.
For Market Incumbents: Anticipate margin pressure from technology-enabled entrants by deepening ISO 50001 certification coverage across technician workforces and securing exclusive building automation partnerships before public retrofit tender specifications solidify. Vertical integration into predictive maintenance software development represents the priority defensive lever against asset advisory competitors. For New Entrants and Emerging Players: Enter via the Nitra agro-industrial zone, where fragmented property ownership has slowed integrated service bundling penetration relative to western Slovakia. Target mid-sized automotive suppliers in the Trnava corridor with IoT-enabled energy monitoring as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to pan-European facility management conglomerates seeking Slovak healthcare and industrial footholds. Long-term viability hinges on technology-led service differentiation rather than labor arbitrage. The signal to watch is Ministry of Transport and Construction tender specification releases for public building retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 50001 Certification Expansion | Filters competitors from EU Green Deal-compliant contract pools under Ministry mandates. |
| Building Automation Partnership | Secures technology differentiation for Bratislava commercial zone multinational tenants. |
| Predictive Maintenance Platform Development | Resets service level benchmarks toward real-time fault detection across automotive campuses. |
| Public Building Retrofit Positioning | Captures multi-year revenue visibility through Ministry energy efficiency upgrade mandates. |
| Trnava Corridor Multi-Site Portfolio | Consolidates vendor relationships with Stellantis and Volkswagen supplier networks. |
Study Parameters
Document review covered EU directive filings, Slovak public procurement databases, and building energy certification registries, complemented by interviews with facility management executives, automotive plant engineering directors, Ministry of Transport and Construction officials, and building automation technology vendors. Secondary sources included BIS technical standards documentation, ISO 50001 certification records, and EU structural fund allocation reports. Bottom-up contract value aggregation and top-down market sizing triangulation validated segment-level estimates.
Market value and volume outputs across the projection horizon reflect analytical framework integration of service type, application, client type, and technology adoption maturity dimensions. CAGRs were derived from trend extrapolation of certified provider contract win rates and automotive manufacturing capacity expansion schedules. Forecast inputs incorporated EU Green Deal implementation timelines and public building retrofit pipeline announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU energy performance mandate tightening or prolonged technician labor shortages. Forecasts reflect assumptions regarding regulatory implementation pace and technology vendor partnership stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Austria Facility Management Market
Facility Management
Vietnam Facility Management Market
Facility Management
Brazil Facility Management Market
Facility Management
Iceland Facility Management Market
Facility Management
Argentina Facility Management Market
Facility Management
Japan Facility Management Market
Facility Management
India Facility Management Market
Facility Management
Germany Facility Management Market
Facility Management
Mexico Facility Management Market
Facility Management
Kuwait Facility Management Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Serbia Facility Management Market
Facility Management
GCC Facility Management Market
Facility Management
Bulgaria Facility Management Market
Facility Management
North America Hard Facility Management Market
Facility Management
Panama Facility Management Market