
 France Facility Management Market | 2026-2036
France Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
France Facility Management Market Insights
Healthcare institutions are redrawing the buyer landscape in French facility management, displacing traditional commercial real estate as the primary growth vector. Sodexo Group leverages its integrated service platform to capture multi-site hospital contracts across France's regional health agencies. VINCI Facilities anchors large infrastructure maintenance through its construction-to-services pipeline. Atalian Group differentiates via specialized cleaning protocols for clinical environments.
France Facility Management encompasses the integrated operation, maintenance, and optimization of built environments across commercial, institutional, and residential assets, incorporating HVAC systems, energy management protocols, and regulatory compliance frameworks to ensure occupant safety and operational continuity. The service type dimension shows maintenance and cleaning commanding established revenue pools while security services gain traction from terrorism preparedness mandates. Deployment patterns reveal hybrid models expanding fastest as clients blend on-site supervision with remote building analytics. Technology adoption concentrates in IoT solutions and software platforms that enable predictive maintenance and real-time energy monitoring.
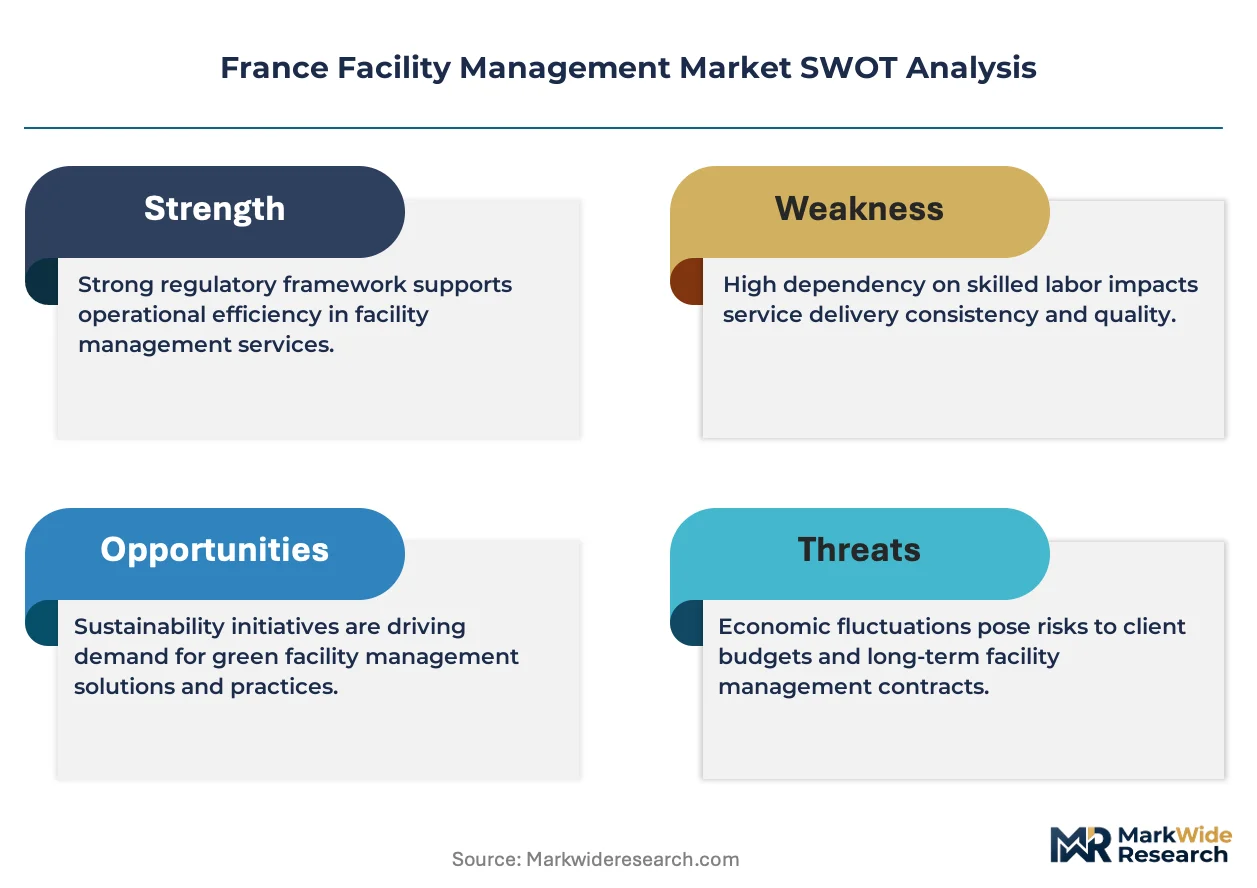
France's facility management sector operates under ANSM health facility standards, the tertiary decree enforcing progressive energy consumption reductions, and CNIL data protection requirements for smart building systems. ANSM protocols dictate infection control specifications in healthcare settings, while the tertiary decree compels commercial buildings above specific thresholds to slash energy use through retrofits and operational upgrades. Stakeholders must weigh capital allocation between compliance-driven building retrofits and technology platforms that unlock recurring efficiency gains.
Market Dynamics
France's tertiary decree on energy efficiency is compressing facility management service models, forcing building operators to merge compliance-driven retrofits with predictive maintenance platforms to avoid penalties.
Growth Catalysts
- Healthcare outsourcing:French regional health agencies are expanding multi-site service contracts for hospital maintenance and clinical cleaning protocols.
- ANSM infection control standards:These protocols mandate specialized facility protocols in healthcare settings, creating demand for certified service providers.
- IoT-enabled predictive maintenance:Sensor networks and building analytics platforms are reducing downtime for HVAC and energy systems across Ile-de-France commercial assets.
Market Restraints
- Skilled technician shortage:France's facility management sector faces acute gaps in certified HVAC and building automation specialists.
- Energy retrofit capex burden:The tertiary decree mandates substantial upfront investment for commercial buildings above 1,000 square meters.
- CNIL data compliance friction:Smart building systems must navigate strict data protection requirements for occupant monitoring and energy analytics.
Strategic Opportunities
- Paris metropolitan decarbonization:Ile-de-France's dense building stock offers concentrated demand for integrated energy retrofit and maintenance services.
- Hybrid deployment models:Clients are blending on-site supervision with remote building analytics, opening margin expansion for technology-integrated providers.
- Clinical environment specialization:ANSM-certified cleaning and maintenance protocols represent underpenetrated white space outside major hospital networks.
Industry Challenges
- Legacy system integration complexity:Older French commercial buildings require costly bridging solutions to connect analog HVAC infrastructure with IoT platforms.
- Certification timeline compression:ANSM and tertiary decree compliance deadlines are shortening procurement cycles while qualification requirements expand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Facility Management Market |
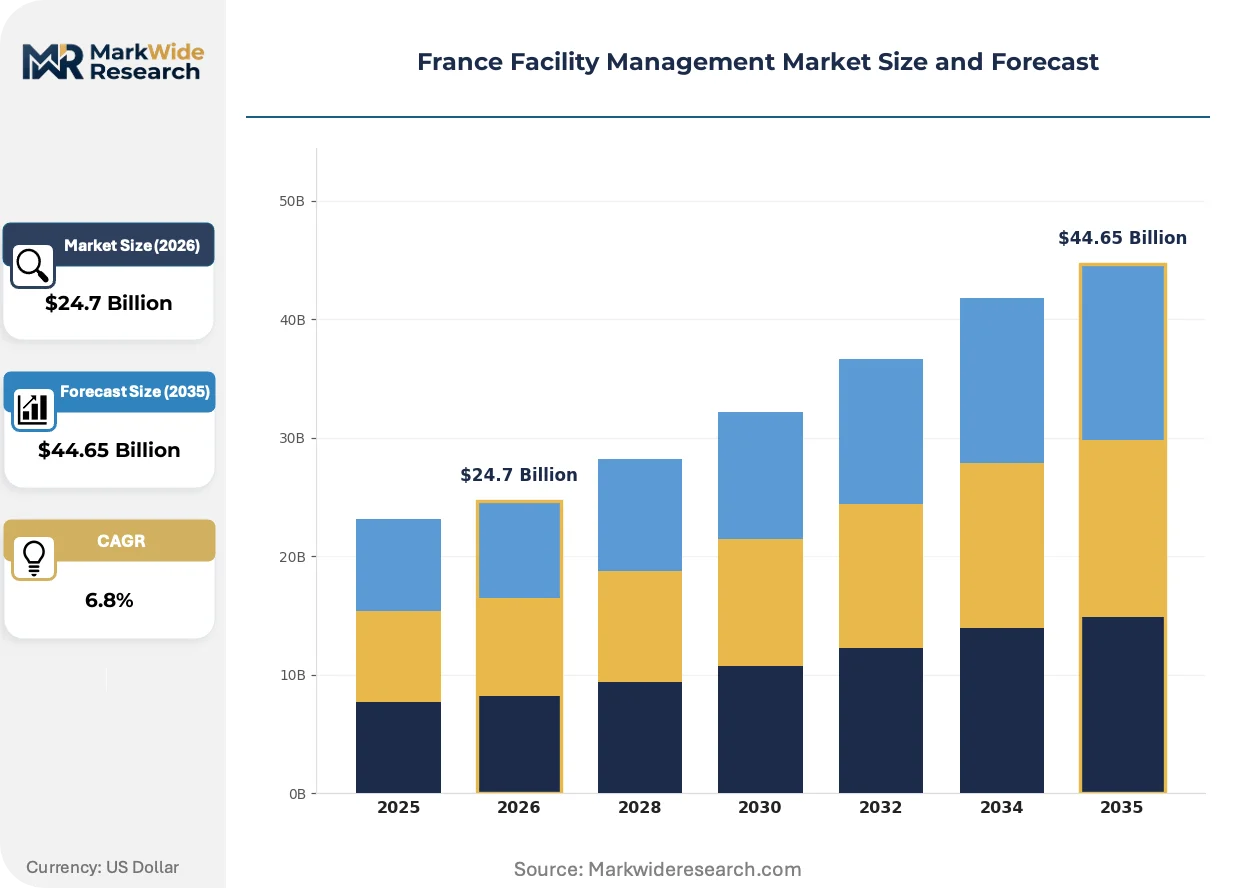
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Landscaping End User: Commercial, Educational, Healthcare, Residential Deployment: On-site, Remote, Hybrid, Outsourced Technology: IoT Solutions, Software Platforms, Automation, Cloud Services |
| Companies Covered | Sodexo Group, VINCI Facilities, Atalian Group, ONET S.A., CBRE Group Inc, Cushman & Wakefield, ISS World Services A/S, Veolia Environnement S.A., Samsic Facility, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Facility Management Market Trends and Innovations
Digital building platforms and regulatory pressure are fragmenting traditional facility management value chains, creating openings for specialized technology providers alongside established service incumbents.
IoT sensor networks are decomposing reactive maintenance models into predictive, condition-based service frameworks. Large commercial landlords in Lyon and Marseille are deploying these systems fastest. This shift is compressing margins for traditional time-and-materials contractors while rewarding analytics-integrated operators.
The tertiary decree enforces progressive energy consumption reductions through binding retrofit mandates and operational benchmarks. Commercial buildings must slash energy use via HVAC upgrades and smart controls. Property managers in Paris and Bordeaux are consolidating vendor relationships to meet compliance timelines.
Buyers are unbundling integrated service contracts into specialized component sourcing. Hospital procurement teams now separate clinical cleaning from technical maintenance and security services. This pattern is most pronounced in France's regional health agency networks, where multi-site standardization demands specialized rather than generalist providers.
France Facility Management Market Segmentation
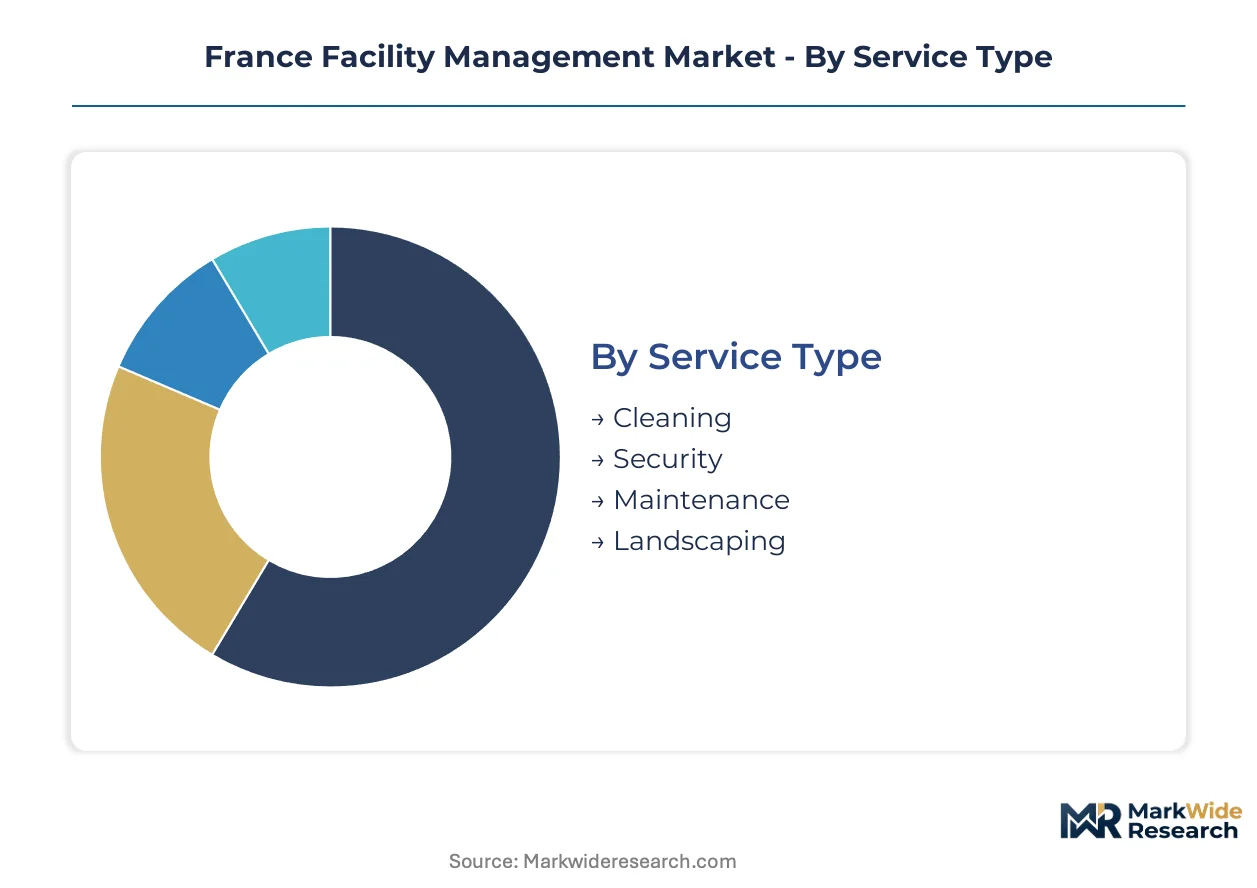
Facility management providers in France must align service portfolios with distinct operational requirements across healthcare, commercial, and institutional environments. Segment-level positioning determines contract win rates and margin sustainability in a market compressed by regulatory mandates and technology disruption.
Service Type:
Maintenance services capture the deepest margin pools due to technical certification barriers and recurring revenue structures, while security services command premium pricing from terrorism preparedness mandates.
- Cleaning:Specialized protocols for clinical environments under ANSM standards require certified staff and infection control equipment. Demand concentrates in Ile-de-France hospital networks facing expanded outsourcing mandates from regional health agencies.
- Security:Personnel-based guarding integrates with access control systems and emergency response protocols. Paris metropolitan commercial landlords are unbundling security from integrated contracts to source terrorism-certified specialists separately.
- Maintenance:HVAC, electrical, and building systems upkeep anchored by tertiary decree compliance requirements.
- Landscaping:Grounds maintenance for corporate campuses and public institutions with seasonal demand fluctuation.
The dominant share belongs to Maintenance, while Security is closing the gap fastest through regulatory-driven premiumization.
End User:
Customer-type concentration reveals healthcare procurement teams as the most sophisticated buyers, demanding outcome-based contracting and multi-site standardization.
- Healthcare:Hospitals and clinics require ANSM-certified cleaning, specialized waste management, and 24/7 technical maintenance. Regional health agencies in Lyon and Marseille are consolidating vendor relationships to reduce procurement fragmentation.
- Commercial:Office buildings and retail centers prioritize energy efficiency retrofits to meet tertiary decree benchmarks. Paris property managers are bundling HVAC upgrades with long-term maintenance agreements.
- Educational:Universities and public schools need seasonal flexibility and safety compliance for student populations.
- Residential:Multi-unit housing associations seek cost-controlled basic services with limited technology integration.
Healthcare commands the steepest expansion trajectory, while Commercial retains the largest contract value base.
Deployment:
Hybrid models are gaining share fastest as clients balance on-site accountability with remote monitoring economics.
- Hybrid:Combines physical supervision with cloud-based building analytics and predictive maintenance platforms. Bordeaux and Nantes commercial landlords are adopting this model to reduce headcount while maintaining service levels.
- On-site:Dedicated staff embedded at single locations for high-security or complex operational environments. Healthcare facilities in Ile-de-France maintain on-site technical teams for critical infrastructure.
- Remote:Centralized monitoring of multiple assets through IoT sensors and digital twins.
- Outsourced:Full facility operations transferred to third-party providers under multi-year agreements.
On-site deployment still holds the majority position, though Hybrid is climbing the fastest as technology integration matures.
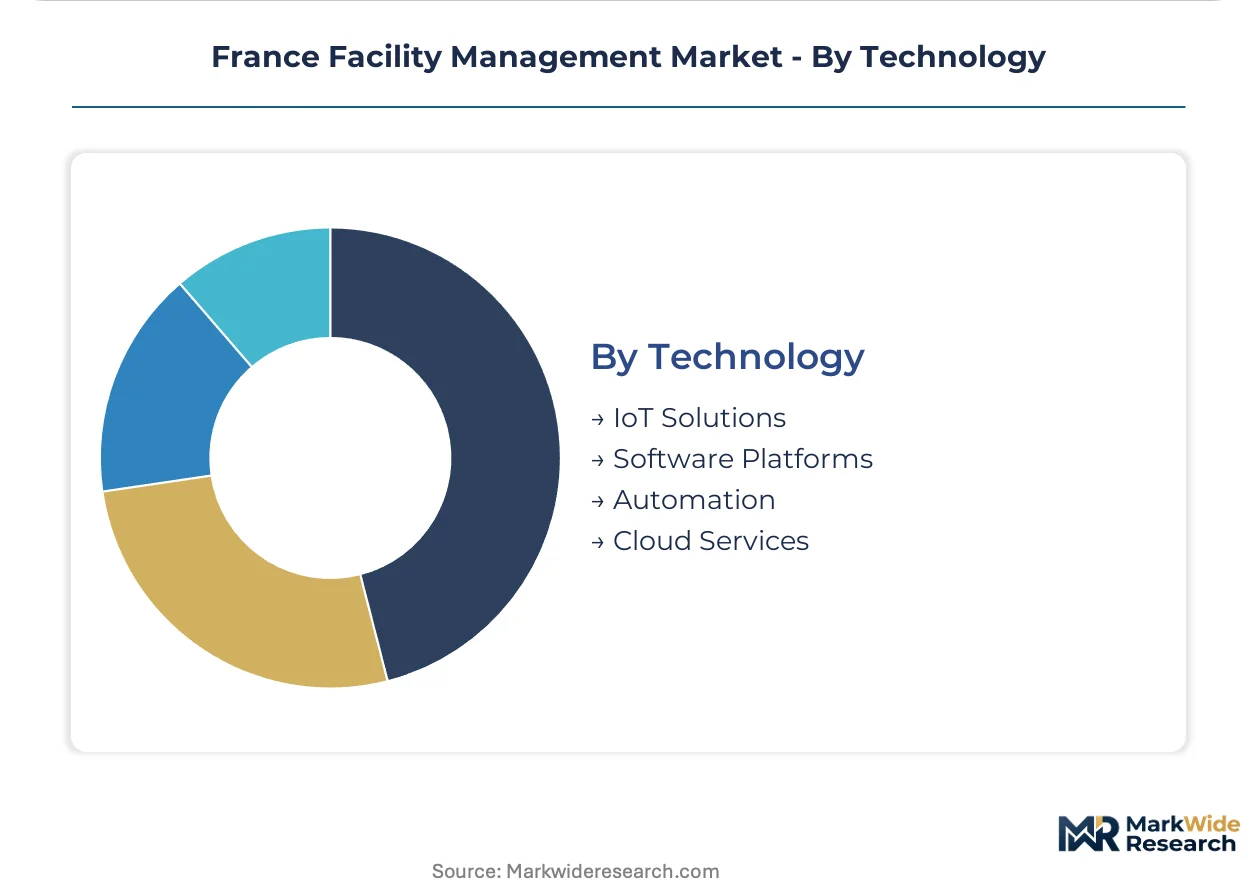
Technology:
Software platforms concentrate vendor margin through recurring licensing and data monetization, while IoT solutions require heavy upfront integration investment.
- IoT Solutions:Sensor networks for HVAC performance, energy consumption, and occupancy monitoring. Lyon commercial real estate investors are deploying these systems to satisfy tertiary decree reporting requirements.
- Software Platforms:Integrated work order management, asset tracking, and compliance documentation systems. Healthcare procurement teams in regional hospital networks are mandating platform interoperability for multi-site contracts.
- Automation:Robotic cleaning systems and automated building controls reducing labor dependency.
- Cloud Services:Data storage and analytics infrastructure enabling remote facility oversight.
Software Platforms dominate technology spending, while IoT Solutions are gaining share fastest through retrofit mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France exports facility management expertise through cross-border service contracts into Belgium, Luxembourg, and Switzerland, with Paris-based operators establishing satellite offices in Geneva and Brussels to capture neighboring healthcare and commercial real estate mandates.
Île-de-France
Paris metropolitan hospitals drive outsourced clinical cleaning contracts under ANSM infection protocols. The tertiary decree enforces energy retrofits on commercial buildings exceeding regulatory thresholds. La Défense business district property managers consolidate multi-site vendor relationships to meet compliance deadlines.
Auvergne-Rhône-Alpes
Lyon's regional health agencies expand multi-site facility management tenders for hospital networks. CNIL data protection requirements shape smart building procurement specifications. Grenoble's technology corridor attracts predictive maintenance providers serving semiconductor cleanroom facilities.
Provence-Alpes-Côte d'Azur
Marseille port infrastructure generates maritime facility maintenance demand alongside healthcare outsourcing. The tertiary decree applies to cruise terminal and logistics buildings above size thresholds. Nice's hospitality sector drives seasonal landscaping and security service contracts.
Hauts-de-France
Lille's logistics hubs concentrate warehouse facility management for e-commerce distribution networks. The tertiary decree mandates energy efficiency upgrades on cold storage facilities. Calais port authorities issue specialized maintenance contracts for border inspection infrastructure.
Nouvelle-Aquitaine
Bordeaux commercial landlords adopt hybrid deployment models blending on-site supervision with remote building analytics. The tertiary decree accelerates HVAC retrofit timelines for historic building stock. Biotech clusters in the region demand ANSM-certified laboratory maintenance protocols.
France Facility Management Market Competitive Landscape
Listed leaders compete with private specialists across service integration depth, with publicly traded operators leveraging capital markets for platform acquisitions while family-owned specialists retain clinical niche dominance. The market structure shows moderate consolidation at the top tier with fragmentation across specialized cleaning and security sub-segments. Three archetypes define positioning: integrated service platforms, construction-to-services pipeline operators, and certified clinical environment specialists. Dominant competitive moves include M&A-driven geographic expansion and technology platform licensing to capture hybrid deployment contracts.
Within the integrated platform tier, Sodexo Group and VINCI Facilities exemplify scale-driven service bundling across healthcare and infrastructure verticals. Atalian Group occupies a specialist position emphasizing certified protocols for clinical environments. These three anchors represent distinct strategic postures—Sodexo Group through multi-site standardization capabilities, VINCI Facilities through construction-backed maintenance pipelines, and Atalian Group through regulatory-certified niche penetration—while smaller operators compete on regional density and single-service excellence.
| Leading Market Players |
|---|
| Sodexo Group |
| VINCI Facilities |
| Atalian Group |
| ONET S.A. |
| CBRE Group Inc |
| Cushman & Wakefield |
| ISS World Services A/S |
| Veolia Environnement S.A. |
| Samsic Facility |
| Others |
Pricing and Supply Chain Analysis
Sensor-to-cloud platform substitution for legacy time-and-materials contracts simultaneously redraws supply geography toward Lyon and Grenoble technology clusters while compressing pricing economics for undifferentiated maintenance providers.
Pricing Analysis
Current-generation IoT-integrated service contracts command substantial premiums over prior-generation reactive maintenance and next-generation autonomous building systems. Pricing stratifies across premium, standard, and economy tiers based on ANSM certification grade and multi-site volume scale. Pricing pressure stems from tertiary decree compliance deadlines forcing rapid vendor consolidation. Regional health agencies exhibit lowest price sensitivity due to outcome-based contracting mandates, while residential housing associations drive hardest bargain negotiations.
Supply Chain Analysis
Inbound logistics costs through Marseille-Fos port congestion and container availability constraints on Asia-Europe trade lanes elevate lead times for HVAC components and sensor hardware. Supply concentrates in Germany, Italy, and Spain for mechanical systems, with China and South Korea anchoring IoT sensor production. Raw material dependencies span copper cabling, refrigerant gases, and lithium-ion backup power units. Single-source vulnerability pervades specialized clinical cleaning chemicals. Distribution runs through regional logistics hubs in Lyon and Lille serving Ile-de-France demand centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates specialized entry points as healthcare procurement teams unbundle integrated contracts into component-specific sourcing, fragmenting vendor relationships across cleaning, maintenance, and security layers.
For Market Incumbents: Shield multi-site hospital contracts through ANSM certification depth and predictive maintenance platform integration. Acquire regional specialists in clinical cleaning to preempt emerging platform competitors. Cement Lyon and Marseille footholds before tertiary decree retrofit peaks. For New Entrants and Emerging Players: Mid-tier commercial building automation gaps in Bordeaux and Nantes offer the most penetrable white space, as incumbents over-serve Paris and under-serve secondary metros. Target hybrid deployment contracts blending on-site supervision with remote analytics. Pursue direct sales to property managers bypassing integrated facility management gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional cleaning specialists holding ANSM certifications but lacking technology platforms. Five-to-ten year viability hinges on tertiary decree enforcement continuity and IoT integration capex cycles. Monitor Ile-de-France regional health agency tender unbundling velocity as inflection signal for specialist provider valuations.| Strategic Initiative | Industry Significance |
|---|---|
| ANSM Certification Investment | Unlocks hospital network contracts under regional health agency standardization mandates. |
| Predictive Maintenance Platform Launch | Captures tertiary decree compliance budgets through IoT-enabled energy retrofit bundling. |
| Geographic Expansion to Secondary Metros | Establishes Bordeaux and Nantes density before incumbent platform rollout accelerates. |
| Clinical Cleaning Specialist Acquisition | Consolidates fragmented ANSM-certified providers into multi-site service capabilities. |
| Hybrid Deployment Model Rollout | Blends on-site accountability with remote monitoring economics for margin expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with regional health agency procurement directors, hospital facility managers, commercial property asset managers, and ANSM compliance officers. Secondary validation drew from tertiary decree regulatory filings, CNIL data protection guidance, regional health agency tender databases, and French building energy performance audit records. Bottom-up contract value estimates triangulated against top-down sector spending benchmarks.
Across the analysis window, forecasts modeled service type, end user vertical, deployment architecture, and technology adoption segmentation dimensions. CAGRs derived from historical contract value trajectories adjusted for regulatory enforcement intensity and technology penetration curves. Energy retrofit capex cycles and healthcare outsourcing velocity served as primary forecast inputs.
Forecasts assume regulatory continuity in ANSM infection control standards and tertiary decree enforcement; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Mexico Facility Management Market
Facility Management
Poland Facility Management Market
Facility Management
North America Facilities Management Market
Facility Management
Czech Republic Facility Management Market
Facility Management
India Facility Management Market
Facility Management
Hong Kong Facility Management Market
Facility Management
United Arab Emirates Facility Management Market
Facility Management
Oman Facility Management Market
Facility Management
Ireland Facility Management Market
Facility Management
Latin America Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Soft Facility Management Market
Facility Management
North America Soft Facility Management Market
Facility Management
Greece Facility Management Market
Facility Management
Indonesia Facility Management Market
Facility Management
Europe Hard Facility Management Market