
 Qatar Facility Management Market | 2026-2036
Qatar Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Facility Management Market Analytics
Direct procurement channels between property developers and integrated FM providers is reshaping competitive dynamics in Qatar. Engie Cofely Mannai Facility Management leverages its energy-services heritage to dominate hard FM and energy management contracts. Sodexo Qatar Services anchors the soft FM segment through institutional catering and workplace services. Al Faisal Holdings (MMG Qatar) competes across total facilities management with real estate-backed vertical capabilities.
Facility management encompasses the integrated coordination of building maintenance, operations, security, cleaning, and energy systems to ensure functional, safe, and efficient built environments, typically governed by service-level agreements specifying response times, uptime thresholds, and compliance benchmarks. Its primary commercial purpose is to preserve asset value and reduce lifecycle costs for property owners and occupiers. Hard facilities management leads value generation due to capital-intensive MEP maintenance and regulatory compliance burdens, while green facilities management represents the fastest-expanding offering category as Qatar enforces sustainability mandates across new developments. Integrated Workplace Management Systems within the technology dimension capture disproportionate investment as portfolio operators digitize asset tracking and preventive maintenance scheduling.
Qatar's Ministry of Municipality and Environment enforces building codes and sustainability standards that elevate FM service specifications, while the Qatar General Organization for Standardization (QS) develops technical benchmarks for fire safety, energy efficiency, and indoor air quality that filter into contract tenders. These frameworks compel providers to certify technicians, adopt digital compliance reporting, and maintain spare-part inventories that meet local content expectations. Stakeholders must monitor how upcoming carbon-neutrality deadlines for the 2030 National Vision recalibrate green FM procurement weights and technician retraining obligations.
Market Dynamics
Qatar's mandatory green building standards under QSAS are compressing procurement cycles and forcing FM providers to retrain technicians and retool service portfolios around energy auditing and indoor air quality compliance.
Growth Catalysts
- QSAS Tier Certification:The Qatar Sustainability Assessment System mandates minimum two-star ratings for new commercial developments, creating binding demand for green FM audits and MEP optimization services.
- Stadium-to-Commercial Asset Conversion:Post-event hospitality infrastructure from FIFA 2022 is transitioning to permanent mixed-use developments requiring integrated hard and soft FM contracts.
- Digital Twin Deployment:Lusail Smart City operators are mandating BIM-integrated asset management platforms that enable predictive maintenance scheduling across building portfolios.
Market Restraints
- Specialized Labor Scarcity:Qatar's kafala sponsorship system constrains mobility of certified MEP technicians, inflating wage premiums for LEED-accredited and fire-safety-licensed personnel.
- Import Dependency for Spare Parts:Critical HVAC and building automation components ship from Germany, Japan, and South Korea, exposing operators to container freight volatility and customs clearance delays.
- Stringent Local Content Quotas:Qatar General Organization for Standardization procurement guidelines mandate 30% domestic value-add in service contracts, complicating technology transfers from foreign FM platforms.
Strategic Opportunities
- Al Wakrah Industrial Zone Expansion:The southern logistics corridor is attracting cold-chain and pharmaceutical warehousing that requires GMP-compliant environmental monitoring and specialized cleaning protocols.
- Convergence of IoT Sensors and AI Diagnostics:Edge computing deployments in Doha's West Bay towers enable real-time fault detection that reduces emergency call-out frequency and extends equipment lifecycles.
- 2030 National Vision Carbon Neutrality Deadlines:Upcoming net-zero commitments for government buildings will mandate deep energy retrofits, creating multi-year performance contracting vehicles for ESCO-FM hybrids.
Industry Challenges
- BIM Technician Certification Bottlenecks:Qatar has only three accredited training centers for building information modeling integration, creating 18-month backlogs for FM firms seeking qualified digital asset managers.
- Legacy System Interoperability:Doha's 1990s-era commercial stock runs on proprietary building automation protocols that resist integration with modern IWMS platforms without expensive gateway hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Facility Management Market |
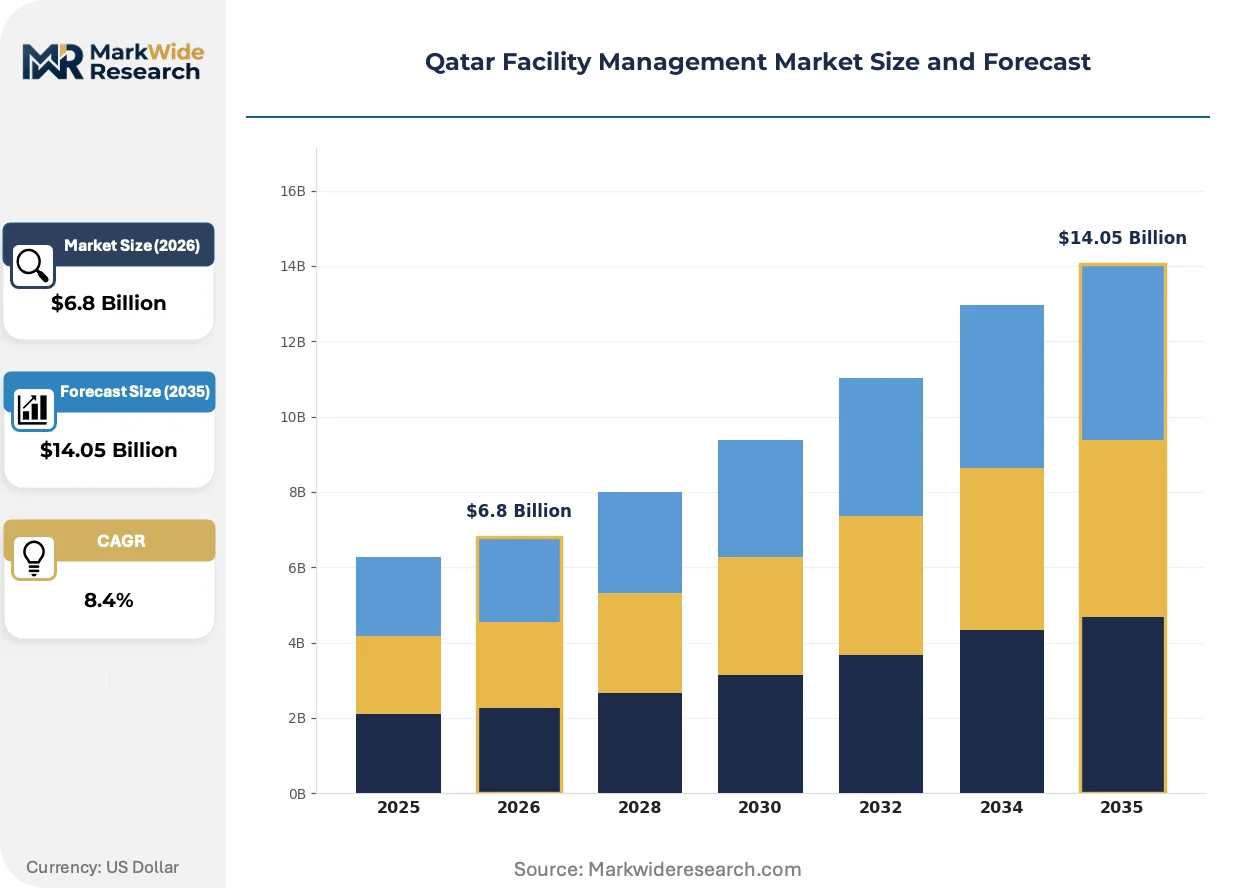
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Security Services, Maintenance Services, Landscaping Services End User: Commercial Properties, Residential Complexes, Educational Institutions, Healthcare Facilities Technology: Integrated Workplace Management Systems, IoT Solutions, Energy Management Systems, Building Automation Offering: Soft Facilities Management, Hard Facilities Management, Green Facilities Management, Total Facilities Management |
| Companies Covered | G4S Qatar, Engie Cofely Mannai Facility Management, Al Faisal Holdings (MMG Qatar), Amenity Facility Management & Services WLL, Como Facility Management Services, Sodexo Qatar Services, EFS Facilities Services, Facilities Management & Maintenance Company LLC, Al-Asmakh Facilities Management, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Facility Management Market Evolving Landscape
Technology migration, regulatory tightening, and buyer behavior shifts are restructuring how FM services are specified, priced, and delivered across Qatar's built environment.
Integrated Workplace Management Systems are migrating from standalone preventive maintenance schedulers to AI-augmented platforms that ingest IoT sensor streams and automate work-order generation. Lusail Development Authority and Msheireb Properties are piloting these systems across their portfolios, compressing mean-time-to-repair metrics and enabling outcome-based contract structures that tie vendor payments to uptime guarantees rather than labor hours.
Qatar's Ministry of Municipality and Environment is tightening enforcement of fire safety and indoor air quality standards through unannounced inspections and digital compliance reporting mandates. The Qatar Civil Defence Department now requires real-time connectivity between fire suppression systems and central monitoring stations, forcing FM providers to upgrade legacy alarm infrastructure or risk contract termination. High-rise residential towers in The Pearl-Qatar and West Bay face the steepest compliance costs due to retrofit complexity.
Buyers are consolidating vendor relationships from fragmented single-service contracts to integrated FM partnerships that bundle hard services, soft services, and energy management under single accountability. Qatar Investment Authority-backed property funds are leading this consolidation, using total cost of ownership modeling that captures hidden coordination costs between multiple subcontractors. The shift is most visible in Doha's Msheireb Downtown district, where master developers specify sole-source FM providers for 10-year terms.
Qatar Facility Management Market Segmentation
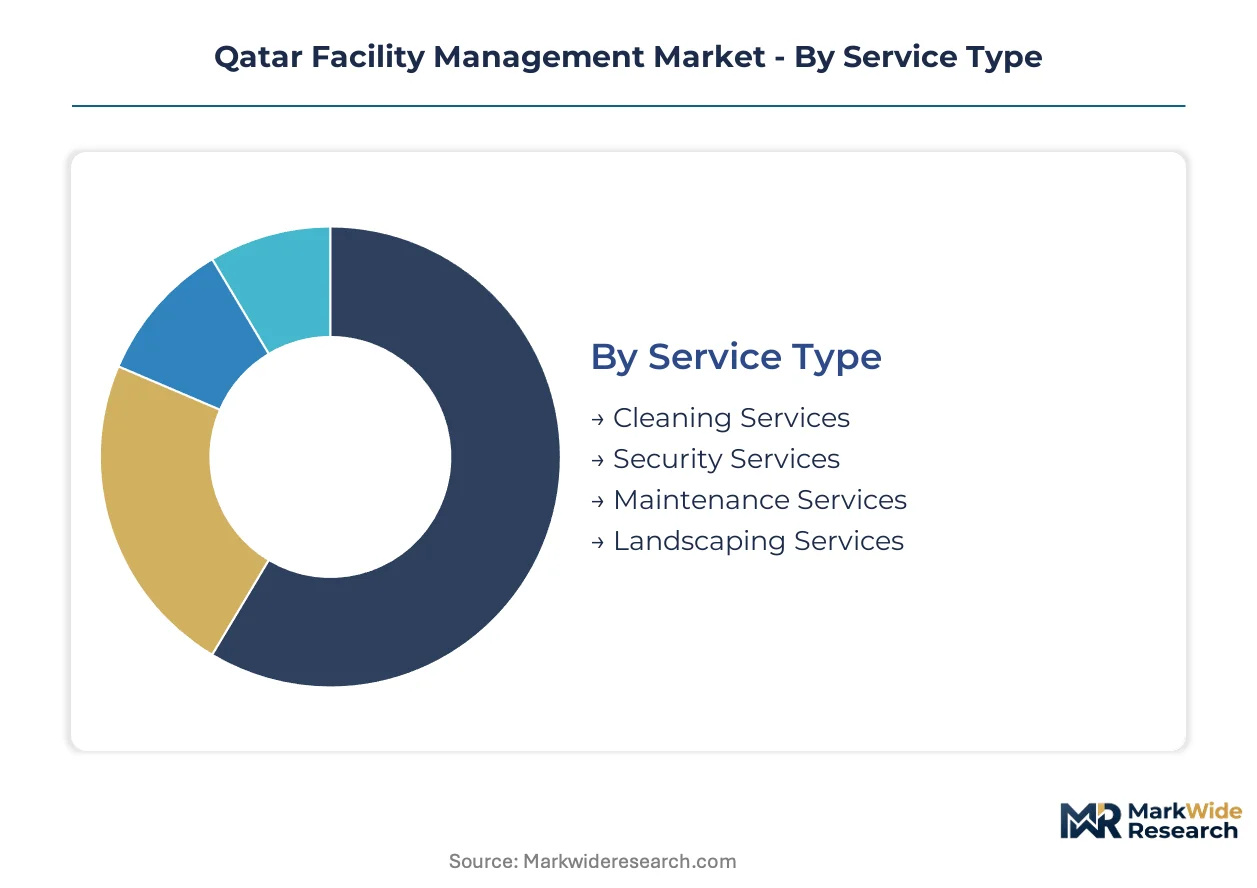
Segmentation in Qatar's facility management market reveals how procurement specifications diverge across asset classes and compliance mandates. Service intensity, technology integration depth, and sustainability certification requirements reshape vendor selection criteria for each cluster.
Service Type:
After-sales service intensity varies sharply across service categories, with MEP-dependent segments demanding 24/7 response capabilities and spare-part localization that inflates operational overhead.
- Maintenance Services:Encompasses mechanical, electrical, and plumbing systems preservation alongside HVAC calibration and fire suppression upkeep. Demand concentrates in Lusail's commercial towers where QSAS energy mandates require continuous MEP optimization and predictive thermal auditing.
- Security Services:Covers access control, surveillance infrastructure, manned guarding, and perimeter monitoring for critical facilities. West Bay financial district and The Pearl-Qatar residential enclaves drive adoption of integrated command centers with Civil Defence Department real-time connectivity requirements.
- Cleaning Services:Includes janitorial operations, specialized healthcare sanitation, and facade maintenance for high-rise portfolios.
- Landscaping Services:Encompasses irrigation management, xeriscaping for water conservation compliance, and outdoor amenity upkeep in hospitality and residential developments.
Maintenance Services holds the largest share; momentum sits with Security Services as regulatory mandates tighten around fire safety and access control digitization.
End User:
Cost tier stratification across end-user categories determines contract value bands, with healthcare and commercial assets commanding premium pricing for compliance-critical service levels.
- Commercial Properties:Encompasses office towers, retail centers, and mixed-use developments requiring integrated hard and soft FM bundles. Msheireb Downtown Doha and Lusail Marina District anchor demand for sole-source 10-year FM partnerships with uptime-guarantee pricing structures.
- Healthcare Facilities:Covers hospitals, clinics, and medical office buildings demanding infection control protocols and specialized waste management. Hamad Medical Corporation facilities and private hospital expansions in Al Wakra drive GMP-compliant environmental monitoring and emergency power system maintenance requirements.
- Residential Complexes:Includes high-rise towers, gated communities, and serviced apartments with varying amenity intensities.
- Educational Institutions:Encompasses K-12 schools, universities, and vocational training centers with seasonal occupancy patterns and specialized laboratory maintenance needs.
Commercial Properties commands the dominant revenue position; Healthcare Facilities is climbing fastest as Qatar's medical infrastructure expansion accelerates post-2022.
Technology:
Application maturity across technology segments separates pilot-stage deployments from scaled implementations, with BIM-integrated platforms still concentrated in greenfield developments.
- Integrated Workplace Management Systems:Unifies asset registries, work-order dispatch, and vendor performance dashboards under single platforms. Lusail Smart City operators and Msheireb Properties mandate these systems for predictive maintenance scheduling and outcome-based vendor payments tied to equipment uptime metrics.
- IoT Solutions:Deploys sensor networks for real-time environmental monitoring, occupancy detection, and energy consumption tracking. West Bay tower portfolios pilot edge-computing fault detection that compresses mean-time-to-repair and extends HVAC equipment lifecycles through automated diagnostic alerts.
- Energy Management Systems:Enables metering infrastructure, demand response coordination, and carbon reporting for QSAS compliance.
- Building Automation:Integrates HVAC, lighting, and security controls through centralized building management protocols.
Integrated Workplace Management Systems captures the largest technology investment; IoT Solutions is expanding most quickly as sensor deployment costs decline and AI diagnostic capabilities mature.
Offering:
Customer type preferences bifurcate between institutional buyers seeking single-accountability partnerships and fragmented ownership structures tolerating multi-vendor arrangements.
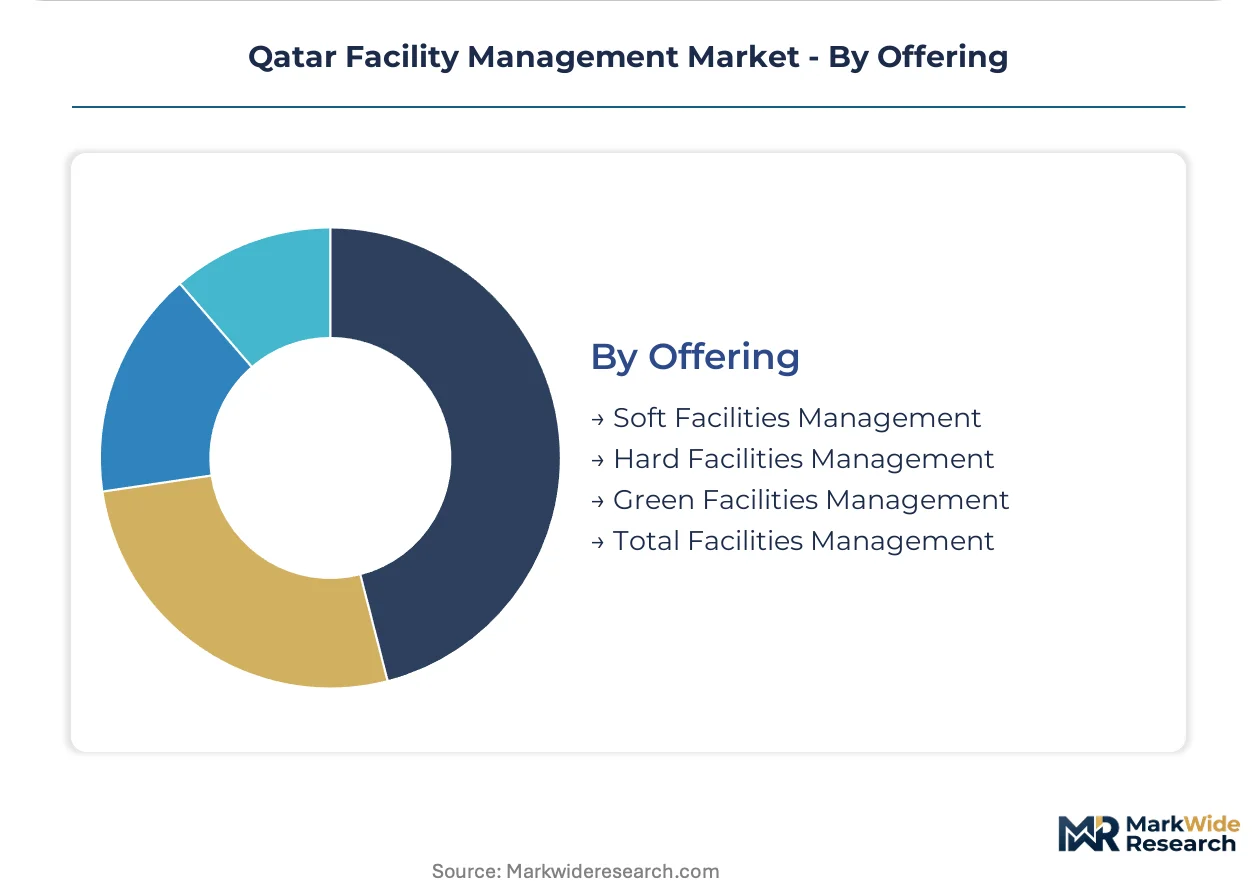
- Hard Facilities Management:Delivers MEP maintenance, structural repairs, fire safety system upkeep, and building fabric preservation. Qatar Investment Authority-backed property funds consolidate procurement here, valuing capital-intensive technical capabilities and regulatory compliance burdens that preserve asset values across 20-year holding periods.
- Green Facilities Management:Provides energy auditing, indoor air quality certification, water efficiency optimization, and QSAS compliance documentation. Mandatory two-star QSAS ratings for new commercial developments create binding demand as 2030 National Vision carbon neutrality deadlines approach for government building portfolios.
- Soft Facilities Management:Encompasses cleaning, catering, security, and workplace concierge services.
- Total Facilities Management:Bundles hard services, soft services, and energy management under single-provider accountability with TCO-modeled pricing.
Hard Facilities Management retains the dominant share; Green Facilities Management shows the steepest expansion trajectory as sustainability mandates reshape procurement weights and technician retraining obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's Ministry of Municipality and Environment anchors regulatory oversight across the peninsula, with the Qatar General Organization for Standardization setting technical benchmarks that cascade into municipal procurement specifications.
Doha
The capital concentrates commercial tower stock and government building portfolios demanding integrated hard FM contracts. Qatar Civil Defence Department mandates real-time fire suppression connectivity here. West Bay financial district and Msheireb Downtown drive sole-source FM partnerships with 10-year uptime-guarantee structures.
Lusail
This smart city development mandates BIM-integrated asset management platforms for predictive maintenance scheduling. Lusail Development Authority requires IoT sensor deployment across commercial and residential clusters. The Marina District anchors demand for outcome-based vendor payments tied to equipment performance metrics.
Al Wakrah
The southern logistics corridor attracts cold-chain and pharmaceutical warehousing requiring GMP-compliant environmental monitoring. Hamad Medical Corporation facility expansions here drive specialized infection control protocols. Industrial zone operators seek FM providers with certified hazardous waste handling capabilities.
The Pearl-Qatar
This artificial island development houses high-rise residential towers facing steep fire safety retrofit costs. Qatar Civil Defence Department inspections target legacy alarm infrastructure upgrades here. Luxury residential enclaves demand integrated security and concierge services under single-provider accountability.
Al Khor and Northern Regions
Industrial city expansions and energy sector facilities dominate FM demand outside the capital corridor. Ras Laffan industrial zone operators require MEP maintenance for process-critical infrastructure. Northern development corridors are attracting logistics warehousing with specialized environmental monitoring needs.
Qatar Facility Management Market Competitive Landscape
Energy-services heritage and real estate-backed vertical capabilities split the market between technical specialists and integrated platform operators. The vendor base organizes around three strategic archetypes: hard FM technical specialists with MEP certification depth, soft FM operators anchoring workplace and hospitality services, and total FM platforms bundling accountability under single-contract structures. M&A activity concentrates on acquiring LEED-accredited technician teams, while strategic partnerships with IWMS technology vendors reshape service delivery capabilities.
Within the energy-services tier, Engie Cofely Mannai Facility Management exemplifies the hard FM specialist archetype through its technical heritage in MEP optimization and regulatory compliance. Sodexo Qatar Services occupies the soft FM anchor position, representing workplace and institutional service capabilities. Al Faisal Holdings (MMG Qatar) sits within the total FM integration tier, exemplifying real estate-backed vertical service bundling across Doha and Lusail developments.
| Leading Market Players |
|---|
| G4S Qatar |
| Engie Cofely Mannai Facility Management |
| Al Faisal Holdings (MMG Qatar) |
| Amenity Facility Management & Services WLL |
| Como Facility Management Services |
| Sodexo Qatar Services |
| EFS Facilities Services |
| Facilities Management & Maintenance Company LLC |
| Al-Asmakh Facilities Management |
| Others |
Value Network & Pricing Analysis
Container freight volatility for German HVAC components and Japanese building automation systems determines both tier spreads between integrated sole-source contracts and fragmented multi-vendor arrangements and the geographic shape of spare-part inventory positioning across Doha and Lusail.
Pricing Analysis
The customization-premium spread separates configured QSAS-compliant energy auditing packages from standard preventive maintenance schedules. Contract structures stratify across premium-tier sole-source 10-year partnerships with uptime guarantees, standard multi-service bundles, and economy spot-purchase cleaning and security. Pricing pressure stems from Qatar General Organization for Standardization local content quotas forcing domestic value-add investments. Government-backed property funds show lowest price sensitivity; small residential developers in The Pearl-Qatar exhibit highest.
Supply Chain Analysis
Export-control regimes on advanced building automation semiconductors from South Korea and precision HVAC components from Germany constrain technology transfer flows into Qatar. Critical inputs draw from Japan for fire suppression systems, South Korea for IoT sensors, and Germany for energy management controllers. Single-source vulnerability concentrates in proprietary BACnet protocol gateways essential for legacy system integration. Distribution runs through Doha-based authorized dealer networks with Ministry of Municipality and Environment certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's facility management market demands substitution defense against in-house captive FM operations by large property developers seeking direct control over critical MEP assets.
For Market Incumbents: Harden technician certification pipelines through Qatar's three accredited BIM training centers to compress 18-month qualification backlogs. Deepen backward integration into spare-part warehousing within Doha free zones to offset container freight exposure. The priority threat is developer vertical integration; the counter-lever is regulatory compliance depth that captive operations cannot replicate.
For New Entrants and Emerging Players: Al Wakrah industrial zone cold-chain facilities represent the most penetrable entry point, with GMP-compliant environmental monitoring demand outpacing certified provider supply. Pharmaceutical warehousing operators seek specialized FM partners with hazardous waste credentials absent from incumbent portfolios. Go-to-market positioning should anchor on certified technician teams rather than asset-light platform plays.
For Investors and Strategic Acquirers: The 2030 National Vision carbon neutrality deadline for government buildings reshapes the acquisition landscape toward ESCO-FM hybrids with performance contracting capabilities. Long-term viability centers on providers with deep energy retrofit execution track records. Acquisition targets should show LEED-accredited technician density above market median. The signal to watch is Ministry of Municipality and Environment procurement weight shifts toward green FM scoring.
| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Pipeline Investment | Qatar's three BIM training centers create 18-month bottlenecks that certified providers exploit. |
| Spare-Part Localization Warehousing | Doha free zone inventory positions reduce German and Japanese component lead-time exposure. |
| QSAS Compliance Documentation Capability | Mandatory two-star ratings for commercial developments bind procurement to green FM specialists. |
| IoT-Integrated Predictive Maintenance Platform | Lusail Smart City mandates edge-computing fault detection for outcome-based vendor payments. |
| ESCO-FM Hybrid Performance Contracting | 2030 carbon neutrality deadlines for government buildings create multi-year retrofit vehicles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across Qatar's facility management ecosystem, including FM procurement directors at Qatar Investment Authority-backed property funds, technical directors at MEP maintenance firms, QSAS certification auditors, and Lusail Development Authority asset managers. Secondary validation drew from Ministry of Municipality and Environment building code filings, Qatar General Organization for Standardization technical benchmarks, Qatar Civil Defence Department compliance databases, and customs records for HVAC and automation component imports. Bottom-up contract value aggregation and top-down market sizing triangulated volume estimates.
Calibration against historical contract award data and announced FM partnership tenors anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type intensity, technology integration depth, sustainability certification tier, and regional development cluster. CAGRs derived from fitted trend analysis of procurement volume growth and QSAS mandate phase-in schedules. Industry-specific forecast inputs incorporated Lusail Smart City build-out timelines and FIFA 2022 stadium conversion pipelines.
Practitioners should monitor QSAS tier requirement escalations, kafala system reforms affecting technician mobility, and container freight rate volatility for early signals of forecast deviation. Forecasts reflect assumptions around regulatory enforcement continuity and greenfield development pacing. Material shifts in Qatar's carbon neutrality implementation timeline or Ministry of Municipality and Environment inspection intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Denmark Facility Management Market
Facility Management
Portugal Facility Management Market
Facility Management
Middle East and Africa Facility Management Market
Facility Management
Soft Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
South Africa Facility Management Market
Facility Management
Hungary Facility Management Market
Facility Management
New Zealand Facility Management Market
Facility Management
Luxembourg Facility Management Market
Facility Management
Global Facility Management Software Market
Facility Management
Lithuania Facility Management Market
Facility Management
Oman Facility Management Market
Facility Management
Argentina Facility Management Market
Facility Management
Malta Facility Management Market
Facility Management
Switzerland Facility Management Market
Facility Management
India Facility Management Market