
 Soft Facility Management Market | 2026-2036
Soft Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Facility Management Market Analytics
Outsourced-to-integrated service migration is decoupling legacy single-vendor relationships from multi-service platform arrangements. Sodexo leverages its food-and-facilities convergence to anchor healthcare and education accounts across France and North America. ISS A/S sustains geographic density in Northern Europe through cleaning and security bundling. CBRE Group Inc. competes on property management integration, extending workplace experience services into corporate client portfolios.
Soft Facility Management encompasses non-structural building services including cleaning, security, landscaping, and waste management, typically delivered under service-level agreements with defined response times and compliance metrics rather than capital-intensive infrastructure modification. Its primary purpose is sustaining occupant productivity, regulatory compliance, and asset lifecycle performance in commercial and institutional environments. Cleaning Services dominates contract value due to daily recurrence and labor intensity, while Security Services captures premium pricing through technology-augmented guarding and access control integration. Healthcare Facilities represents the fastest-growing end-user segment as patient-safety protocols and infection-control standards tighten procurement requirements. Integrated Services models are gaining share against pure outsourcing as clients seek single-accountability structures for cost and risk consolidation.
OSHA workplace safety standards and EPA chemical handling regulations in the United States shape vendor qualification and training mandates, while REACH and the EU Green Deal in Europe restrict cleaning agent compositions and mandate carbon disclosure in service procurement. India's BIS cleanliness standards and building code enforcement are elevating formal vendor participation against informal operators. Stakeholders must monitor how regulatory fragmentation across jurisdictions affects cross-border contract standardization and technology platform deployment.
Market Dynamics
The migration from single-service outsourcing to integrated facility platforms is compressing vendor relationships and reshaping procurement architectures across commercial and institutional real estate.
Growth Catalysts
- EU Green Deal carbon disclosure mandates:Procurement specifications now require documented emissions tracking for cleaning and waste management contracts, elevating formal vendors with certified environmental management systems.
- Healthcare infection-control protocols:Patient-safety standards in hospitals and long-term care facilities are tightening service-level requirements and extending contract durations for qualified facility operators.
- Technology-augmented guarding:Security services integrating AI-powered surveillance and access control systems command premium pricing and anchor multi-service platform renewals.
Market Restraints
- Labor cost volatility:Cleaning and security services remain wage-intensive, with minimum wage escalations in Germany and the United States compressing operating margins for fixed-price contracts.
- Informal operator competition:Unregistered vendors in India and Southeast Asia undercut formal pricing on non-technical services, limiting market share capture despite BIS cleanliness standard enforcement.
- REACH chemical restrictions:Cleaning agent reformulation requirements increase compliance costs and reduce product substitution flexibility for European contract operators.
Strategic Opportunities
- India's formalization wave:Building code enforcement and municipal cleanliness mandates in Mumbai, Delhi, and Bangalore are displacing informal operators and creating acquisition targets for integrated service platforms.
- Food-and-facilities convergence:Healthcare and education institutions seek single-accountability vendors combining nutrition services with environmental management, reducing vendor management overhead.
- Workplace experience integration:Corporate real estate teams are bundling cleaning, security, and concierge services under unified service-level agreements with occupant satisfaction metrics.
Industry Challenges
- Certified technician scarcity:HVAC-light and building automation system maintenance within soft service contracts requires cross-trained personnel that outpace vocational pipeline output.
- Legacy contract fragmentation:Corporate clients maintain overlapping single-service agreements with staggered renewal cycles, complicating platform consolidation and margin recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Facility Management Market |
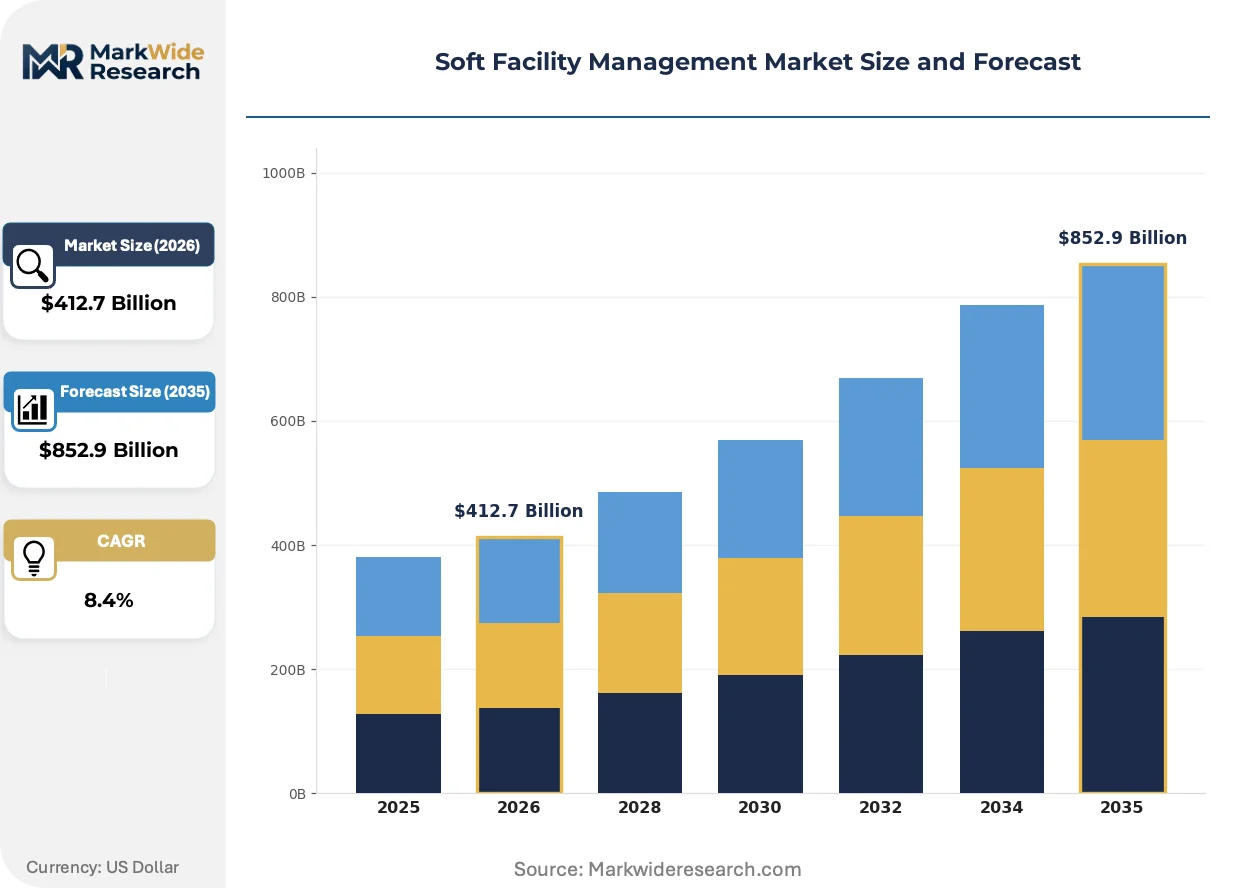
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $852.9 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Security Services, Landscaping, Waste Management End User: Commercial Buildings, Educational Institutions, Healthcare Facilities, Government Institutions Service Delivery Model: In-House Services, Outsourced Services, Integrated Services, Hybrid Models Contract Type: Fixed-Term Contracts, Long-Term Agreements, Pay-Per-Use Contracts, Performance-Based Contracts |
| Companies Covered | Sodexo, CBRE Group Inc., ISS A/S, Compass Group, Aramark, Jones Lang LaSalle Incorporated, Cushman & Wakefield plc, AHI Facility Services Inc., Johnson Controls International plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Facility Management Market Evolving Landscape
Digital monitoring systems and sustainability-driven procurement criteria are compressing traditional service delivery models and redefining competitive differentiation in facility management contracting.
Robotic cleaning equipment is overtaking manual methods in high-frequency, large-footprint environments such as airports, shopping centers, and hospital corridors. Facility operators in Germany and the United States are deploying autonomous scrubbers and vacuum systems during off-peak hours to reduce labor hours while maintaining compliance with defined response-time metrics. This technology is overtaking conventional crew-based models by enabling 24-hour coverage guarantees without shift premium costs.
The EU Green Deal's carbon disclosure requirements for public procurement are mandating lifecycle emissions documentation from cleaning and waste management vendors. Service providers must now submit verified carbon footprints for equipment, chemicals, and transportation as qualifying criteria for municipal and institutional contracts. Healthcare facilities in France and the Netherlands are prioritizing vendors with certified environmental management systems, compressing qualification timelines for uncertified competitors.
Integrated service agreements with outcome-based pricing are replacing transactionally renewed single-service contracts in corporate real estate portfolios. Occupant satisfaction scores and energy-adjusted cost-per-square-foot metrics now determine vendor compensation and renewal eligibility. This restructuring is most visible in United States technology campuses and financial services headquarters, where workplace experience has become a talent retention instrument.
Soft Facility Management Market Segmentation
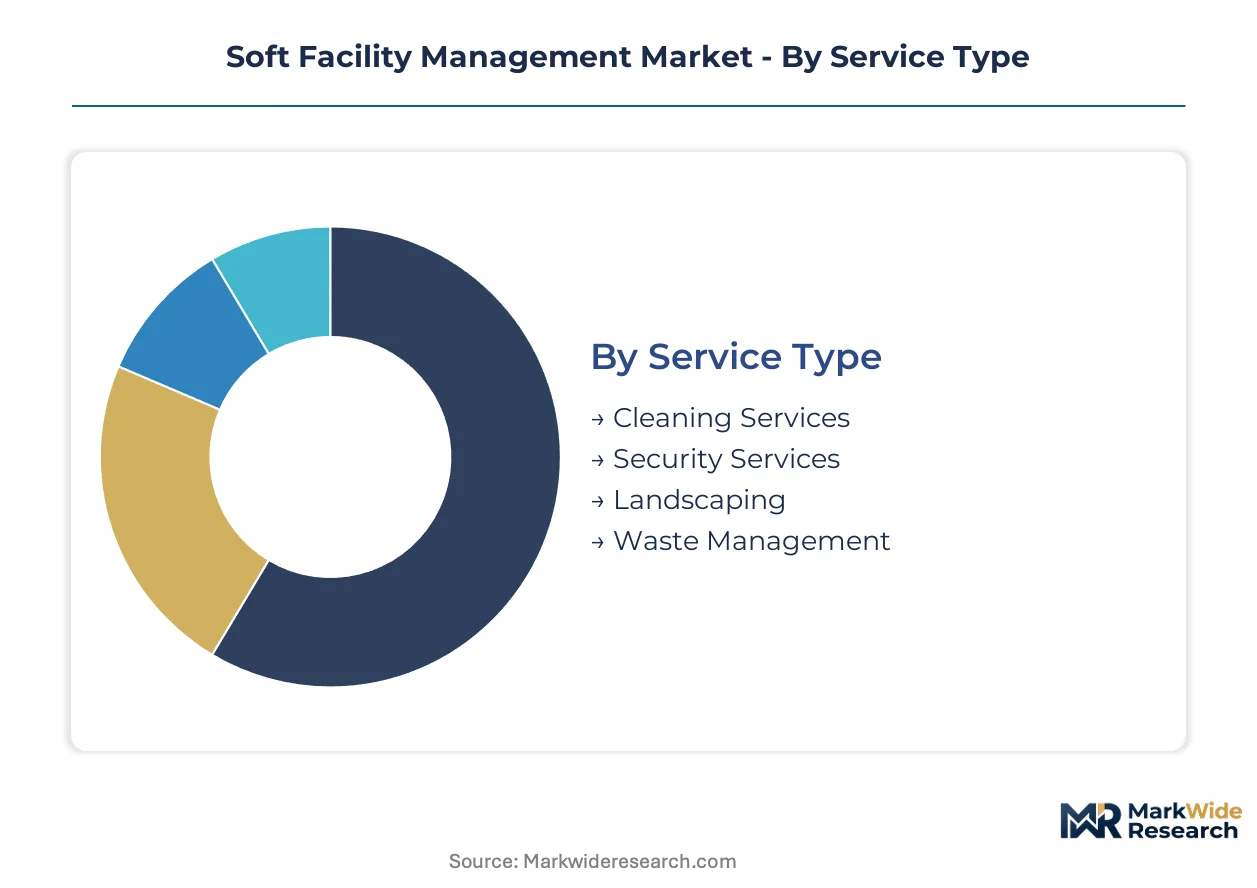
Soft facility management segments diverge sharply in capital requirements and labor intensity, with cleaning and security services demanding workforce scale while waste management and landscaping require specialized equipment fleets. Procurement patterns across these categories determine vendor profitability and contract renewal rates.
Service Type:
Capital intensity varies dramatically across service types, with security services requiring the heaviest upfront investment in surveillance infrastructure and guard training certification programs.
- Cleaning Services:Daily recurrence and labor intensity define this segment, with crews deploying industrial-grade equipment and EPA-registered disinfectants across healthcare and commercial footprints. Demand concentrates in Germany and the United States where unionized labor pools and OSHA workplace safety standards elevate formal vendor qualification barriers.
- Security Services:Technology-augmented guarding integrates AI-powered surveillance, access control systems, and mobile patrol coordination. Healthcare facilities in France and corporate campuses in the United States anchor premium pricing through integrated threat detection mandates.
- Landscaping:Seasonal equipment fleets and certified horticultural staff serve municipal parks and corporate grounds. Germany's municipal procurement specifications favor vendors with carbon-neutral maintenance fleets.
- Waste Management:Segregation infrastructure and hazardous material handling certifications dominate compliance costs. India's BIS cleanliness standards are elevating formal participation against informal collectors in Mumbai and Delhi.
Cleaning Services absorbs the bulk of installed capacity; Security Services is expanding most quickly.
End User:
Contract value and duration diverge by end-user sophistication, with healthcare and government institutions demanding the most stringent compliance documentation.
- Healthcare Facilities:Infection-control protocols and patient-safety standards tighten service-level requirements, extending contract durations for qualified operators. The EU Green Deal's carbon disclosure mandates reshape French and Dutch hospital procurement toward certified environmental management systems.
- Commercial Buildings:Workplace experience metrics now bundle cleaning, security, and concierge services under unified agreements. United States technology campuses anchor outcome-based pricing tied to occupant satisfaction scores.
- Educational Institutions:Food-and-facilities convergence reduces vendor management overhead across K-12 and university portfolios. France and North America show strongest adoption of single-accountability structures.
- Government Institutions:Municipal procurement specifications prioritize documented emissions tracking and certified technician availability. German federal building mandates enforce REACH-compliant chemical handling across cleaning contracts.
Commercial Buildings commands the largest contract volume; Healthcare Facilities shows the steepest expansion trajectory.
Service Delivery Model:
Vendor consolidation patterns vary by delivery structure, with integrated platforms capturing share from fragmented single-service arrangements.
- Integrated Services:Single-accountability structures consolidate cost and risk across cleaning, security, and environmental management. Corporate real estate teams in the United States and healthcare systems in Western Europe drive fastest adoption.
- Outsourced Services:Transactional vendor relationships persist where legacy contract fragmentation complicates platform migration. India's formalization wave displaces informal operators through building code enforcement.
- In-House Services:Direct employment models retain control over sensitive facilities and unionized workforces. Government institutions maintain larger in-house footprints than commercial real estate.
- Hybrid Models:Core functions remain internal while specialized services rotate through external vendors. Educational institutions favor this structure for seasonal landscaping and event security.
Outsourced Services still dominates active contract value; Integrated Services is gaining share fastest.
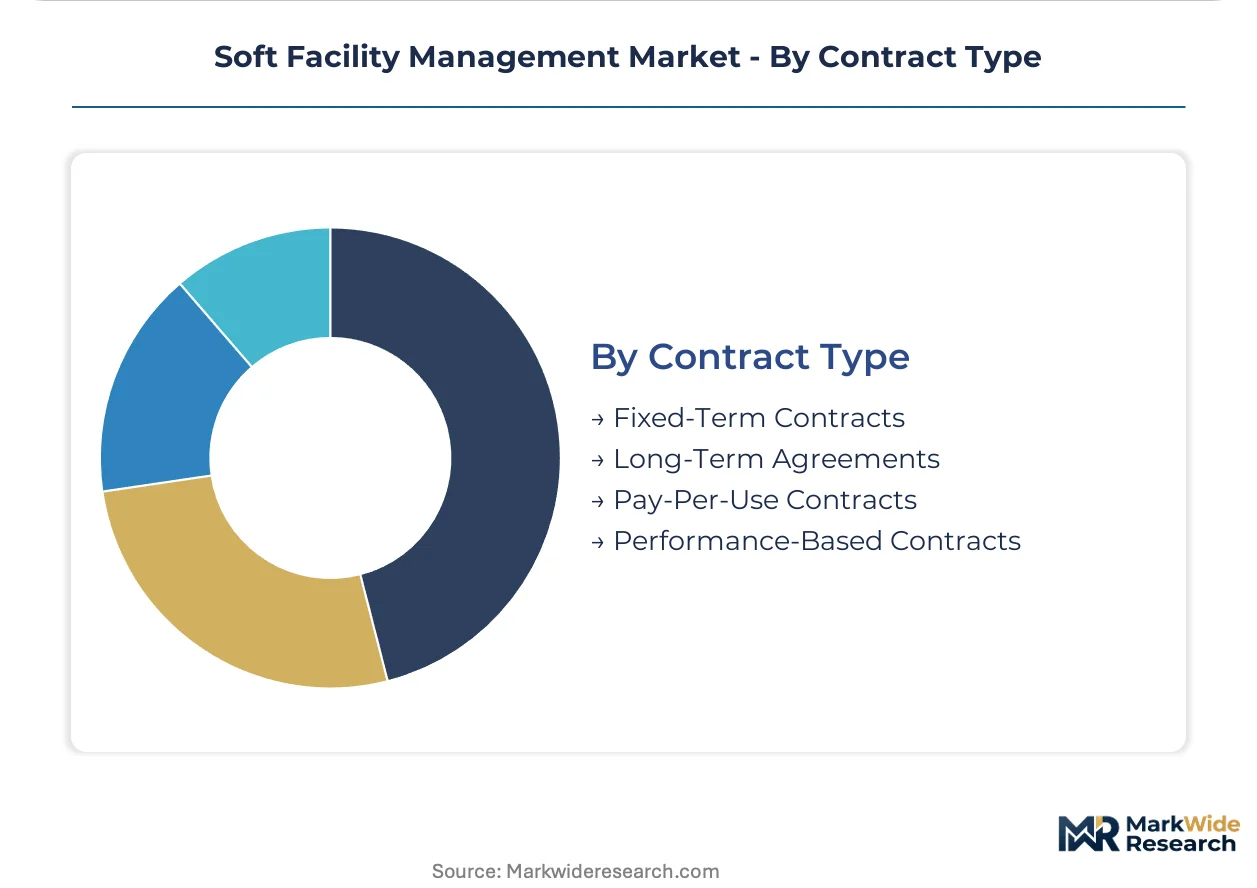
Contract Type:
Pricing structure and margin stability hinge on contract duration and performance linkage mechanisms.
- Performance-Based Contracts:Compensation ties directly to occupant satisfaction scores, energy-adjusted cost metrics, and compliance audit results. United States financial services headquarters and technology campuses anchor this structure.
- Long-Term Agreements:Multi-year frameworks reduce procurement overhead and enable vendor capital recovery for specialized equipment. Healthcare facilities favor five-to-seven-year terms to match accreditation cycles.
- Fixed-Term Contracts:Annual or bi-annual renewals dominate municipal and government procurement where budget cycles constrain commitment duration. Germany's public sector shows this pattern most clearly.
- Pay-Per-Use Contracts:Transactional pricing applies to event security, emergency cleaning, and seasonal landscaping where demand fluctuates unpredictably. Commercial real estate uses this for tenant turnover scenarios.
Fixed-Term Contracts represent the largest outstanding contract base; Performance-Based Contracts is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial labor pool anchors European facility service standardization, while India's municipal enforcement drives formalization across Asian procurement markets.
United States
Healthcare systems and technology campuses drive integrated service adoption. OSHA workplace safety standards and EPA chemical handling regulations elevate vendor qualification barriers. Texas and California anchor multi-service platform deployment across corporate real estate portfolios.
Germany
Unionized cleaning crews and carbon-neutral municipal fleets concentrate contract value. REACH chemical restrictions and EU Green Deal disclosure mandates reshape procurement specifications. Bavaria and North Rhine-Westphalia enforce federal building mandates for certified environmental management systems.
India
Building code enforcement in Mumbai, Delhi, and Bangalore displaces informal waste collectors. BIS cleanliness standards elevate formal vendor participation against unregistered competitors. Maharashtra and Karnataka anchor acquisition activity for integrated service platforms.
France
Hospital procurement prioritizes vendors combining food services with environmental management. EU Green Deal carbon disclosure requirements compress qualification timelines for uncertified operators. Île-de-France and Auvergne-Rhône-Alpes anchor healthcare facility contract expansion.
Netherlands
Corporate real estate teams bundle workplace experience services under unified agreements. CSRD reporting obligations extend to service procurement documentation. Randstad region anchors outcome-based pricing tied to occupant satisfaction metrics.
Soft Facility Management Market Competitive Landscape
Global majors compete with regional champions across integrated service platforms, with contract consolidation favoring multi-service accountability structures over fragmented single-vendor relationships. The vendor base spans three tiers: diversified facility conglomerates, specialized cleaning and security operators, and property management integrators. M&A activity targets regional density expansion, while technology licensing agreements accelerate robotic deployment and AI-augmented guarding capabilities.
Within the diversified conglomerate tier, Sodexo and Compass Group exemplify food-and-facilities convergence strategies that reduce client vendor management overhead. ISS A/S occupies a position as a European density specialist, while CBRE Group Inc. and Jones Lang LaSalle Incorporated anchor property management integration in North American corporate portfolios. Aramark represents the education and healthcare institutional focus archetype.
| Leading Market Players |
|---|
| Sodexo |
| CBRE Group Inc. |
| ISS A/S |
| Compass Group |
| Aramark |
| Jones Lang LaSalle Incorporated |
| Cushman & Wakefield plc |
| AHI Facility Services Inc. |
| Johnson Controls International plc |
| Others |
Value Network & Pricing Analysis
Certified-versus-informal vendor divergence splits contract value between premium integrated platforms and commodity labor brokers, with Germany's unionized wage floors and India's municipal enforcement driving opposite ends of this bifurcation in both pricing power and supplier qualification requirements. EU Green Deal carbon disclosure mandates and REACH chemical restrictions elevate compliant vendor costs while compressing margins for fixed-price operators unable to pass through compliance investments.
Pricing Analysis
Warranty and service-level bundling separates premium integrated contracts from unbundled transactional arrangements, with healthcare facilities in France and the Netherlands paying premiums for guaranteed infection-control response times and certified environmental management systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, contract duration, and technology augmentation intensity. Cost compression in standard-tier cleaning contracts intensifies because Germany's minimum wage escalations outpace indexation clauses in legacy agreements. Municipal procurement teams in India exhibit highest price sensitivity, while United States technology campuses anchor least sensitive demand through workplace experience metrics.
Supply Chain Analysis
Labor pool availability rests on immigration policy flexibility in Germany, vocational training throughput in the United States, and informal-to-formal transition velocity in India. Equipment and chemical inputs draw from Chinese manufacturing for robotic cleaning systems, German specialty chemical producers for REACH-compliant agents, and domestic distributors for consumable supplies. Single-source vulnerability concentrates in AI-powered surveillance hardware sourced from limited qualified vendors. Distribution runs through regional service hubs that deploy crews and equipment within defined response-time radii.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotic cleaning equipment is displacing manual crew-based models in high-frequency environments, compressing labor share of contract value and redefining competitive positioning around technology deployment capabilities rather than workforce scale alone.
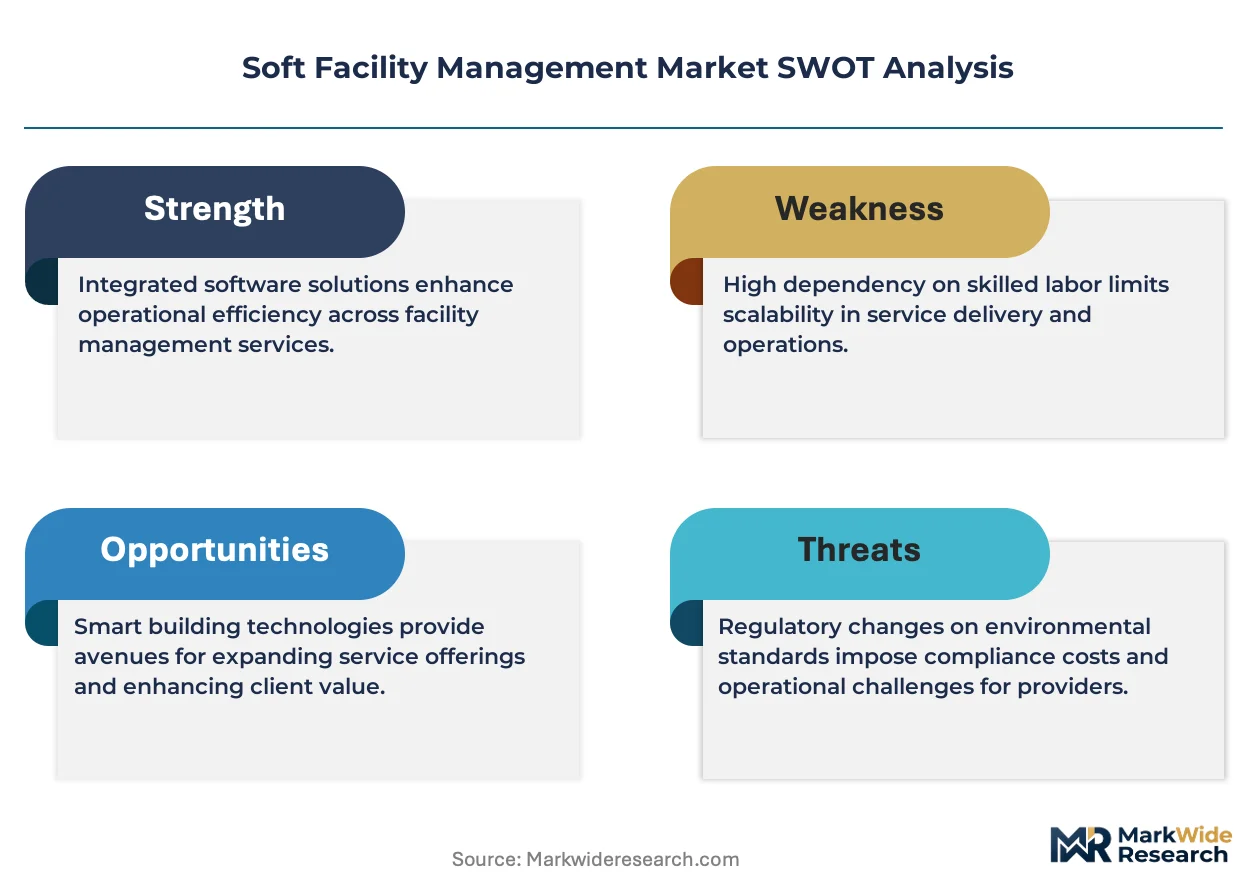
For Market Incumbents: Hedge margin erosion in wage-intensive cleaning segments by accelerating autonomous equipment deployment in German airport and healthcare contracts before union density restricts technology substitution. Acquire certified environmental management capabilities to meet EU Green Deal disclosure mandates in French hospital procurement. Labor cost volatility in fixed-price agreements and informal operator undercutting in India represent parallel threats requiring differentiated regional responses.
For New Entrants and Emerging Players: Direct-to-platform digital channels enable rapid qualification for municipal contracts in India's formalizing markets, bypassing incumbent relationship advantages in legacy procurement systems. Target Maharashtra and Karnataka state-level building code enforcement zones where informal displacement creates immediate contract availability. Food-and-facilities convergence in North American education institutions offers white-space entry with lower competitive density than corporate integrated services.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap integrated platforms possessing certified healthcare capabilities given tightening infection-control protocol enforcement across Western Europe. Long-term viability favors operators with technology-augmented guarding and robotic cleaning deployment experience over pure labor brokers. Watch municipal procurement specification releases in Mumbai, Delhi, and Bangalore as inflection indicators for India's formalization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Equipment Deployment | Autonomous scrubbers in German airports reduce labor hours while maintaining OSHA-compliant response-time guarantees. |
| Environmental Certification Investment | ISO 14001 systems qualify vendors for EU Green Deal-mandated French hospital procurement contracts. |
| Food-and-Facilities Convergence | Single-accountability structures reduce vendor management overhead in North American education and healthcare portfolios. |
| Regional Density Acquisition | Mumbai and Delhi building code enforcement displaces informal operators, creating certified vendor acquisition targets. |
| Outcome-Based Contract Structuring | Occupant satisfaction metrics in United States technology campuses align vendor compensation with workplace experience outcomes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with facility management executives, municipal procurement officers, healthcare infection-control directors, and cleaning equipment distributors. OSHA enforcement databases, EPA chemical handling guidelines, EU Green Deal procurement specifications, and India's BIS cleanliness standards provided regulatory validation. Bottom-up contract value estimates triangulated against top-down market sizing from service provider revenue disclosures.
Data-stream reconciliation across service type, end-user vertical, delivery model, and contract structure dimensions produced volume and value outputs across the projection horizon. CAGRs derived from historical contract renewal rates, technology adoption curves for robotic equipment, and regulatory mandate implementation timelines. Labor cost indices, municipal enforcement intensity scores, and carbon disclosure compliance penetration informed segment-specific trajectory modeling.
The model holds under steady regulatory enforcement and technology cost decline assumptions; deviation in immigration policy restricting German labor supply, or abrupt REACH chemical ban expansions, would shift vendor qualification timelines and contract pricing structures. A small set of named triggers—India's BIS enforcement velocity, EU Green Deal procurement mandate expansion, and United States minimum wage indexation patterns—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Indonesia Facility Management Market
Facility Management
Thailand Facility Management Market
Facility Management
Poland Facility Management Market
Facility Management
Hong Kong Facility Management Market
Facility Management
Europe Hard Facility Management Market
Facility Management
Saudi Arabia Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
Taiwan Facility Management Services Market
Facility Management
Austria Facility Management Market
Facility Management
Facility Management Services Market
Facility Management
Asia Pacific Facility Management Market
Facility Management
Albania Facility Management Market
Facility Management
Nigeria Facility Management Services Market
Facility Management
Italy Facility Management Services Market
Facility Management
Egypt Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market