
 Albania Facility Management Market | 2026-2036
Albania Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Albania Facility Management Market Analysis
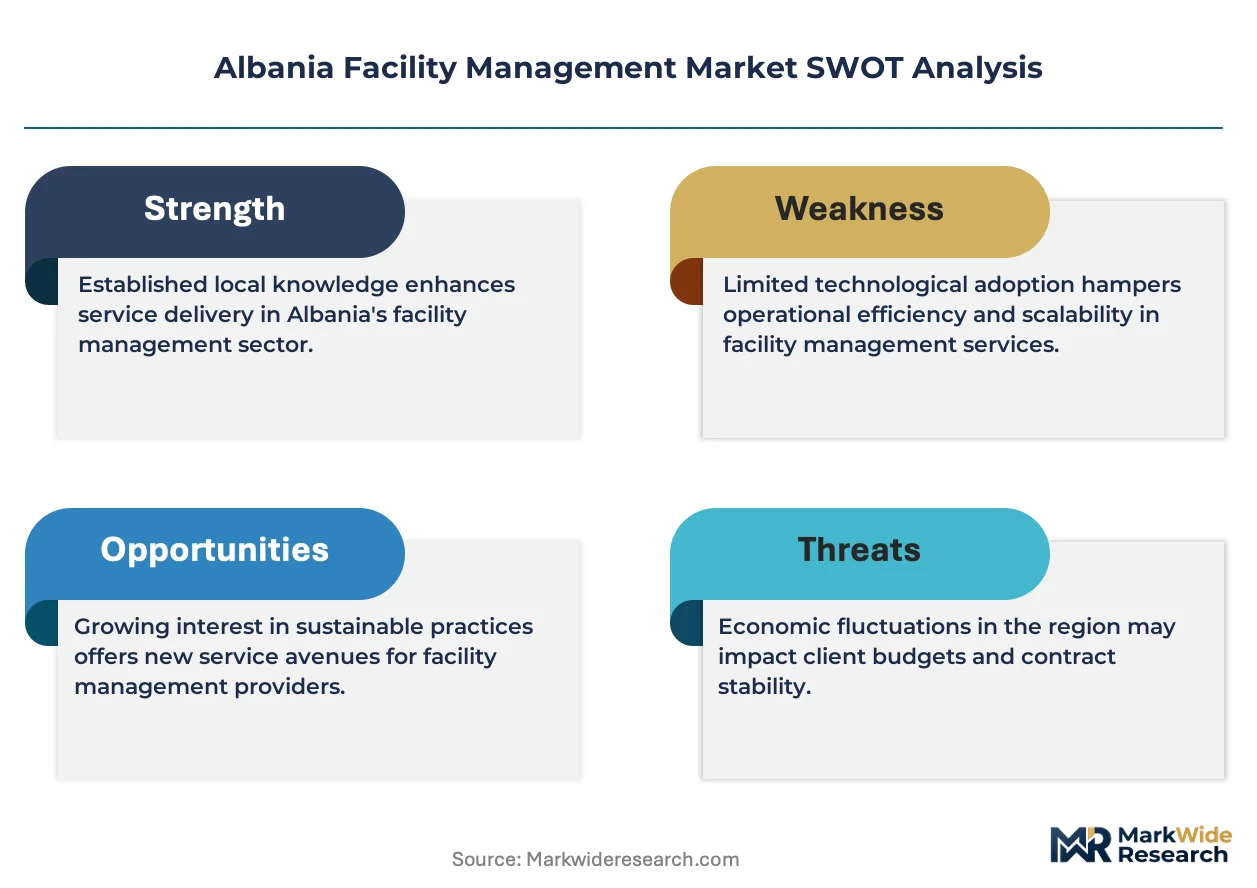
Albania's national building energy performance regulation is realigning the cost-of-entry calculus for facility management providers. JLL leverages its international certification protocols to anchor premium service contracts in Tirana's Class A office segment. CBRE Group Inc. competes through integrated workplace technology platforms that sustain operational transparency for multinational tenants. AlbStar Sh.a. differentiates via deep local subcontractor networks that control maintenance response times across secondary cities.
Facility management encompasses the coordination of building operations, maintenance, and support services to ensure functional, safe, and efficient built environments, typically governed by service-level agreements specifying response times, uptime thresholds, and compliance benchmarks. Its primary purpose is to optimize lifecycle costs while preserving asset value across commercial, industrial, and institutional property portfolios. Cleaning services and security services dominate current revenue pools as commoditized entry points, while integrated facility management captures expanding margin concentration as clients consolidate vendor relationships. Outsourced services accelerate fastest among corporate clients seeking to transfer fixed cost burdens, whereas in-house management persists in government institutions constrained by public procurement rigidities.
Albania's Ministry of Economy and Finance enforces public procurement standards that shape competitive bidding access for facility contracts, while the country's national construction inspectorate mandates periodic technical audits that elevate compliance-driven maintenance spending. The EU Energy Performance of Buildings Directive, transposed into Albanian law, imposes efficiency disclosure obligations that redirect demand toward certified energy management services. Stakeholders must monitor accession-aligned regulatory tightening and decide whether to build in-house technical audit capabilities or partner with EU-accredited certification bodies.
Market Dynamics
EU accession alignment is compressing service procurement timelines as Albanian commercial landlords face mandatory energy disclosure obligations that demand certified technical audit capabilities.
Growth Catalysts
- EU Energy Performance of Buildings Directive transposition:Albania's national construction inspectorate now mandates periodic technical audits, redirecting facility spending toward certified energy management services and creating compliance-driven contract volumes.
- Tirana Class A office development:Premium commercial stock concentration in the capital's business districts is accelerating outsourced integrated facility management adoption among multinational tenants seeking single-vendor accountability.
- Building Management Systems integration:IoT-enabled predictive maintenance platforms are reducing unplanned downtime for corporate clients, pulling demand away from reactive service models toward technology-augmented contracts.
Market Restraints
- Skilled technician scarcity:Albania's vocational training pipeline produces insufficient HVAC and electrical specialists, inflating wage costs for providers serving secondary cities beyond Tirana-Durrës corridor.
- Subcontractor network fragmentation:Deep reliance on informal maintenance crews in Vlorë and Shkodër creates service quality inconsistency and liability exposure for integrated facility management contracts.
- Public procurement rigidity:Ministry of Economy and Finance bidding standards enforce lowest-price selection criteria that commoditize cleaning and security services, compressing margins for compliance-heavy offerings.
Strategic Opportunities
- Durrës port-zone industrial facilities:Maritime logistics expansion is generating demand for specialized hard services including crane maintenance and hazardous materials handling that local providers currently underserve.
- EU pre-accession technical assistance funds:Instrument for Pre-Accession Assistance financing is subsidizing energy retrofit audits, creating a pipeline of certified upgrade projects for facility management firms with accreditation partnerships.
- Smart building convergence:Integration of Building Management Systems with Albania's expanding fiber-optic backbone is enabling remote monitoring services that reduce truck-roll costs for geographically dispersed assets.
Industry Challenges
- Certification timeline compression:EU-aligned energy auditor qualifications require 18-24 month accreditation cycles that outpace contract award windows, forcing providers to absorb pre-qualification costs without guaranteed revenue.
- Legacy asset integration complexity:Communist-era building stock in Tirana's inner ring lacks BAS infrastructure, requiring costly sensor retrofits that erode margins on fixed-price integrated contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Albania Facility Management Market |
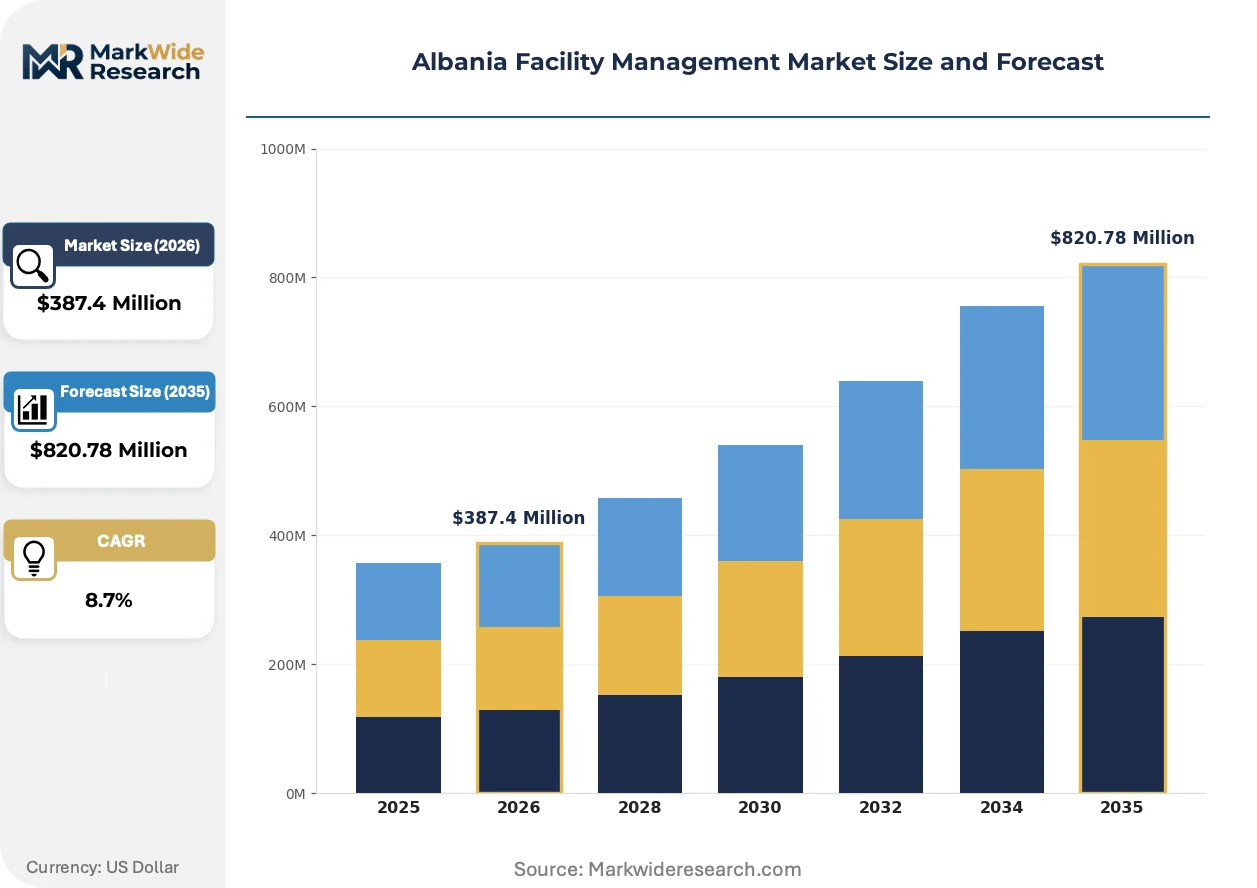
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $820.78 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Security Services, Maintenance Services, Landscaping Client Type: Residential Clients, Corporate Clients, Government Institutions, Educational Facilities Facility Type: Commercial Buildings, Industrial Facilities, Healthcare Institutions, Retail Spaces Management Approach: In-House Management, Outsourced Services, Hybrid Management, Integrated Facility Management |
| Companies Covered | Diversey Holdings Ltd., Mott Macdonald, AlbStar Sh.a., JLL (Jones Lang LaSalle), CBRE Group Inc., ACREM (Albanian Commercial Real Estate Management), Globe William International, Fusha sh.a., Colliers International Group Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Albania Facility Management Market Emerging Trajectories
Digital infrastructure deployment is rewiring how Albanian facility operators balance centralized oversight against localized response capabilities. Three developments are compressing the traditional trade-off between cost and service quality.
Cloud-native Computerized Maintenance Management Systems are modularizing service delivery architectures across Tirana's Class A office portfolio. These platforms enable real-time work order dispatch to distributed technician networks. Corporate occupiers in the capital's Blloku district are adopting subscription-based CMMS modules faster than traditional ERP-integrated suites, fragmenting vendor selection criteria by functional need rather than bundled capability.
Albania's transposition of EU Energy Performance of Buildings Directive disclosure mandates is redirecting capital toward certified audit services. Commercial landlords must now publish standardized efficiency ratings before lease execution. The regulation is forcing property managers to pre-qualify facility vendors based on ISO 50001 energy management certification, compressing the competitive set for integrated contracts in Tirana's emerging CBD developments.
Corporate procurement departments are unbundling service contracts that historically combined cleaning, security, and maintenance under single providers. Multinational tenants in Albania's tech outsourcing sector now source hard facilities services separately from soft services, enabling direct vendor performance comparison. This pattern is most pronounced among Greek and Italian parent companies applying Mediterranean procurement templates to their Tirana operations.
Albania Facility Management Market Segmentation
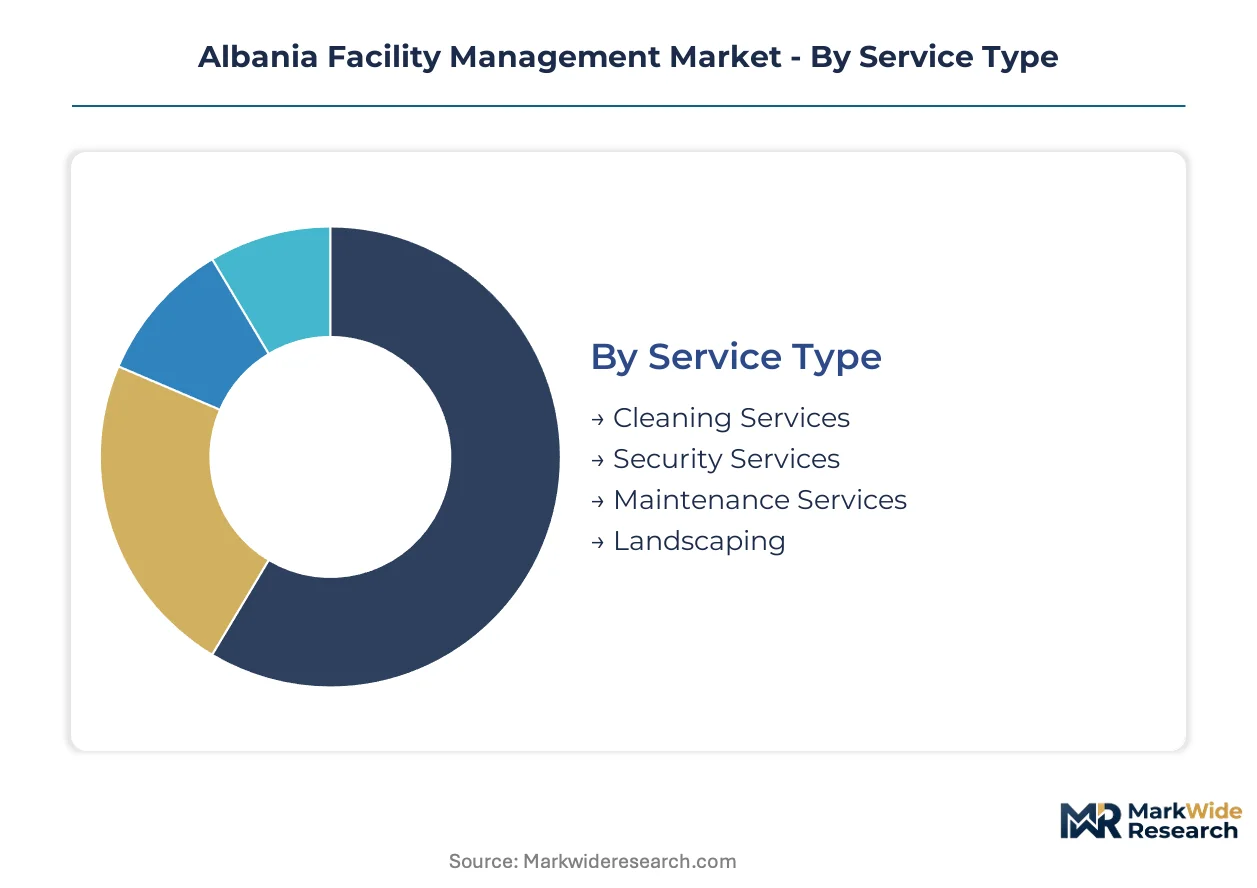
Albania's facility management market fragments across service delivery models and client procurement sophistication. Segmentation reveals where EU accession pressures concentrate compliance spending versus where commoditized competition erodes provider margins.
Service Type:
Standalone service contracts dominate procurement in secondary cities, while integrated bundles concentrate in Tirana's Class A office developments where single-vendor accountability reduces coordination overhead.
- Cleaning Services:Labor-intensive janitorial operations employing alkaline-based disinfectants and HEPA filtration protocols for healthcare-grade environments. Demand clusters in Tirana's Blloku district retail corridors and Durrës port-zone logistics facilities, driven by EU hygiene standards transposition for food-handling adjacent spaces.
- Security Services:Manned guarding supplemented by CCTV and access control integration, with Tier 1 providers deploying RFID-enabled patrol verification. Corporate clients in the capital's emerging CBD specify SOC-2 compliant operators to satisfy parent-company risk protocols, compressing vendor qualification timelines.
- Maintenance Services:HVAC and electrical corrective work dominates revenue pools.
- Landscaping:Seasonal grounds maintenance with irrigation system oversight.
Cleaning services lead volumes today; integrated maintenance bundles are gaining share fastest as energy audit mandates elevate technical service requirements.
Client Type:
Procurement sophistication varies sharply across client categories, with EU-exposed corporates demanding certified energy management while public institutions remain constrained by lowest-price bidding rules.
- Corporate Clients:Multinational tenants and Albanian-headquartered firms with foreign ownership, prioritizing ISO 50001-certified integrated facility management to satisfy EU Energy Performance of Buildings Directive disclosure obligations. These clients consolidate vendor relationships fastest, pulling hard and soft services under single accountability structures.
- Government Institutions:Ministry of Economy and Finance procurement standards enforce rigid lowest-price selection, fragmenting contracts across cleaning, security, and maintenance silos. The public sector's 18-24 month payment cycles and bid protest vulnerability deter premium providers, leaving commoditized local operators dominant.
- Residential Clients:Condominium management boards sourcing fragmented point services.
- Educational Facilities:University and K-12 institutions with seasonal demand fluctuation.
Corporate clients anchor premium pricing tiers; government institutions represent the largest addressable contract volume despite procurement friction.
Facility Type:
Building vintage and energy performance exposure determine service bundling economics, with new commercial stock enabling predictive maintenance platforms and legacy industrial assets requiring reactive intervention.
- Commercial Buildings:Class A office developments in Tirana's CBD and Blloku district, equipped with Building Management Systems infrastructure enabling IoT-enabled predictive maintenance. These assets generate the highest integrated facility management contract values as landlords pre-qualify vendors for energy audit certification.
- Industrial Facilities:Manufacturing plants and Durrës port-zone logistics warehouses requiring specialized hard services including crane maintenance, hazardous materials handling, and fire suppression system inspection. Local provider capability gaps in these technical disciplines create margin expansion for accredited specialists.
- Healthcare Institutions:Hospitals and clinics with infection control protocols.
- Retail Spaces:Shopping centers and high-street storefronts with high-traffic cleaning intensity.
Commercial buildings concentrate premium contract values; industrial facilities show the steepest expansion trajectory as port-zone logistics investment accelerates.
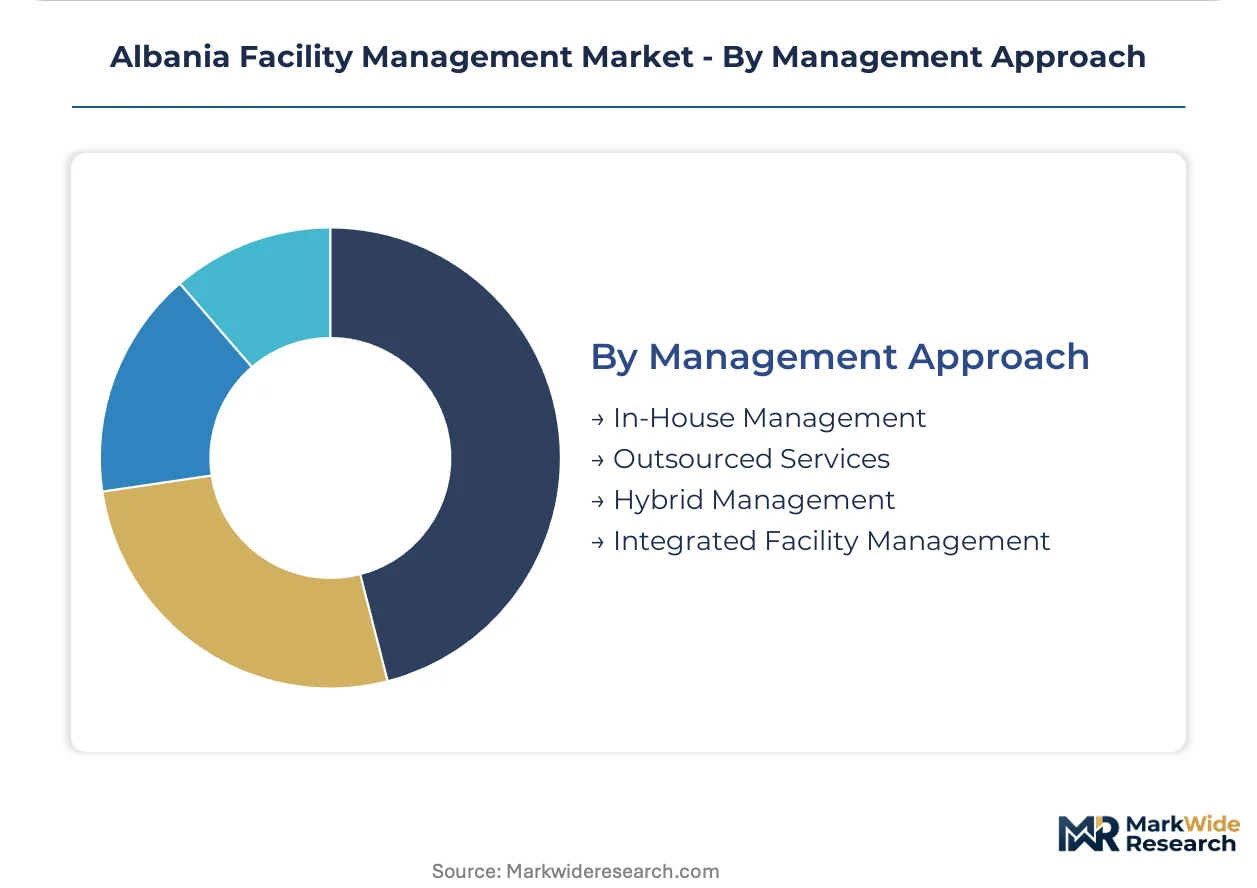
Management Approach:
Cost structure preferences and risk transfer appetite segment procurement patterns, with outsourced models accelerating among growth-stage enterprises and integrated approaches dominating mature portfolios.
- Outsourced Services:Third-party facility management transferring fixed labor costs and compliance liability to specialized providers. Albanian tech outsourcing sector employers and Greek-owned manufacturing subsidiaries adopt this model fastest, applying Mediterranean procurement templates that separate hard facilities services from soft service bundles.
- Integrated Facility Management:Single-vendor accountability spanning maintenance, cleaning, security, and energy management under unified service-level agreements. This approach concentrates in Tirana's Class A office stock where multinational tenants demand uptime guarantees and transparent operational metrics.
- In-House Management:Direct employment of maintenance and security staff, persisting in government institutions and legacy state-owned enterprises.
- Hybrid Management:Core functions retained internally with specialized services contracted externally.
Outsourced services dominate current contract flow; integrated facility management is climbing the fastest as energy disclosure mandates elevate technical service bundling requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility management services originated in post-war Western Europe's industrial reconstruction, spreading to Southern Europe through EU convergence funds and regulatory harmonization programs that Albania now accesses through its accession candidacy.
Tirana Metropolitan Area
Class A office developments in the Blloku district and emerging central business district concentrate demand for integrated facility management contracts. The Ministry of Economy and Finance enforces public procurement standards that shape competitive bidding access. Multinational tenants from Greece and Italy apply Mediterranean procurement templates that separate hard facilities services from soft service bundles.
Durrës Port Zone
Maritime logistics expansion generates specialized hard services demand including crane maintenance and hazardous materials handling. The national construction inspectorate mandates periodic technical audits for industrial facilities. Local provider capability gaps in these technical disciplines create margin expansion opportunities for accredited specialists serving container terminal operators.
Vlorë Coastal Corridor
Tourism infrastructure development drives seasonal facility service demand with fluctuating occupancy patterns. EU Energy Performance of Buildings Directive transposition imposes efficiency disclosure obligations on hospitality assets. Subcontractor network fragmentation creates service quality inconsistency for integrated contracts covering beachfront resort properties.
Shkodër Northern Region
Legacy industrial assets from the communist era require reactive maintenance intervention rather than predictive platforms. Skilled technician scarcity inflates wage costs for providers operating beyond the Tirana-Durrës corridor. Informal maintenance crews dominate local service provision, creating liability exposure for integrated facility management contracts.
Albania Facility Management Market Vendor Landscape
The competitive structure tilts toward international property consultancies anchoring premium service tiers while local operators capture commoditized cleaning and security volumes. Tier-1 providers leverage ISO 50001 energy management certification to pre-qualify for Class A office contracts, while mid-tier local firms compete on response time control through deep subcontractor networks. Strategic moves concentrate on certification timeline acceleration and technology platform deployment rather than asset-heavy expansion.
Among international consultancies, JLL and CBRE Group Inc. occupy positions exemplifying the premium-tier archetype through integrated workplace platforms, while AlbStar Sh.a. represents the local-network specialist model controlling maintenance response times across secondary cities. Colliers International Group Inc. and ACREM anchor mid-market positioning between these poles.
| Leading Market Players |
|---|
| Diversey Holdings Ltd. |
| Mott Macdonald |
| AlbStar Sh.a. |
| JLL (Jones Lang LaSalle) |
| CBRE Group Inc. |
| ACREM (Albanian Commercial Real Estate Management) |
| Globe William International |
| Fusha sh.a. |
| Colliers International Group Inc. |
| Others |
Supply Flow & Price Mechanics
HVAC and electrical technician concentration in the Tirana-Durrës corridor establishes labor-cost differentials that widen pricing spreads between premium integrated contracts and commoditized point services. Albania's vocational training gap inflates wage premiums for certified specialists serving secondary cities, compressing margins for providers unable to cluster operations geographically.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the Albania facility management market by certification grade and service bundling intensity. ISO 50001 energy management certification commands substantial premiums in Tirana's Class A office segment, while uncertified local operators compete on response-time guarantees in secondary markets. Cost compression in the government procurement tier is intensifying because Ministry of Economy and Finance bidding standards enforce lowest-price selection criteria. Corporate clients with EU exposure demonstrate the least price sensitivity, prioritizing single-vendor accountability and transparent operational metrics over unit cost minimization.
Supply Chain Analysis
Reverse-logistics flows for Building Management Systems components remain underdeveloped in Albania, with sensor refurbishment and control system remanufacturing concentrated in Italy and Germany. Equipment supply draws from Italian HVAC manufacturers, Turkish security systems providers, and Chinese IoT hardware vendors, creating multi-currency procurement exposure. Single-source vulnerability concentrates in cloud-native CMMS platform licensing, where subscription dependencies tether Albanian operators to EU-based software vendors. Distribution runs through Tirana-based master distributors serving regional subcontractor networks across Vlorë, Shkodër, and Durrës.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Albania's facility management market represents a late-cycle quality story as EU Energy Performance of Buildings Directive transposition redirects demand toward certified energy audit capabilities and away from commoditized service bundles.
For Market Incumbents: To counter subcontractor network fragmentation in secondary cities, anchor integrated contracts through direct employment of HVAC and electrical specialists in the Tirana-Durrës corridor, while accelerating ISO 50001 certification timelines to pre-qualify for emerging Class A office developments in the capital's central business district. For New Entrants and Emerging Players: Launch via specialized hard services partnerships targeting Durrës port-zone industrial facilities, where crane maintenance and hazardous materials handling capability gaps create white-space opportunities. Maritime logistics operators represent the most penetrable client segment, with technical accreditation from Albania's national construction inspectorate serving as the critical go-to-market credential. For Investors and Strategic Acquirers: EU-based property consultancies with Balkan expansion strategies are the most active acquirer in this space, seeking local operators with established subcontractor networks. Long-term viability hinges on accession-aligned regulatory tightening accelerating consolidation. Monitor EU pre-accession technical assistance fund disbursement rates as the inflection indicator for certified energy retrofit project pipeline expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 50001 Certification Investment | Pre-qualifies providers for Tirana Class A office contracts under EU energy disclosure mandates. |
| Direct Technician Employment | Reduces liability exposure from informal subcontractor crews in Vlorë and Shkodër corridors. |
| CMMS Platform Deployment | Enables real-time work order dispatch across Albania's expanding fiber-optic backbone infrastructure. |
| Durrës Port-Zone Specialization | Captures margin expansion from crane maintenance and hazardous materials handling undersupply. |
| EU Accreditation Partnership | Accelerates energy auditor qualification timelines for compliance-driven contract volumes. |
Methodological Framework
Multiple input streams — facility management contract databases, EU pre-accession funding disbursement records, and national construction inspectorate audit filings — were reconciled against primary interviews with property portfolio managers, facility operations directors, and procurement officers at multinational tenants. Secondary validation incorporated Albania's Ministry of Economy and Finance public procurement registries, EU Energy Performance of Buildings Directive transposition documents, and vocational training pipeline statistics from the national employment agency. Bottom-up contract value aggregation and top-down market sizing triangulation anchored volume estimates.
Historical contract award patterns were cross-referenced against expert panel assessments to construct projection scenarios across the analysis window. Segmentation dimensions modeled include service type bundling intensity, client procurement sophistication tier, facility vintage and BAS infrastructure readiness, and management approach preference. CAGRs were derived from weighted average growth assumptions calibrated to EU accession timeline milestones and energy retrofit subsidy pipeline visibility.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU accession timelines or prolonged skilled technician scarcity. Practitioners should monitor EU pre-accession technical assistance fund allocation rates and national construction inspectorate audit mandate enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Brazil Facility Management Market
Facility Management
Netherlands Facility Management Market
Facility Management
Germany Facility Management Market
Facility Management
Greece Facility Management Market
Facility Management
United Arab Emirates Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
Belgium Facility Management Market
Facility Management
Middle East and Africa Facility Management Market
Facility Management
New Zealand Facility Management Market
Facility Management
Spain Facility Management Market
Facility Management
Latvia Facility Management Market
Facility Management
Global Unified Facility Management Market
Facility Management
Global Facility Management Software Market
Facility Management
Warehouse Management Service Market
Facility Management
Lithuania Facility Management Market