
 Africa Facility Management Market | 2026-2036
Africa Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Facility Management Market Outlook
REACH-equivalent chemical safety standards across African trade blocs are rebalancing the cost-of-entry calculus for facility management providers seeking cross-border contracts. Bidvest Facilities Management leverages its integrated service platform to sustain dominance across South Africa's commercial property sector. Tsebo Solutions Group anchors its competitive position through deep specialization in healthcare and education end users. Servest Africa competes aggressively on security and cleaning bundled contracts across multiple jurisdictions.
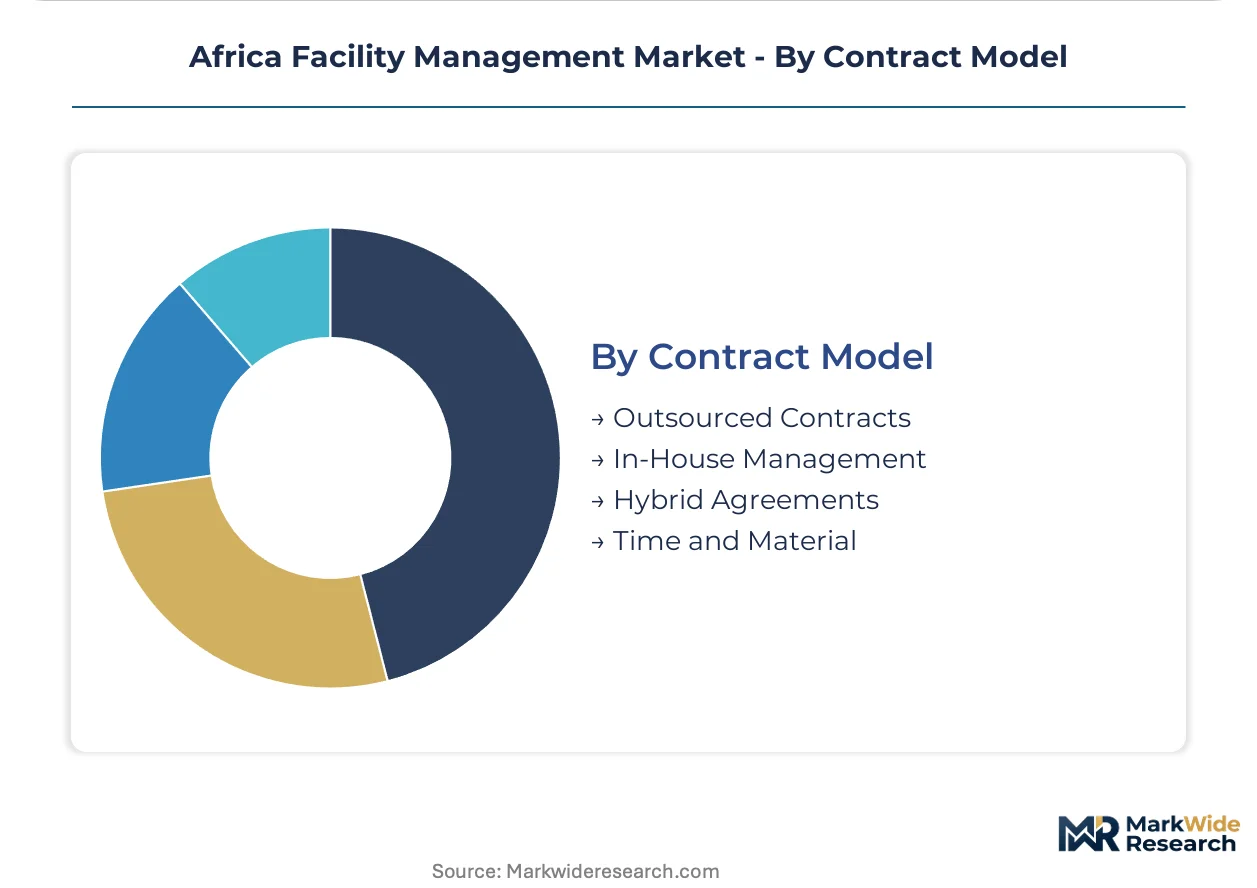
Facility management encompasses the professional coordination of building operations, maintenance, cleaning, security, and landscaping services to ensure functional, safe, and cost-efficient property environments; core technical parameters include service level agreement adherence, energy benchmarking per square meter, and integrated workplace management system deployment. The service type dimension shows maintenance and security services capturing the largest contract values due to their labor intensity and regulatory visibility, while IoT solutions within the technology segment represent the fastest-expanding margin pool as predictive maintenance replaces reactive protocols. Contract models reveal outsourced contracts leading volume but hybrid agreements gaining share as clients retain strategic control while delegating operational execution.
BIS-aligned national standards in South Africa, Kenya's Energy Regulatory Authority building codes, and Nigeria's Federal Ministry of Environment sustainability directives collectively shape compliance costs and technology procurement decisions across the market. The CSRD disclosure framework from European-headquartered multinationals operating African assets is accelerating ESG reporting requirements in facility supply chains. Stakeholders must decide whether to build captive technology capabilities or partner with cloud platform vendors before integrated software becomes a non-negotiable bid requirement.
Market Dynamics
Integrated workplace management systems are compressing contract negotiation cycles across Africa's facility management sector as multinational tenants demand real-time performance visibility and automated compliance reporting from their service providers.
Growth Catalysts
- Energy benchmarking mandates:Kenya's Energy Regulatory Authority building codes compel commercial property operators to deploy consumption monitoring systems, expanding the addressable market for technology-integrated facility contracts.
- Healthcare infrastructure expansion:Hospital groups across Nigeria and South Africa are consolidating non-core operations into outsourced bundled service agreements covering maintenance, cleaning, and security.
- REACH-equivalent chemical safety standards:Harmonized trade bloc regulations are reducing cross-border compliance friction for facility management providers seeking multi-country contracts.
Market Restraints
- Skilled technician scarcity:Certification requirements for HVAC and electrical systems maintenance outpace vocational training output in secondary cities.
- Input cost volatility:Diesel fuel price fluctuations directly compress margins for generator-dependent maintenance operations across markets with unreliable grid supply.
- Concentrated supplier base:IoT sensor and building automation hardware procurement depends on a narrow import channel through Johannesburg and Lagos port corridors.
Strategic Opportunities
- Underpenetrated East African corridor:Ethiopia and Tanzania commercial property stocks lack integrated facility management penetration relative to Southern African benchmarks.
- CSRD disclosure acceleration:European-headquartered multinationals operating African assets are mandating ESG data collection across their facility supply chains.
- Predictive maintenance convergence:Machine learning analytics layered onto existing building management systems creates new recurring revenue streams for incumbent service providers.
Industry Challenges
- Integration complexity with legacy infrastructure:Colonial-era building stock across West African commercial centers lacks the sensor readiness for IoT-enabled service models.
- Certification timeline compression:South Africa's updated National Building Regulations require rapid compliance upgrades that strain contractor capacity planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Facility Management Market |
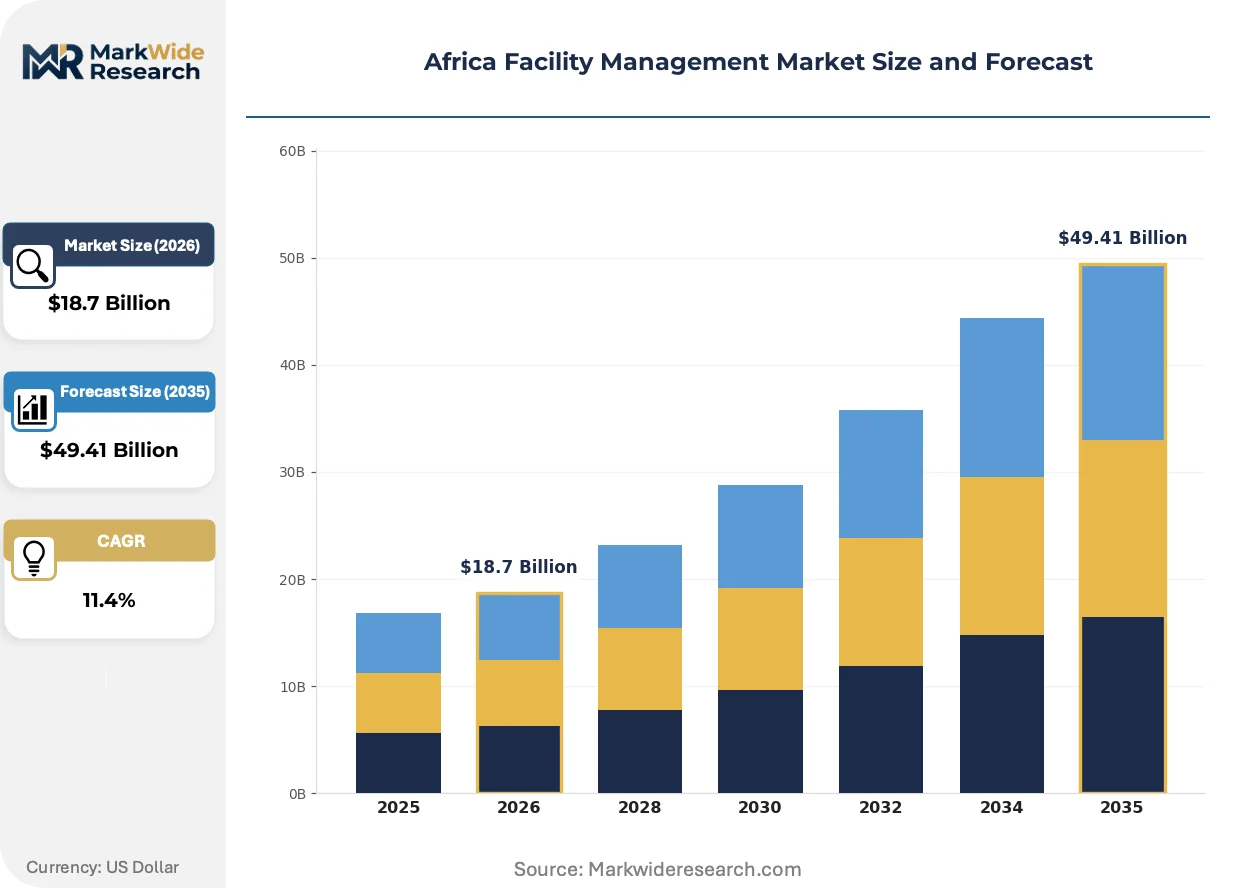
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Maintenance Services, Security Services, Landscaping Services End User: Commercial Buildings, Residential Complexes, Educational Institutions, Healthcare Facilities Technology: Integrated Software, IoT Solutions, Cloud Platforms, Automation Tools Contract Model: Outsourced Contracts, In-House Management, Hybrid Agreements, Time and Material |
| Companies Covered | Bidvest Facilities Management, Tsebo Solutions Group, Apleona GmbH, Servest Africa, G4S Africa, Contrack Facilities Management S.A.E., Broll Property Group, Excellerate Services, Integrico Private Limited, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Facility Management Market Strategic Shifts
Technology deployment patterns across African facility management are pivoting from centralized control rooms toward distributed sensor networks and edge computing architectures that reduce latency for critical building systems.
IoT-enabled building automation is decentralizing operational decision-making across commercial property portfolios. Facility managers in Lagos and Nairobi are deploying wireless sensor networks for HVAC and lighting control without hardwired backbone infrastructure. This architecture is decentralizing service delivery models by enabling remote diagnostics and reducing truck-roll dependency for routine maintenance interventions.
South Africa's BIS-aligned national standards are tightening energy efficiency disclosure requirements for commercial buildings above specified floor areas. Property owners must now submit verified consumption data to national registries. Large-format office complexes in Johannesburg and Cape Town are responding by embedding sub-metering infrastructure into new lease agreements.
Corporate real estate teams are unbundling long-term bundled contracts into modular service components with shorter renewal cycles. Multinational tenants in Nigeria's commercial corridor now separate security, cleaning, and technical maintenance into distinct procurement streams with independent performance metrics. This pattern is most visible among financial services and professional services firms with standardized regional workplace policies.
Africa Facility Management Market Segmentation
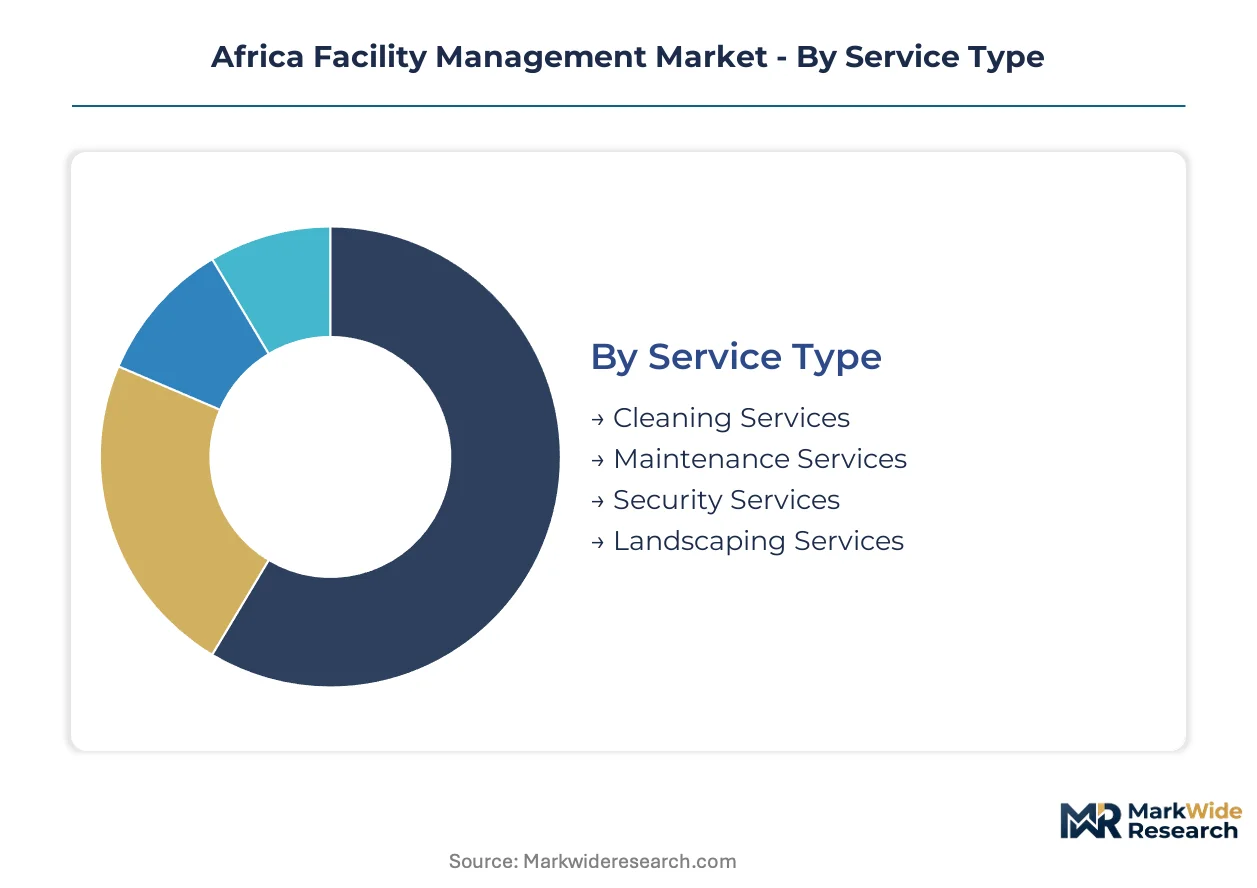
Service differentiation across Africa's facility management sector tracks divergent labor intensity, technology readiness, and regulatory exposure. Procurement patterns reveal how multinational tenants prioritize integrated platforms while public sector clients optimize for cost containment.
Service Type:
Technical specifications determine margin structure and workforce certification requirements across the service spectrum.
- Cleaning Services:Labor-intensive operations deploy chemical agents subject to REACH-equivalent trade bloc standards. Demand clusters in Nigeria's Lagos commercial corridor where multinational tenants mandate ISO-certified hygiene protocols for Class A office stock.
- Maintenance Services:HVAC and electrical system upkeep requires certified technician labor that outpaces vocational training output in secondary cities. South Africa's updated National Building Regulations compel energy and safety compliance upgrades, expanding contract values for technical maintenance bundles.
- Security Services:Personnel deployment dominates, though technology integration accelerates in premium commercial segments.
- Landscaping Services:Water-scarce regions drive xeriscaping specifications and native species mandates.
Mature deployment sits with Maintenance Services. Newer deployment is concentrated in Security Services technology integration.
End User:
Cost tier segmentation separates premium-grade integrated contracts from commodity service procurement.
- Commercial Buildings:Class A office complexes in Johannesburg and Cape Town embed sub-metering infrastructure into lease agreements under BIS-aligned national standards. Kenya's Energy Regulatory Authority building codes compel consumption monitoring systems, expanding technology-integrated contract penetration.
- Healthcare Facilities:Hospital groups across Nigeria and South Africa consolidate non-core operations into outsourced bundled agreements covering maintenance, cleaning, and security. Infection control specifications exceed general commercial standards.
- Educational Institutions:Public budget constraints favor basic service tiers with limited technology deployment.
- Residential Complexes:Gated community security bundles dominate, with maintenance lagging commercial sophistication.
Volume concentration rests with Commercial Buildings. Margin expansion is steepest in Healthcare Facilities.
Technology:
Application maturity varies sharply between legacy building stock and new construction.
- IoT Solutions:Wireless sensor networks for HVAC and lighting control enable remote diagnostics without hardwired backbone infrastructure. Facility managers in Lagos and Nairobi deploy distributed architectures that reduce truck-roll dependency for routine interventions.
- Integrated Software:Enterprise platforms compress contract negotiation cycles as multinational tenants demand real-time performance visibility. CSRD disclosure requirements from European-headquartered multinationals accelerate ESG data collection mandates across facility supply chains.
- Cloud Platforms:Scalable deployment suits mid-market property portfolios with limited IT infrastructure.
- Automation Tools:Building management system integration faces compatibility barriers with colonial-era West African commercial stock.
Customer adoption concentrates in Integrated Software. Technology integration is expanding most quickly in IoT Solutions.
Contract Model:
Procurement structure reflects client risk appetite and strategic control preferences.
- Outsourced Contracts:Full delegation dominates volume as public infrastructure budgets tighten across the continent. Bidvest Facilities Management and Tsebo Solutions Group compete for bundled service portfolios in South Africa.
- Hybrid Agreements:Clients retain strategic control while delegating operational execution, gaining share as corporate real estate teams unbundle long-term contracts into modular components with shorter renewal cycles.
- In-House Management:Persists in government facilities with civil service workforce constraints.
- Time and Material:Reactive procurement for ad-hoc maintenance in smaller property portfolios.
Procurement maturity centers on Outsourced Contracts. Structural shift is accelerating toward Hybrid Agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Nigeria, South Africa, Kenya, Egypt, and Morocco concentrate facility management demand through tax-incentivized commercial development corridors.
South Africa
Johannesburg and Cape Town Class A office complexes embed sub-metering infrastructure under BIS-aligned national standards. The country's updated National Building Regulations compel rapid energy and safety compliance upgrades. Bidvest Facilities Management and Tsebo Solutions Group compete intensively for bundled service portfolios in Gauteng and Western Cape commercial corridors.
Nigeria
Lagos commercial corridor multinational tenants mandate ISO-certified hygiene protocols and integrated property management. The Federal Ministry of Environment sustainability directives shape technology procurement decisions. Hospital groups across Lagos and Abuja consolidate non-core operations into outsourced agreements covering maintenance, cleaning, and security.
Kenya
Nairobi facility managers deploy wireless sensor networks for HVAC and lighting control without hardwired backbone infrastructure. The Energy Regulatory Authority building codes compel consumption monitoring systems in commercial properties above specified floor areas. Technology-integrated contracts expand as property owners submit verified energy data to national registries.
Egypt
Cairo and Alexandria commercial property stocks drive demand for maintenance and security bundled contracts. Contrack Facilities Management S.A.E. anchors competitive positioning through deep specialization in technical services. Government infrastructure budgets tighten, accelerating outsourced service adoption across public facilities.
Morocco
Casablanca and Rabat commercial centers attract European-headquartered multinationals mandating CSRD-aligned ESG data collection across facility supply chains. REACH-equivalent chemical safety standards reduce cross-border compliance friction for providers seeking multi-country contracts. Hybrid agreements gain share as clients retain strategic control while delegating operational execution.
Africa Facility Management Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across contract value tiers. Market structure tilts toward consolidation in South Africa and Nigeria while remaining fragmented in East African secondary cities. Three archetypes dominate: integrated platform operators bundling multiple service lines, security-centric providers layering technology onto personnel deployment, and healthcare-education specialists with deep vertical expertise. Competitive moves center on geographic expansion into underpenetrated corridors and technology partnerships for IoT-enabled service delivery.
Among integrated platform operators, Bidvest Facilities Management and Tsebo Solutions Group exemplify the diversified conglomerate archetype through multi-service bundling across commercial and institutional segments. Servest Africa occupies a position representing the security-centric model with bundled cleaning and technical maintenance add-ons. These three anchors illustrate how competitive positioning stratifies between breadth-driven scale and vertical specialization depth.
| Leading Market Players |
|---|
| Bidvest Facilities Management |
| Tsebo Solutions Group |
| Apleona GmbH |
| Servest Africa |
| G4S Africa |
| Contrack Facilities Management S.A.E. |
| Broll Property Group |
| Excellerate Services |
| Integrico Private Limited |
| Others |
Value Chain & Pricing Dynamics
Certified HVAC technician concentration in Johannesburg and Cape Town compresses labor-cost differentials across service tiers, widening the spread between premium technology-integrated contracts and commodity maintenance bundles in secondary African cities.
Pricing Analysis
Lead-time-driven pricing separates urgent-response premiums from scheduled-maintenance discounts across African facility management contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and IoT integration depth. Price differentiation hinges on ISO-certified hygiene protocols versus basic cleaning specifications. Pricing pressure stems from diesel fuel volatility in generator-dependent operations. Public sector clients in education and government facilities exhibit highest price sensitivity, while healthcare and Class A commercial tenants prioritize compliance over cost.
Supply Chain Analysis
Regional distribution centers in Johannesburg and Lagos anchor hub-and-spoke patterns for IoT sensors and building automation hardware across African markets. Supply concentration centers on China, South Korea, and Germany for critical components. Raw material dependencies include lithium-ion batteries, semiconductor chips, and specialized HVAC refrigerants. Single-source vulnerability through the Durban-Cape Town corridor and Lagos port creates structural risk. Distribution runs through authorized dealer networks with technical certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
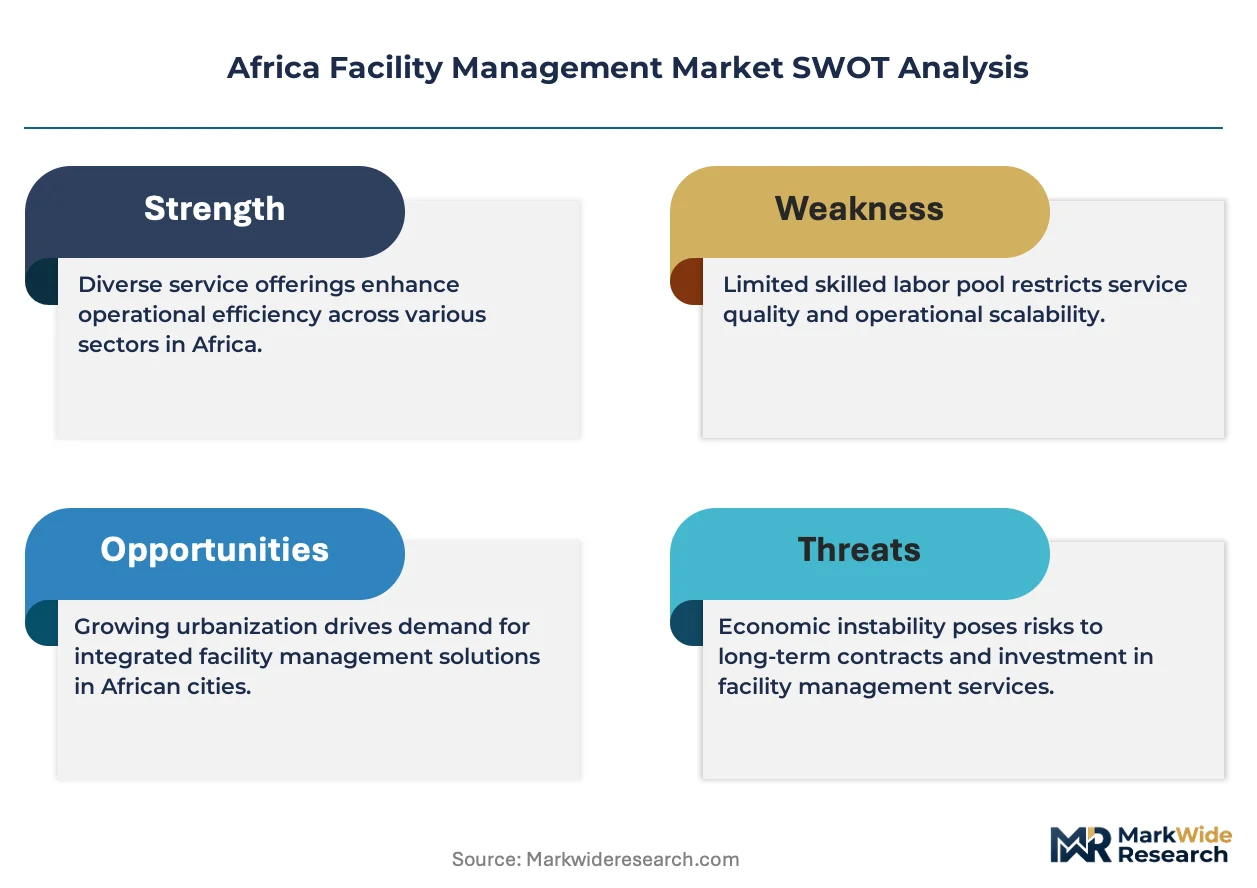
South Africa's updated National Building Regulations function as a cost-of-compliance moat, elevating capital requirements for market entry while rewarding incumbent certification investments.
For Market Incumbents: Extend predictive maintenance capabilities through machine learning analytics layered onto existing building management systems. Bidvest Facilities Management and Tsebo Solutions Group should deepen technician certification pipelines to defend against skilled labor scarcity. Vertical integration into cloud platform partnerships addresses the non-negotiable software requirements emerging in multinational tenant RFPs.
For New Entrants and Emerging Players: Begin with Ethiopia and Tanzania's underpenetrated commercial property corridors where integrated facility management penetration lags Southern African benchmarks. Target healthcare infrastructure expansion in Nigeria's secondary cities outside Lagos. Pursue security-cleaning bundled contracts as the most penetrable entry wedge before expanding into technical maintenance.
For Investors and Strategic Acquirers: Re-rating potential sits with healthcare-education specialists given CSRD disclosure acceleration forcing ESG data collection across European-headquartered multinational supply chains. Long-term viability favors providers with captive technology capabilities or exclusive cloud platform partnerships. Watch hybrid agreement share gains as the inflection signal separating scalable platforms from commodity service vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Wireless sensor deployment in Lagos and Nairobi reduces truck-roll dependency for routine HVAC interventions. |
| Technician Certification Pipeline | South Africa's National Building Regulations compel rapid compliance upgrades that strain contractor capacity. |
| Healthcare Vertical Specialization | Hospital groups across Nigeria consolidate non-core operations into outsourced bundled service agreements. |
| East African Geographic Expansion | Ethiopia and Tanzania commercial property stocks lack integrated facility management penetration relative to benchmarks. |
| CSRD-Aligned ESG Data Infrastructure | European-headquartered multinationals mandate sustainability reporting across African facility supply chains. |
Study Parameters
Multi-period observation of contract value migration, technology adoption curves, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with facility management executives, commercial property portfolio managers, healthcare infrastructure planners, and government procurement officers. Secondary validation drew from Kenya Energy Regulatory Authority filings, South African National Building Regulations updates, Nigerian Federal Ministry of Environment directives, trade bloc harmonization documents, and European CSRD implementation guidance. Bottom-up service line sizing and top-down macroeconomic triangulation cross-checked volume estimates.
Segment-weighting approaches modeled service type, end user vertical, technology deployment, and contract structure dimensions throughout the forecast period. CAGRs derived from regression analysis against construction spending, healthcare infrastructure investment, and commercial property stock expansion trajectories. Forecast inputs incorporated diesel price volatility assumptions and grid reliability indices affecting generator-dependent maintenance operations.
Underlying measurement precision varies by segment; IoT-enabled technology contracts and integrated software carry tighter precision than commodity cleaning and security services due to disclosed platform pricing. Forecasts reflect documented assumptions regarding regulatory implementation timelines and multinational tenant policy standardization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
United Arab Emirates Facility Management Market
Facility Management
New Zealand Facility Management Market
Facility Management
Netherlands Facility Management Market
Facility Management
Iceland Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
France Facility Management Market
Facility Management
Finland Facility Management Market
Facility Management
Asia-Pacific Soft Facility Management Market
Facility Management
Germany Facility Management Market
Facility Management
Norway Facility Management Market
Facility Management
Malaysia Facility Management Market
Facility Management
Ireland Facility Management Market
Facility Management
South Africa Facility Management Market
Facility Management
Middle East and Africa Hard Facility Management Market
Facility Management
Chile Facility Management Market
Facility Management
Austria Facility Management Market