
 Malta Facility Management Market | 2026-2036
Malta Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Malta Facility Management Market Foresight
Asset-light leasing and project finance models is fragmenting competitive boundaries in Malta's facility management sector, allowing mid-tier operators to bid on contracts historically reserved for integrated providers. Sodexo leverages its hospitality heritage to anchor premium service lines in tourism-dependent assets. CBRE Group, Inc. competes through its cross-border property platform, while Clentec Malta Limited specializes in locally rooted technical maintenance.
Facility management encompasses the integrated coordination of building operations, maintenance, cleaning, security, and environmental systems to ensure functional, safe, and efficient built environments across commercial, institutional, and residential assets. Technical specifications typically span HVAC performance thresholds, energy benchmarking protocols, and preventive maintenance scheduling aligned with equipment lifecycle parameters. Cleaning and maintenance services occupy the mature revenue core, while IoT-based technology segments attract accelerated investment as building automation demand intensifies. Software solutions and mobile apps are gaining traction among medium and large client types seeking real-time work order visibility.
Malta's facility management sector operates under the EU Energy Performance of Buildings Directive, national building codes enforced by the Building and Construction Authority, and occupational health standards administered by the Occupational Health and Safety Authority. These frameworks mandate energy audits, safety certifications, and accessibility compliance that elevate service complexity and favor qualified operators. Stakeholders must monitor how forthcoming EU sustainability disclosure requirements reshape procurement criteria and contractor qualification thresholds.
Market Dynamics
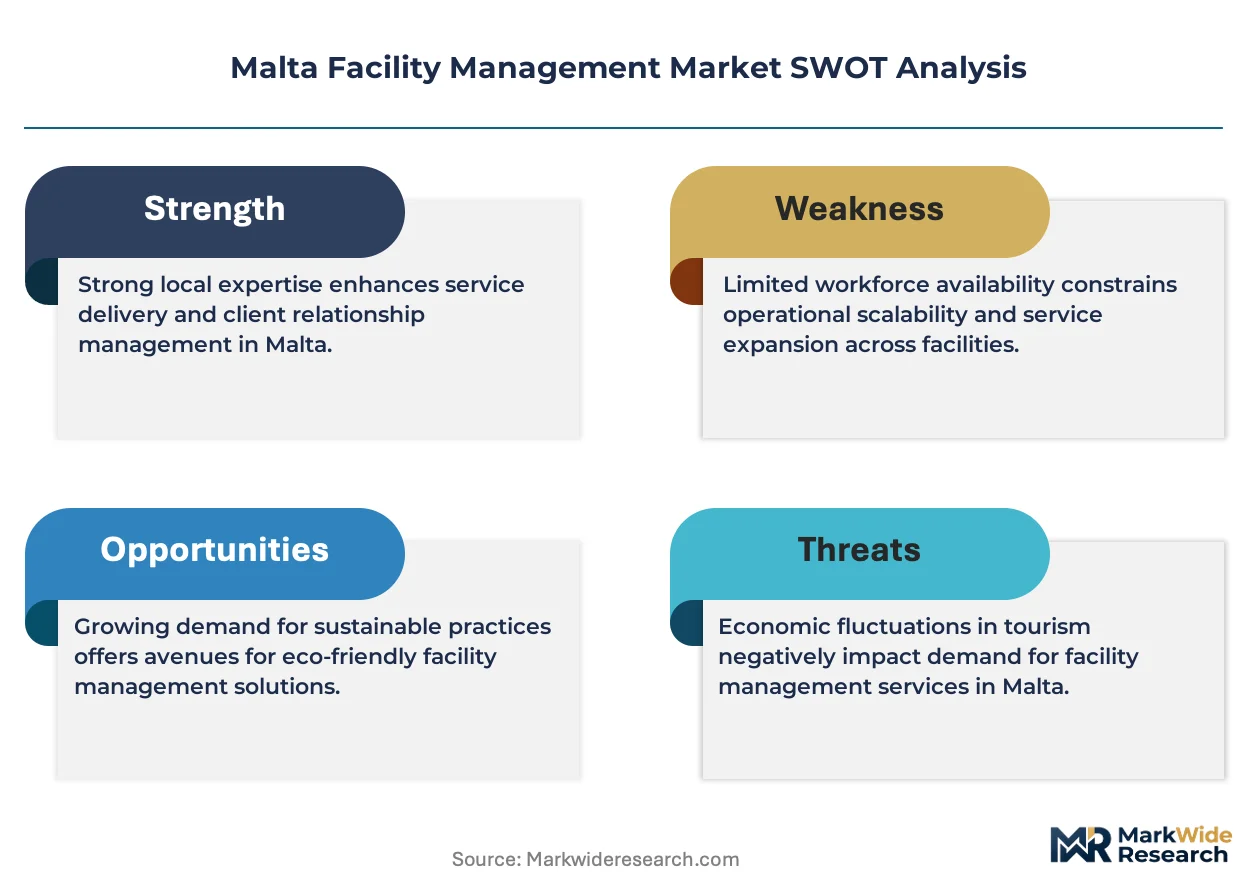
Malta's facility management sector is restructuring around the EU Energy Performance of Buildings Directive, which mandates energy audits and retrofits across commercial portfolios. This regulatory pressure compresses service timelines and elevates technical qualification thresholds for contractors operating in the Greater Valletta corridor.
Growth Catalysts
- Healthcare estate modernization:Hospital infrastructure expansion in Malta is extending outsourced FM contract scopes to encompass clinical equipment maintenance and infection control protocols.
- EU Green Deal compliance deadlines:Building renovation requirements under the Energy Performance of Buildings Directive are accelerating demand for energy auditing and HVAC retrofit services.
- Tourism asset premiumization:Hospitality clusters in Valletta, Sliema, and St. Julian's are specifying integrated FM packages combining technical maintenance with guest-facing service lines.
Market Restraints
- Labor pool constraints:Malta's small domestic workforce limits availability of certified HVAC technicians and building automation specialists, constraining service expansion.
- Import dependency for smart building components:IoT sensors and building management system hardware concentrate supply from German and Italian manufacturers, exposing operators to euro-denominated cost volatility.
- Regulatory compliance fragmentation:Divergent enforcement timelines between the Building and Construction Authority and Occupational Health and Safety Authority create permitting bottlenecks for multi-site contracts.
Strategic Opportunities
- Gozo island underpenetration:Secondary hospitality and residential developments in Malta's northern island present first-mover advantages for integrated FM providers with ferry-logistics capabilities.
- CSRD-aligned sustainability reporting:Corporate Sustainability Reporting Directive requirements are creating advisory service adjacencies for FM operators capable of documenting building-level carbon performance.
- Convergence of predictive maintenance AI with mobile workforce platforms:Technology integration enables real-time dispatch optimization for technical teams serving dispersed commercial portfolios.
Industry Challenges
- Multi-certification timelines:Operators must secure separate credentials from the Building and Construction Authority for structural work and the Occupational Health and Safety Authority for operational safety, extending qualification periods.
- Legacy BMS integration complexity:Older commercial buildings in Valletta's historic core require customized retrofit approaches incompatible with standardized smart building platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malta Facility Management Market |
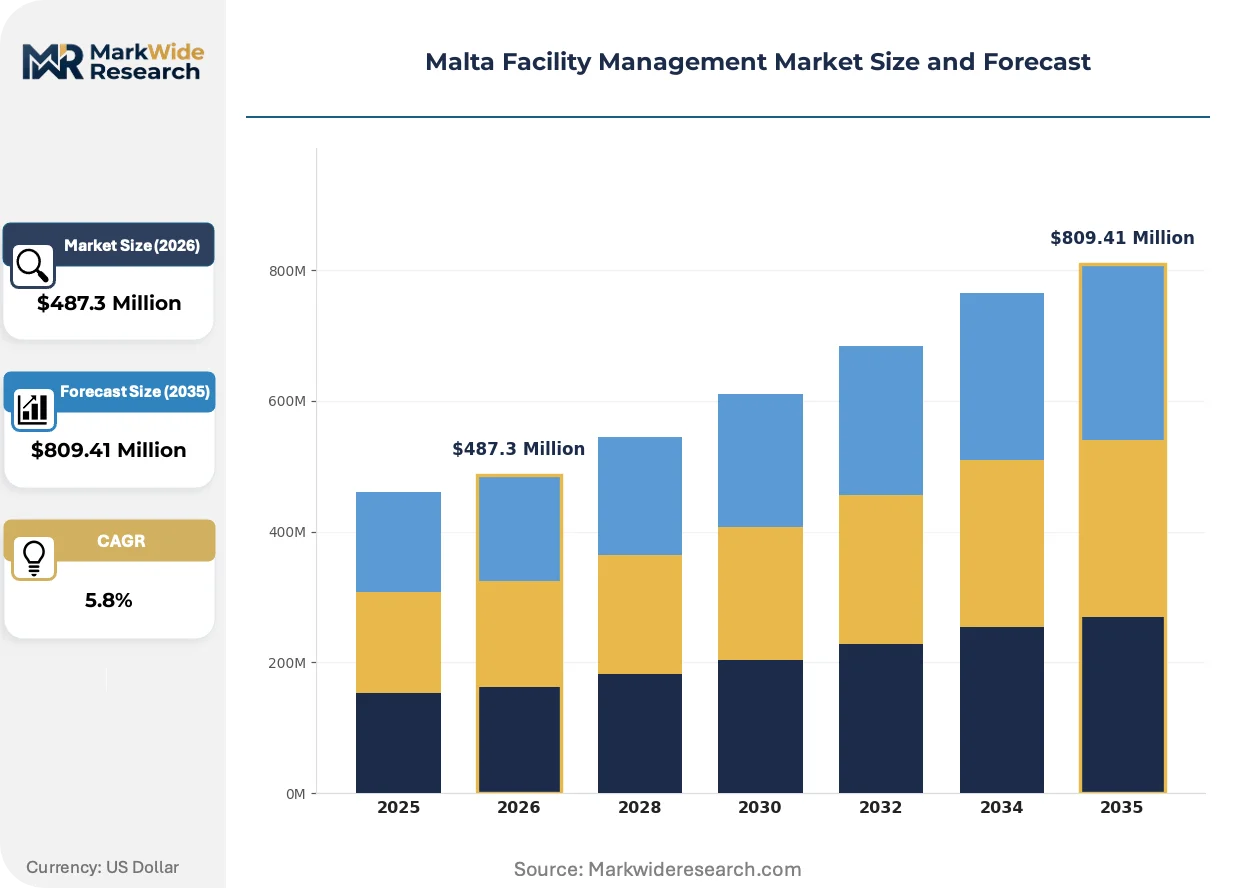
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Maintenance, Security, Landscaping Client Type: Commercial, Residential, Educational, Healthcare Technology: IoT-Based, Software Solutions, Automated Systems, Mobile Apps Size: Small, Medium, Large, Enterprise |
| Companies Covered | Emeric Facility Services, Sodexo, CBRE Group, Inc., FMcore, ISS Facility Services, Inc., Jones Lang LaSalle Incorporated, SMI Facility Services, Clentec Malta Limited, Cushman & Wakefield plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malta Facility Management Market Shifts & Advancements
Building automation and data-driven service delivery are reconfiguring competitive capabilities across Malta's FM landscape. Technology migration, regulatory tightening, and procurement evolution constitute the three dominant vectors of change.
Building management systems are migrating from on-premise server architectures to cloud-native platforms with API-based integration. Mid-sized commercial landlords in Msida and Birkirkara are adopting these platforms fastest, driven by portfolio consolidation needs. This technology shift is compressing maintenance response windows from days to hours while elevating cybersecurity requirements for FM providers.
The EU Energy Performance of Buildings Directive is tightening operational compliance through mandatory energy audits and renovation roadmaps. Commercial property owners must now document asset-level performance trajectories to 2030. Healthcare estates and tourism-dependent assets face the steepest compliance gradients, driving bundled service contracts that combine technical maintenance with energy advisory.
Service contracting is fragmenting from single-source integrated agreements toward modular, performance-guaranteed work packages. Financial services tenants in Ta' Xbiex are unbundling cleaning, security, and technical maintenance to specialist providers with sector-specific credentials. This pattern concentrates in premium-grade office stock where tenant churn accelerates re-tendering cycles.
Malta Facility Management Market Segmentation
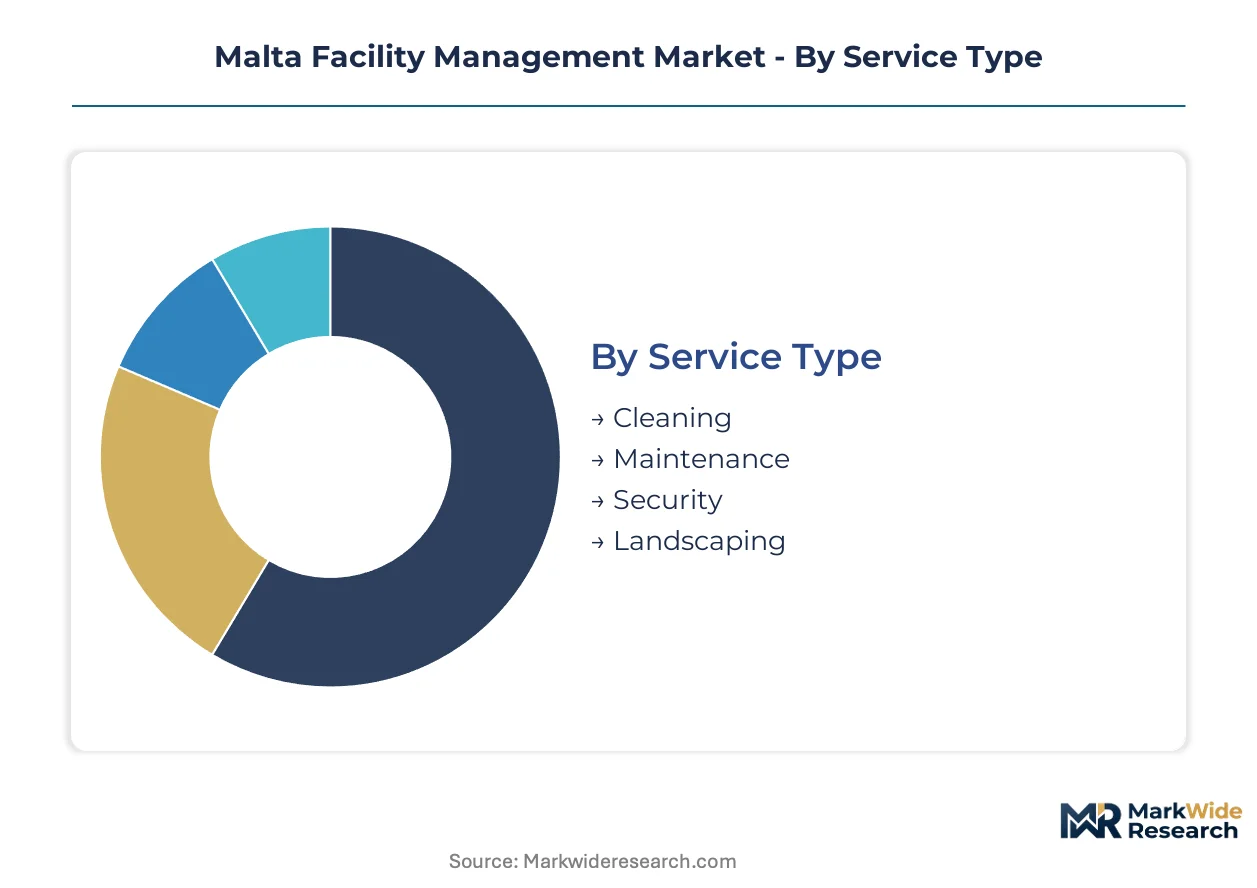
Service configuration in Malta's facility management sector reflects the island's compressed geography and concentrated asset clusters. Procurement patterns diver sharply between tourism-dependent hospitality assets and regulated healthcare estates, creating distinct operational requirements across each segment dimension.
Service Type:
Cost tier differentiation separates commoditized offerings from premium integrated bundles in Malta's service marketplace.
- Cleaning:Mature revenue core encompassing daily janitorial operations, specialized sanitization for healthcare estates, and guest-facing housekeeping in Valletta-Sliema tourism corridors. Demand concentrates in hospitality assets where brand standards mandate premium service levels alongside the Building and Construction Authority's hygiene certifications.
- Maintenance:Technical services span HVAC performance optimization, electrical systems, and preventive scheduling aligned with equipment lifecycle parameters under Occupational Health and Safety Authority oversight. Hospital infrastructure modernization in Malta is extending outsourced scopes to clinical equipment maintenance and infection control protocols.
- Security:Personnel-based guarding and access control systems for commercial portfolios and residential developments.
- Landscaping:Grounds maintenance for hospitality assets, corporate campuses, and public spaces.
Maintenance commands the established base. The steepest expansion runs through cleaning as healthcare estates upgrade sanitization standards.
Client Type:
Application-specific requirements reshape contractor qualification thresholds across Malta's end-use verticals.
- Commercial:Office stock in Ta' Xbiex and financial services clusters demand modular contracting with sector-specific credentials. Financial services tenants are unbundling cleaning, security, and technical maintenance to specialist providers, accelerating re-tendering cycles in premium-grade buildings.
- Healthcare:Hospital estates require bundled contracts combining technical maintenance with clinical equipment servicing and energy advisory under EU Energy Performance of Buildings Directive compliance. The EU Green Deal mandates energy audits and renovation roadmaps that elevate service complexity.
- Residential:Multi-unit developments and gated communities requiring integrated FM packages.
- Educational:Schools and university facilities with seasonal demand patterns and accessibility compliance requirements.
Healthcare commands the established base. The steepest expansion runs through commercial as financial services procurement fragments toward specialist providers.
Technology:
Customer type sophistication determines adoption velocity for digital service delivery platforms across Malta's contractor base.
- IoT-Based:Sensor networks and building automation systems migrating from on-premise architectures to cloud-native platforms with API-based integration. Mid-sized commercial landlords in Msida and Birkirkara are adopting these platforms fastest, driven by portfolio consolidation needs.
- Software Solutions:Work order management, asset tracking, and compliance documentation systems. Real-time visibility platforms are gaining traction among medium and large client types seeking dispatch optimization for dispersed commercial portfolios.
- Automated Systems:Robotic cleaning equipment and autonomous security patrols with limited penetration due to labor pool constraints.
- Mobile Apps:Field technician enablement and tenant service request portals with compressed maintenance response windows from days to hours.
Software solutions command the established base. The steepest expansion runs through IoT-based segments as building automation demand intensifies.
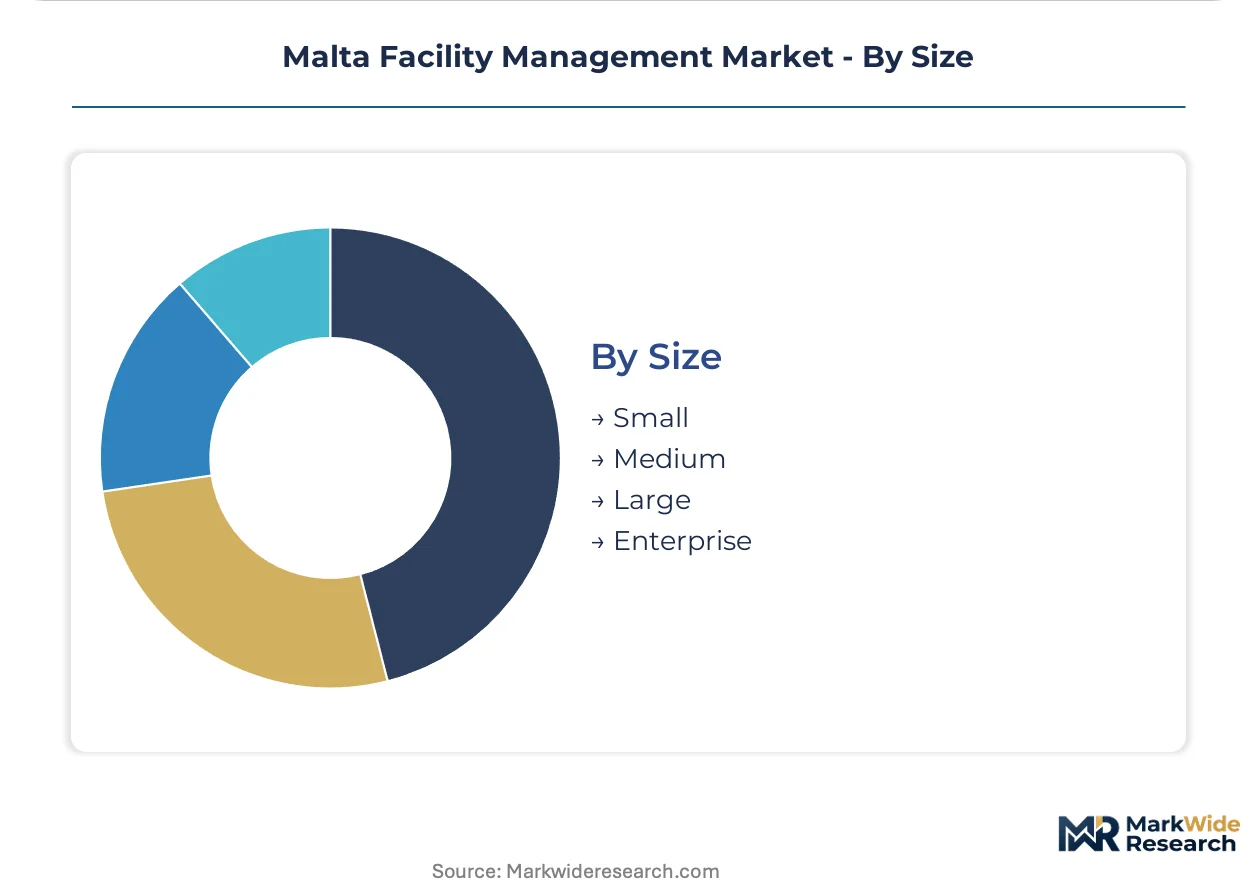
Size:
Volume concentration in Malta's Greater Valletta corridor shapes contract scalability requirements across operator tiers.
- Large:Integrated multi-service contracts spanning 50,000+ square meter portfolios, typically in tourism and financial services clusters. Asset-light leasing and project finance models are fragmenting competitive boundaries, allowing mid-tier operators to bid on contracts historically reserved for integrated providers.
- Enterprise:National-scale agreements covering dispersed healthcare estates or hospitality chains with ferry-logistics requirements for Gozo island coverage.
- Medium:Single-building or small portfolio contracts with unbundled service procurement.
- Small:Residential and micro-commercial accounts with localized operator relationships.
Large contracts command the established base. The steepest expansion runs through enterprise segments as healthcare estate modernization extends outsourced FM scopes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal compliance deadlines are redistributing facility management contract flows across Mediterranean economies. Member states with concentrated tourism and financial services clusters face the steepest operational retrofit requirements under the Energy Performance of Buildings Directive.
Germany
Industrial manufacturing estates and logistics parks drive outsourced technical maintenance demand. The country's national building energy regulator enforces stringent HVAC efficiency standards under the F-Gas Regulation. The Rhine-Ruhr corridor concentrates contract volume where pharmaceutical and automotive facilities require integrated FM packages.
Italy
Heritage building stock and hospitality infrastructure create specialized conservation FM requirements. REACH compliance obligations elevate chemical handling protocols for cleaning and maintenance contractors. Milan's commercial district and Rome's tourism corridor attract premium service providers with dual technical and guest-facing capabilities.
France
Healthcare estate modernization and corporate campus expansion extend integrated FM scopes. The national pharmaceutical regulator mandates infection control standards that reshape hospital maintenance protocols. The Île-de-France region concentrates demand where financial services and public hospital networks overlap.
Spain
Coastal tourism assets and logistics hubs drive seasonal and year-round service requirements. The national occupational safety authority enforces workplace certification standards that filter contractor eligibility. Barcelona's technology corridor and Madrid's financial district specify divergent service bundles.
United Kingdom
Commercial property decarbonization targets accelerate energy advisory and retrofit service demand. The Health and Safety Executive mandates risk assessment protocols for multi-site contracts. London's financial services cluster unbundles FM procurement toward specialist providers with sector-specific credentials.
Malta Facility Management Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Malta's compressed geography. The vendor base organizes around three tiers: integrated multinational platforms with cross-border property capabilities, mid-tier regional operators with ferry-logistics competencies, and locally rooted technical specialists. Strategic moves concentrate on portfolio diversification into energy advisory services and technology platform licensing rather than asset-heavy expansion.
Within the integrated platform tier, Sodexo leverages hospitality heritage to anchor premium service lines, while CBRE Group, Inc. competes through cross-border property platform scale. Clentec Malta Limited exemplifies the locally rooted specialist archetype with concentrated technical maintenance positioning.
| Leading Market Players |
|---|
| Emeric Facility Services |
| Sodexo |
| CBRE Group, Inc. |
| FMcore |
| ISS Facility Services, Inc. |
| Jones Lang LaSalle Incorporated |
| SMI Facility Services |
| Clentec Malta Limited |
| Cushman & Wakefield plc |
| Others |
Supply & Pricing Matrix
German and Italian IoT sensor manufacturers anchor the upstream hardware tier, concentrating margin capture in building management system integration services downstream. FM operators serving Malta's commercial portfolios absorb euro-denominated cost volatility while competing on technical certification depth.
Pricing Analysis
Certification level under the Building and Construction Authority and Occupational Health and Safety Authority creates the primary spread between premium and standard service tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with ISO-compliant technical maintenance commanding substantial premiums over basic janitorial contracts. Cost compression in the mid-tier is intensifying because asset-light leasing models allow mid-tier operators to bid on contracts historically reserved for integrated providers. Healthcare estates demonstrate the least price sensitivity due to mandatory infection control protocols, while small residential accounts exhibit the highest sensitivity to service rate adjustments.
Supply Chain Analysis
Tariff exposure between Italy and Malta dominates supply chain risk for smart building hardware components. Component sourcing draws from Germany, Italy, and the Netherlands for HVAC automation systems, IoT sensors, and building management software platforms. Raw material dependencies center on semiconductor chips, copper wiring, and specialized cleaning chemicals under REACH compliance. Single-source vulnerability concentrates in German-engineered BMS controllers. Distribution runs through ferry-connected logistics nodes serving the Greater Valletta corridor with secondary routing to Gozo island developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are proliferating as financial services tenants unbundle integrated FM contracts toward specialist providers with sector-specific credentials. This demand-side shift creates definable niches for qualified operators.
For Market Incumbents: Insulate core healthcare and tourism asset relationships through preemptive certification investments in EU Energy Performance of Buildings Directive compliance advisory. Deepen technical maintenance capabilities in clinical equipment servicing to offset margin pressure from modular procurement trends. Anchor integrated service bundles in hospital estates where infection control protocols create switching costs.
For New Entrants and Emerging Players: Establish a beachhead in Gozo island hospitality developments where ferry-logistics capabilities filter incumbent competition. Target secondary residential and boutique tourism assets with unbundled technical maintenance and energy auditing services. Lead with CSRD-aligned sustainability reporting capabilities to differentiate in commercial procurement cycles.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier operators with established Occupational Health and Safety Authority credentials and cloud-native platform architectures. Long-term viability hinges on technology-enabled service delivery models capable of spanning Malta's compressed geography with lean operational structures. Watch for inflection when EU sustainability disclosure requirements reshape procurement qualification thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Energy Advisory Service Launch | EU Energy Performance of Buildings Directive compliance creates bundled contract opportunities in healthcare estates. |
| Cloud-Native Platform Integration | API-based building management systems compress maintenance response windows for Msida and Birkirkara landlords. |
| CSRD Reporting Capability Buildout | Corporate Sustainability Reporting Directive requirements open advisory revenue streams in commercial portfolios. |
| Ferry-Logistics Infrastructure Investment | Gozo island underpenetration offers first-mover positioning in secondary hospitality developments. |
| Clinical Equipment Maintenance Certification | Hospital infrastructure modernization extends outsourced FM scopes beyond traditional building operations. |
Research Methodology
Operator-level perspectives from facility management directors, healthcare estate managers, commercial property landlords, and Building and Construction Authority officials anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through EU Energy Performance of Buildings Directive implementation documents, Occupational Health and Safety Authority certification records, and hospitality industry procurement databases. Customs data on IoT sensor imports, Building and Construction Authority permit filings, and healthcare estate modernization announcements provided quantitative anchors. Bottom-up service provider revenue estimates triangulated against top-down addressable market calculations.
Scenario-bracketing framed the analytical approach across the projection horizon, with baseline, accelerated regulatory compliance, and delayed healthcare modernization pathways modeled. Segmentation dimensions included service type configuration, client vertical, technology adoption tier, and contract scale category. CAGRs were derived from fitted growth curves applied to validated base-year estimates, with healthcare estate outsourcing intensity and tourism asset premiumization serving as key industry-specific forecast inputs.
Stress conditions across euro-denominated import cost volatility, labor pool availability for certified HVAC technicians, and regulatory enforcement timeline divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EU Green Deal implementation pacing and healthcare infrastructure investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Norway Facility Management Market
Facility Management
Latin America Facility Management Market
Facility Management
Singapore Facility Management Market
Facility Management
Ireland Facility Management Market
Facility Management
Latin America Soft Facility Management Market
Facility Management
United Arab Emirates Facility Management Market
Facility Management
Warehouse Management Service Market
Facility Management
Switzerland Facility Management Market
Facility Management
North America Hard Facility Management Market
Facility Management
Oman Facility Management Market
Facility Management
Austria Facility Management Market
Facility Management
Albania Facility Management Market
Facility Management
Nigeria Facility Management Services Market
Facility Management
Kuwait Facility Management Market
Facility Management
Argentina Facility Management Market
Facility Management
Soft Facility Management Market