
 New Zealand Facility Management Market | 2026-2036
New Zealand Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Facility Management Market Foresight
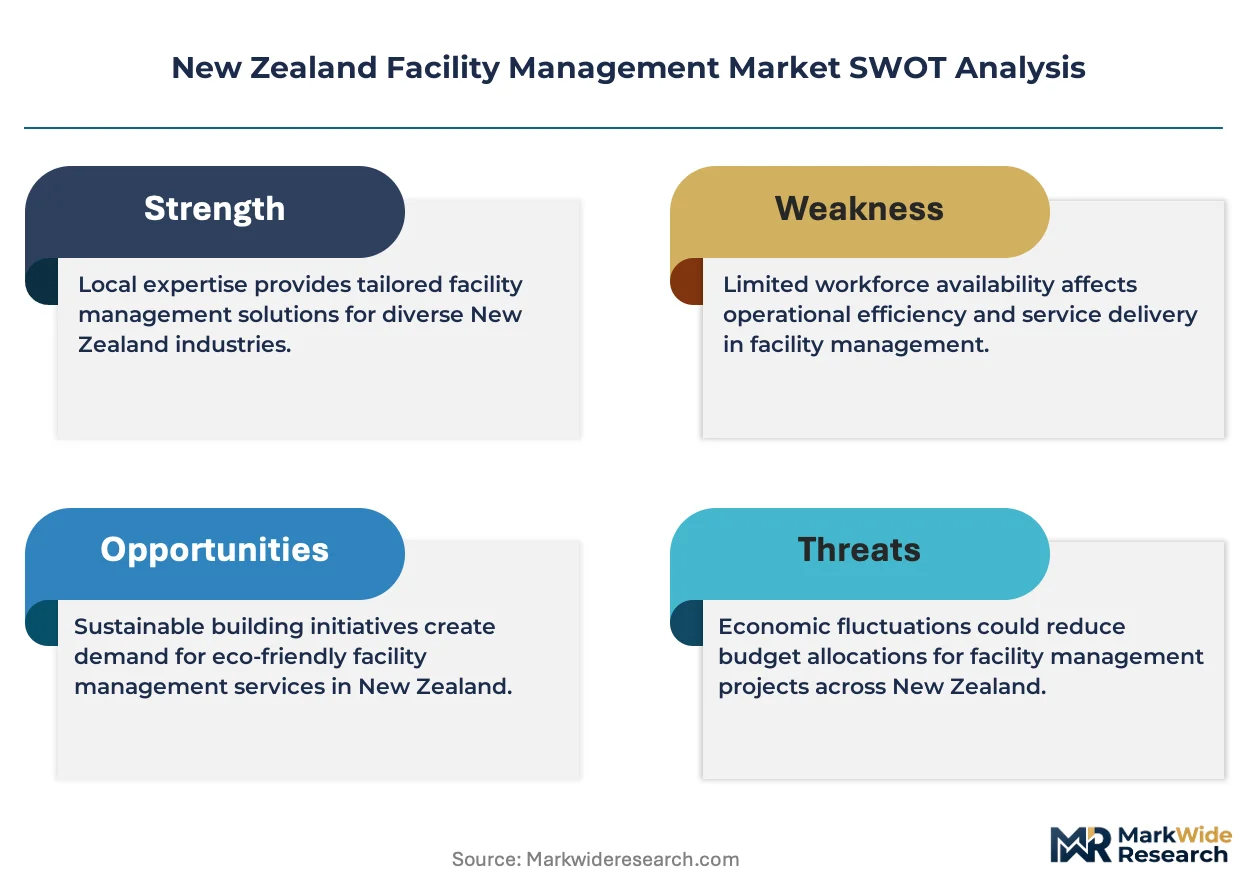
Project finance and operational leasing for public infrastructure assets is rewriting competitive dynamics in New Zealand facility management. Ventia Services Group leverages its infrastructure heritage to dominate transport and utilities contracts nationwide. Downer Group anchors its position through backward integration into engineering services that feed captive FM demand. ISS Facility Services NZ differentiates through technology-led service delivery across corporate and healthcare portfolios.
Facility management encompasses the integrated coordination of hard services (building systems maintenance, energy infrastructure upkeep) and soft services (cleaning, security, landscaping) to ensure operational continuity of built assets. The discipline applies technical protocols including HVAC performance benchmarking, preventive maintenance scheduling, and compliance auditing against building code standards. Cleaning and maintenance services command the largest revenue pools given their non-discretionary nature across all client categories, while IoT Solutions and Building Automation represent the fastest-expanding technology dimension as owners pursue energy cost reduction. Commercial and government client types generate the steadiest contract tenures, though healthcare facilities are emerging as a high-growth end user segment due to stringent infection control and equipment uptime requirements.
WorkSafe New Zealand governs occupational health and safety standards that directly shape cleaning chemical handling protocols and contractor accreditation requirements. The New Zealand Building Code, administered by the Ministry of Business, Innovation and Employment, mandates energy performance thresholds that drive demand for building automation and energy management retrofits. Stakeholders must weigh capital deployment into predictive maintenance platforms against the risk of margin compression from fixed-price public contracts that carry escalating compliance burdens.
Market Dynamics
The New Zealand Facility Management Market is undergoing structural recalibration as the Ministry of Business, Innovation and Employment tightens energy performance thresholds through Building Code updates, forcing asset owners to choose between compliance capex and operational penalties.
Growth Catalysts
- Healthcare Infrastructure Modernization:District Health Boards are consolidating facilities and outsourcing non-clinical operations to specialized FM providers capable of meeting infection control protocols.
- WorkSafe NZ Enforcement Intensification:Stricter contractor accreditation requirements for hazardous substance handling are driving demand for certified cleaning and maintenance specialists.
- Auckland Commercial Stock Expansion:Premium office developments in the CBD and Wynyard Quarter are creating sustained demand for integrated hard and soft service contracts.
Market Restraints
- Skilled Technician Scarcity:Immigration constraints have tightened the labor pool for HVAC and building automation specialists, inflating wage costs.
- Fixed-Price Contract Rigidity:Public infrastructure tenders with decade-long tenures expose operators to margin erosion from unindexed compliance cost escalations.
- Energy Input Volatility:Spot electricity price fluctuations complicate guaranteed savings clauses in energy performance contracts.
Strategic Opportunities
- IoT-Enabled Predictive Maintenance:Sensor networks and AI-driven analytics platforms allow FM providers to shift from scheduled to condition-based servicing, capturing premium pricing.
- Wellington Government Asset Outsourcing:Central agency consolidation of property portfolios creates openings for bundled FM contracts across ministries.
- Christchurch Rebuild Transition:Post-earthquake construction completion is shifting focus from build to operate-maintain phases, requiring long-term FM partnerships.
Industry Challenges
- Legacy System Integration Complexity:Aging BMS infrastructure in 1990s commercial stock resists seamless connection to modern cloud-based energy management platforms.
- Certification Timeline Compression:WorkSafe NZ accreditation renewals for hazardous substance contractors now require documented training hours that strain smaller operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Facility Management Market |
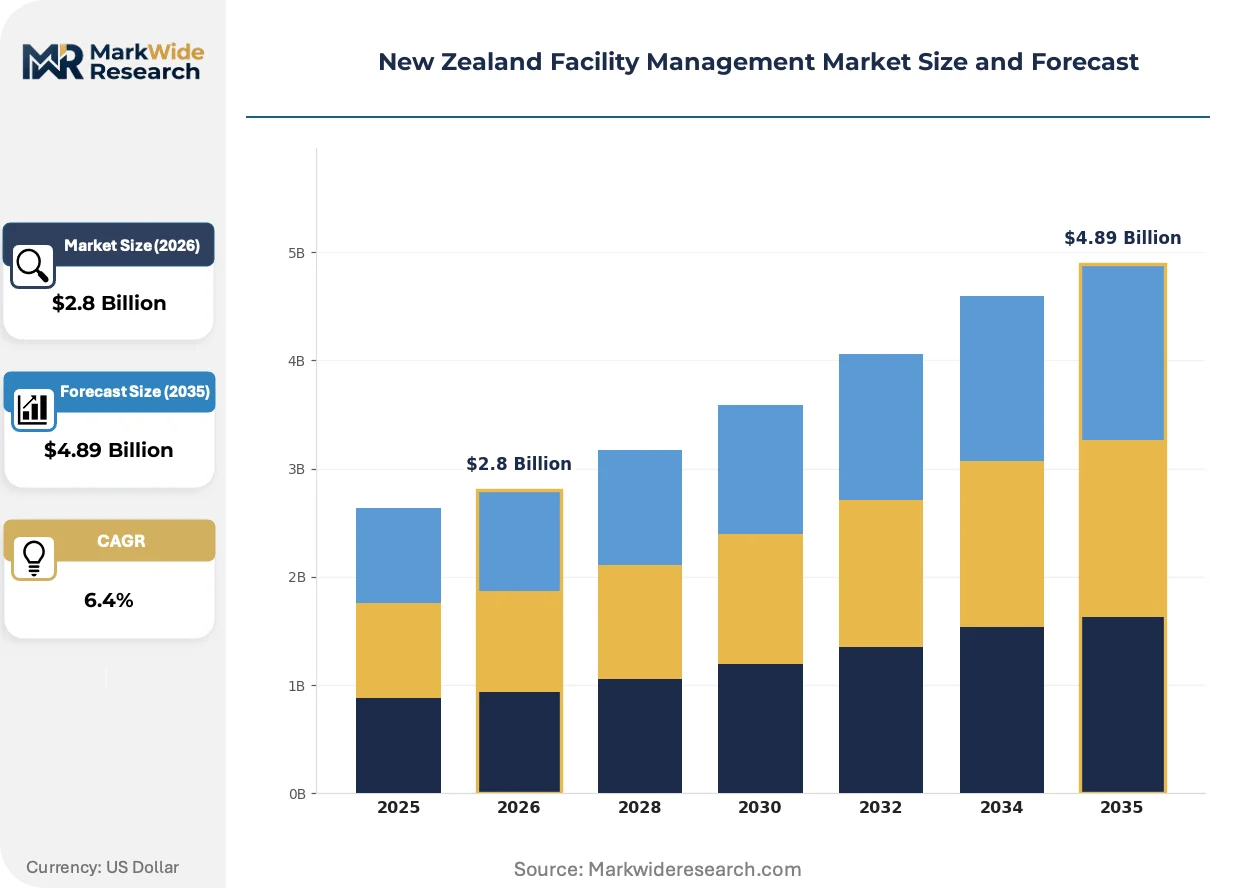
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Maintenance, Security, Landscaping Client Type: Commercial, Industrial, Government, Educational Technology: IoT Solutions, Building Automation, Energy Management, Software Tools End User: Corporate Offices, Retail Spaces, Healthcare Facilities, Residential Complexes |
| Companies Covered | Professional Property and Cleaning Services Ltd, Ventia Services Group, OCS New Zealand, ISS Facility Services NZ, Downer Group, Spotless (Downer Company), Infratel Networks Limited, Cushman and Wakefield Services NZ, PAE New Zealand, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Facility Management Market Shifts & Advancements
Digital instrumentation and regulatory tightening are converging to transform how New Zealand facility operators procure, measure, and pay for asset maintenance services.
Cloud-based building analytics platforms are rendering obsolete the spreadsheet-driven energy reporting that dominated corporate property management for two decades. Large commercial landlords in Auckland's CBD are adopting these systems within eighteen-month procurement cycles. The shift is compressing RFP evaluation periods and disqualifying vendors lacking real-time dashboard capabilities.
The New Zealand Building Code's updated energy efficiency mandates are forcing retrofit programs across commercial portfolios. MBIE enforcement timelines require compliance documentation by specified certification deadlines. Healthcare facilities face the steepest adaptation curves given simultaneous infection control and climate system performance requirements.
Consolidated service bundling is displacing single-service contracting across government and corporate accounts. Property managers are negotiating master agreements covering hard services, cleaning, security, and landscaping under unified KPI frameworks. This pattern is most pronounced in Wellington's parliamentary precinct and Auckland's public transport hubs.
New Zealand Facility Management Market Segmentation
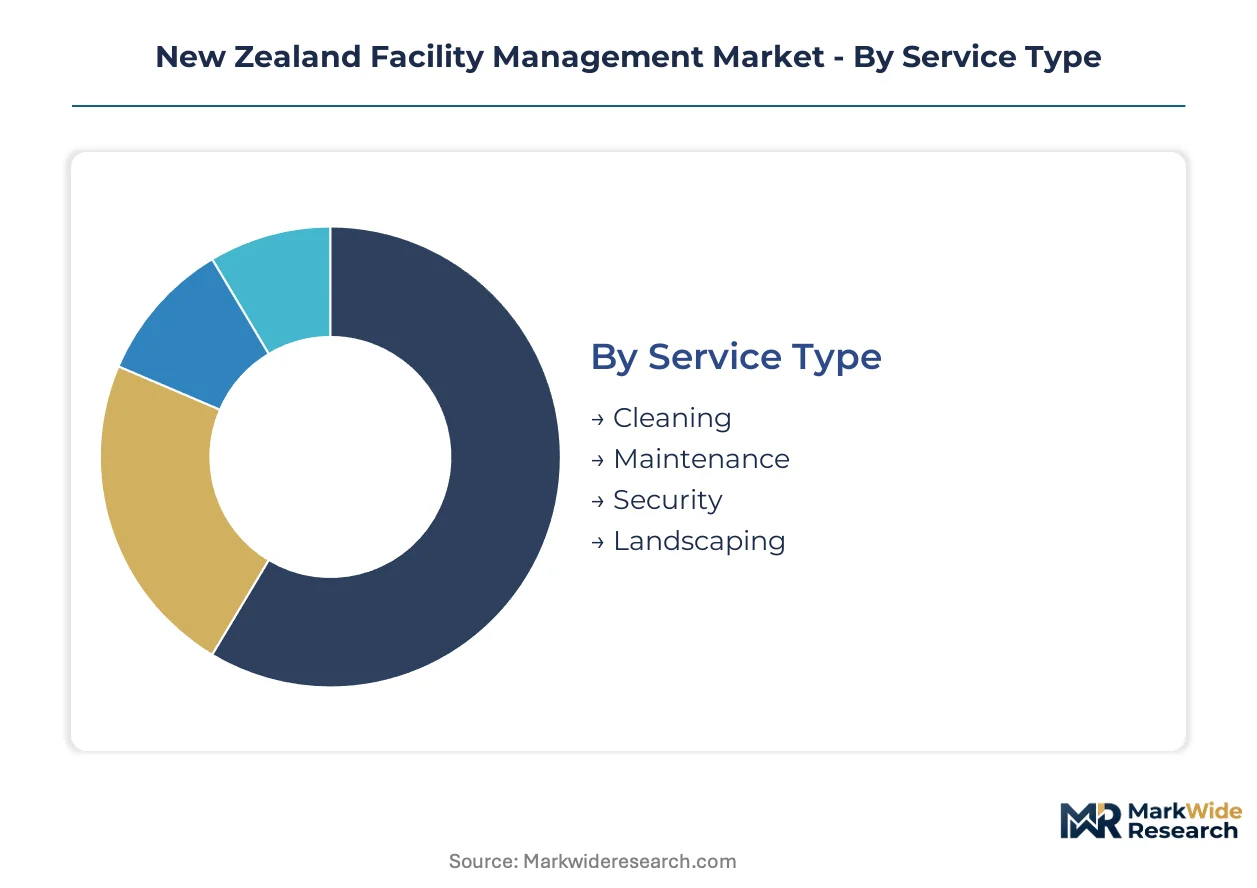
Facility management procurement in New Zealand stratifies across service intensity, asset complexity, and regulatory exposure. Each segmentation dimension reveals distinct margin structures and contract tenure patterns that shape provider positioning.
Service Type:
Service portfolios span from labor-intensive recurring tasks to technology-augmented infrastructure oversight, with cost-to-serve ratios varying by technical specialization.
- Cleaning:Encompasses infection control protocols, hazardous chemical handling under WorkSafe NZ accreditation, and specialized healthcare sanitation. District Health Boards in Auckland and Wellington drive premium pricing for certified operators meeting dual compliance standards.
- Maintenance:Hard services covering HVAC systems, electrical infrastructure, and building envelope integrity. Auckland's premium commercial stock generates sustained demand for preventive maintenance contracts tied to Building Code energy performance thresholds.
- Security:Personnel-based and electronic surveillance services protecting corporate and government assets. Wellington's parliamentary precinct concentrates high-assurance requirements.
- Landscaping:Grounds maintenance and environmental compliance for commercial and public spaces. Christchurch rebuild projects sustain contract volumes.
The dominant share belongs to Cleaning, while Maintenance is closing the gap fastest.
Client Type:
Contract economics diverge sharply between private sector flexibility and public sector rigidity, with tenure lengths and indexation terms defining provider selection criteria.
- Commercial:Corporate landlords and tenant organizations procuring integrated hard and soft services. Auckland CBD and Wynyard Quarter developments favor bundled contracts with unified KPI frameworks.
- Industrial:Manufacturing and logistics facilities requiring specialized maintenance for production-critical systems. Port facilities and distribution centers concentrate demand.
- Government:Central agencies and Crown entities consolidating property portfolios. Wellington-based ministries are shifting toward master agreements covering multiple ministries.
- Educational:Universities and polytechnics managing aging campus infrastructure. Tertiary institutions face deferred maintenance backlogs and sustainability retrofit mandates.
Commercial contracts yield the widest margins, though Government is expanding most quickly through central agency consolidation.
Technology:
Digital adoption separates premium-positioned operators from commodity competitors, with procurement cycles accelerating for vendors offering real-time visibility.
- IoT Solutions:Sensor networks enabling condition-based monitoring of building systems. Large Auckland landlords now require IoT capabilities within RFP evaluation windows.
- Building Automation:Integrated control systems for HVAC, lighting, and access management. MBIE enforcement timelines for Building Code compliance are accelerating retrofit demand.
- Energy Management:Platforms optimizing consumption patterns and documenting efficiency gains. Guaranteed savings clauses face pressure from spot electricity price volatility.
- Software Tools:Cloud-based work order management and compliance documentation systems. Smaller operators struggle with legacy system integration complexity.
Building Automation commands the largest technology spend, while IoT Solutions is climbing the fastest as sensor costs decline and analytics capabilities mature.
End User:
Asset-specific operational requirements create distinct service specifications, with healthcare and corporate segments driving divergent capability investments.
- Corporate Offices:Premium CBD stock requiring integrated hard and soft services with sustainability reporting. Auckland's commercial precincts concentrate contract value.
- Retail Spaces:High-traffic environments demanding rapid-response maintenance and flexible cleaning schedules. Shopping centers prioritize uptime guarantees.
- Healthcare Facilities:Hospitals and clinics with stringent infection control and equipment uptime requirements. District Health Board consolidation is expanding outsourced FM scope.
- Residential Complexes:Body corporate-managed apartments and retirement villages. Aging building stock in major cities drives maintenance demand.
Corporate Offices retain the deepest contract penetration, yet Healthcare Facilities are gaining share fastest as clinical infrastructure modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's facility management sector operates as a net service importer, with specialized technical capabilities and technology platforms flowing primarily from Australia and global FM networks. The domestic market concentrates in three metropolitan zones where commercial density and public infrastructure investment create contract volume.
Auckland
Auckland's premium CBD office stock and Wynyard Quarter developments generate the densest FM contract concentration nationwide. WorkSafe NZ enforcement of contractor accreditation standards shapes procurement criteria across commercial precincts. The central business district and transport hubs sustain integrated hard and soft service bundles under unified KPI frameworks.
Wellington
Wellington's parliamentary precinct and central agency property portfolios drive government-focused FM demand with high-assurance security requirements. The Ministry of Business, Innovation and Employment administers Building Code compliance timelines that accelerate retrofit procurement across Crown-owned assets. Ministries are consolidating toward master agreements spanning multiple departments.
Christchurch
Christchurch's post-earthquake rebuild transition shifts construction expenditure toward operate-maintain phases. Canterbury District Health Board consolidation of clinical facilities expands outsourced non-clinical operations. The central city rebuild zone sustains long-term FM partnerships as assets transition from build to operational stewardship.
Hamilton
Hamilton's logistics and distribution corridor generates industrial facility management demand for production-critical systems maintenance. The Port of Tauranga connectivity supports manufacturing and warehousing clusters requiring specialized HVAC and electrical upkeep. Waikato District Health Board facilities add healthcare-specific infection control requirements to regional service specifications.
New Zealand Facility Management Market Competitive Landscape
On the supply side, the industry is moderately consolidated around infrastructure heritage players and global FM networks, with tiered positioning between integrated providers and specialized operators. Three archetypes dominate: engineering-construction conglomerates with backward integration into captive FM demand, Australian-headquartered infrastructure service platforms leveraging trans-Tasman capability transfer, and global FM networks deploying standardized technology platforms. Competitive dynamics center on public infrastructure tender participation and technology-led service differentiation.
Within the infrastructure heritage tier, Ventia Services Group and Downer Group exemplify engineering-rooted market presence, with the latter anchoring position through integrated construction-to-operations capability chains. ISS Facility Services NZ occupies the global network position, representing technology-forward service delivery archetypes. These three entities collectively illustrate the competitive tension between domestic infrastructure legacy and international platform standardization.
| Leading Market Players |
|---|
| Professional Property and Cleaning Services Ltd |
| Ventia Services Group |
| OCS New Zealand |
| ISS Facility Services NZ |
| Downer Group |
| Spotless (Downer Company) |
| Infratel Networks Limited |
| Cushman and Wakefield Services NZ |
| PAE New Zealand |
| Others |
Supply & Pricing Matrix
Undercapacity in Auckland's HVAC technician labor pool is compressing margins across maintenance contracts while simultaneously elevating pricing power for certified operators who can meet WorkSafe NZ accreditation demands. This utilization imbalance feeds directly into supplier selection criteria and contract indexation negotiations.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term pricing structure across New Zealand facility management, with ten-year public infrastructure tenders dominating procurement volumes. Price differentiation separates premium-tier providers holding WorkSafe NZ hazardous substance certifications from standard operators lacking documented training hours. Cost compression in fixed-price government contracts is intensifying because compliance burdens escalate without indexation relief. District Health Boards demonstrate the least price sensitivity given infection control mandates, while educational institutions face the tightest budget constraints.
Supply Chain Analysis
Tariff exposure between Australia and New Zealand dominates supply chain risk for building automation hardware and IoT sensor components. Equipment sourcing draws from Australia, China, and Singapore, with control systems and sensor networks resting on semiconductor inputs, copper wiring, and cloud computing infrastructure. Single-source vulnerability concentrates in proprietary BMS platforms that resist integration with modern energy management systems. Distribution runs through engineering-construction conglomerates and global FM networks that bundle procurement across trans-Tasman capability transfers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-house FM capabilities retained by large corporate landlords pose the central substitution threat that specialized providers must neutralize through demonstrable compliance and technology differentiation.
For Market Incumbents: Harden contract renewal positions by embedding IoT-enabled predictive maintenance platforms that generate condition-based servicing data competitors cannot replicate. Deepen backward integration into engineering services that feed captive demand for hard services maintenance. Certification investment in WorkSafe NZ hazardous substance handling creates switching costs that neutralize price-only challengers.
For New Entrants and Emerging Players: Establish a beachhead in Wellington's central agency property consolidation, where master agreements spanning multiple ministries are displacing fragmented single-service contracts. Target Christchurch's post-earthquake rebuild transition as assets shift from construction to operate-maintain phases. Lead with cloud-based compliance documentation systems that accelerate procurement cycles for legacy-burdened competitors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among infrastructure heritage players with decade-long transport and utilities contracts. Long-term viability hinges on technology platform standardization that scales across trans-Tasman operations. Acquisition candidates should demonstrate integrated hard-soft service bundling capability. The signal to monitor is District Health Board outsourcing velocity as clinical infrastructure modernization accelerates.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Deployment | Sensor networks enable condition-based servicing that commands premium pricing from Auckland commercial landlords. |
| WorkSafe NZ Certification Investment | Documented hazardous substance training creates defensible positioning against non-accredited competitors in healthcare. |
| Master Agreement Consolidation | Bundled hard and soft services under unified KPI frameworks capture Wellington government portfolio rationalization. |
| Backward Integration into Engineering | In-house construction-to-operations capability chains anchor captive demand for preventive maintenance contracts. |
| Cloud-Based Compliance Documentation | Real-time dashboard capabilities disqualify spreadsheet-dependent vendors from MBIE-mandated retrofit procurement. |
Research Methodology
Initial hypotheses were tested against primary input from facility management executives, property portfolio directors, WorkSafe NZ accreditation officers, and District Health Board procurement managers and refined through secondary validation against MBIE Building Code enforcement timelines, WorkSafe NZ contractor registry data, Crown entity property consolidation disclosures, and Auckland commercial development permits. Bottom-up contract value aggregation was cross-checked against top-down market sizing from engineering services revenue disclosures.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by service type, client category, technology adoption tier, and regional metropolitan zone. CAGRs were derived from fitted growth curves applied to documented contract tenures and procurement cycle frequencies. Forecast inputs incorporated District Health Board consolidation timelines, Christchurch rebuild phase transitions, and Auckland commercial stock completion schedules.
Sensitivities concentrate around immigration policy shifts affecting HVAC technician availability and electricity spot price volatility impacting guaranteed savings clauses. Forecasts reflect assumptions about regulatory enforcement intensity and technology adoption curves that could revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Argentina Facility Management Market
Facility Management
Saudi Arabia Soft Facility Management Market
Facility Management
Middle East and Africa Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
Panama Facility Management Market
Facility Management
Brazil Facility Management Market
Facility Management
Thailand Facility Management Market
Facility Management
Luxembourg Facility Management Market
Facility Management
United Arab Emirates Facility Management Market
Facility Management
Croatia Facility Management Market
Facility Management
Mexico Facility Management Market
Facility Management
Asia-Pacific Soft Facility Management Market
Facility Management
India Facility Management Market
Facility Management
Philippines Facility Management Market
Facility Management
Africa Facility Management Market
Facility Management
Australia Facility Management Market