
 Slovenia Facility Management Market | 2026-2036
Slovenia Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Slovenia Facility Management Market Analytics
Asset-light service contracting and operational leasing of building systems is reconfiguring competitive entry barriers for mid-sized FM providers. Sodexo Slovenia leverages its integrated service platform to anchor multi-site corporate accounts across Ljubljana and Maribor. CBRE GWS sustains competitive positioning through technology-led workplace management and centralized procurement scale. Protim Ržišnik Perc d.o.o. specializes in engineering-heavy maintenance for industrial facilities along the Slovene-Austrian border corridor.
Facility management encompasses the coordinated delivery of hard services (mechanical, electrical, plumbing maintenance) and soft services (cleaning, security, catering) to ensure operational continuity, safety, and regulatory compliance of built assets. Hard services typically require certified technician deployment, SLA-bound response times under 24 hours for critical systems, and compliance with EN 15221 facility management standards. Cleaning and Maintenance within Service Type capture the largest revenue pools due to universal building code mandates and aging public infrastructure renewal cycles. IoT Solutions and AI Platforms across Technology represent the fastest-expanding segment as Slovenia's public sector tenders increasingly mandate real-time energy telemetry and predictive fault detection.
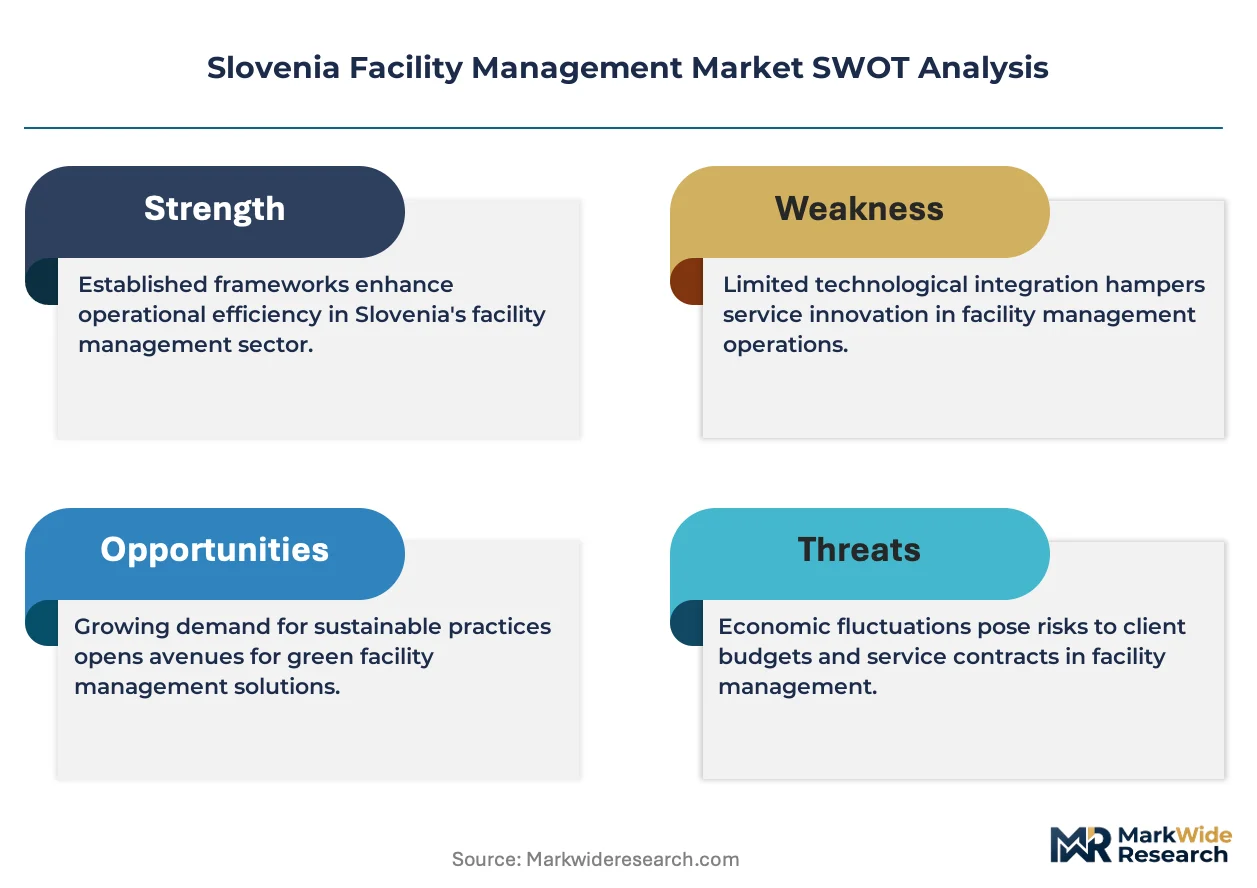
Slovenia's Ministry of Public Administration enforces public procurement rules that favor FM contractors with ISO 41001 certification and documented carbon reduction protocols. The country's adoption of EU CSRD reporting obligations is pushing corporate real estate owners to demand audited FM performance data on energy intensity and waste diversion. Stakeholders must weigh technology capital commitments against the contracting risk of multi-year public sector tenders that now embed decarbonization KPIs as mandatory evaluation criteria.
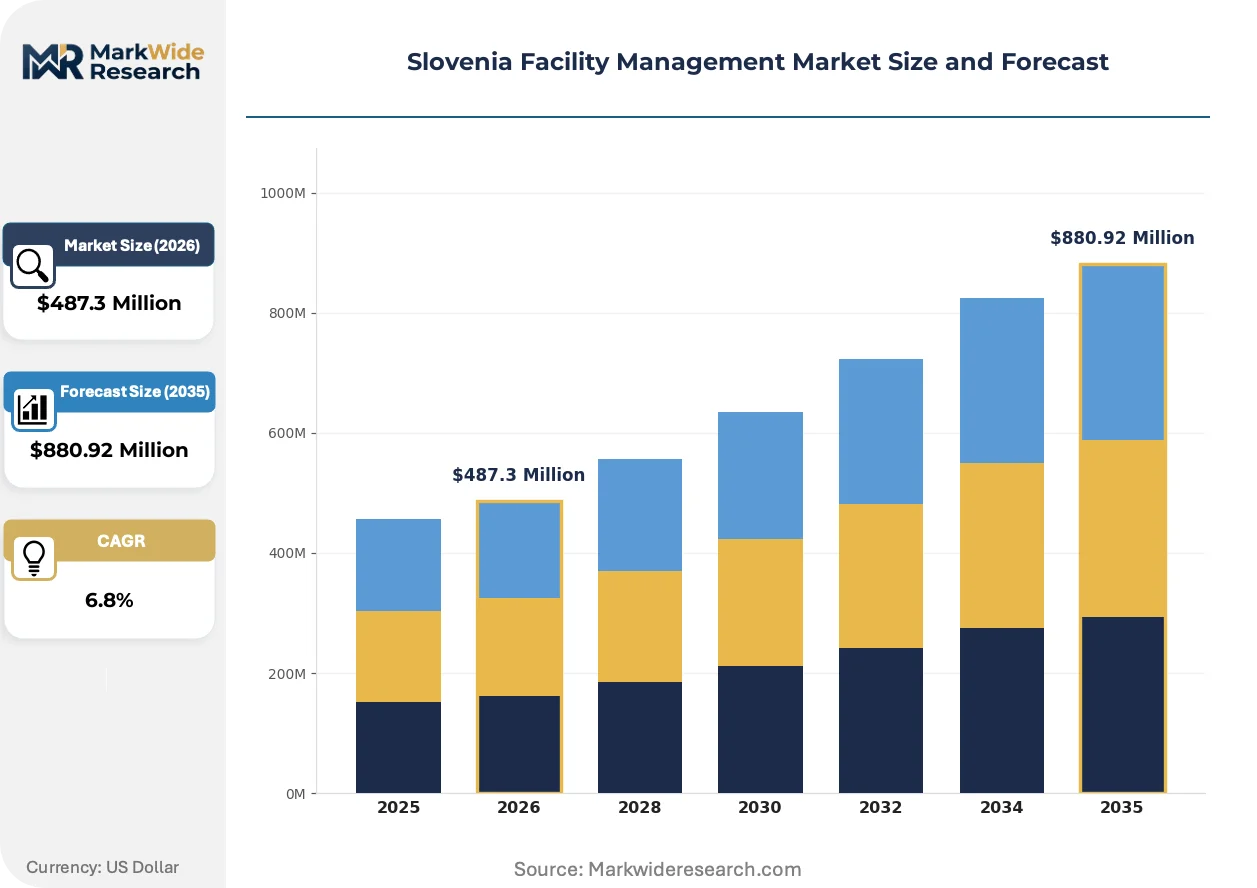
Market Dynamics
Slovenia's facility management sector faces a structural pivot as the EU Energy Performance of Buildings Directive transposition forces state-owned building portfolios toward mandatory digital energy monitoring, compressing traditional service margins while elevating technology-enabled providers.
Growth Catalysts
- CSRD Reporting Mandates:Corporate real estate owners now demand audited FM performance data on energy intensity and waste diversion, expanding the addressable market for compliance-integrated service providers.
- Public Healthcare Estate Expansion:Ljubljana and Maribor hospital networks are lengthening outsourced FM contract durations and scope, creating multi-year revenue visibility for specialized operators.
- IoT-Enabled Predictive Maintenance:Real-time fault detection systems are reducing unplanned downtime in aging public infrastructure, justifying premium pricing for technology-augmented hard services.
Market Restraints
- Certified Technician Scarcity:EN 15221-qualified mechanical and electrical specialists command wage premiums that compress field service margins, particularly in the Ljubljana urban corridor.
- ISO 41001 Compliance Burden:Public procurement rules now weight certification and carbon documentation heavily, disqualifying smaller operators from state tender participation.
- Technology Capital Intensity:Real-time energy telemetry platforms require upfront sensor deployment and cloud infrastructure investment that strains mid-sized FM balance sheets.
Strategic Opportunities
- Maribor Secondary Market Penetration:Commercial stock modernization lags Ljubljana by several years, creating first-mover advantage for integrated platform operators willing to establish regional service hubs.
- Industrial Corridor Specialization:The Slovene-Austrian border zone hosts manufacturing facilities requiring engineering-heavy maintenance that commands higher margins than standard commercial cleaning and security.
- Operational Leasing Convergence:Asset-light contracting models for HVAC and building automation systems are opening recurring revenue streams distinct from traditional time-and-materials billing.
Industry Challenges
- Multi-Year Tender Risk Allocation:Public sector contracts now embed decarbonization KPIs as mandatory evaluation criteria, forcing FM providers to assume performance risk on energy outcomes they do not fully control.
- Legacy System Integration Complexity:Predictive maintenance platforms must interface with decades-old building automation infrastructure in Slovenia's state-owned portfolio, extending deployment timelines and eroding project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slovenia Facility Management Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Maintenance, Security, Landscaping Facility Type: Commercial Buildings, Industrial Sites, Residential Complexes, Educational Institutions Client Type: Corporations, Government Agencies, Nonprofits, Private Owners Technology: Building Management Systems, IoT Solutions, Energy Management Tools, AI Platforms |
| Companies Covered | First Facility d.o.o., FMG Facility Management Group, Sodexo Slovenia, Protim Ržišnik Perc d.o.o., ses European Slovenia, CBRE GWS, Diversey Slovenia, Iskra Facility Management, MG Facility Management d.o.o., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slovenia Facility Management Market Evolving Landscape
Digital telemetry and predictive analytics are reconfiguring competitive advantage in Slovenian facility management, compressing response windows and elevating data transparency from differentiating feature to baseline procurement requirement.
IoT sensor networks for energy and equipment monitoring are migrating from pilot deployments to standard contract inclusions. Ljubljana-based corporate headquarters and public administration buildings are adopting these systems fastest, with procurement specifications now mandating API-accessible dashboards. This technology shift is compressing the competitive set to providers with in-house software development or platform partnerships, marginalizing pure staffing-based operators.
The EU CSRD and Slovenia's transposed Energy Performance of Buildings Directive are mandating granular energy disclosure from state-owned and large corporate real estate portfolios. Building owners must now source verified FM performance data on carbon intensity and operational efficiency, creating procurement pressure for audited, standardized reporting formats. Public healthcare estates in Ljubljana and Maribor are responding by bundling energy management into integrated FM contracts rather than retaining separate energy service companies.
Corporate real estate buyers are consolidating vendor relationships across multi-site portfolios, replacing fragmented single-service contracts with integrated hard-plus-soft service platforms. This pattern concentrates procurement authority within Ljubljana-based headquarters functions, reducing the addressable market for regional specialists. The shift favors operators with centralized help desks, unified SLA frameworks, and cross-functional technician deployment capabilities.
Slovenia Facility Management Market Segmentation
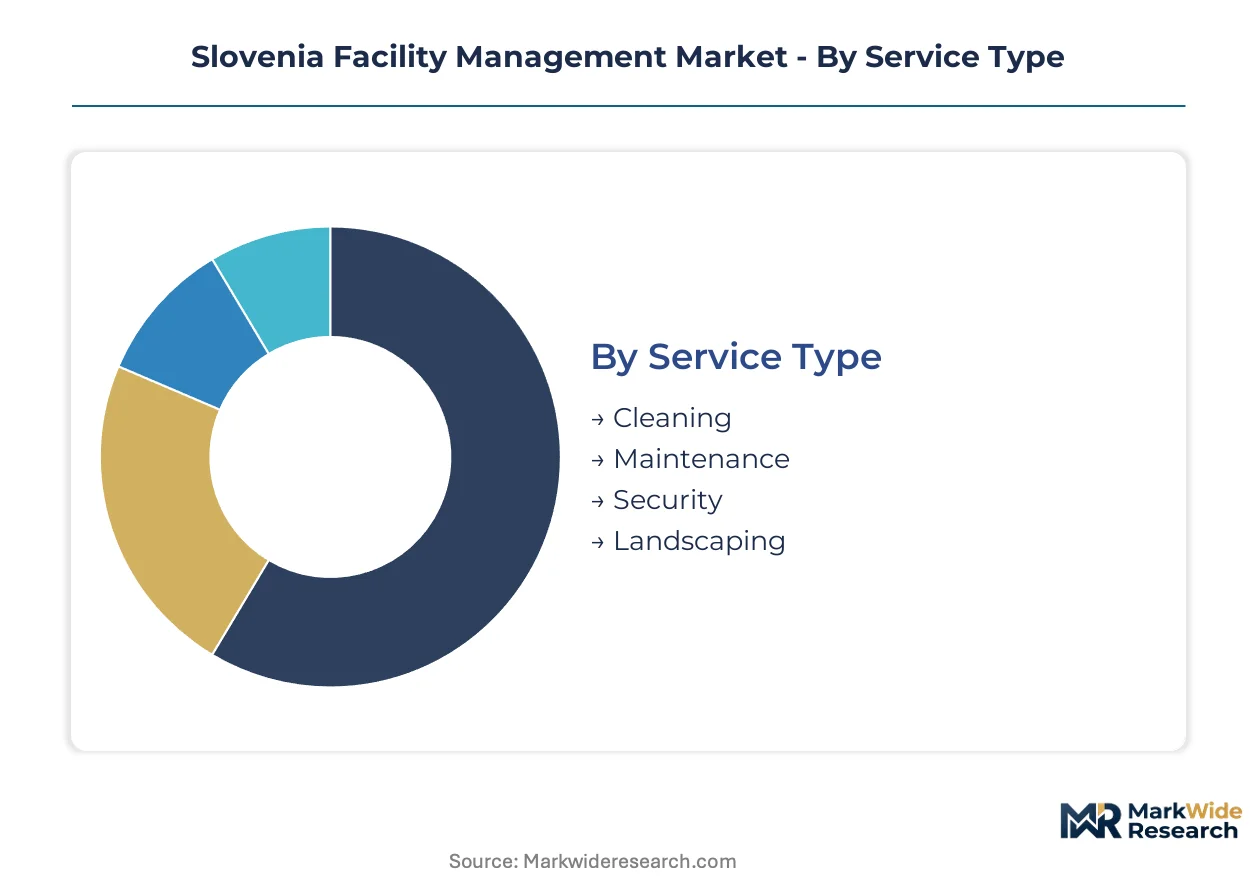
Facility management procurement in Slovenia fragments across service intensity, asset class, and technology sophistication. Contract renewal cycles vary dramatically—from monthly cleaning schedules to decade-long integrated facilities agreements—creating distinct competitive dynamics within each segment cluster.
Service Type:
Cleaning contracts turn over fastest with 12-18 month typical durations, while integrated maintenance agreements extend 3-7 years and lock in vendor relationships through embedded asset knowledge.
- Cleaning:Labor-intensive service requiring EN 16636 certification for commercial disinfection protocols. Demand concentrates in Ljubljana healthcare estates and corporate headquarters where infection control standards have tightened under Ministry of Health directives. Wage inflation for certified staff compresses margins while contract frequency sustains volume.
- Maintenance:Hard services spanning mechanical, electrical, and plumbing systems with SLA-bound response mandates under 24 hours for critical infrastructure. Industrial facilities along the Slovene-Austrian border corridor anchor demand, driven by manufacturing uptime requirements and cross-border supply chain integration.
- Security:Personnel-based and technology-augmented guarding services governed by Slovenia's Private Security Act. Banking and pharmaceutical distribution centers in Ljubljana drive premium segment demand.
- Landscaping:Seasonal grounds maintenance with lowest capital barriers to entry. Municipal contracts in Maribor and regional administrative centers provide baseline volume.
Maintenance anchors the volume base while IoT-augmented service bundles gain share at the steepest rate.
Facility Type:
Cost tiers stratify sharply across asset classes, with industrial sites commanding 40-60% premium pricing over standard commercial due to specialized equipment and safety compliance requirements.
- Commercial Buildings:Office stock concentrated in Ljubljana's BTC City and Šiška district, where lease structures increasingly pass FM costs to tenants. CSRD reporting obligations are forcing landlords to demand metered energy data and verified carbon disclosures from service providers.
- Industrial Sites:Manufacturing and logistics facilities requiring ATEX-certified maintenance for hazardous zones and 24/7 operational continuity. The border corridor from Kranj to Maribor hosts automotive and electronics production with the most demanding technical specifications.
- Residential Complexes:Multi-unit housing with standardized, price-sensitive procurement. Ljubljana's new-build developments are beginning to specify smart building integration.
- Educational Institutions:Public sector tendering with heavy ISO 41001 weighting and extended payment terms. University campuses in Ljubljana and Maribor represent the largest concentrated demand pool.
Commercial buildings generate the highest contract frequency while industrial sites deliver the strongest margin profile.
Client Type:
Procurement authority and contract duration diverge substantially, with government agencies mandating multi-year frameworks and corporations favoring flexible, performance-indexed agreements.
- Corporations:Multi-site portfolios with centralized procurement functions in Ljubljana headquarters. These buyers are consolidating vendors across hard and soft services, favoring integrated platform operators with unified SLA frameworks and cross-functional technician deployment.
- Government Agencies:Public procurement under Ministry of Public Administration rules with mandatory ISO 41001 certification and documented carbon reduction protocols. Hospital networks in Ljubljana and Maribor are extending contract durations and expanding scope.
- Nonprofits:Cost-constrained segment with fragmented demand and limited contract scale.
- Private Owners:Single-asset or small portfolio holders with price-sensitive, transactional procurement patterns.
Government agencies anchor contract value stability while corporations are driving the fastest platform consolidation.
Technology:
Adoption maturity spreads across a decade-wide spectrum, from legacy building automation to predictive AI platforms requiring substantial upfront sensor deployment.
- Building Management Systems:Centralized control platforms for HVAC, lighting, and access systems. State-owned buildings undergoing EU Energy Performance of Buildings Directive compliance are retrofitting these systems fastest.
- IoT Solutions:Real-time sensor networks for energy and equipment monitoring migrating from pilot to standard contract inclusion. Ljubljana corporate headquarters now mandate API-accessible dashboards in procurement specifications.
- Energy Management Tools:Software platforms for carbon accounting and efficiency optimization. These are expanding most quickly as CSRD mandates force verified disclosure of operational energy intensity.
- AI Platforms:Predictive fault detection and automated work order generation. Deployment remains concentrated among technology-enabled providers with in-house development capabilities.
Building management systems retain the largest installed base while AI platforms are climbing the fastest adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Slovenia's facility management sector operates as a net service importer from Austria and Italy, with cross-border contracting concentrated in the Ljubljana-Maribor corridor where Austrian engineering firms supply specialized industrial maintenance.
Ljubljana Urban Region
Corporate headquarters and public healthcare estates drive integrated FM demand. The Ministry of Public Administration enforces ISO 41001 certification in public tenders. BTC City and the Šiška district concentrate commercial office stock where landlords now mandate CSRD-aligned energy reporting from service providers.
Maribor Secondary Market
Hospital network expansion and university campus modernization extend contract durations. EU Energy Performance of Buildings Directive transposition accelerates digital energy monitoring mandates. The Drava River industrial zone hosts manufacturing facilities requiring ATEX-certified maintenance with 24/7 operational continuity.
Slovene-Austrian Border Corridor
Automotive and electronics production clusters anchor engineering-heavy maintenance demand. Cross-border supply chain integration with Carinthia and Styria elevates technical specifications above domestic standards. Kranj-based manufacturing parks source specialized hard services from Austrian-certified technician pools.
Coastal Region
Port logistics and tourism infrastructure generate seasonal service volatility. Koper's container terminal operations require security and maintenance bundling under unified SLA frameworks. Municipal contracts in Piran and Izola remain price-sensitive with fragmented procurement authority.
Slovenia Facility Management Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical credentials. The Slovenian market structures around three tiers: multinational platform operators with centralized procurement scale, mid-sized integrated providers with regional hub networks, and niche engineering specialists serving industrial corridors. Consolidation pressure intensifies as corporate buyers demand unified hard-plus-soft service bundles. Technology licensing partnerships and operational leasing models for building systems represent the dominant competitive moves reshaping vendor relationships.
Among multinational platform operators, Sodexo Slovenia and CBRE GWS exemplify the integrated service archetype with cross-functional deployment capabilities. Protim Ržišnik Perc d.o.o. occupies a specialized position within the engineering-heavy maintenance tier, serving industrial facilities along border manufacturing corridors. These three represent distinct strategic postures: centralized platform scale, technology-led workplace management, and technical specialization in high-margin industrial verticals.
| Leading Market Players |
|---|
| First Facility d.o.o. |
| FMG Facility Management Group |
| Sodexo Slovenia |
| Protim Ržišnik Perc d.o.o. |
| ses European Slovenia |
| CBRE GWS |
| Diversey Slovenia |
| Iskra Facility Management |
| MG Facility Management d.o.o. |
| Others |
Value Network & Pricing Analysis
The Ljubljana-Vienna freight corridor shapes cost dynamics across Slovenia's facility management sector, concentrating supply leverage among Austrian engineering firms while compressing margins for domestic operators unable to absorb cross-border logistics premiums.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in Slovenia's facility management market. Price differentiation rests on ISO 41001 certification grade and bundled technology platform access, with certified operators commanding substantial premiums over uncertified competitors. Cost compression in the standard tier is intensifying because EN 15221-qualified technician scarcity drives wage inflation. Government agencies exhibit the lowest price sensitivity due to multi-year tender security, while private owners remain the most price-sensitive segment.
Supply Chain Analysis
EU dual-use technology controls on building automation systems limit sensor and control equipment flows into Slovenian FM providers, creating procurement friction for predictive maintenance platforms. Geographic supply concentration draws from Germany, Austria, and Italy for HVAC components, engineering software, and certified technician training programs. Raw material dependencies center on copper wiring, refrigerants, and IoT sensor arrays. Single-source vulnerability runs through Austrian engineering firms dominating specialized industrial maintenance. Distribution runs through Ljubljana-based procurement hubs serving multi-site corporate portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Slovenia's facility management market operates as a defensive-moat story where ISO 41001 certification and embedded asset knowledge create switching costs that protect incumbent positions against pure technology disruptors.
For Market Incumbents: Entrench platform consolidation by acquiring regional cleaning and security specialists to complete hard-plus-soft service bundles. Deepen backward integration into HVAC operational leasing to capture recurring revenue streams distinct from time-and-materials billing. The threat of technology-enabled entrants with pure-play IoT platforms demands preemptive certification investment in EN 15221 technician pipelines.
For New Entrants and Emerging Players: Pursue Maribor's secondary market gap where commercial stock modernization lags Ljubljana by several years and incumbent presence remains thin. Target university campus and hospital network tenders where extended payment terms deter established operators. A specialized industrial corridor go-to-market angle serving ATEX-certified maintenance needs along the Slovene-Austrian border offers the most penetrable entry vector.
For Investors and Strategic Acquirers: Carve-out targets emerge from Austrian and Italian engineering parents seeking to divest non-core Slovenian operations. Long-term viability over a multi-year window hinges on technology-augmented service differentiation rather than pure labor arbitrage. Acquisition candidates with documented carbon reduction protocols and existing public sector contract relationships represent the strongest archetype. The signal to watch is Ministry of Public Administration tender specification changes embedding real-time energy telemetry as mandatory evaluation criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 41001 Certification Investment | Qualifies bidders for Ministry of Public Administration tenders excluding uncertified competitors. |
| Operational Leasing Convergence | Transforms HVAC and building automation from capital sales into recurring revenue streams. |
| IoT Platform Partnership | Supplies API-accessible dashboards now mandatory in Ljubljana corporate procurement specifications. |
| Maribor Regional Hub Establishment | Captures first-mover advantage in secondary market where modernization cycles lag Ljubljana. |
| ATEX-Certified Maintenance Specialization | Commands 40-60% pricing premiums in Slovene-Austrian border manufacturing corridors. |
Research Methodology
Desk research of EU regulatory filings, national procurement databases, and EN standard documentation preceded structured interviews with facility management executives, public sector procurement officers, building automation engineers, and certification body representatives. Primary fieldwork combined with secondary validation against Ministry of Public Administration tender records and CSRD implementation guidance. Bottom-up contract value aggregation and top-down sector sizing triangulated market estimates.
Assumptions held fixed include EU Energy Performance of Buildings Directive transposition timelines and ISO 41001 certification weighting in public tenders, while technology adoption curves and technician wage inflation were varied across sensitivity scenarios. Segmentation modeling incorporated service type intensity, facility asset class, client procurement authority, and technology sophistication tier. CAGRs derived from contract renewal probability weighting and scope expansion coefficients calibrated against historical tender award patterns. Industry-specific inputs included public healthcare estate expansion pipelines and industrial corridor manufacturing uptime requirements.
Sensitivities concentrate around EU CSRD reporting obligation enforcement intensity and EN 15221-qualified technician pipeline expansion rates. Forecasts reflect documented assumptions on public sector outsourcing momentum and corporate real estate vendor consolidation trajectories. Material shifts in EU building decarbonization policy stringency or cross-border technician mobility agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
North America Soft Facility Management Market
Facility Management
Australia Facility Management Market
Facility Management
North America Hard Facility Management Market
Facility Management
Malta Facility Management Market
Facility Management
Europe Soft Facility Management Market
Facility Management
Facility Management Services Market
Facility Management
Denmark Facility Management Market
Facility Management
Kuwait Facility Management Market
Facility Management
Asia-Pacific Hard Facility Management Market
Facility Management
Hungary Facility Management Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
North America Facilities Management Market
Facility Management
Cold Storage Warehouse Market
Facility Management
France Facility Management Market
Facility Management
Argentina Facility Management Market
Facility Management
Finland Facility Management Market