
 India Integrated Facility Management Market | 2026-2036
India Integrated Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
India Integrated Facility Management Market Insights
The BIS energy efficiency standards for commercial buildings is consolidating vendor qualification requirements across metro clusters. CBRE India leverages its property management scale to anchor large-campus contracts in Mumbai and Delhi-NCR. JLL India competes through technology-led asset diagnostics, while BVG India dominates government and institutional accounts with its labor-heavy operating model.
India Integrated Facility Management denotes the bundled delivery of hard services (HVAC, electrical, plumbing maintenance) and soft services (cleaning, security, landscaping) under unified governance with SLAs spanning multiple client locations. The practice relies on CAFM platforms, workforce dispatch algorithms, and preventive maintenance schedules to sustain asset uptime across distributed real estate portfolios. The outsourced delivery model leads transaction volumes as enterprises divest non-core operations, while the managed services tier captures expanding margin pools through outcome-based contracts. IoT integration within the technology segment is growing fastest as sensor networks enable predictive maintenance and energy optimization in commercial and healthcare end-user verticals.
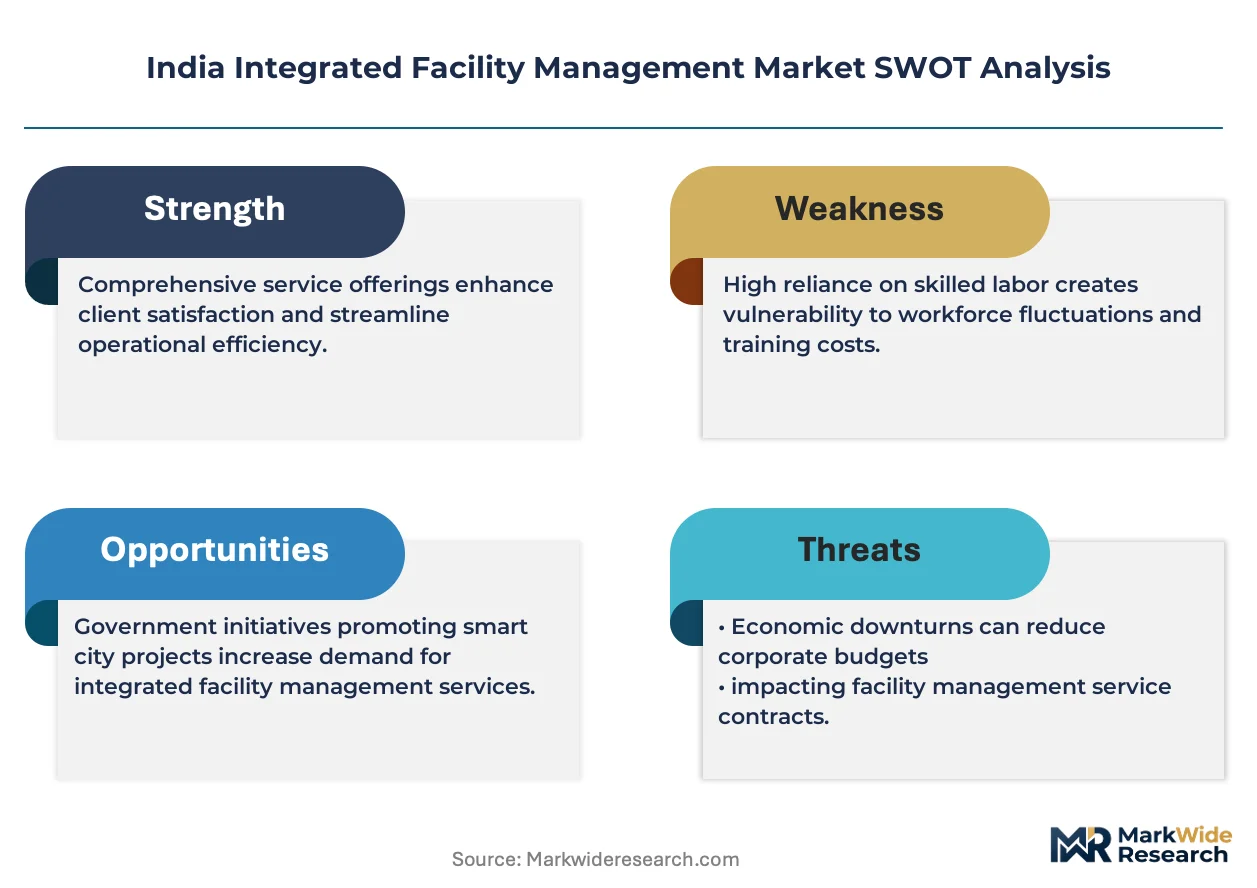
SEBI's mandate for ESG disclosures by listed entities and the Energy Conservation Building Code enforced by the Bureau of Energy Efficiency are elevating compliance spending on monitored facility operations. CDSCO guidelines for healthcare infrastructure sanitation and the PLI scheme for domestic manufacturing are indirectly stimulating demand for certified facility management in pharmaceutical clusters and industrial townships. Stakeholders must weigh capital deployment between proprietary technology stacks and partnership-led platform integrations as contract tenures lengthen and performance penalties tighten.
Market Dynamics
SEBI's ESG disclosure mandate for listed entities is compressing procurement cycles as boards demand verifiable facility performance data. This regulatory pressure is forcing facility management vendors to deploy sensor networks and automated reporting dashboards ahead of contract renewals.
Growth Catalysts
- Energy Conservation Building Code:The Bureau of Energy Efficiency's enforcement is mandating monitored HVAC operations in commercial buildings above 100 kW connected load. Facility managers must install sub-metering and automated fault detection to retain occupancy permits.
- PLI scheme for domestic manufacturing:Industrial townships in Gujarat and Tamil Nadu are expanding certified facility management coverage to meet pharmaceutical and electronics cluster requirements. Cleanroom protocols and wastewater treatment monitoring are now standard in these contracts.
- IoT-enabled asset monitoring:Predictive maintenance platforms using vibration and thermal sensors are reducing unplanned downtime in hospital infrastructure. Healthcare end-users in Hyderabad and Chennai are specifying CAFM integration in RFPs.
Market Restraints
- Skilled technician scarcity:Certification programs for BMS operators and energy auditors lag demand in Tier-2 cities. Training infrastructure concentrates in Mumbai, Bengaluru, and Delhi-NCR, limiting service expansion.
- Imported sensor dependency:IoT hardware for energy monitoring relies on Chinese and German suppliers. Rupee volatility and extended customs clearances at Mumbai and Chennai ports are inflating deployment timelines.
- CDSCO sanitation mandates:Healthcare facility contracts require documented compliance with evolving sterilization protocols. Documentation burden and inspection frequency are extending sales-to-revenue cycles for hospital accounts.
Strategic Opportunities
- Kerala and Odisha healthcare infrastructure:Government medical college expansions and specialty hospital PPPs in these states lack established facility management vendors. First-movers can anchor multi-site contracts with limited competition.
- SEBI ESG disclosure mandate:Listed real estate investment trusts and corporate campuses must publish verified energy and water consumption data. Audited facility management contracts are becoming a procurement priority for compliance officers.
- CAFM and workforce dispatch convergence:Platforms integrating asset diagnostics with gig-economy security and cleaning staffing are enabling dynamic SLA pricing. IT parks in Pune are piloting outcome-based contracts tied to occupancy rates.
Industry Challenges
- Legacy BMS integration:Commercial buildings commissioned before 2010 operate on proprietary protocols incompatible with open IoT architectures. Retrofit projects require custom middleware development, compressing margins on technology-led contracts.
- Multi-site workforce compliance:The Shops and Establishments Act varies across Maharashtra, Karnataka, and Telangana. Vendors operating nationally must maintain state-specific payroll and shift-hour compliance systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Integrated Facility Management Market |
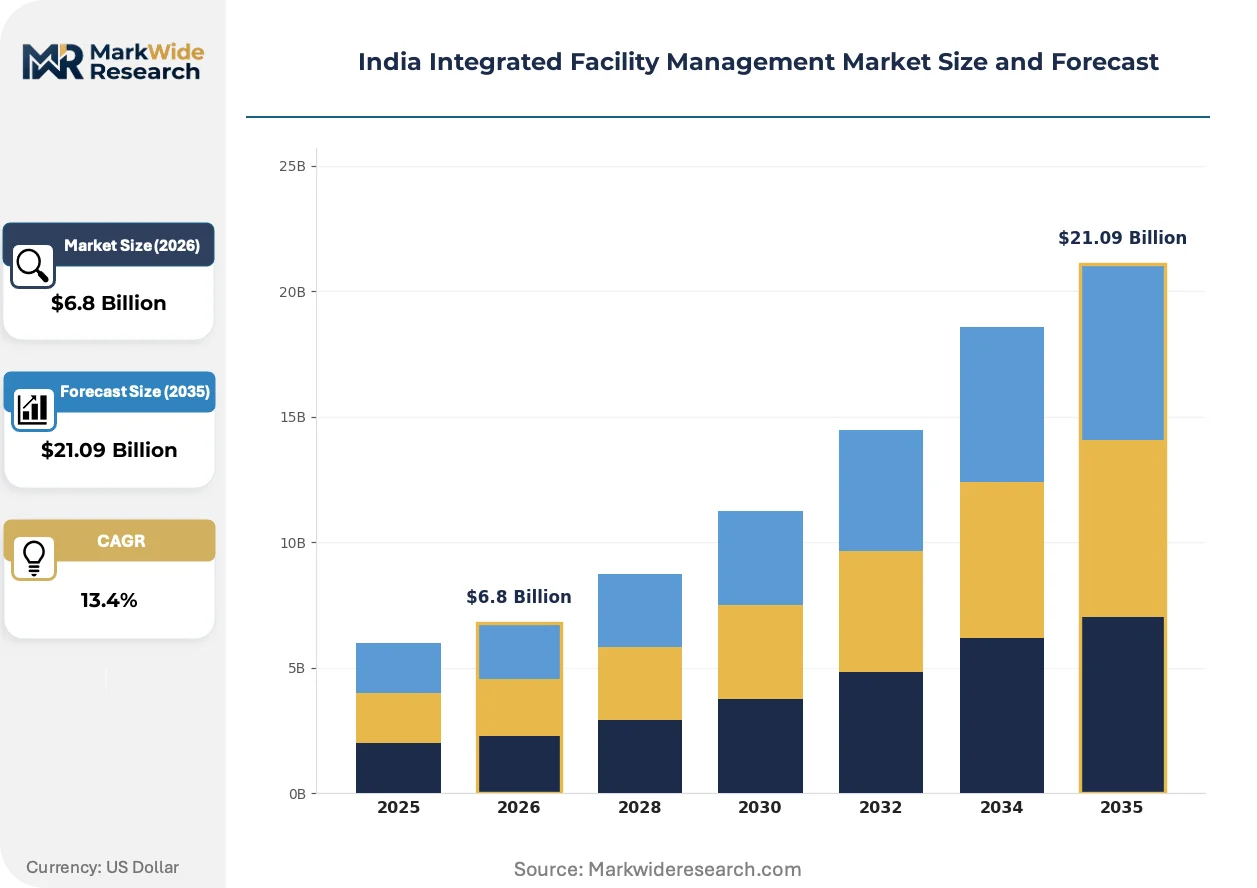
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
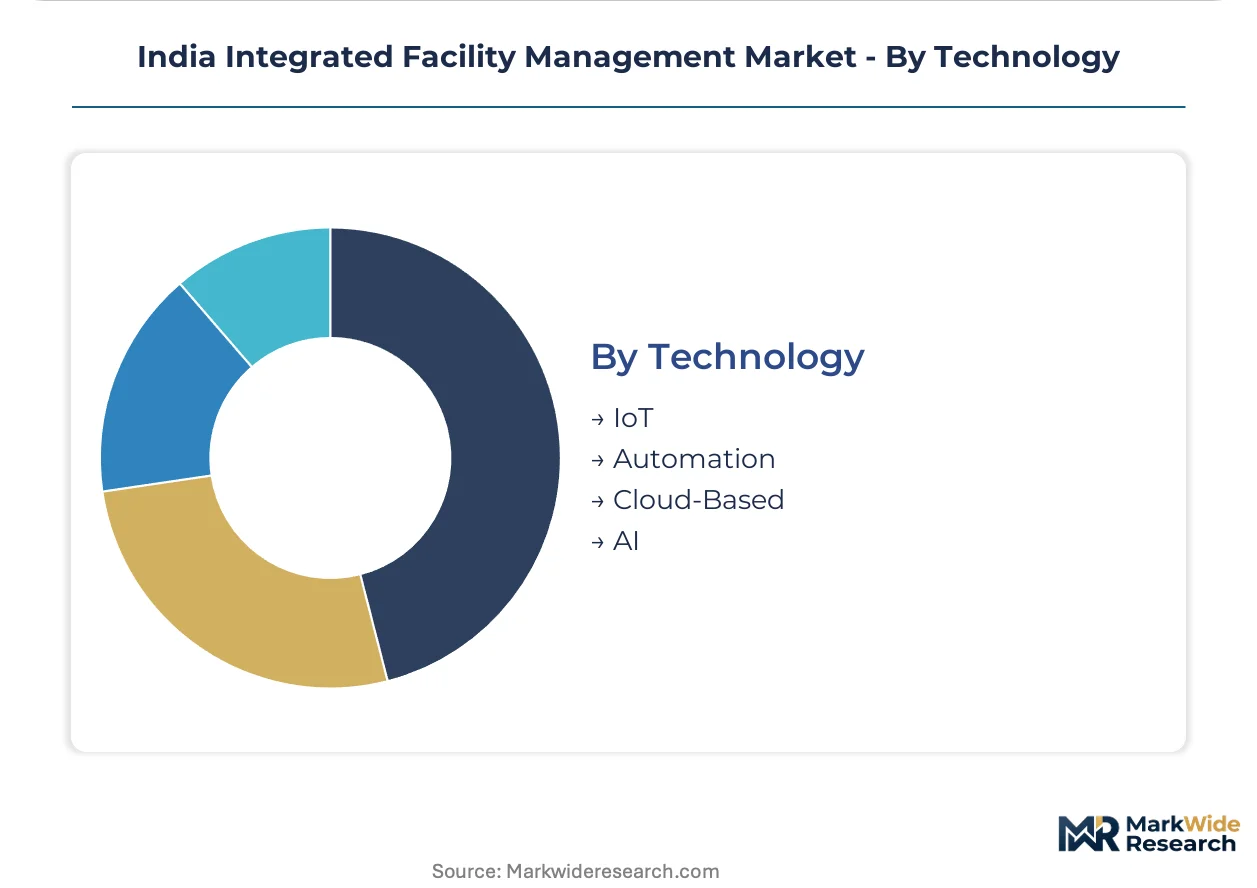
| Segmentation | Service Type: Cleaning, Security, Maintenance, HVAC End User: Commercial, Residential, Healthcare, Education Delivery Model: In-House, Outsourced, Hybrid, Managed Services Technology: IoT, Automation, Cloud-Based, AI |
| Companies Covered | Sodexo Facilities Management, Quess Corp, CBRE India, Tenon Group, Updater Services, JLL India, BVG India, Cushman & Wakefield, ISS Facility Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Integrated Facility Management Market Trends and Innovations
Digital twin technology is compressing the gap between physical asset performance and remote management capability. Vendors are racing to embed predictive analytics into standard service offerings before contract terms harden around uptime guarantees.
Digital twin platforms are creating virtual replicas of HVAC, electrical, and plumbing systems across distributed campus portfolios. Large IT parks in Hyderabad and Bengaluru are mandating twin deployment for new construction and major retrofits. This technology is rewriting how SLAs are structured, with vendors accepting penalties tied to simulated versus actual asset performance.
BIS energy efficiency standards for commercial buildings are consolidating vendor qualification requirements across metro clusters. The mandate for audited energy consumption reporting is disqualifying uncertified operators from Grade A commercial contracts. Maharashtra and Karnataka are seeing accelerated procurement of integrated facility services as landlords seek single-accountability partners for compliance.
Enterprise buyers are unbundling long-term bundled contracts into modular service tiers with separate technology and labor components. Corporate campuses in Pune are separating CAFM platform licensing from on-site staffing, enabling direct software procurement by IT departments. This pattern is most pronounced in technology sector end-users where CIOs demand control over data architecture and cybersecurity protocols.
India Integrated Facility Management Market Segmentation
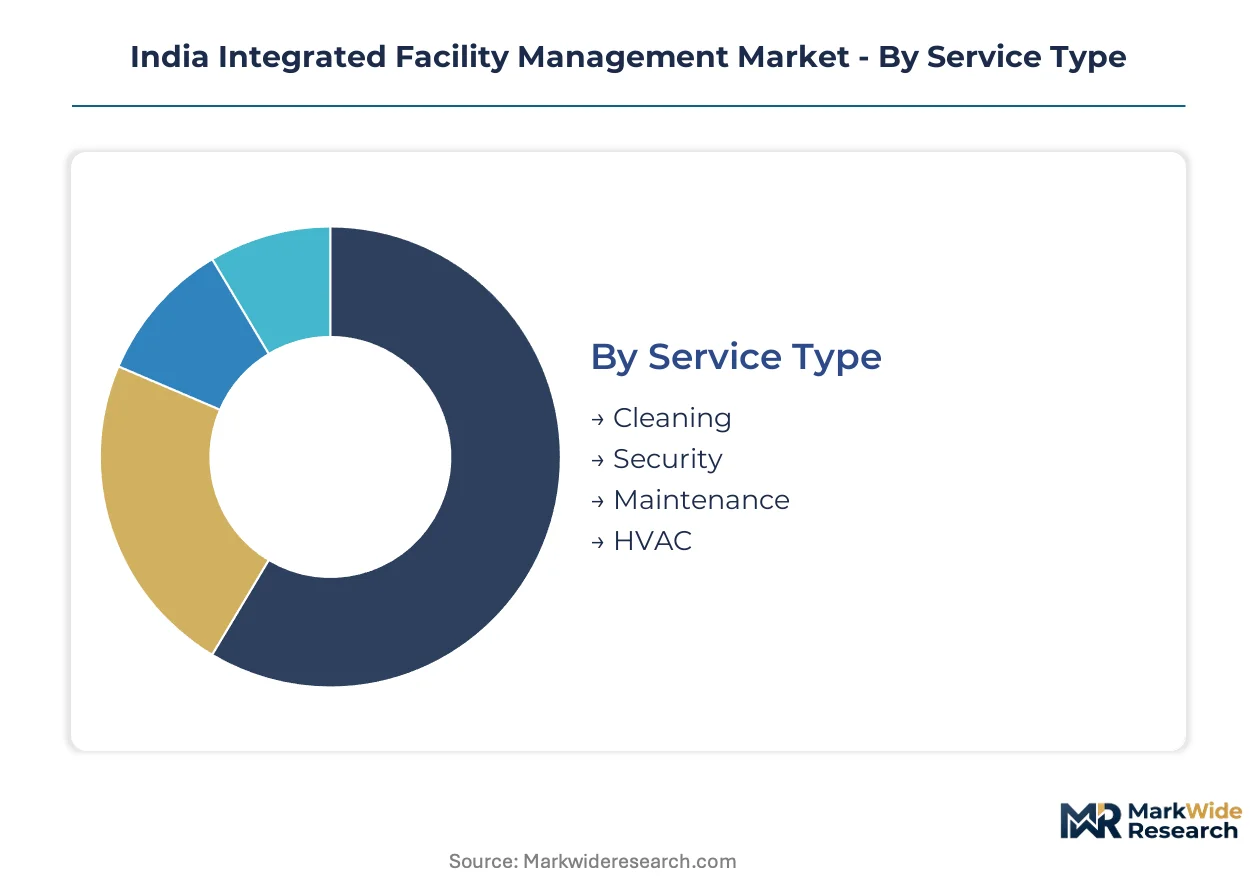
Segmentation in India's integrated facility management market reveals how procurement priorities diverge across asset types and compliance regimes. Service bundling decisions, technology adoption thresholds, and delivery model preferences vary sharply between IT campuses in Hyderabad and government hospitals in Kerala.
Service Type:
Technical sophistication and regulatory intensity separate high-margin service lines from commodity offerings.
- HVAC:Energy monitoring and automated fault detection now dominate commercial contracts above 100 kW connected load. The Bureau of Energy Efficiency's sub-metering mandate is compressing procurement cycles in Maharashtra and Karnataka Grade A stock.
- Maintenance:Preventive schedules using vibration sensors and thermal imaging are reducing unplanned downtime in hospital infrastructure. Healthcare end-users in Chennai and Hyderabad specify CAFM integration in RFPs.
- Security:Gig-economy staffing models are converging with access control systems in IT parks.
- Cleaning:CDSCO sanitation protocols are extending documentation burdens for healthcare accounts.
HVAC leads on scale; Maintenance leads on momentum.
End User:
Compliance intensity and contract tenure shape profitability profiles across verticals.
- Healthcare:CDSCO sterilization mandates and JCI accreditation requirements demand documented compliance with evolving protocols. Hospital expansions in Kerala and Odisha lack established vendors, creating first-mover opportunities.
- Commercial:SEBI's ESG disclosure mandate is forcing sensor deployment and automated reporting ahead of contract renewals. Corporate campuses in Bengaluru and Pune are unbundling long-term contracts into modular tiers.
- Education:Government medical college PPPs are stimulating demand for certified facility management.
- Residential:Gated community contracts concentrate in Mumbai and Delhi-NCR metro clusters.
Commercial dominates contract volume; Healthcare shows steepest expansion trajectory.
Delivery Model:
Margin capture shifts as enterprises divest non-core operations and performance penalties tighten.
- Outsourced:Single-accountability partnerships are consolidating vendor relationships as landlords seek unified governance for BIS energy compliance. IT parks in Hyderabad favor bundled hard and soft services under unified SLAs.
- Managed Services:Outcome-based contracts tied to uptime guarantees and energy performance are capturing expanding margin pools. Pune campuses pilot dynamic pricing linked to occupancy rates.
- Hybrid:Split arrangements separate CAFM platform licensing from on-site staffing.
- In-House:Retained models persist in sensitive government and defense installations.
Outsourced anchors transaction volume; Managed Services captures margin expansion.
Technology:
Integration depth and data sovereignty concerns are restructuring procurement authority between facility and IT departments.
- IoT:Sensor networks for energy monitoring and predictive maintenance rely on Chinese and German hardware suppliers. Rupee volatility at Mumbai and Chennai ports is inflating deployment timelines.
- AI:Predictive analytics platforms are compressing the gap between simulated and actual asset performance. Digital twin mandates in Bengaluru IT parks are rewriting penalty structures around performance variance.
- Cloud-Based:CIOs in technology sector end-users demand direct control over data architecture and cybersecurity protocols.
- Automation:Workforce dispatch algorithms are converging with gig-economy staffing for dynamic SLA pricing.
IoT leads on deployment scale; AI gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled facility management technicians cluster disproportionately in Maharashtra, Karnataka, and Telangana, creating service delivery density that outpaces northern and eastern states. This workforce geography shapes contract fulfillment capabilities and vendor expansion timelines across the subcontinent.
Maharashtra
Mumbai's Grade A commercial stock and Pune's IT corridor generate concentrated demand for bundled hard and soft services. The Bureau of Energy Efficiency's Energy Conservation Building Code mandates sub-metering in commercial buildings above 100 kW connected load, accelerating sensor deployment in Mumbai's Bandra-Kurla Complex and Lower Parel clusters.
Karnataka
Bengaluru's corporate campuses and electronics manufacturing zones anchor the state's facility management procurement. SEBI's ESG disclosure requirements for listed entities are compressing renewal cycles as boards demand verified energy and water consumption data from Whitefield and Electronic City assets.
Telangana
Hyderabad's pharmaceutical clusters and hospital infrastructure are specifying CAFM-integrated contracts with predictive maintenance clauses. The PLI scheme for domestic manufacturing is expanding certified facility coverage in Genome Valley and Pashamylaram industrial zones.
Gujarat
Industrial townships in Sanand and Vadodara are adopting cleanroom protocols and wastewater monitoring under pharmaceutical cluster requirements. CDSCO sanitation mandates are extending documentation burdens for contract sterilization compliance in these manufacturing hubs.
Tamil Nadu
Chennai's healthcare infrastructure and Sriperumbudur electronics corridor are driving demand for vibration-sensor preventive maintenance. The state's medical college expansions lack established facility vendors, creating first-mover opportunities in government hospital PPPs.
India Integrated Facility Management Market Competitive Landscape
The competitive structure tilts toward property management specialists with technology-led differentiation. Market concentration remains moderate, with national-scale operators anchoring metro contracts while regional labor-heavy vendors capture institutional accounts. Three archetypes dominate: global property consultancies leveraging CAFM platforms, domestic workforce aggregators with government relationships, and integrated operators bundling hard and soft services under unified SLAs. Strategic moves center on platform partnerships for IoT integration and outcome-based contract structures with penalty clauses tied to energy performance.
Within the property consultancy tier, CBRE India and JLL India exemplify technology-led positioning, while BVG India occupies a distinct labor-heavy institutional niche. Sodexo Facilities Management and ISS Facility Services represent the global service integrator archetype with standardized delivery frameworks. Quess Corp anchors the domestic workforce aggregation segment. These players collectively illustrate the market's segmentation between platform-driven metro commercial contracts and relationship-driven government and healthcare accounts.
| Leading Market Players |
|---|
| Sodexo Facilities Management |
| Quess Corp |
| CBRE India |
| Tenon Group |
| Updater Services |
| JLL India |
| BVG India |
| Cushman & Wakefield |
| ISS Facility Services |
| Others |
Pricing and Supply Chain Analysis
IoT-enabled predictive maintenance platforms are compressing service delivery costs while concentrating procurement power among technology-integrated vendors. The shift from labor-heavy operating models to sensor-network dependency simultaneously elevates upfront CAFM investment requirements and disqualifies uncertified competitors from Grade A commercial contracts in Maharashtra and Karnataka.
Pricing Analysis
Bundled hard-and-soft service contracts command premium positioning against unbundled modular tiers where CAFM licensing separates from on-site staffing. Price differentiation hinges on BIS energy audit certification and SEBI-compliant ESG reporting capability, with certified vendors capturing margin expansion in Mumbai and Bengaluru. Cost compression in commodity cleaning and security staffing intensifies as gig-economy platforms erode traditional labor markups. Corporate IT campuses in Pune show least price sensitivity due to outcome-based SLA structures, while government hospital PPPs in Kerala and Odisha remain most sensitive to upfront capital deployment.
Supply Chain Analysis
Freight cost volatility at Mumbai and Chennai ports inflates deployment timelines for German vibration sensors and Chinese thermal imaging hardware. Component supply concentrates in China, Germany, and South Korea for IoT-enabled energy monitoring equipment. The vendor ecosystem draws from specialized BMS middleware developers in Bengaluru and legacy protocol retrofit specialists in Delhi-NCR. Single-source vulnerability runs through German sensor suppliers for pharmaceutical cleanroom monitoring. Distribution runs through direct vendor-client contracting for large-campus integrated services, with regional labor aggregators handling government and healthcare accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with SEBI's ESG disclosure mandate forcing sensor deployment ahead of every contract renewal cycle and compressing procurement authority toward compliance officers.
For Market Incumbents: Extend CAFM platform penetration into hospital infrastructure before CDSCO documentation requirements harden around sterilization protocols. Anchor multi-site contracts in Kerala and Odisha government medical college expansions where established vendor presence remains thin. Vertical integration into proprietary workforce dispatch algorithms defends margin position against gig-economy staffing platforms eroding traditional security and cleaning markups. For New Entrants and Emerging Players: AI-first digital twin deployment creates entry leverage in Bengaluru IT parks where simulated-versus-actual performance penalties are rewriting SLA structures. Target healthcare infrastructure in Tamil Nadu government hospital PPPs lacking certified facility management coverage. Lead with outcome-based pricing tied to energy performance guarantees rather than labor-hour rates. For Investors and Strategic Acquirers: Valuations sit cheapest among labor-heavy regional operators with government relationships but limited technology integration. Long-term viability favors vendors with proprietary CAFM stacks and BIS energy auditor certification pipelines. The inflection signal to watch is unbundling velocity—when IT departments in Pune and Hyderabad begin direct CAFM platform procurement separate from facilities management.| Strategic Initiative | Industry Significance |
|---|---|
| CAFM Platform Integration | SEBI-compliant ESG reporting becomes mandatory for listed REITs and corporate campuses. |
| BIS Energy Auditor Certification | Bureau of Energy Efficiency mandates disqualify uncertified vendors from Grade A commercial contracts. |
| Digital Twin Deployment | Hyderabad IT parks now mandate virtual asset replicas for new construction and major retrofits. |
| Healthcare Infrastructure Expansion | Kerala and Odisha government medical college PPPs lack established facility management vendors. |
| Outcome-Based Contract Structuring | Pune campuses pilot dynamic pricing linked to occupancy rates and energy performance guarantees. |
Research Methodology
Coverage spans Maharashtra, Karnataka, Telangana, Gujarat, and Tamil Nadu, with primary inputs from each state's facility management procurement clusters. The approach combines primary interviews with CAFM platform engineers, hospital purchasing committees, commercial real estate asset managers, and Bureau of Energy Efficiency compliance officers with secondary validation through SEBI ESG disclosure filings, BIS certification databases, CDSCO sanitation guidelines, and state-level Shops and Establishments Act variations. Bottom-up contract value aggregation triangulates against top-down market sizing from commercial stock expansion data.
Rate-of-change decomposition separates volume expansion from value capture across the projection horizon. Segmentation dimensions modeled include service type bundling, delivery model migration from outsourced to managed services, technology integration depth, and end-user vertical compliance intensity. CAGRs derive from contract renewal velocity analysis and sensor deployment run-rates in IT parks and hospital infrastructure. Industry-specific inputs incorporate PLI scheme manufacturing cluster expansion timelines and Energy Conservation Building Code enforcement phasing.
The model holds under sustained regulatory enforcement of BIS standards and SEBI disclosure mandates; deviation in rupee volatility severity or customs clearance disruptions at Mumbai and Chennai ports would shift hardware deployment timelines and vendor margin structures. Stakeholders should weight assumptions against their own operating context and regional compliance burden trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Global Facility Management Software Market
Facility Management
Greece Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
Hong Kong Facility Management Market
Facility Management
Switzerland Facility Management Market
Facility Management
Argentina Facility Management Market
Facility Management
Refrigerated Warehousing Market
Facility Management
Belgium Facility Management Market
Facility Management
Brazil Facility Management Market
Facility Management
Saudi Arabia Soft Facility Management Market
Facility Management
France Facility Management Market
Facility Management
Lithuania Facility Management Market
Facility Management
Hungary Facility Management Market
Facility Management
Sweden Facility Management Market
Facility Management
Philippines Facility Management Market
Facility Management
Asia-Pacific Hard Facility Management Market