
 North America Soft Facility Management Market | 2026-2036
North America Soft Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Soft Facility Management Market Analytics
ISO 41001 facility management certification is bifurcating the competitive landscape into qualified and non-qualified service tiers. CBRE Group Inc. leverages its integrated service platform to dominate corporate campus contracts across the Sun Belt. Sodexo Inc. anchors its position through specialized healthcare facility protocols that exceed Joint Commission standards. ISS A/S competes aggressively on cost-plus contracts for educational institution portfolios.
Soft facility management encompasses non-structural building services including cleaning, security, landscaping, and reception operations, typically delivered through labor-intensive workflows with measurable service-level agreements tied to occupancy rates and tenant satisfaction scores. The service type dimension shows cleaning and security commanding the largest contract values due to daily recurrence requirements, while landscape management generates premium margins in climate-sensitive geographies. Within end users, healthcare facilities impose the most stringent compliance burdens, and corporate offices represent the deepest volume pool for multi-year outsourced agreements.
OSHA workplace safety standards, EPA green cleaning mandates, and ISO 41001 certification requirements collectively elevate operational compliance costs while creating barriers to market entry for unqualified regional operators. The Department of Labor's evolving contractor classification rules further reshape cost structures for outsourced facility staffing models. Stakeholders must monitor regulatory divergence between US federal standards and emerging provincial certification frameworks in Canada to preserve cross-border service scalability.
Market Dynamics
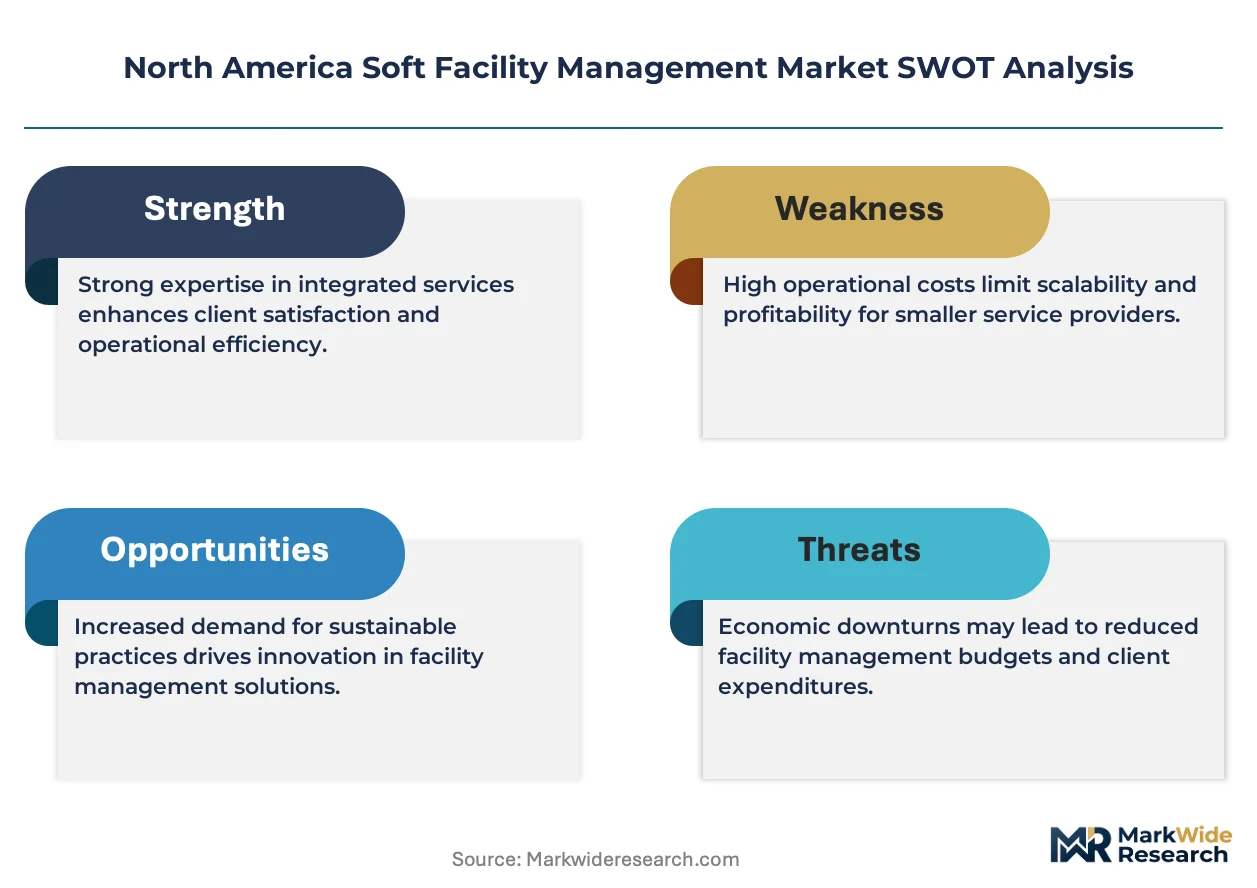
OSHA workplace safety standards and EPA green cleaning mandates are compressing vendor margins while forcing portfolio consolidation among regional operators unable to absorb compliance infrastructure costs.
Growth Catalysts
- Post-pandemic hygiene protocols:Corporate office portfolios across the United States are expanding cleaning and security service contracts to meet elevated tenant expectations for sanitization frequency and air quality verification.
- ISO 41001 certification:This facility management standard is creating qualified service tiers that favor certified vendors in competitive bidding processes for multi-year outsourced agreements.
- Commercial real estate absorption:Texas and California metropolitan corridors are outpacing national averages, concentrating demand for soft facility services in climate-sensitive geographies with premium landscaping requirements.
Market Restraints
- Labor cost volatility:The Department of Labor's evolving contractor classification rules are reshaping cost structures for outsourced facility staffing models, particularly in states with stringent wage enforcement.
- Supply concentration risk:Specialized healthcare facility protocols that exceed Joint Commission standards limit vendor pools to operators with dedicated clinical training infrastructure.
- Regulatory friction:Divergence between US federal OSHA standards and emerging provincial certification frameworks in Canada threatens cross-border service scalability for integrated North American portfolios.
Strategic Opportunities
- Underpenetrated educational institutions:Cost-plus contract structures in this segment reward vendors who can demonstrate measurable service-level agreements tied to occupancy rates and tenant satisfaction scores.
- Technology convergence:Integration of IoT-enabled occupancy sensors with automated work-order dispatch systems is enabling predictive cleaning schedules that reduce labor deployment waste.
- Green cleaning mandates:EPA procurement preferences for environmentally preferable products create certification-driven demand rotation toward vendors with verified sustainable chemical inventories.
Industry Challenges
- ISO 41001 compliance timeline:The certification burden stretches 12-18 months for mid-tier operators, creating execution risk during competitive renewal cycles.
- Talent retention in specialized functions:Healthcare facility managers with Joint Commission expertise command premium compensation that compresses contract profitability.
- Legacy system integration:Work-order management platforms from the 2010s lack API compatibility with modern tenant experience applications, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Soft Facility Management Market |
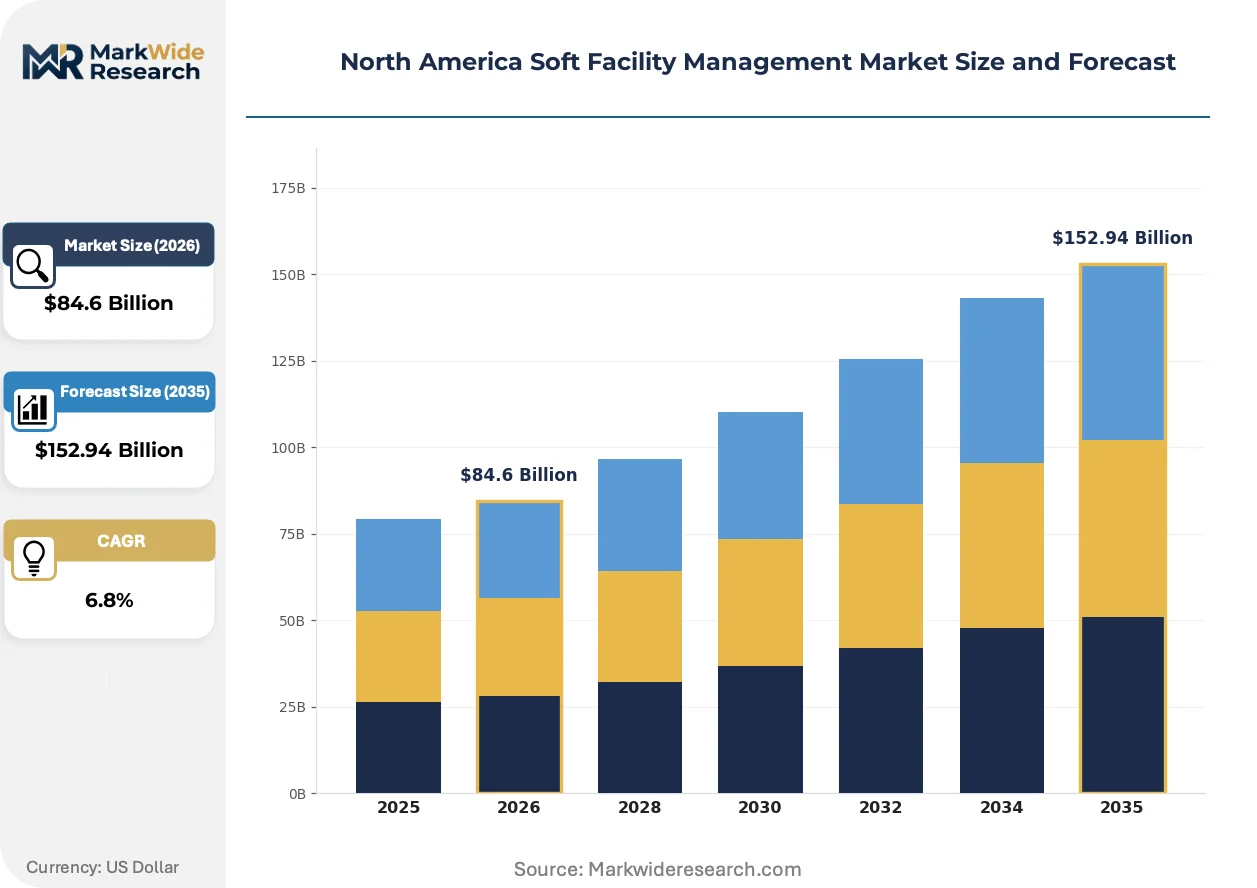
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Landscape Management, Reception End User: Corporate Offices, Educational Institutions, Healthcare Facilities, Retail Outlets Contract Type: Fixed Price, Cost Plus, Time and Materials, Outsourced Technology: IoT Solutions, CMMS, Smart Sensors, Automation Tools |
| Companies Covered | CBRE Group Inc., Sodexo Inc., ISS A/S, ABM Industries Inc., Cushman & Wakefield Plc, GDI Integrated Facility Services Inc., Guardian Service Industries Inc., AHI Facility Services Inc., SMI Facility Services, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Soft Facility Management Market Evolving Landscape
Automation is penetrating labor-intensive workflows while regulatory complexity elevates the strategic value of compliance infrastructure over pure cost competition.
Electrostatic disinfection technology applies charged antimicrobial particles to surfaces with 360-degree coverage, reducing dwell time requirements versus conventional spray-wipe protocols. Large corporate campuses in the Sun Belt are deploying this equipment for high-touch point sanitation on daily recurrence schedules. This capability is displacing traditional mop-bucket crews in premium office contracts where tenant satisfaction scores directly influence renewal rates.
EPA's Safer Choice program and state-level green procurement mandates in California and New York are restricting allowable cleaning chemical inventories. Facility managers must maintain verified product lists and staff training documentation to avoid liability exposure. Healthcare facilities face the most stringent documentation burdens, with some systems requiring quarterly third-party audits of chemical handling protocols.
Performance-based contracting is replacing time-and-materials pricing in multi-year corporate agreements. Buyers now tie vendor compensation to measurable outcomes including tenant complaint resolution speed, emergency response time, and energy-adjusted cleaning efficacy scores. This shift is most visible in technology sector campuses where facilities teams report to workplace experience executives rather than traditional operations managers.
North America Soft Facility Management Market Segmentation
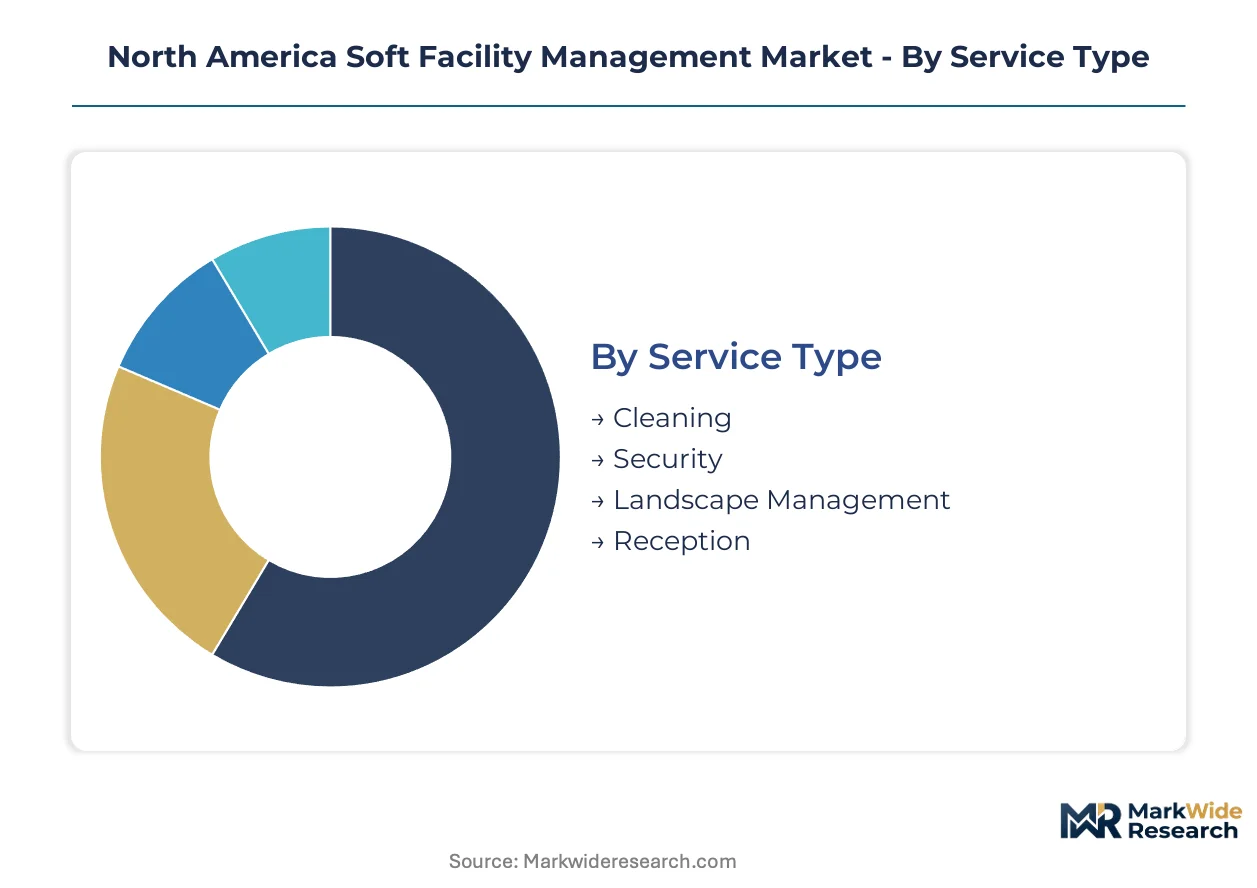
Soft facility management contracts distribute unevenly across service dimensions, with margin concentration tracking regulatory burden and labor specialization rather than pure contract volume. Understanding these segment boundaries clarifies where vendor qualification investments yield sustainable competitive position.
Service Type:
Margin pools concentrate in services requiring daily recurrence and compliance documentation, with premium capture available to operators bearing certification infrastructure costs.
- Cleaning:Encompasses janitorial, disinfection, and specialized sanitization protocols with chemical inventory verification requirements. Demand concentrates in Texas and California metropolitan corridors where commercial real estate absorption outpaces national averages, with post-pandemic hygiene protocols mandating increased service frequency and air quality documentation.
- Security:Includes manned guarding, access control monitoring, and emergency response coordination with liability exposure management. Corporate office portfolios across the United States are expanding these contracts to meet elevated tenant expectations for visible safety presence and rapid incident resolution.
- Landscape Management:Covers grounds maintenance, irrigation systems, and seasonal planting with climate-sensitive scheduling. Premium margins emerge in geographies with water restrictions and native species mandates requiring specialized horticultural expertise.
- Reception:Front-desk staffing, visitor management, and tenant concierge services with brand representation functions. Corporate campuses prioritize this segment for workplace experience differentiation.
Cleaning holds installed capacity. Security is rotating up the share rankings.
End User:
Application intensity varies by sector compliance burden, with healthcare and education creating divergent vendor selection criteria around certification versus cost efficiency.
- Healthcare Facilities:Imposes the most stringent compliance burdens including Joint Commission standards, infection control protocols, and chemical handling audits. Specialized healthcare facility protocols limit vendor pools to operators with dedicated clinical training infrastructure and quarterly third-party audit capabilities.
- Corporate Offices:Represents the deepest volume pool for multi-year outsourced agreements with performance-based contracting replacing time-and-materials pricing. Technology sector campuses drive outcome-based vendor compensation tied to tenant complaint resolution speed and emergency response metrics.
- Educational Institutions:Cost-plus contract structures reward vendors demonstrating measurable service-level agreements tied to occupancy rates and tenant satisfaction scores. ISS A/S competes aggressively in this segment through scalable labor deployment models.
- Retail Outlets:Seasonal demand fluctuations and high-traffic surface maintenance requirements with compressed response windows for spill remediation and fixture presentation standards.
Corporate Offices holds installed capacity. Healthcare Facilities is climbing the fastest.
Contract Type:
Customer procurement sophistication is shifting risk allocation and pricing transparency expectations across agreement structures.
- Fixed Price:Comprehensive scope definition with vendor assumption of cost overruns, favored by mature corporate real estate portfolios with predictable occupancy patterns.
- Cost Plus:Direct cost recovery with agreed margin percentage, prevalent in educational institutions where service scope fluctuates with academic calendar cycles.
- Time and Materials:Hourly labor rates plus material markups, declining share as buyers demand outcome accountability over input measurement.
- Outsourced:Full function transfer with vendor responsibility for staffing, training, and compliance infrastructure, commanding premium margins for ISO 41001 certified operators.
Outsourced holds installed capacity. Fixed Price is gaining share fastest.
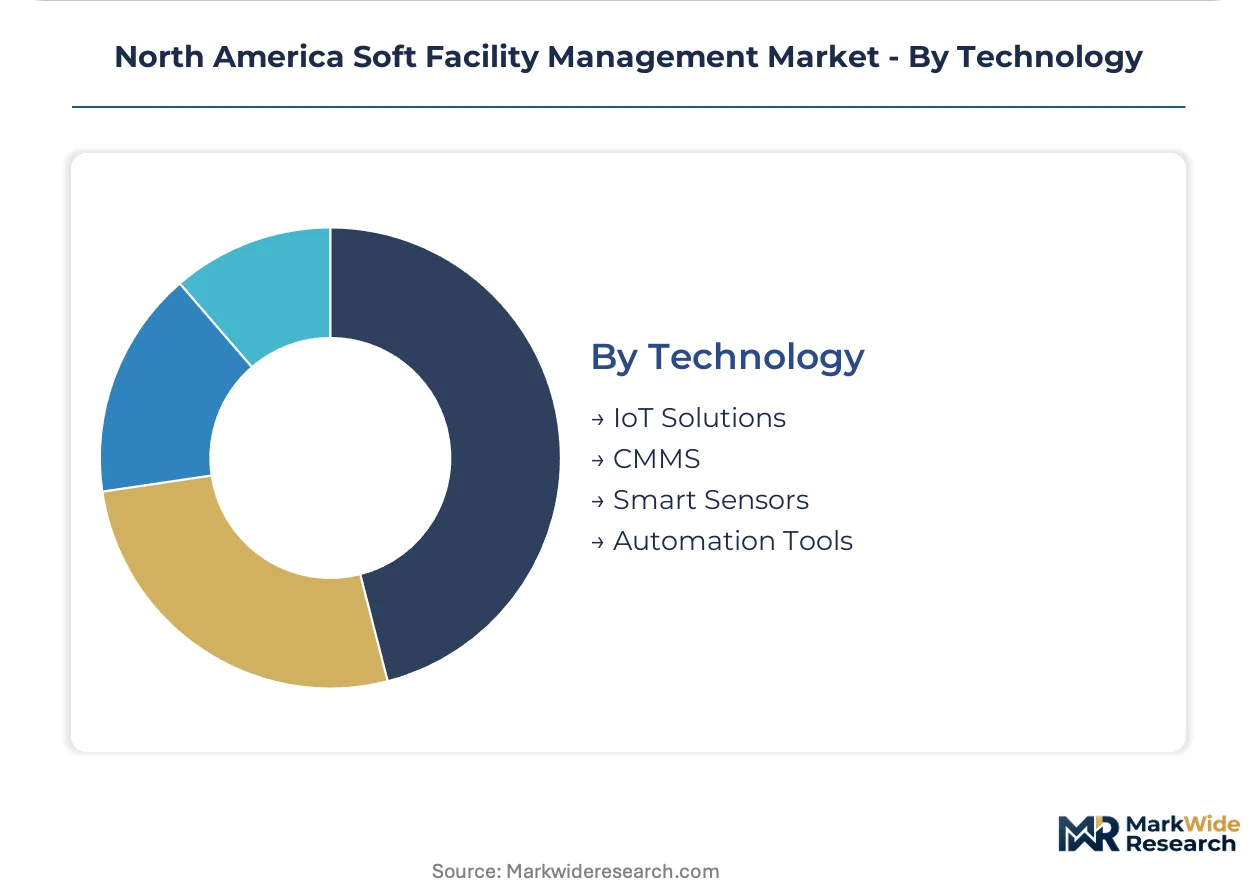
Technology:
Technology convergence is enabling predictive service delivery with labor deployment optimization creating differentiation in competitive bidding processes.
- IoT Solutions:Connected device networks for occupancy monitoring and environmental condition tracking. Integration with automated work-order dispatch systems enables predictive cleaning schedules that reduce labor deployment waste.
- CMMS:Computerized maintenance management systems for asset tracking and preventive scheduling. Legacy platforms from the 2010s lack API compatibility with modern tenant experience applications, forcing costly middleware development for integrated portfolios.
- Smart Sensors:Real-time data collection for restroom usage, air quality, and space utilization with automated alert generation.
- Automation Tools:Robotic floor cleaning and electrostatic disinfection equipment reducing dwell time requirements versus conventional spray-wipe protocols in high-touch point applications.
CMMS holds installed capacity. IoT Solutions is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal green procurement mandates and provincial certification frameworks are reshaping vendor qualification requirements across North America. OSHA workplace safety standards and EPA Safer Choice program preferences concentrate demand in jurisdictions with stringent enforcement capacity. Metropolitan corridors with elevated commercial real estate absorption are driving contract expansion for certified facility management operators.
United States
Corporate office portfolios in Texas and California metropolitan corridors are expanding cleaning and security service contracts to meet post-pandemic hygiene protocols. OSHA workplace safety standards and EPA green cleaning mandates are elevating operational compliance costs while creating barriers to entry for unqualified regional operators. The Sun Belt corridor from Dallas-Fort Worth through Houston anchors multi-year outsourced agreements for integrated service platforms.
Canada
Provincial certification frameworks in Ontario and British Columbia are diverging from US federal standards, threatening cross-border service scalability for integrated North American portfolios. Health Canada and PMRA chemical handling regulations impose documentation burdens comparable to Joint Commission standards in healthcare facilities. Toronto and Vancouver metropolitan areas concentrate demand for ISO 41001 certified operators serving commercial real estate absorption growth.
Mexico
Nearshoring manufacturing expansion in Nuevo León and Baja California is generating demand for facility management services aligned with US corporate parent standards. Mexico's federal labor law reforms and emerging state-level workplace safety protocols are reshaping contractor classification rules for outsourced staffing models. Monterrey and Tijuana industrial corridors are attracting vendors with cross-border compliance infrastructure.
North America Soft Facility Management Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and contract structure dimensions. The competitive landscape bifurcates into ISO 41001 qualified service tiers and non-qualified regional operators unable to absorb compliance infrastructure costs. Three strategic archetypes dominate: integrated platform operators with multi-service portfolios, healthcare specialists with Joint Commission expertise, and cost-plus competitors targeting educational institution scalability. Portfolio consolidation and technology convergence represent the dominant competitive moves reshaping vendor positioning.
Within the integrated platform tier, CBRE Group Inc. and Cushman & Wakefield Plc exemplify archetypes competing for corporate campus contracts across climate-sensitive geographies. Sodexo Inc. occupies a position among healthcare specialists with protocols exceeding regulatory baselines. ISS A/S represents the cost-plus competitor archetype targeting scalable labor deployment in educational segments. These three anchors illustrate how certification infrastructure and service specialization stratify competitive positioning across contract types.
| Leading Market Players |
|---|
| CBRE Group Inc. |
| Sodexo Inc. |
| ISS A/S |
| ABM Industries Inc. |
| Cushman & Wakefield Plc |
| GDI Integrated Facility Services Inc. |
| Guardian Service Industries Inc. |
| AHI Facility Services Inc. |
| SMI Facility Services |
| Others |
Value Network & Pricing Analysis
Ninety-day chemical inventory cycles for EPA Safer Choice certified products concentrate procurement leverage among multi-state operators while compressing margins for regional vendors lacking volume scale. This lead-time band directly shapes pricing power across the ISO 41001 qualified tier versus non-certified competitors.
Pricing Analysis
Certification level creates the primary spread between ISO 41001 qualified operators and regional competitors, with three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels dominating contract structures. Price differentiation hinges on Joint Commission healthcare credentials and EPA green chemical verification, with cost compression in the economy tier intensifying due to OSHA compliance infrastructure requirements. Corporate office buyers exhibit lowest price sensitivity where workplace experience metrics drive vendor selection, while educational institutions remain most sensitive to per-square-foot service rates.
Supply Chain Analysis
Strategic stockpiling of specialized cleaning chemicals and PPE dominates inventory strategy over just-in-time approaches, reflecting pandemic-era disruption memories and EPA procurement preference volatility. Supply concentration rests on Mexico for nearshored staffing pools, the United States for electrostatic disinfection equipment manufacturing, and Canada for provincial certification framework compliance services. Critical dependencies include green cleaning chemical formulations, IoT sensor hardware, and clinical training infrastructure. Single-source vulnerability runs through EPA Safer Choice product approvals. Distribution runs through integrated service platforms with multi-state coverage rather than fragmented regional operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 41001 certification deadlines and EPA green procurement mandates are accelerating vendor consolidation faster than organic growth can replenish competitive density.
For Market Incumbents: Shield market position by accelerating backward integration into certified chemical supply chains and captive training academies for Joint Commission healthcare protocols. Consolidate regional operators in Texas and California metropolitan corridors before certification barriers harden. Vertical control over compliance infrastructure represents the critical defensive lever against margin compression from non-qualified competitors. For New Entrants and Emerging Players: Anchor in educational institution cost-plus contracts where ISO 41001 certification timelines create temporary bidding windows for agile operators. Target underpenetrated community college portfolios in Sun Belt expansion corridors. Lead with IoT-enabled predictive cleaning platforms as differentiated go-to-market positioning against legacy time-and-materials incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from real estate investment trusts divesting non-core facility management subsidiaries to focus on property acquisition strategies. Five-to-ten year viability favors operators with cross-border US-Canada compliance infrastructure over pure-play domestic specialists. Monitor EPA Safer Choice product list expansion velocity as inflection indicator for green cleaning mandate enforcement intensity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 41001 Certification Investment | Creates qualified service tier access for multi-year corporate campus contracts across Sun Belt metros. |
| Backward Integration into Green Chemical Supply | Secures EPA Safer Choice inventory continuity while capturing margin from procurement markups. |
| IoT Platform Deployment | Enables predictive cleaning schedules tied to occupancy sensors for labor deployment optimization. |
| Healthcare Clinical Training Infrastructure | Unlocks Joint Commission-compliant contracts with quarterly audit capabilities and premium pricing. |
| Cross-Border US-Canada Compliance Buildout | Preserves service scalability for integrated North American portfolios amid regulatory divergence. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with facility directors at healthcare systems, corporate real estate portfolio managers, educational institution procurement officers, and soft services vendor executives. Secondary validation drew from OSHA enforcement databases, EPA Safer Choice product registries, ISO certification body disclosures, and commercial real estate absorption reports. Bottom-up contract value aggregation and top-down market sizing triangulation anchored volume estimates.
Across the analysis window, forecasts model service type segmentation by daily recurrence intensity and compliance documentation burden, end-user verticals by Joint Commission and OSHA regulatory exposure, and contract structures by risk allocation sophistication. CAGRs derive from trajectory fitting to historical outsourcing penetration rates and post-pandemic hygiene protocol permanence assumptions. Labor cost inflation indices and commercial real estate vacancy projections feed scenario-weighted outputs.
Decision-makers should treat outputs as directional under assumptions of sustained OSHA enforcement intensity and EPA green procurement preference stability; material deviation would warrant model refresh. Revision becomes warranted when provincial certification divergence between US federal standards and Canadian frameworks crosses thresholds that fragment cross-border service scalability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
China Facility Management Market
Facility Management
Warehouse Management Service Market
Facility Management
Facility Management Services Market
Facility Management
Asia-Pacific Hard Facility Management Market
Facility Management
Slovak Republic Facility Management Market
Facility Management
Malta Facility Management Market
Facility Management
North America Facilities Management Market
Facility Management
Middle East and Africa Hard Facility Management Market
Facility Management
GCC Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
UK Facility Management Market
Facility Management
Bahrain Facility Management Market
Facility Management
South Africa Facility Management Market
Facility Management
Panama Facility Management Market
Facility Management
Saudi Arabia Soft Facility Management Market