
 South Africa Facility Management Market | 2026-2036
South Africa Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Facility Management Market Analytics
Asset-light service contracts and equipment-leasing arrangements is narrowing the capital barrier for mid-tier competitors entering integrated facilities management. Excellerate Services leverages its national footprint to sustain multi-site contracts across retail and banking estates. Tsebo Facilities Solutions anchors its position through vertical integration into cleaning, security, and technical maintenance streams. SSG Holdings competes on technology leadership by deploying proprietary workforce-management platforms.
Facility management encompasses the coordination of physical infrastructure, operational services, and workplace systems to ensure buildings function safely, efficiently, and in compliance with regulatory standards. Core activities span HVAC maintenance, energy monitoring, space planning, and environmental health compliance across commercial, institutional, and industrial properties. Cleaning Services and Security Management dominate current revenue pools due to labor intensity and mandatory provisioning in commercial leases. IoT Solutions and CMMS represent the fastest-expanding technology categories as building owners prioritize predictive maintenance and real-time energy analytics over reactive service models.
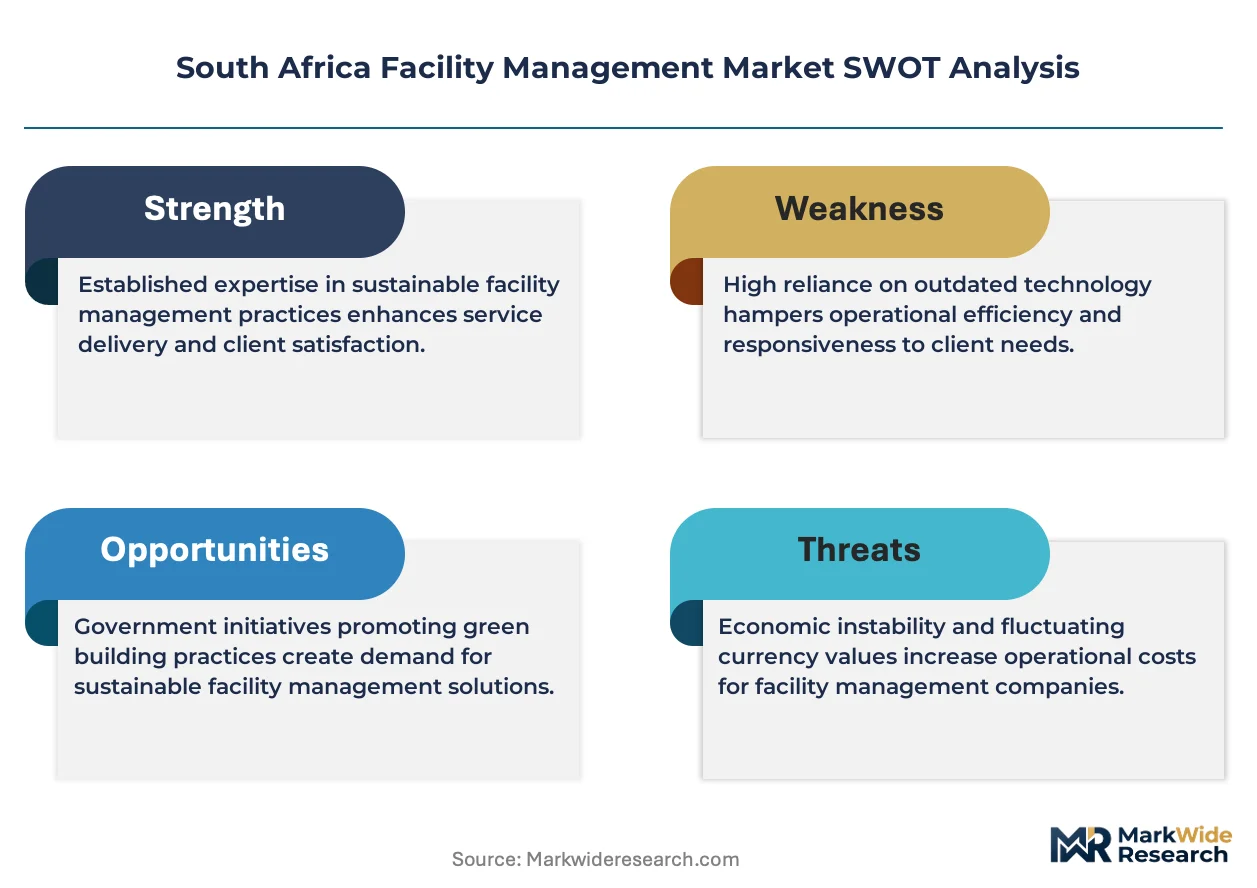
South Africa's National Regulator for Compulsory Specifications enforces SANS building and fire safety standards that mandate regular inspection and certification cycles. The Department of Employment and Labour's Occupational Health and Safety Act shapes demand for specialized compliance-management services and trained technical personnel. The country's central bank and National Treasury procurement frameworks increasingly require facilities vendors to meet B-BBEE ownership and local-content thresholds. Stakeholders must monitor how pending amendments to energy-efficiency regulations and carbon-reporting obligations will reshape service specifications and vendor qualification criteria.
Market Dynamics
Johannesburg's commercial precincts and Cape Town's mixed-use developments are pulling integrated facilities management contracts toward bundled service models that compress vendor counts and extend contract tenures.
Growth Catalysts
- National Building Regulations:Mandatory fire safety and accessibility upgrade cycles under the National Building Regulations and Building Standards Act sustain recurring compliance-driven maintenance spend across aging commercial stock.
- Healthcare Facilities:Gauteng and KwaZulu-Natal provinces are expanding hospital and clinic infrastructure, generating dedicated facilities management procurement streams for infection control and critical systems uptime.
- IoT Solutions:Building owners are deploying sensor networks for real-time energy analytics, creating attach rates for predictive maintenance software and remote monitoring service tiers.
Market Restraints
- Skilled Labor Scarcity:South Africa's technical certification pipeline for HVAC and electrical trades constrains service expansion velocity and inflates wage premiums for qualified technicians.
- Capital Intensity:Equipment-leasing arrangements narrow mid-tier competitor access to integrated contracts requiring upfront technology platform investments and fleet standardization.
- Regulatory Friction:B-BBEE ownership thresholds in National Treasury procurement frameworks disqualify foreign-owned vendors from public-sector and parastatal facilities contracts.
Strategic Opportunities
- Energy-Efficiency Mandates:Pending amendments to carbon-reporting obligations will force building owners to contract specialized energy auditing and retrofit project management services.
- Retail Banking Estates:Multi-site branch networks present white space for national-footprint vendors offering standardized security, cleaning, and technical maintenance across dispersed locations.
- CMMS Convergence:Integration of workforce-management platforms with legacy building automation systems creates differentiation for technology-capable service providers.
Industry Challenges
- Certification Timelines:SANS building and fire safety inspection cycles create revenue recognition gaps and working capital pressure for inspection-dependent service lines.
- Legacy System Integration:Predictive maintenance deployments face interoperability barriers with decades-old HVAC and access control infrastructure in Johannesburg's commercial core.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Facility Management Market |
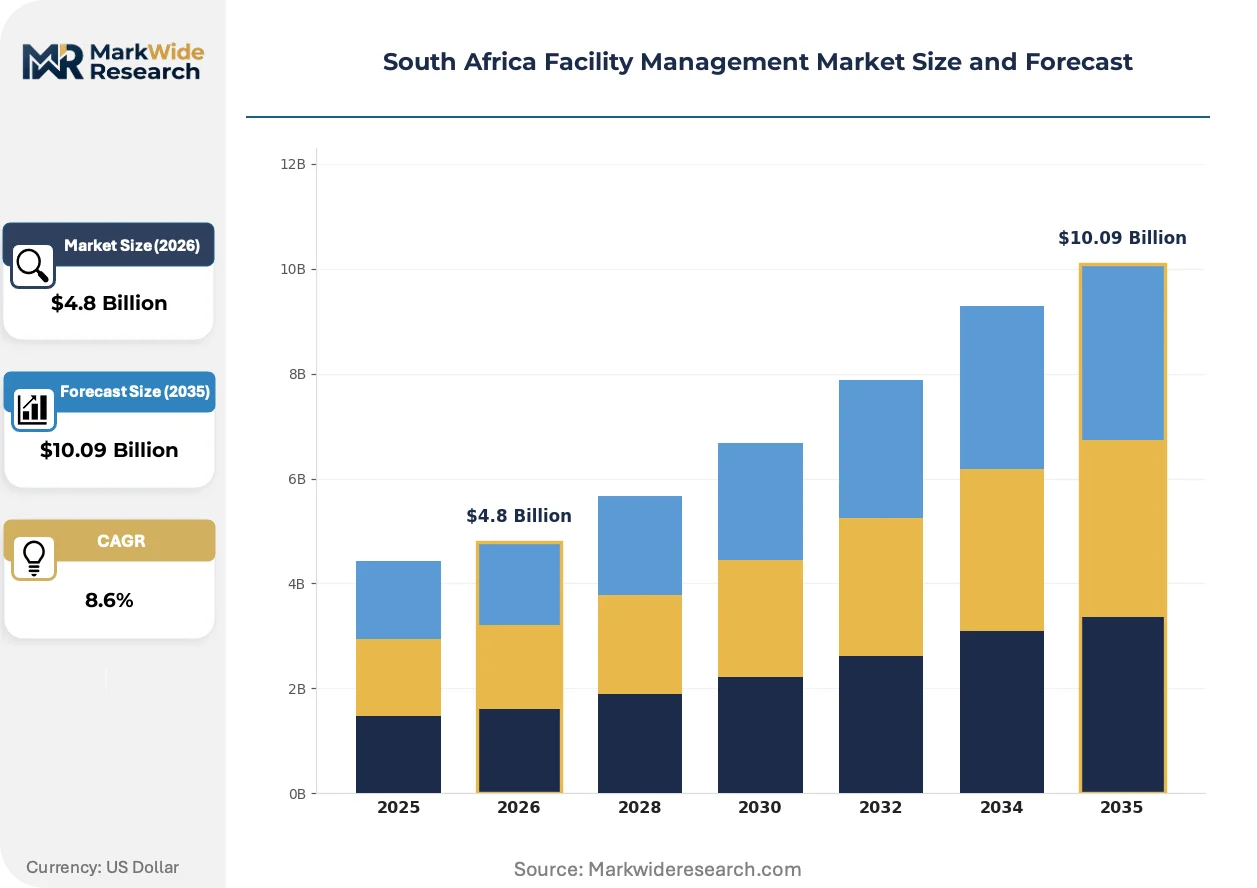
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Security Management, Maintenance Services, Landscaping End User: Commercial Buildings, Educational Institutions, Healthcare Facilities, Industrial Parks Technology: Building Management Systems, IoT Solutions, Energy Management Software, CMMS Application: Asset Management, Space Management, Environmental Management, Compliance Management |
| Companies Covered | Chiefton Facilities Management (Pty) Ltd, Excellerate Services, Matrix Consulting Services, Integrico (Pty) Ltd, Akweni Group Property Solutions (Pty) Ltd, SGS SA, Tsebo Facilities Solutions, SSG Holdings, Facilities Management Solutions (Pty) Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Facility Management Market Evolving Landscape
Digital infrastructure is compressing reactive service models into predictive operating frameworks, while regulatory pressure and buyer consolidation reshape vendor selection criteria.
Predictive maintenance algorithms are rendering obsolete scheduled-interval servicing for HVAC and electrical systems. Large commercial landlords in Johannesburg's Sandton precinct are adopting these platforms fastest, compressing technician dispatch frequencies and shifting contract structures toward outcome-based availability guarantees rather than time-and-materials billing.
The Department of Employment and Labour's Occupational Health and Safety Act amendments are tightening trained personnel mandates for high-risk maintenance activities. Industrial facilities and healthcare estates face stepped-up audit frequencies, driving demand for compliance-documentation software and certified technical workforce provisioning from facilities vendors.
Buyers are consolidating vendor relationships into single-source integrated contracts spanning cleaning, security, and technical streams. Property management firms in Cape Town's Atlantic Seaboard developments are displacing fragmented point-solution procurement, favoring vendors with captive supply of all three service categories and unified SLA reporting.
South Africa Facility Management Market Segmentation
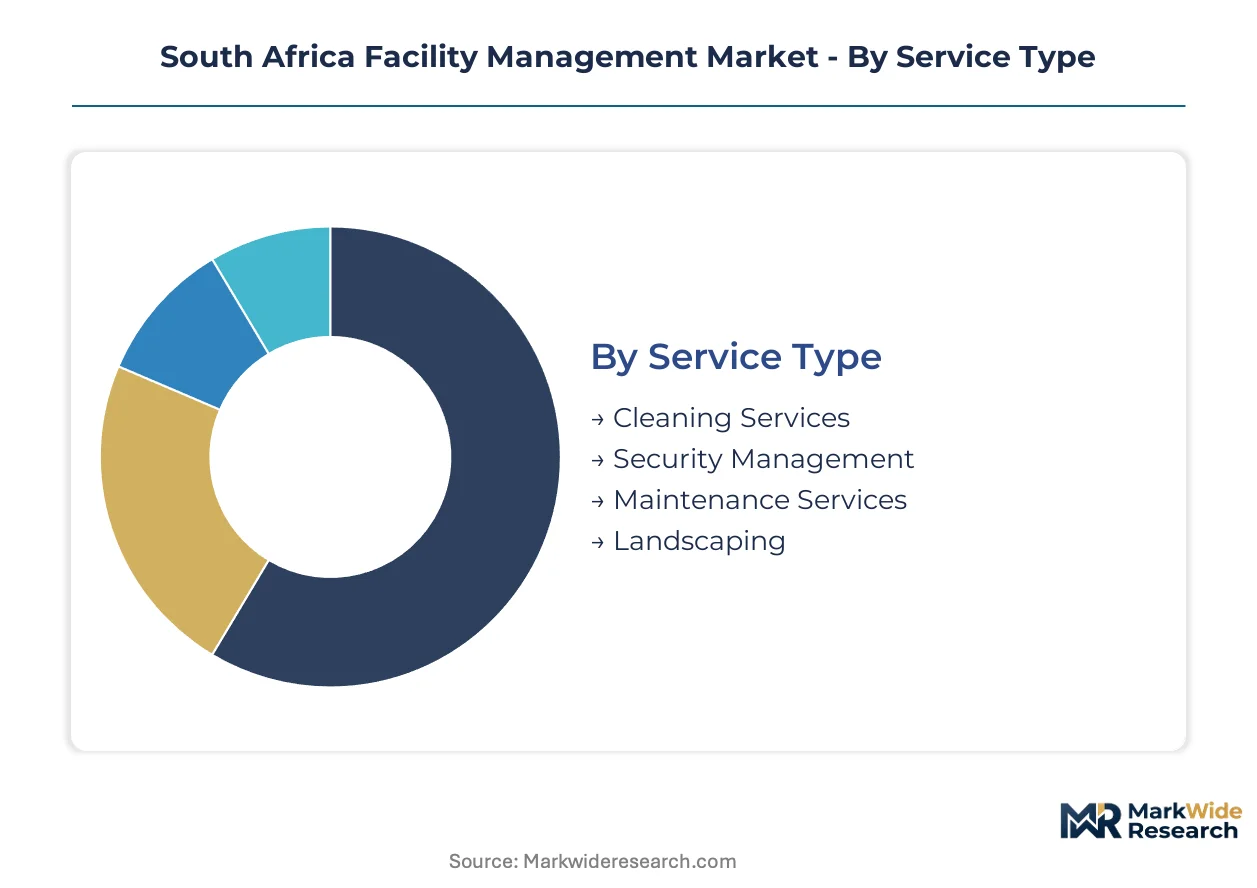
Service bundling across cleaning, security, and technical streams reshapes how procurement teams evaluate vendor capabilities in South Africa's facilities market. Segmentation reveals where technology adoption outpaces labor-intensive traditions and which verticals absorb compliance-driven spending mandates.
Service Type:
Mature labor-intensive segments dominate current revenue pools, while technology-augmented service lines emerge as margin expansion levers.
- Cleaning Services:Labor-heavy janitorial and specialized sanitation contracts anchor baseline revenue across commercial leases. Gauteng's retail banking estates generate concentrated demand for standardized multi-site cleaning protocols with strict SLA reporting.
- Security Management:Manned guarding and electronic surveillance integration requires B-BBEE-compliant workforce provisioning under National Treasury frameworks. Johannesburg's commercial precincts prioritize vendors with national vetting capabilities and centralized command infrastructure.
- Maintenance Services:HVAC, electrical, and plumbing technical streams face skilled certification bottlenecks.
- Landscaping:Grounds maintenance and irrigation management concentrate in Cape Town's Atlantic Seaboard mixed-use developments.
Cleaning Services handles the majority of throughput; IoT-augmented Maintenance Services is the fastest mover on share.
End User:
Customer-type concentration varies sharply between compliance-heavy institutional verticals and cost-sensitive commercial portfolios.
- Commercial Buildings:Office towers and retail centers in Sandton and Cape Town CBD drive bundled integrated facilities management contracts. Property managers favor single-source vendors compressing vendor counts across cleaning, security, and technical streams.
- Healthcare Facilities:Hospital and clinic infrastructure expansion across Gauteng and KwaZulu-Natal generates specialized procurement for infection control and critical systems uptime. The Department of Employment and Labour's Occupational Health and Safety Act mandates trained personnel for high-risk maintenance activities.
- Educational Institutions:University campuses and school districts require seasonal staffing flexibility and security compliance.
- Industrial Parks:Manufacturing estates demand predictive maintenance platforms and energy auditing services.
Commercial Buildings absorbs the largest contract value; Healthcare Facilities climbs the fastest as provincial infrastructure budgets expand.
Technology:
Adoption curves separate legacy building automation from cloud-native predictive platforms.
- IoT Solutions:Sensor networks for real-time energy analytics and occupancy monitoring attach to predictive maintenance software tiers. Large Sandton landlords deploy these platforms fastest, compressing technician dispatch frequencies toward outcome-based availability guarantees.
- CMMS:Computerized maintenance management systems integrate workforce platforms with legacy HVAC infrastructure, though interoperability barriers persist in Johannesburg's aging commercial core.
- Building Management Systems:Centralized control platforms for HVAC, lighting, and access dominate established building stock.
- Energy Management Software:Carbon-reporting compliance tools gain traction as pending amendments to energy-efficiency regulations force audit documentation.
Building Management Systems retains installed-base dominance; IoT Solutions gains share fastest among new construction and major retrofits.
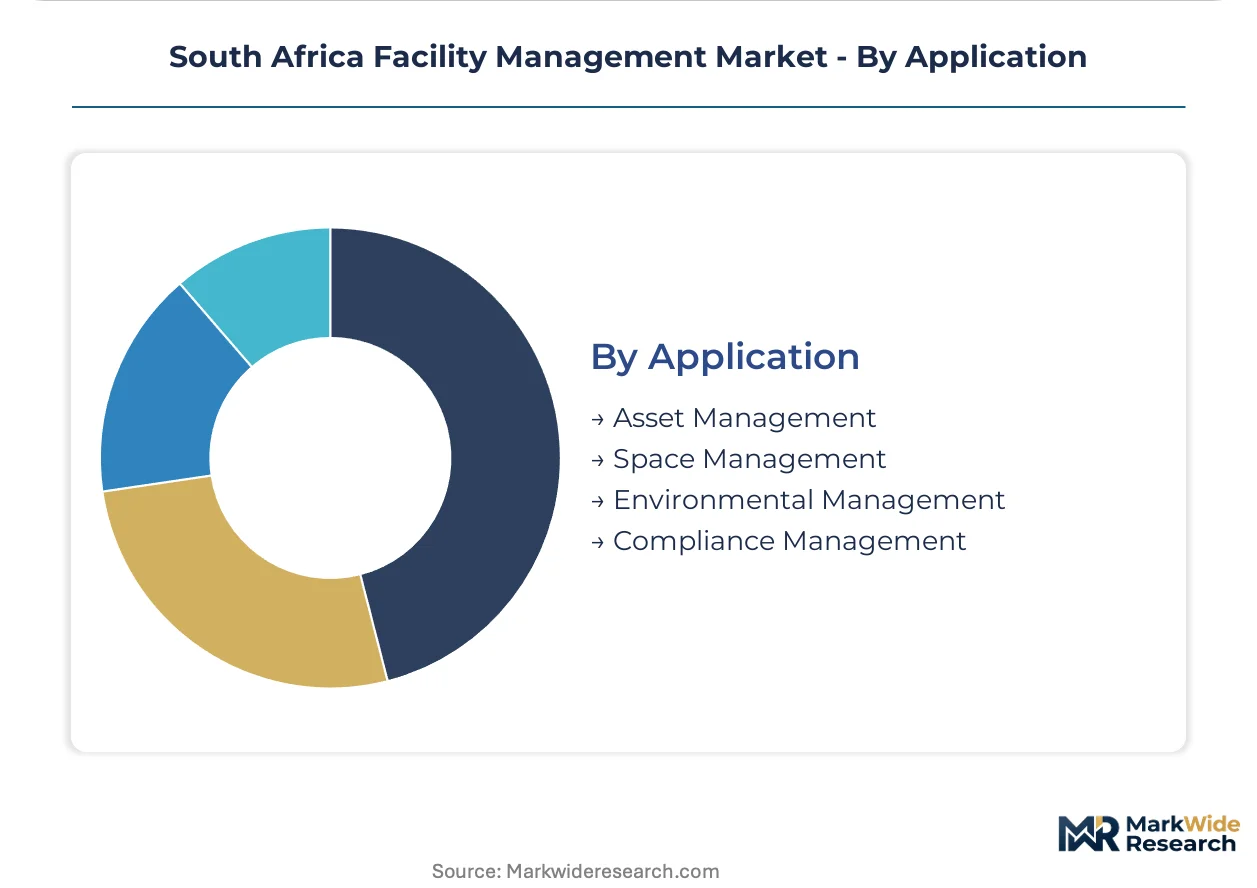
Application:
Functional use cases align with regulatory pressure points and operational cost centers.
- Compliance Management:SANS building and fire safety inspection cycles under the National Building Regulations create recurring certification revenue. Documentation software and trained technical workforce provisioning differentiate vendor offerings.
- Asset Management:Lifecycle tracking for HVAC, electrical, and structural systems supports capital planning decisions. Cape Town property firms prioritize unified SLA reporting across dispersed portfolios.
- Space Management:Occupancy analytics and workplace reconfiguration services respond to hybrid work patterns.
- Environmental Management:Waste, water, and air quality monitoring aligns with corporate sustainability commitments.
Asset Management carries the heaviest software attach rates; Compliance Management expands most quickly under tightening audit frequencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's facility management sector generates surplus service capacity that regional neighbors import, while equipment and technology components flow inward from European and Asian suppliers. Gauteng and Western Cape provinces anchor domestic demand concentration. Cross-border contract awards into Botswana, Namibia, and Mozambique extend South African vendor reach.
Gauteng
Johannesburg's Sandton commercial precinct and Pretoria's government cluster drive bundled integrated facilities management procurement. The National Treasury's B-BBEE procurement frameworks mandate local ownership thresholds for public-sector contracts. Healthcare facility expansion across the province generates specialized demand for infection control and critical systems maintenance.
Western Cape
Cape Town's Atlantic Seaboard mixed-use developments favor single-source vendors combining cleaning, security, and technical streams. The National Building Regulations and Building Standards Act enforces fire safety inspection cycles that sustain compliance-driven service revenue. Stellenbosch's university and research estates require seasonal staffing flexibility and specialized laboratory maintenance protocols.
KwaZulu-Natal
Durban's port logistics corridor and Richards Bay industrial zone generate demand for predictive maintenance platforms and energy auditing services. The Department of Employment and Labour's Occupational Health and Safety Act shapes trained personnel mandates for high-risk industrial maintenance. Hospital infrastructure expansion across the province creates dedicated procurement streams for healthcare facilities management.
Eastern Cape
Gqeberha's automotive manufacturing cluster and East London's industrial parks require specialized technical maintenance for production-critical infrastructure. Provincial procurement frameworks increasingly mirror national B-BBEE ownership requirements. Nelson Mandela Bay's commercial property stock drives demand for bundled service contracts compressing vendor counts.
Free State
Bloemfontein's government and educational institutions anchor steady demand for compliance-documentation and seasonal facilities services. The central province's location supports multi-site contract logistics for national-footprint vendors serving retail banking estates. Mining and agricultural processing facilities in the northern Free State require specialized environmental and asset management services.
South Africa Facility Management Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying discrete service modules. The South Africa facility management market structures around three distinct tiers: national-scale integrated providers, regional specialists with captive supply chains, and technology-forward mid-tier entrants leveraging asset-light contract models. Consolidation pressures favor vendors with unified SLA reporting across cleaning, security, and technical streams. Competitive moves center on geographic footprint expansion and workforce-management platform deployment.
Among Johannesburg-based integrated providers, Excellerate Services and Tsebo Facilities Solutions exemplify the national-footprint archetype serving multi-site retail and banking estates. SSG Holdings occupies a position within the technology-differentiated tier, representing vendors deploying proprietary platforms for predictive maintenance and real-time workforce coordination. These three companies anchor the competitive structure through which procurement teams evaluate bundled service capabilities and compliance-documentation standards.
| Leading Market Players |
|---|
| Chiefton Facilities Management (Pty) Ltd |
| Excellerate Services |
| Matrix Consulting Services |
| Integrico (Pty) Ltd |
| Akweni Group Property Solutions (Pty) Ltd |
| SGS SA |
| Tsebo Facilities Solutions |
| SSG Holdings |
| Facilities Management Solutions (Pty) Ltd |
| Others |
Value Network & Pricing Analysis
Overcapacity in Gauteng's security services labor pool compresses contract margins while simultaneously enabling aggressive pricing postures from national-footprint vendors seeking to displace regional competitors. This utilization dynamic feeds back into supplier consolidation, as mid-tier operators accept extended payment terms from equipment financiers to maintain workforce deployment scale.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across technical maintenance streams, with pricing stratifies across premium certification tiers, volume scale commitments, and geographic delivery radius. Cost compression in mid-market cleaning services is intensifying because asset-light entrants lease equipment rather than deploy owned fleets. Retail banking estates exhibit highest price sensitivity due to standardized multi-site procurement protocols, while healthcare facilities demonstrate lowest sensitivity given infection-control certification mandates.
Supply Chain Analysis
Extended payment terms from European HVAC component suppliers and supply-chain finance facilities from Asian IoT sensor manufacturers structure working capital requirements for South African integrators. Equipment and technology components draw from Germany, China, and South Korea, while raw material dependencies span steel fabrication inputs, electronic control modules, and specialized cleaning chemicals. Single-source vulnerability concentrates in proprietary workforce-management software licenses. Distribution runs through national-footprint service hubs in Johannesburg, Cape Town, and Durban with last-mile technician dispatch.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against in-house facilities teams at large commercial landlords building captive technical capabilities. Automation of routine maintenance tasks represents the most credible substitute threat incumbents must navigate.
For Market Incumbents: Insulate integrated contract positions by deepening captive supply of certified technical personnel and deploying proprietary CMMS platforms that embed switching costs. The substitute threat of landlord in-house teams demands workforce certification investments under the Department of Employment and Labour's Occupational Health and Safety Act as the priority defensive lever.
For New Entrants and Emerging Players: Mid-market commercial buildings in Eastern Cape and Free State provinces represent the most penetrable entry point given lower incumbent saturation and provincial procurement frameworks mirroring national B-BBEE requirements. A go-to-market angle anchored to energy auditing services pending carbon-reporting amendments offers differentiation without direct confrontation with national-scale integrated providers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light service contract models enabled by equipment-leasing arrangements. Long-term viability over the analysis window favors acquisition targets with established B-BBEE ownership structures and captive technical certification pipelines. The signal to monitor is amendment timing to energy-efficiency regulations that would force building owner retrofit spending.
| Strategic Initiative | Industry Significance |
|---|---|
| CMMS Platform Integration | Unifies SLA reporting across cleaning, security, and technical streams for Sandton commercial landlords. |
| Technical Workforce Certification | Addresses skilled labor scarcity under Department of Employment and Labour mandates for high-risk maintenance. |
| Energy Auditing Service Launch | Captures pending carbon-reporting amendment demand from Cape Town Atlantic Seaboard mixed-use developments. |
| Multi-Site Contract Consolidation | Compresses vendor counts for retail banking estates across Gauteng and KwaZulu-Natal provinces. |
| B-BBEE Ownership Restructuring | Qualifies vendors for National Treasury procurement frameworks governing public-sector facilities contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with facilities directors at commercial property firms, procurement leads at healthcare estates, technical maintenance managers, security operations controllers, and cleaning services contract administrators. Secondary validation drew from National Treasury procurement framework disclosures, Department of Employment and Labour regulatory filings, SANS building standards documentation, and industry association membership records. Bottom-up contract value aggregation and top-down macroeconomic scaling were triangulated to establish market boundaries.
Calibration against historical contract award patterns and disclosed vendor revenue footprints anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, end-user vertical, technology adoption tier, and provincial regulatory cluster. CAGRs were derived from fitted trend extrapolation adjusted for policy inflection points, with forecast inputs incorporating healthcare infrastructure budget allocations and energy-efficiency amendment probability assessments.
Practitioners should monitor regulatory amendment timelines for early signals of forecast revision, particularly carbon-reporting obligation finalization and B-BBEE threshold adjustments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Chile Facility Management Market
Facility Management
Norway Facility Management Market
Facility Management
United States Facility Management Market
Facility Management
North America Hard Facility Management Market
Facility Management
Europe Soft Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
Egypt Facility Management Market
Facility Management
Europe Hard Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
North America Facilities Management Market
Facility Management
China Facility Management Market
Facility Management
Asia Pacific Facility Management Market
Facility Management
Asia-Pacific Hard Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
Malta Facility Management Market
Facility Management
Finland Facility Management Market