
 Canada Facility Management Market | 2026-2036
Canada Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Facility Management Market Outlook
Healthcare infrastructure spending is expanding across Canadian provinces, pulling facility management contracts toward specialized medical cleaning, HVAC compliance, and 24/7 security protocols. GDI Integrated Facility Services leverages its national scale to anchor hospital and long-term care accounts. Brookfield Global Integrated Solutions Canada LP sustains competitive positioning through integrated asset management platforms. CBRE Group differentiates via technology-forward workplace strategy advisory tied to lease administration.
Canada Facility Management encompasses the coordinated delivery of hard services (mechanical, electrical, plumbing maintenance) and soft services (cleaning, security, waste removal) to maintain operational continuity of commercial, institutional, and industrial buildings. The discipline applies standardized work order systems, preventive maintenance scheduling, and regulatory compliance tracking to reduce asset downtime and extend building lifecycle performance. Hard maintenance commands the largest revenue pool due to skilled labor requirements and capital-intensive equipment replacement cycles. IoT Solutions within the Technology segment is expanding fastest as building operators deploy sensor networks for predictive HVAC diagnostics and real-time energy monitoring. Integrated contracts are capturing margin preference as clients consolidate vendor relationships under single-accountability frameworks.
Health Canada sets infection control benchmarks that directly shape cleaning protocols in healthcare-adjacent facility contracts. The National Building Code of Canada and provincial energy regulators enforce escalating efficiency standards that retrofitters must navigate to maintain certification eligibility. CSA Group standards govern electrical and mechanical safety compliance, creating recurring audit demand for third-party facility auditors. Stakeholders must monitor how carbon performance disclosure rules reshape capital planning priorities for building owners.
Market Dynamics
Consolidation of vendor relationships under single-accountability frameworks is compressing contract structures across Canadian commercial real estate. Building owners now demand unified hard and soft service delivery from single providers rather than fragmented specialist networks.
Growth Catalysts
- National Building Code of Canada updates:Tightening energy efficiency mandates for commercial buildings are accelerating retrofit demand and pulling long-term facility management contracts toward compliance-focused providers.
- Healthcare infrastructure expansion:Provincial capital programs for hospitals and long-term care facilities are generating specialized contracts for medical-grade cleaning, HVAC compliance, and continuous security protocols.
- IoT sensor networks:Predictive diagnostics for mechanical systems are reducing unplanned downtime and extending asset lifecycles in Ontario and British Columbia commercial portfolios.
Market Restraints
- Skilled trades shortage:Licensed electricians and HVAC technicians concentrate in Toronto and Vancouver, creating wage pressure and service coverage gaps in secondary markets.
- Input cost volatility:Refrigerant prices fluctuate under federal hydrofluorocarbon phase-down schedules, compressing margins on HVAC maintenance contracts.
- Contractor consolidation limits:Three national providers control integrated platform capacity, restricting mid-tier competitors from scaling beyond regional footprints.
Strategic Opportunities
- Carbon performance disclosure rules:Federal and provincial mandates for operational emissions reporting are creating advisory revenue streams for facility managers with energy analytics capabilities.
- Indigenous community infrastructure:Federal settlement agreements and northern development programs are opening underpenetrated markets for remote facility operations.
- Convergence of digital twin and AI:Building information modeling integrated with machine learning is enabling predictive maintenance at scale for multi-site corporate clients.
Industry Challenges
- Certification timeline compression:CSA Group electrical and mechanical safety audits face backlogs, delaying contract commencement and revenue recognition.
- Legacy system integration friction:Older building automation protocols resist seamless connection to cloud-based work order platforms, requiring costly middleware development.
- Specialized cleaning credential scarcity:Health Canada infection control certification for healthcare-adjacent contracts cannot scale with provincial hospital expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Facility Management Market |
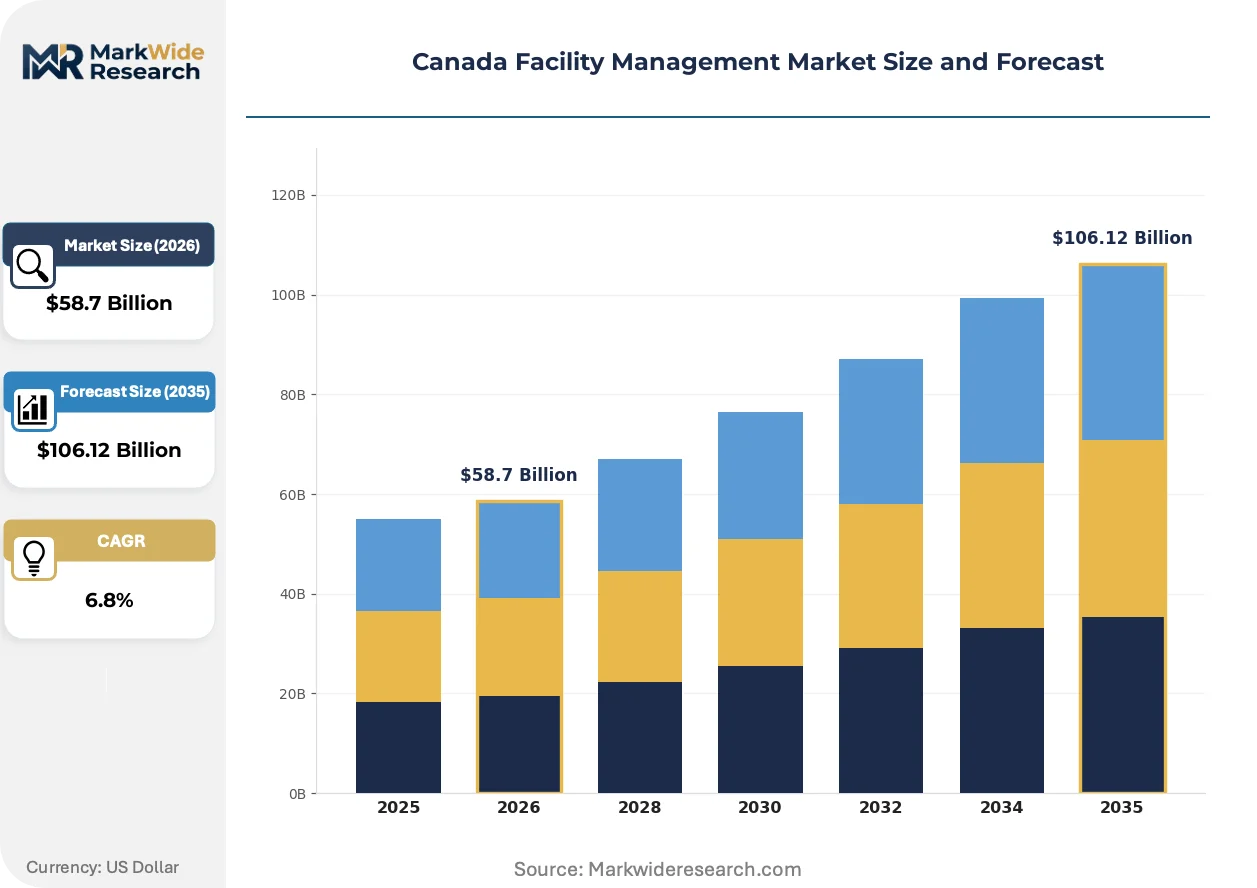
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
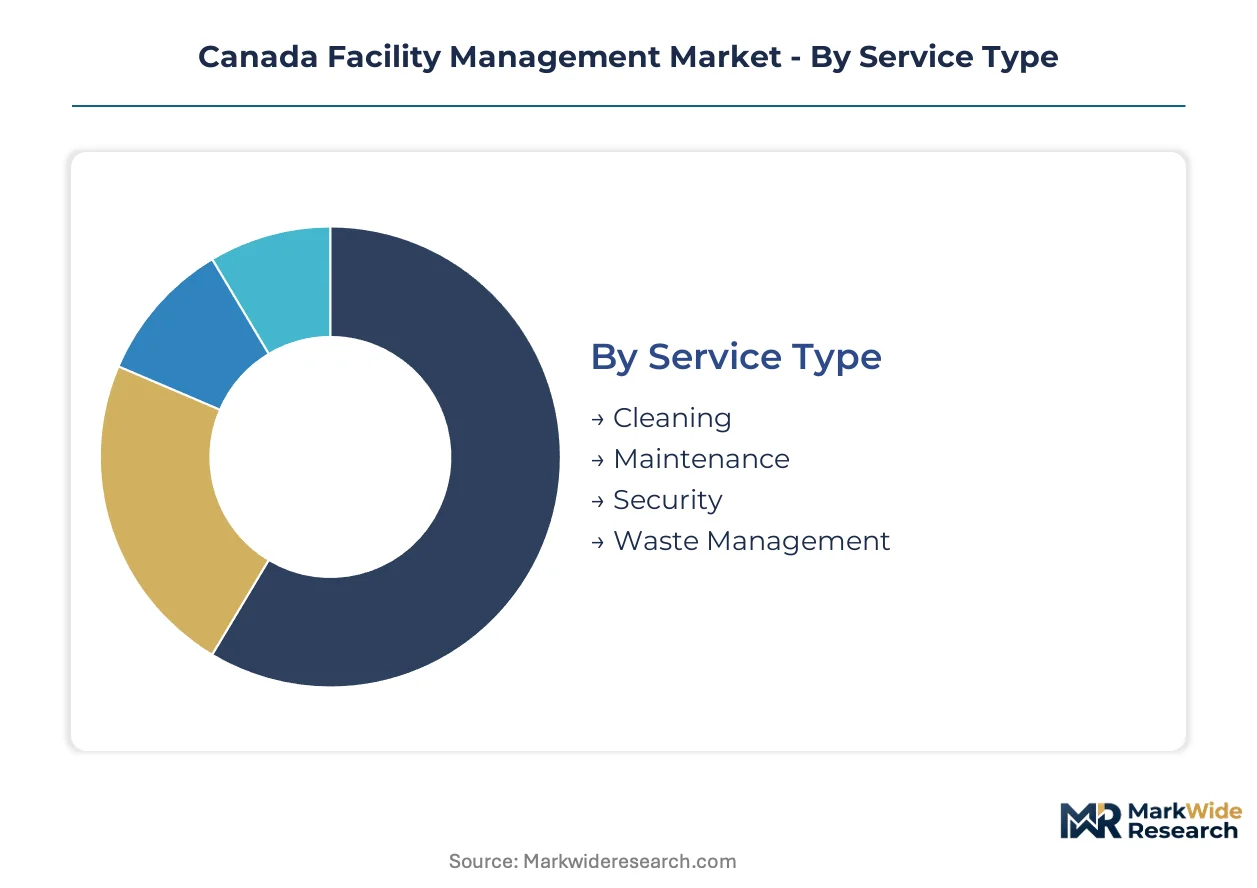
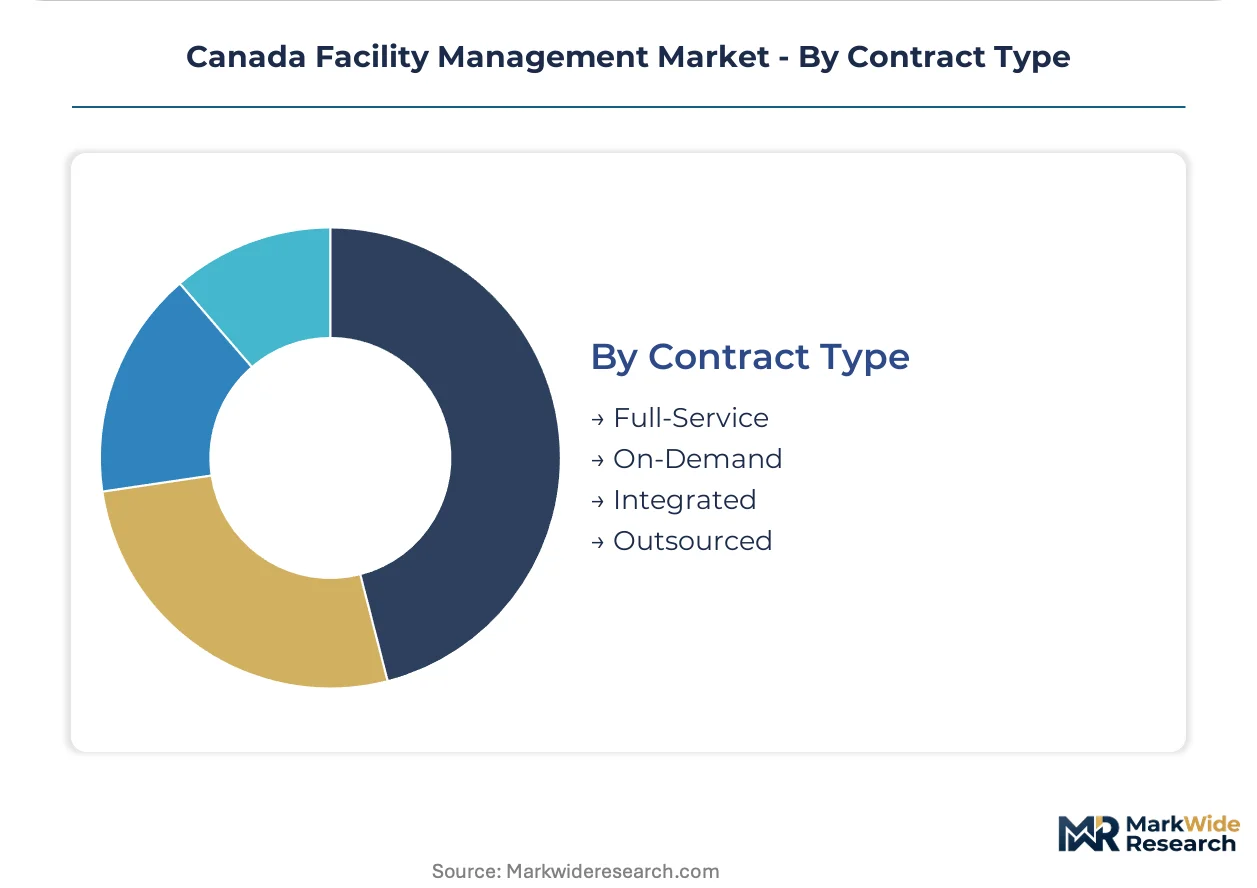
| Segmentation | Service Type: Cleaning, Maintenance, Security, Waste Management Client Type: Healthcare, Education, Retail, Hospitality Technology: IoT Solutions, Cloud Services, Energy Management, Automation Contract Type: Full-Service, On-Demand, Integrated, Outsourced |
| Companies Covered | GDI Integrated Facility Services, Brookfield Global Integrated Solutions Canada LP, Aecon Group Inc, ION Facility Services Inc, Cushman and Wakefield, JLL Limited, CBRE Group, Black & McDonald, ISS Global, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Facility Management Market Strategic Shifts
Digital infrastructure is rewiring how Canadian facility operators deliver and monetize building services. Three interconnected developments are compressing traditional contract structures while opening new performance-based revenue models.
IoT-enabled building automation is electrifying competitive positioning across the sector. Sensor networks now stream real-time HVAC performance data to centralized dashboards, enabling predictive maintenance before system failures trigger tenant complaints. Large commercial landlords in Toronto and Vancouver are mandating these installations in new lease agreements. The technology is electrifying margin structures by converting fixed-price maintenance contracts into performance-guarantee arrangements with penalty clauses.
Health Canada is tightening infection control benchmarks for healthcare-adjacent facilities through updated guidance documents and provincial enforcement protocols. These standards now require documented cleaning frequencies, validated disinfectant contact times, and audit trails for high-touch surfaces. Long-term care operators in Ontario and British Columbia are responding by outsourcing to facility managers with dedicated healthcare credentials rather than generalist commercial cleaners.
Corporate real estate directors are consolidating vendor relationships under integrated service contracts that bundle hard maintenance, soft services, and workplace strategy advisory. This procurement compression displaces fragmented specialist networks in favor of single-accountability providers. The shift is most visible in Calgary and Montreal office markets, where landlords face vacancy pressure and seek operational cost transparency to retain anchor tenants.
Canada Facility Management Market Segmentation
Facility management contracts in Canada fragment across service intensity, client risk profiles, and technology integration depth. Understanding these splits reveals where procurement budgets concentrate and how vendors must configure delivery models to capture share.
Service Type:
Buyers differentiate by whether they need continuous labor presence or intermittent technical intervention.
- Maintenance:Hard services encompassing mechanical, electrical, and plumbing systems demand licensed trades and capital equipment access. Demand concentrates in Ontario and British Columbia commercial portfolios where aging HVAC infrastructure requires preventive scheduling under National Building Code efficiency mandates.
- Cleaning:Soft service delivery spans routine janitorial to medical-grade disinfection protocols. Ontario hospital expansion and long-term care provincial capital programs are pulling contracts toward providers with Health Canada infection control certification.
- Security:Personnel-based and technology-enabled protection services for commercial and institutional assets.
- Waste Management:Collection, sorting, and disposal coordination aligned with municipal diversion targets and hazardous material handling requirements.
Volume sits with Maintenance; growth tilts toward Cleaning.
Client Type:
Risk tolerance and regulatory exposure shape how clients structure facility relationships.
- Healthcare:Hospitals, long-term care, and clinics require 24/7 operational continuity with strict infection control and emergency response protocols. Provincial infrastructure spending across Canadian provinces is expanding contract pipelines for specialized facility managers.
- Education:School boards and universities balance seasonal demand fluctuations with aging building portfolios. British Columbia and Ontario districts are consolidating vendor relationships under single-accountability frameworks to reduce administrative overhead.
- Retail:High-traffic commercial spaces prioritize rapid response and brand-aligned presentation standards.
- Hospitality:Hotels and event venues demand flexible staffing models with guest experience integration.
Healthcare commands premium pricing; Education offers volume scale.
Technology:
Digital maturity determines whether contracts include performance guarantees or remain cost-plus arrangements.
- IoT Solutions:Sensor networks for predictive HVAC diagnostics and real-time energy monitoring are expanding fastest. Toronto and Vancouver landlords now mandate these installations in new lease agreements, converting fixed-price maintenance to outcome-based contracts with penalty clauses.
- Energy Management:Systems optimization for carbon performance disclosure compliance under federal and provincial mandates. Building operators in Calgary and Montreal office markets seek advisory revenue streams tied to operational emissions reporting.
- Cloud Services:Centralized work order platforms and mobile workforce management applications.
- Automation:Robotic cleaning systems and building control integration reducing labor dependency.
IoT Solutions is climbing the fastest; Cloud Services provides infrastructure foundation.
Contract Type:
Procurement structure reflects client preference for cost predictability versus flexibility.
- Integrated:Single-accountability frameworks bundling hard services, soft services, and workplace strategy. Calgary and Montreal office markets show this shift most visibly as landlords face vacancy pressure and seek operational transparency.
- Full-Service:Comprehensive facility management under long-term agreements with defined service level agreements.
- On-Demand:Reactive service dispatch without committed volume or preventive scheduling.
- Outsourced:Transfer of in-house facility functions to third-party operators with asset responsibility.
Integrated contracts are gaining share fastest; On-Demand retains spot-market relevance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility management services concentrate where commercial building stock and regulatory pressure intersect most intensely. Ontario and British Columbia generate disproportionate contract volume, while Alberta and Quebec sustain specialized demand tied to energy and institutional infrastructure. Provincial energy codes and healthcare capital programs reshape regional competitive positioning.
Ontario
Toronto's dense commercial core drives integrated contract demand as landlords consolidate vendor relationships under single-accountability frameworks. The National Building Code of Canada updates tighten energy efficiency mandates, accelerating retrofit procurement across Greater Toronto Area office portfolios. Hospital expansion in Ottawa and Hamilton pulls specialized healthcare facility management contracts toward providers with Health Canada infection control certification.
British Columbia
Vancouver's premium office market mandates IoT sensor networks in new lease agreements, converting fixed-price maintenance to outcome-based contracts. Provincial energy regulators enforce escalating efficiency standards that retrofitters must navigate to maintain certification eligibility. Long-term care provincial capital programs in Victoria and Surrey generate contracts for medical-grade cleaning and HVAC compliance.
Alberta
Calgary office market vacancy pressure pushes landlords toward operational cost transparency through integrated service contracts. The province's energy sector infrastructure sustains demand for industrial facility management and remote operations support. Edmonton institutional portfolios balance aging building stock with seasonal demand fluctuations through consolidated vendor relationships.
Quebec
Montreal commercial real estate directors adopt bundled hard maintenance, soft services, and workplace strategy advisory to retain anchor tenants. Provincial building codes and municipal diversion targets shape waste management and sustainability service requirements. Quebec City healthcare and education facilities generate volume scale for providers with French-language service capabilities.
Atlantic Canada
Federal settlement agreements and northern development programs open underpenetrated markets for remote facility operations in Indigenous community infrastructure. Smaller urban centers face skilled trades shortages that concentrate licensed electrician and HVAC technician availability in Halifax. Secondary markets experience service coverage gaps and wage pressure relative to Toronto and Vancouver benchmarks.
Canada Facility Management Market Competitive Environment
Top-tier vendors anchor national integrated platforms, while mid-tier competitors remain confined to regional footprints. Three national providers control the majority of bundled hard and soft service contracts under single-accountability frameworks. The competitive terrain separates into scale-driven integrators, specialized healthcare operators, and technology-forward workplace strategists. Consolidation through acquisition and vertical integration into energy analytics capabilities represent the dominant competitive moves reshaping vendor positioning.
Among Canada-based facility operators, GDI Integrated Facility Services and Brookfield Global Integrated Solutions Canada LP exemplify the integrated service archetype with national coverage. CBRE Group occupies a position representing technology-forward workplace strategy advisory tied to lease administration. These three anchors demonstrate how scale, specialization, and digital capability stratify competitive access to provincial healthcare infrastructure and commercial real estate contracts.
| Leading Market Players |
|---|
| GDI Integrated Facility Services |
| Brookfield Global Integrated Solutions Canada LP |
| Aecon Group Inc |
| ION Facility Services Inc |
| Cushman and Wakefield |
| JLL Limited |
| CBRE Group |
| Black & McDonald |
| ISS Global |
| Others |
Value Chain & Pricing Dynamics
Licensed HVAC technician wages in Toronto and Vancouver cascade through maintenance contract tiers, compressing margins on standardized service agreements while enabling premium pricing for emergency-response coverage in remote Atlantic Canada markets. Refrigerant costs under federal hydrofluorocarbon phase-down schedules feed directly into input cost volatility, forcing providers to renegotiate long-term contracts or absorb margin erosion.
Pricing Analysis
Cost-down pressure on integrated service bundles accelerates because three national providers dominate capacity, restricting price competition to credential differentiation and performance-guarantee terms. Three-tier pricing structure across certified-premium, standard-compliance, and economy-response levels separates healthcare-adjacent contracts with Health Canada infection control mandates from general commercial cleaning. Price differentiation hinges on CSA Group electrical safety certification tier and 24/7 emergency response commitment. Healthcare buyers show lowest price sensitivity due to operational continuity requirements; retail and hospitality segments drive hardest bargain on unit-rate negotiations.
Supply Chain Analysis
Dual-sourcing requirements for critical HVAC components now mandate qualified backup suppliers after refrigerant supply disruptions exposed single-source vulnerability. Equipment and specialized chemicals draw from domestic Canadian distributors, U.S. Midwest manufacturing clusters, and German automation technology providers. Skilled trades labor pools concentrate in Ontario and British Columbia, creating geographic dependency for licensed technician deployment. Supply chain risk centers on tariff exposure for U.S.-sourced building automation hardware under evolving trade frameworks. Distribution runs through regional service hubs with mobile technician dispatch rather than centralized inventory models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada Facility Management Market functions as a cost-of-compliance arena where National Building Code energy efficiency mandates erect certification barriers that favor incumbent players with established audit relationships and capital reserves for retrofit equipment.
For Market Incumbents: Anticipate margin compression from mid-tier competitors acquiring IoT analytics capabilities by locking in multi-year integrated contracts before carbon performance disclosure rules mature. Defensive consolidation through backward integration into energy advisory services creates captive revenue streams. Prioritize CSA Group certification investment to accelerate audit timeline advantages over challengers facing backlog delays. For New Entrants and Emerging Players: Capture Indigenous community infrastructure contracts in Atlantic Canada and northern territories where federal settlement agreements outpace national provider coverage expansion. Remote facility operations in underpenetrated markets tolerate higher price points due to logistics complexity. Lead with French-language service capabilities in Quebec education and healthcare verticals where linguistic requirements filter competition. For Investors and Strategic Acquirers: Provincial hospital expansion announcements are the leading indicator that specialized healthcare facility management capacity will command acquisition premiums. Long-term viability rests on energy analytics platform ownership rather than pure labor arbitrage. Target mid-tier operators with Health Canada infection control credentials and established relationships with Ontario and British Columbia health authorities. Watch for CSA Group audit backlog resolution as signal for contract commencement velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Energy Analytics Platform Integration | Enables carbon performance advisory revenue under federal emissions disclosure mandates. |
| Healthcare Credential Acquisition | Health Canada infection control certification unlocks provincial hospital expansion contracts. |
| Indigenous Community Infrastructure Partnership | Federal settlement agreements create protected demand pools with limited national competition. |
| IoT Sensor Network Deployment | Toronto and Vancouver landlords now mandate predictive HVAC diagnostics in lease agreements. |
| CSA Group Certification Fast-Track | Accelerated electrical and mechanical safety audit completion compresses contract commencement timelines. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with facility management executives, hospital procurement directors, commercial real estate portfolio managers, and HVAC contractor operations leads. Health Canada guidance documents, National Building Code of Canada update notices, provincial energy regulator filings, and CSA Group standards publications provided regulatory trajectory validation. Bottom-up contract value estimates from identified provider portfolios reconciled against top-down provincial infrastructure spending announcements.
Data-stream reconciliation across service type segmentation, client vertical risk profiles, technology integration depth, and contract structure maturity shaped the analytical framework over the projection horizon. Modeled dimensions encompassed hard versus soft service intensity, healthcare versus education versus commercial client archetypes, IoT-enabled versus conventional delivery platforms, and integrated versus fragmented procurement structures. CAGRs derived from weighted average of historical contract value trajectories and announced provincial capital program pipelines, with carbon compliance cost pass-through assumptions for energy-intensive maintenance categories.
The model holds under steady provincial healthcare infrastructure spending and National Building Code enforcement continuity; deviation in federal trade policy affecting U.S. equipment sourcing or accelerated refrigerant phase-down schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Romania Facility Management Market
Facility Management
Warehouse Management Service Market
Facility Management
Soft Facility Management Market
Facility Management
Norway Facility Management Market
Facility Management
Luxembourg Facility Management Market
Facility Management
Latin America Soft Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
Bahrain Facility Management Market
Facility Management
Ireland Facility Management Market
Facility Management
Portugal Facility Management Market
Facility Management
Global Unified Facility Management Market
Facility Management
Chile Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Serbia Facility Management Market
Facility Management
Brazil Facility Management Market