
 Asia Pacific Office Real Estate Market | 2026-2036
Asia Pacific Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Office Real Estate Market Outlook
Hybrid-work skill adaptation across property management and tenant-experience design is bifurcating the competitive landscape into operators with embedded workplace-strategy teams and those reliant on traditional leasing. JLL leverages its integrated workplace consulting platform to capture advisory fees alongside lease transactions. Mitsubishi Estate Company anchors its regional position through concentrated ownership of premium Grade A towers in Tokyo's Marunouchi district. Frasers Property differentiates via mixed-use precincts that combine office, residential, and retail in Singapore and Australian gateway cities.
Asia Pacific office real estate comprises purpose-built commercial structures with floor plates typically exceeding 500 square meters, engineered for open-plan configuration, raised-floor systems, and centralized HVAC with energy-recovery ventilation, serving as primary operational infrastructure for knowledge-intensive enterprises. Grade A stock commands persistent rent premiums owing to scarcity of buildings meeting simultaneous criteria for transit connectivity, sustainability certification, and flexible floorplates. Co-working space and serviced offices are absorbing incremental demand from mid-size enterprises seeking lease-term flexibility without capital deployment into fit-outs. Investment strategies gravitate toward Core Plus and Value-Add categories as yield compression in stabilized assets pushes capital toward repositioning opportunities with measurable renovation upside.
Singapore's Building and Construction Authority mandates Green Mark certification thresholds that filter speculative supply, while Australia's National Construction Code enforces minimum energy-performance standards affecting refurbishment economics. India's RERA framework imposes project-level disclosure requirements that alter pre-commitment risk allocation between developers and occupiers. Stakeholders must monitor how evolving hybrid-work policies across multinational technology and financial-services tenants recalibrate effective space-per-employee metrics and, consequently, absorption timelines for new supply pipelines.
Market Dynamics
Hybrid work stabilization is compressing absorption timelines across Asia Pacific office markets, forcing developers to recalibrate pre-commitment strategies around reduced space-per-employee ratios and flexible lease structures.
Growth Catalysts
- Technology sector expansion:Software and IT services firms in Bangalore and Hyderabad are scaling leased footprints as return-to-office protocols mature. Campus-style developments along India's western corridor capture this demand.
- Singapore's Green Mark certification:Mandatory energy-efficiency thresholds under the Building and Construction Authority are filtering speculative supply and elevating certified stock premiums.
- India's RERA framework:Project-level disclosure requirements are reallocating pre-commitment risk toward developers, accelerating institutional capital deployment into compliant pipelines.
Market Restraints
- Grade A supply scarcity:Buildings meeting simultaneous criteria for transit connectivity, sustainability certification, and flexible floorplates face structural undersupply in Tokyo's Marunouchi district and Singapore's core.
- Refurbishment cost escalation:Australia's National Construction Code minimum energy-performance standards are raising capital requirements for repositioning older stock.
- Fit-out capital burden:Mid-size enterprises avoiding capital deployment into tenant improvements are compressing effective rents for landlords offering turnkey specifications.
Strategic Opportunities
- Mixed-use precinct development:Frasers Property's integrated office-residential-retail models in Australian gateway cities demonstrate replicable formats for capturing cross-syndicated demand.
- Workplace strategy advisory:Embedded consulting services capturing fees alongside lease transactions represent underpenetrated revenue pools for operators with tenant-experience capabilities.
- Co-working absorption channels:Serviced office providers are capturing incremental demand from enterprises seeking lease-term flexibility without long-term capital commitment.
Industry Challenges
- Workplace strategy talent scarcity:Property management teams lacking hybrid-work skill adaptation are losing competitive positioning to operators with dedicated tenant-experience design functions.
- Energy-recovery ventilation integration:Centralized HVAC retrofits in existing stock face technical complexity and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Office Real Estate Market |
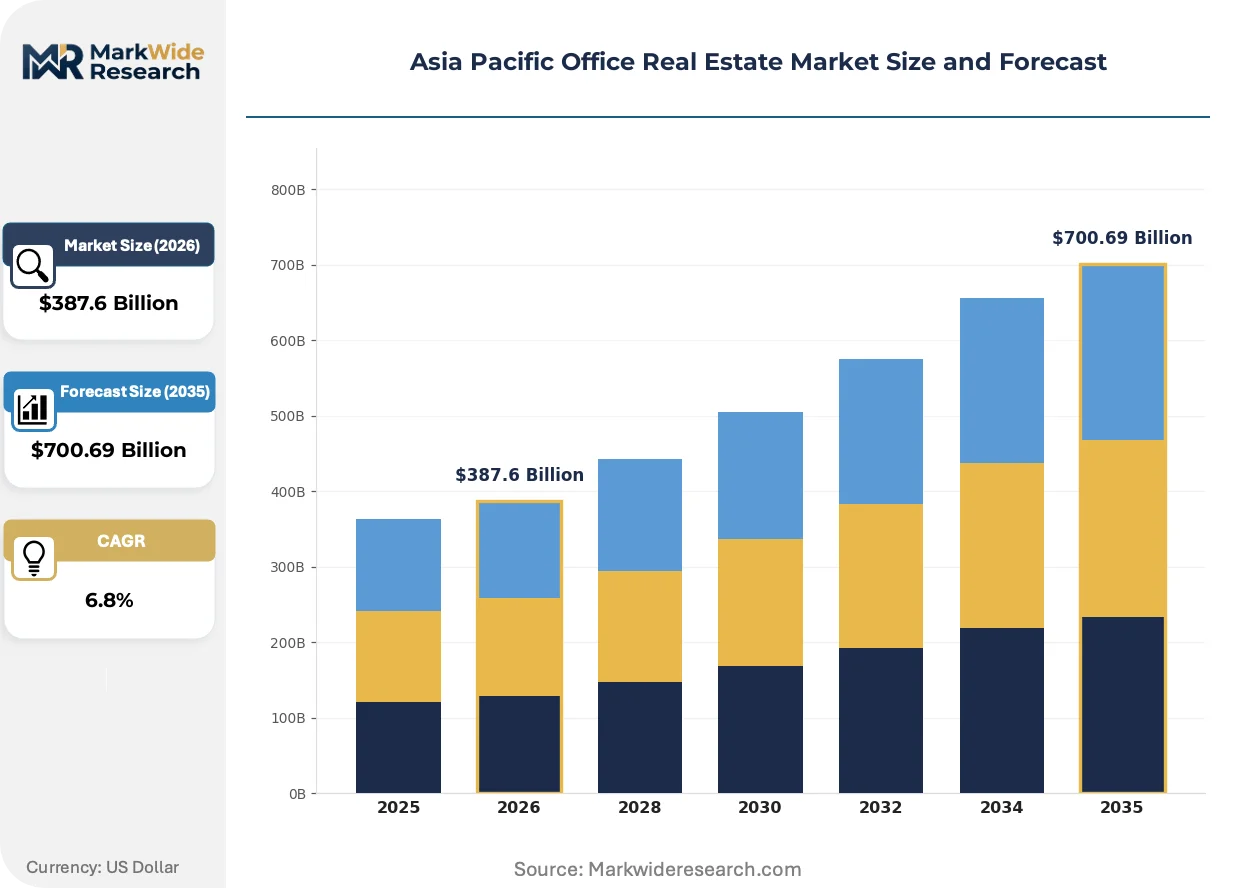
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Grade A, Grade B, Grade C, Serviced Office, Co-working Space Lease Structure: Gross Lease, Net Lease, Modified Gross Lease, Full-Service Lease, Percentage Lease End User: IT Firms, Financial Services, Consulting Firms, Legal Services, Creative Agencies Investment Strategy: Core, Core Plus, Value-Add, Opportunistic, Development |
| Companies Covered | Colliers, Frasers Property, CBRE, Henderson Land Development Company, CDL, JLL, Knight Frank, Mitsubishi Estate Company, Cushman & Wakefield, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Office Real Estate Market Strategic Shifts
Digital infrastructure embedded within office assets is compressing the boundary between building operations and tenant productivity tools, reshaping how landlords monetize space beyond base rent.
Smart building management systems integrating IoT sensors with predictive analytics are miniaturizing the cost and footprint of energy monitoring equipment. Technology and financial services tenants in Singapore and Sydney are specifying these capabilities in new lease negotiations. This compression is enabling real-time optimization of HVAC and lighting loads, reducing operational expenditure premiums that previously justified Grade A rent differentials.
Singapore's Building and Construction Authority is tightening Green Mark certification thresholds for new supply submissions. Developers face mandatory disclosure of embodied carbon metrics and energy-use intensity projections. Premium stock in the central business district is responding with integrated photovoltaic arrays and district cooling connections to maintain eligibility for institutional capital mandates.
Enterprise procurement of office space is fragmenting toward shorter lease terms with expansion-contraction rights. Multinational technology tenants in Bangalore and Hyderabad are negotiating 3-year base terms with modular growth options, displacing traditional 9-year locked structures. This compression is most visible in India's western corridor, where infrastructure upgrades support phased campus deliveries aligned to workforce scaling timelines.
Asia Pacific Office Real Estate Market Segmentation
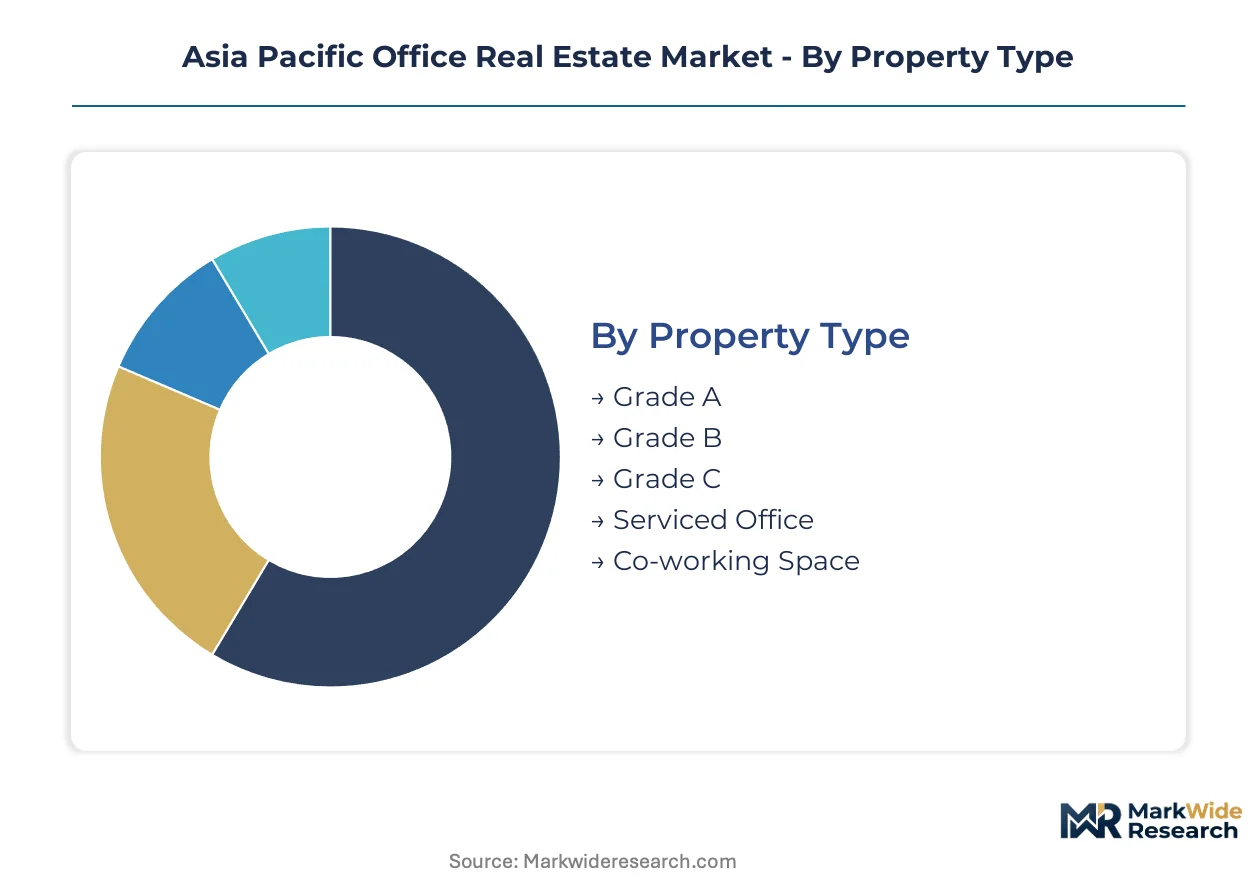
Asia Pacific office real estate segmentation reveals how capital deployment, tenant specifications, and regulatory frameworks fragment across property grades and lease structures. Distinct risk-return profiles emerge from Singapore's Green Mark mandates to India's RERA disclosure requirements, reshaping how investors and occupiers navigate supply pipelines.
Property Type:
Singapore's Building and Construction Authority Green Mark thresholds and Australia's National Construction Code energy standards create divergent compliance burdens across quality tiers.
- Grade A:Premium stock engineered for transit connectivity, sustainability certification, and flexible floorplates exceeding 500 square meters. Demand concentrates in Tokyo's Marunouchi district and Singapore's core CBD, where institutional capital mandates filter for energy-recovery ventilation and raised-floor systems.
- Grade B:Mid-tier assets with functional HVAC and standard floorplates lacking dual certification for transit access and green building standards. Bangalore and Hyderabad technology firms absorb this stock as secondary locations while scaling to Grade A campuses.
- Grade C:Older stock with legacy mechanical systems and limited repositioning economics under tightening energy codes.
- Serviced Office:Turnkey specifications with embedded reception, IT infrastructure, and short-term lease flexibility for mid-size enterprises avoiding fit-out capital deployment.
- Co-working Space:Open-plan configurations with modular expansion-contraction rights, capturing incremental demand from multinational technology tenants in India's western corridor.
Grade A handles the majority of throughput; Co-working Space is expanding most quickly on share.
Lease Structure:
Cost tier differentiation separates institutional-grade stability from operational risk transfer to tenants.
- Gross Lease:Landlord assumes property tax, insurance, and maintenance costs within base rent, preferred by financial services tenants seeking budget predictability in Singapore and Sydney CBD towers.
- Net Lease:Tenant reimburses operating expenses directly, shifting volatility risk and attracting value-add investors targeting yield compression through expense recovery optimization.
- Modified Gross Lease:Hybrid cost allocation with expense stops and caps, balancing landlord-tenant risk in secondary Australian gateway cities.
- Full-Service Lease:Comprehensive amenity bundling including cleaning, security, and reception, standard in Grade A stock with embedded workplace strategy teams.
- Percentage Lease:Rent tied to tenant revenue metrics, rare in office but emerging in mixed-use precincts with retail cross-syndication.
Gross Lease dominates institutional mandates; Net Lease is climbing the fastest as yield-seeking capital targets operational upside.
End User:
Application-specific space requirements drive divergent absorption timelines across knowledge-intensive sectors.
- IT Firms:Campus-style developments with redundant power, high-density cooling, and phased delivery aligned to workforce scaling. Demand clusters in Bangalore and Hyderabad as hybrid protocols mature and leased footprints expand.
- Financial Services:Trading floors with low-latency connectivity, backup generators, and compliance-grade security specifications. Singapore and Tokyo command persistent premiums for regulatory proximity.
- Consulting Firms:Project-room density and client-facing reception requirements, absorbing serviced office and co-working channels for flexibility.
- Legal Services:Confidential meeting suite ratios and document storage compliance, concentrating in established CBD towers with prestige address requirements.
- Creative Agencies:High-ceiling loft configurations and informal collaboration zones, driving adaptive reuse of industrial stock in Australian inner-urban precincts.
IT Firms anchor volume absorption; Financial Services maintains steepest rent premiums per square meter.
Investment Strategy:
Maturity-based risk stratification channels capital from stabilized yield to development ground-up exposure.
- Core:Stabilized Grade A assets in gateway cities with long-term lease profiles and minimal capital expenditure requirements. Singapore's Marina Bay and Tokyo's Otemachi district concentrate institutional mandate deployment.
- Core Plus:Light value creation through lease rollover optimization or minor amenity upgrades, capturing spread compression as hybrid work stabilizes effective rents.
- Value-Add:Repositioning older stock with HVAC retrofits, sustainability certification pursuit, and tenant-mix reconfiguration. Australia's National Construction Code raises capital requirements but institutional capital pursues measurable renovation upside.
- Opportunistic:Distressed acquisition or complex recapitalization with entitlement risk, targeting Mumbai and Pune infrastructure corridor timing.
- Development:Ground-up construction with pre-commitment dependency, filtered by India's RERA disclosure requirements reallocating risk toward compliant developers.
Value-Add handles majority of active capital deployment; Development is gaining share fastest as yield compression pushes risk tolerance outward.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Building and Construction Authority anchors regulatory standards across the region through mandatory Green Mark certification thresholds that filter speculative supply and elevate certified stock premiums.
Singapore
Financial services and technology tenants concentrate demand in the central business district, driving absorption of Grade A stock with integrated workplace amenities. The Building and Construction Authority mandates embodied carbon disclosure and energy-use intensity projections for new submissions. Marina Bay premium towers attract institutional capital through district cooling connections and photovoltaic arrays.
Japan
Multinational corporations sustain leasing velocity in Tokyo's established financial district, prioritizing transit connectivity and seismic resilience specifications. METI guidelines influence building energy performance benchmarking for large-scale commercial structures. Marunouchi and Otemachi districts concentrate ownership of premium Grade A inventory with long-term tenant profiles.
India
Technology sector expansion in software and IT services drives campus-style development along infrastructure corridors. The RERA framework imposes project-level disclosure requirements that reallocate pre-commitment risk toward compliant developers. Bangalore and Hyderabad absorb leased footprint growth as hybrid work protocols mature and workforce scaling continues.
Australia
Gateway city office markets face repositioning economics as energy-performance standards tighten refurbishment requirements. The National Construction Code enforces minimum standards affecting capital deployment into older stock upgrades. Sydney and Melbourne CBD towers specify smart building management systems in new lease negotiations with technology and financial services tenants.
South Korea
Corporate headquarters and professional services sustain demand in Seoul's concentrated commercial districts, with technology tenants specifying digital infrastructure integration. National building codes emphasize energy efficiency and green certification alignment with institutional investor mandates. Yeouido and Gangnam sub-markets concentrate premium stock with transit-oriented development characteristics.
Asia Pacific Office Real Estate Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with property management platforms and development houses occupying distinct competitive positions. The market structure separates operators with embedded workplace consulting capabilities from transaction-focused leasing brokers. Three archetypes dominate: integrated real estate services firms with advisory platforms, concentrated premium asset owners, and mixed-use precinct developers. Competitive moves center on portfolio diversification into flexible lease products and strategic partnerships with technology infrastructure providers.
Within the integrated services tier, JLL and CBRE exemplify operators capturing advisory fees alongside lease transactions through workplace strategy capabilities. Mitsubishi Estate Company occupies a position as a concentrated premium asset owner anchoring regional presence through Grade A tower ownership. Frasers Property represents the mixed-use precinct archetype, combining office, residential, and retail formats across gateway cities.
| Leading Market Players |
|---|
| Colliers |
| Frasers Property |
| CBRE |
| Henderson Land Development Company |
| CDL |
| JLL |
| Knight Frank |
| Mitsubishi Estate Company |
| Cushman & Wakefield |
| Others |
Value Chain & Pricing Dynamics
Singapore's Building and Construction Authority Green Mark certification gates both supply qualification and price differentiation simultaneously, filtering speculative development while elevating rent premiums for certified stock across the Asia Pacific office real estate market.
Pricing Analysis
Tokyo's Marunouchi district commands the steepest rent spreads against secondary Indian markets, with Grade A towers achieving persistent premiums through transit connectivity and sustainability certification. Pricing stratifies across premium, standard, and economy tiers based on energy-recovery ventilation specifications and flexible floorplate engineering. Cost compression in Grade B repositioning is intensifying because Australia's National Construction Code raises minimum energy-performance thresholds. Mid-size enterprises seeking turnkey specifications exhibit highest price sensitivity, while financial services tenants in Singapore's Marina Bay demonstrate lowest sensitivity due to compliance-grade security requirements.
Supply Chain Analysis
Japan and Singapore anchor premium Grade A tower development, while India and Australia concentrate campus-style and repositioning pipelines. Construction inputs draw from steel fabrication in China, HVAC equipment from South Korea, and raised-floor systems from domestic suppliers. Single-source vulnerability sits with district cooling infrastructure concentrated in Singapore's central business district. Distribution runs through institutional capital mandates filtering development finance toward compliant projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific office real estate sits in early-cycle expansion as hybrid work stabilization recalibrates effective space-per-employee metrics and extends absorption timelines for certified stock.
For Market Incumbents: Compound defensive positioning through embedded workplace strategy advisory capabilities that capture fees alongside lease transactions. Deepen vertical integration into smart building management systems to counter technology infrastructure providers encroaching on tenant productivity monetization. Expand ownership concentration in Tokyo's Otemachi and Singapore's Marina Bay districts where Grade A scarcity sustains rent premiums. For New Entrants and Emerging Players: Workplace strategy talent scarcity in property management teams opens white-space for specialized consulting boutiques targeting mid-tier landlords lacking hybrid-work adaptation. India's western corridor between Mumbai and Pune offers the most penetrable geography, with infrastructure upgrades supporting phased campus deliveries. Lead with co-working absorption channels emphasizing modular expansion-contraction rights for technology tenants scaling leased footprints. For Investors and Strategic Acquirers: India's RERA framework reshapes the acquisition landscape by reallocating pre-commitment risk toward compliant developers with disclosed project pipelines. Long-term viability centers on Value-Add and Development strategies capturing renovation upside and ground-up yields as Core compression pushes risk tolerance outward. Monitor Green Mark threshold tightening as the signal indicating accelerated capital rotation toward certified stock.| Strategic Initiative | Industry Significance |
|---|---|
| Green Certification Pursuit | Singapore's Building and Construction Authority mandates filter speculative supply and elevate certified stock premiums for institutional capital. |
| Mixed-Use Precinct Development | Frasers Property's integrated office-residential-retail models demonstrate replicable formats for cross-syndicated demand capture. |
| Workplace Strategy Advisory | JLL's integrated consulting platform captures advisory fees alongside lease transactions through embedded tenant-experience capabilities. |
| Smart Building Integration | IoT sensor deployment with predictive analytics compresses operational expenditure premiums justifying Grade A rent differentials. |
| Campus-Style Phased Delivery | Bangalore and Hyderabad infrastructure corridors support modular expansion aligned to technology workforce scaling timelines. |
Study Parameters
Initial hypotheses were tested against primary input from property fund managers, development executives, tenant experience directors, and sustainability consultants and refined through secondary validation. Primary research combined structured interviews with institutional capital deployment leads and corporate real estate strategists at multinational technology and financial services firms. Secondary sources included Building and Construction Authority submission filings, National Construction Code compliance databases, RERA project disclosure registries, and listed developer financial statements. Bottom-up lease transaction analysis triangulated against top-down capital flow tracking across Core Plus and Value-Add investment mandates.
Variance decomposition separated volume drivers from value drivers across property grade, lease structure, end-use sector, and investment strategy dimensions. Segmentation modeling incorporated Grade A/Grade B/Serviced Office/Co-working property types, Gross/Net/Modified Gross lease structures, IT/Financial Services/Consulting end-user categories, and Core/Core Plus/Value-Add/Development investment approaches. CAGRs were derived from absorption timeline projections calibrated to hybrid work stabilization patterns and infrastructure corridor completion schedules. Forecast inputs included energy-performance standard tightening trajectories and institutional capital mandate evolution toward sustainability certification thresholds.
Material uncertainties — regulatory threshold acceleration, technology tenant footprint contraction, and capital flow redirection — sit outside the modeled envelope. Forecasts reflect assumptions around hybrid work protocol permanence and Green Mark eligibility maintenance for premium stock. Recalibration cycles align with material shifts in Building and Construction Authority mandate updates and National Construction Code revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
China Office Real Estate Market
Office Real Estate
Bahrain Flexible Office Space Market
Office Real Estate
Italy Office Real Estate Market
Office Real Estate
Asia Pacific Flexible Office Market
Office Real Estate
North America Flexible Office Market
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
Japan Office Real Estate Market
Office Real Estate
India Office Real Estate Market
Office Real Estate
South Korea Office Real Estate Market
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
Saudi Arabia Real Estate Market
Office Real Estate
Office Real Estate Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
Australia Co-Working Office Spaces Market