
 Europe Flexible Office Market | 2026-2036
Europe Flexible Office Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flexible Office Market Foresight
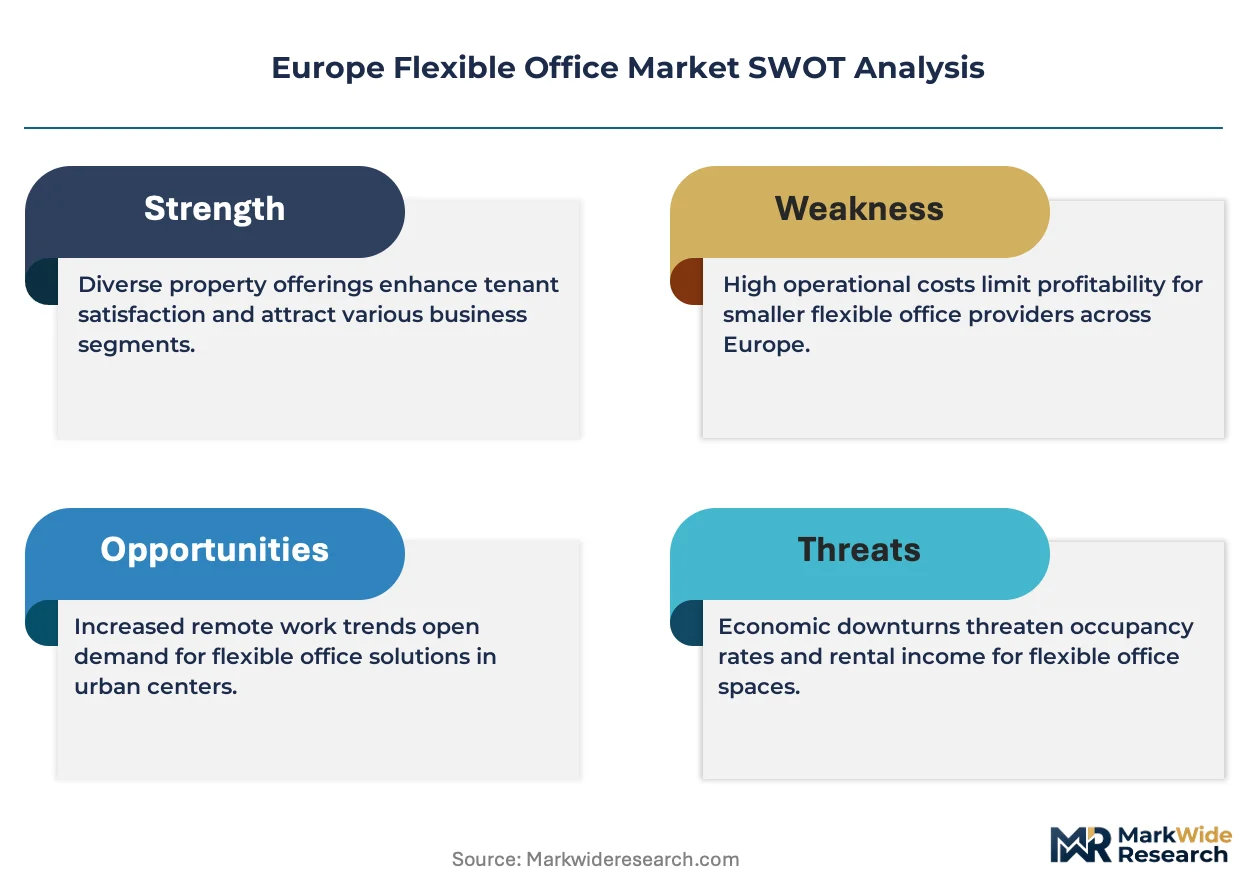
Enterprise occupiers is unwinding the startup-heavy demand profile that defined flexible office growth during the last decade. IWG leverages its Regus and Spaces brands to sustain the largest physical footprint across European capitals. Mindspace differentiates through design-led environments that command premium pricing in tier-one cities. Wojo anchors its expansion strategy through a partnership with Bouygues Immobilier, giving it captive access to new commercial developments.
Flexible office space denotes commercial real estate delivered under short-term or variable-length contracts, typically inclusive of furnishings, connectivity infrastructure, and shared amenities such as meeting rooms and breakout areas. The operational model eliminates capital expenditure for tenants while providing landlords with yield optimization through denser space utilization. Co-working spaces lead in transaction velocity across European hubs, though serviced offices capture disproportionate margin pools from legal and consulting tenants. Smart office solutions within the technology dimension are expanding fastest, driven by enterprise requirements for occupancy analytics and climate control integration.
The EU Green Deal and national transpositions of the Energy Performance of Buildings Directive shape refurbishment timelines and minimum efficiency standards for flexible office operators. ESG reporting under CSRD compels corporate tenants to verify the sustainability credentials of their workspace providers. Stakeholders must monitor how building certification thresholds alter site selection criteria and lease renewal decisions across European markets.
Market Dynamics
Enterprise adoption is displacing startup dominance as the primary demand engine across European flexible office markets, fundamentally altering space configuration requirements and contract structures toward longer tenures and dedicated floorplates.
Growth Catalysts
- EU Green Deal:Building efficiency mandates accelerate retrofit activity across existing commercial stock, expanding the addressable inventory for flexible office conversion.
- Corporate ESG reporting:CSRD obligations compel tenants to verify workspace sustainability credentials, favoring certified flexible operators over conventional leases.
- Hybrid work normalization:Enterprise real estate teams require distributed satellite locations, driving portfolio diversification beyond central business districts.
Market Restraints
- Energy cost volatility:Natural gas and electricity price swings compress operator margins on all-inclusive utility-inclusive contracts.
- Prime asset concentration:Grade-A supply concentrates in London, Paris, and Frankfurt, limiting expansion options in secondary cities.
- Debt financing friction:ECB interest rate policy elevates refinancing costs for development-stage operators acquiring leaseholds.
Strategic Opportunities
- Suburban penetration:Poland and Portugal exhibit underdeveloped flexible office density relative to enterprise employment growth.
- Smart building convergence:Integration of occupancy analytics with climate control systems creates premium positioning for tech-enabled operators.
- Repurposing tailwinds:National building efficiency codes in Germany and France incentivize conversion of obsolete commercial stock to flexible use.
Industry Challenges
- Fit-out capex intensity:Biophilic design and wellness certification requirements demand substantial upfront capital per square meter.
- Integration complexity:Enterprise clients require seamless connection to existing security, IT, and visitor management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flexible Office Market |
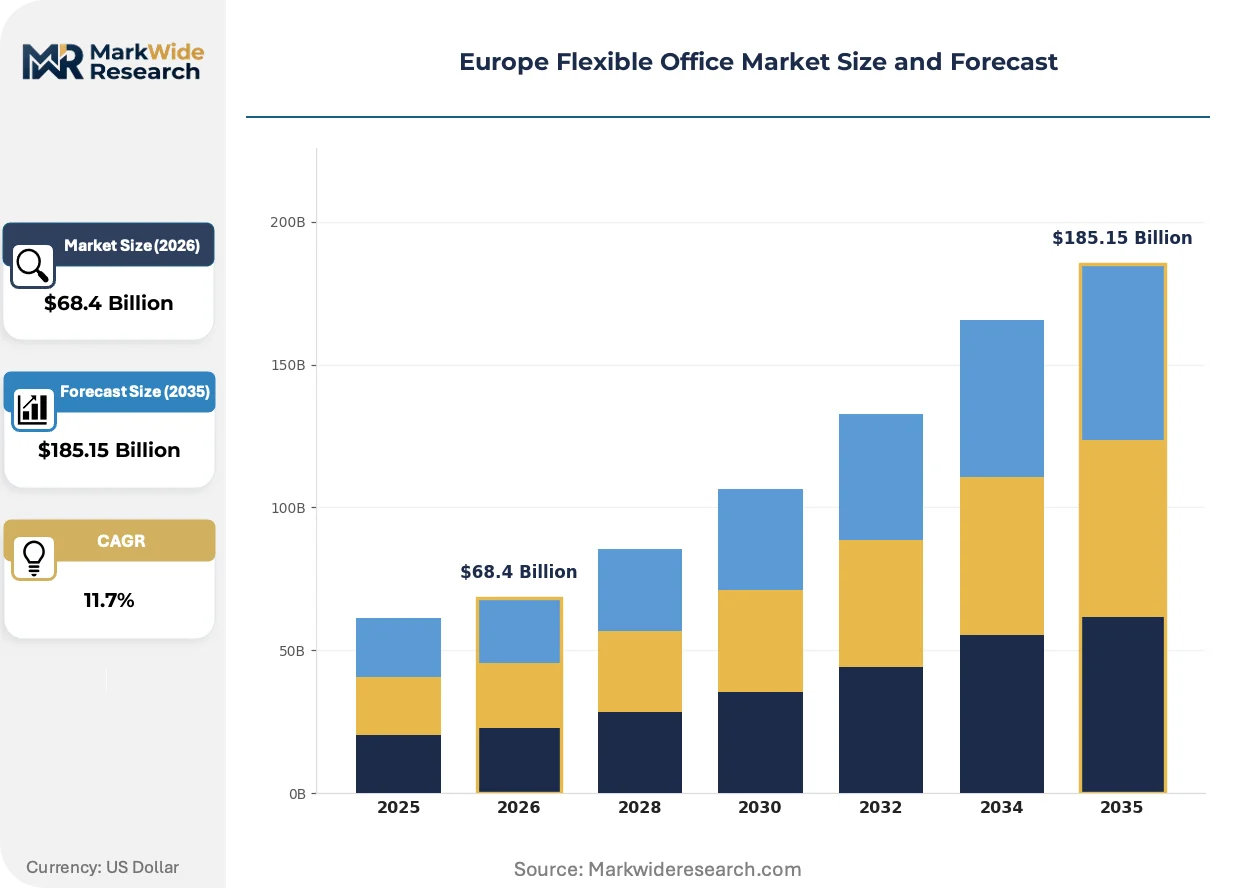
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Co-Working Spaces, Serviced Offices, Virtual Offices, Meeting Rooms End User: Startups, Freelancers, Enterprises, Remote Teams Service Type: Membership Plans, Pay-as-you-go, Hybrid Solutions, Custom Packages Technology: Smart Office Solutions, IoT Integration, Cloud Connectivity, Mobile Apps |
| Companies Covered | Mindspace, International Workplace Group (IWG), Regus Group Companies, Talent Garden, KNOTEL, WeWork, Wojo, Huckletree, The Office Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flexible Office Market Shifts & Advancements
Technology deployment and regulatory compliance are reshaping competitive positioning across European flexible office markets, creating divergence between premium tech-enabled operators and commodity space providers.
Smart office solutions encompassing occupancy sensors, air quality monitoring, and automated climate control is bifurcating the competitive landscape. Enterprise occupiers with CSRD reporting obligations prioritize these capabilities, compressing margins for operators unable to deliver verified environmental data. The technology is enabling yield optimization through dynamic space reconfiguration while compressing pricing power for undifferentiated providers.
CSRD transposition across EU member states mandates granular sustainability disclosure from corporate tenants. This regulatory framework compels verification of building energy performance and embodied carbon in fit-out materials. Legal and consulting sectors—heavy users of serviced offices—exhibit the most stringent supplier qualification requirements.
Enterprise procurement teams are consolidating vendor relationships and demanding multi-location framework agreements rather than site-by-site negotiations. This behavioral shift disrupts independent operators reliant on transactional leasing. The United Kingdom and Germany demonstrate the most advanced procurement sophistication, with facilities management teams integrating flexible office spend into broader real estate portfolio optimization.
Europe Flexible Office Market Segmentation
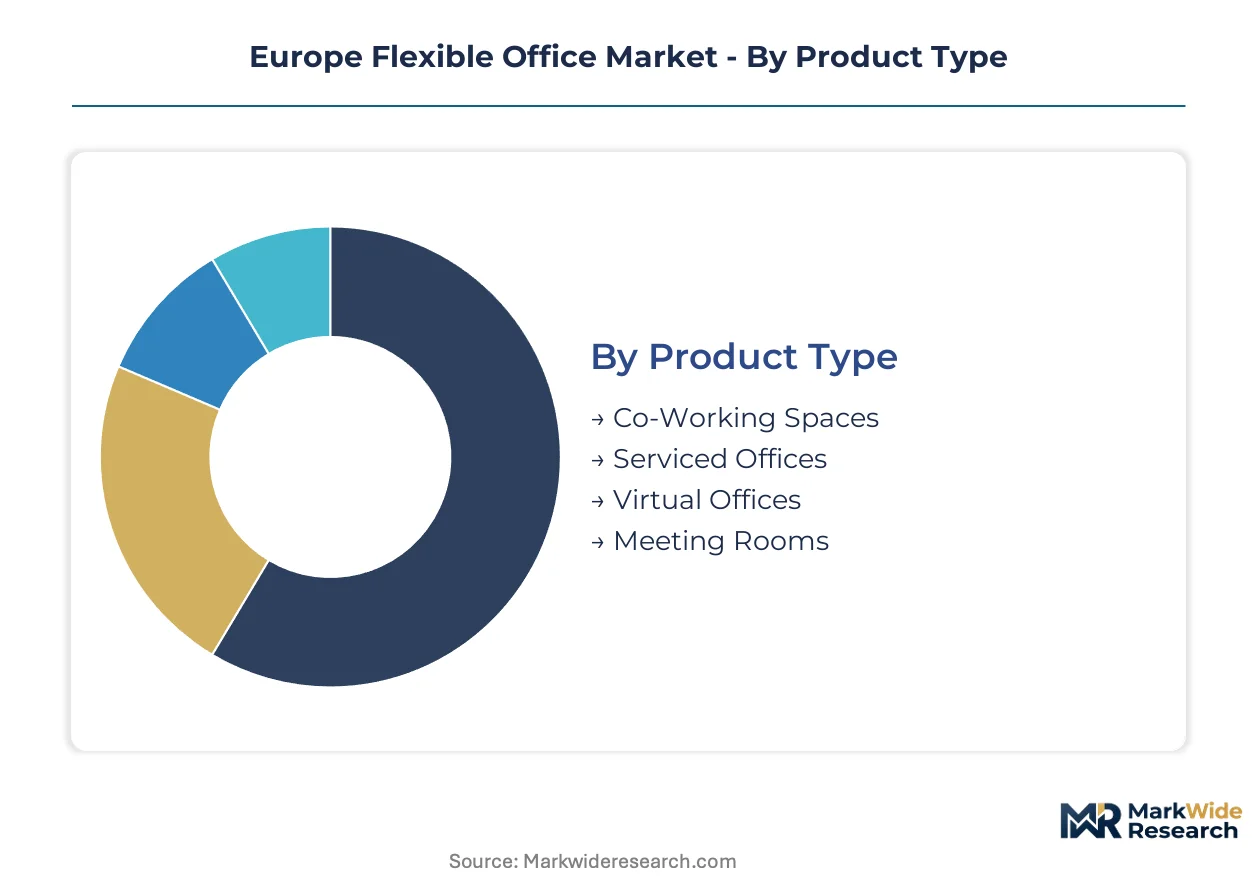
Segmentation in the Europe Flexible Office Market reveals how tenant requirements diverge across contract structures, technology readiness, and organizational scale. Operators must align service architecture with distinct procurement behaviors rather than applying uniform offerings.
Product Type:
Substitution pressure intensifies as conventional lease structures compete with flexible alternatives, particularly for occupiers seeking cost certainty without capital deployment.
- Co-Working Spaces:Open-plan environments with shared amenities and hot-desking arrangements. Demand concentrates among freelancers and early-stage ventures in Berlin, London, and Amsterdam where density economics support premium location access at reduced per-desk cost.
- Serviced Offices:Fully fitted private suites with dedicated reception and administrative support. Legal and consulting tenants in Paris and Frankfurt drive disproportionate margin capture through long-term contracts requiring confidentiality infrastructure.
- Virtual Offices:Mailing address and call handling services without physical occupancy. Remote-first enterprises in Portugal and Spain utilize these for market presence without real estate commitment.
- Meeting Rooms:Bookable conference and presentation facilities on hourly or daily terms. Corporate training teams and external board meetings generate intermittent but high-yield utilization.
Co-working spaces retain volume leadership; serviced offices hold the steepest expansion curve as enterprise procurement shifts toward professionalized flexible solutions.
End User:
Cost tier stratification separates price-sensitive individual users from enterprise buyers with consolidated procurement budgets and compliance requirements.
- Startups:Venture-backed companies requiring scalable headroom without lease liability. Demand clusters in technology corridors near venture capital access points.
- Freelancers:Independent professionals seeking community infrastructure and client meeting venues. Subscription elasticity and month-to-month terms dominate selection criteria.
- Enterprises:Established corporations deploying satellite locations for hybrid work mandates. CSRD reporting obligations under EU regulation compel sustainability verification from workspace providers.
- Remote Teams:Distributed employees requiring periodic physical collaboration points. Suburban and secondary city locations gain traction as commute tolerance declines.
Enterprises are climbing the fastest in absolute contract value; freelancers maintain the broadest geographic dispersion across price points.
Service Type:
Volume concentration favors predictable recurring revenue models over transactional arrangements as operators seek yield stability.
- Membership Plans:Fixed monthly fees for defined access levels and amenity bundles. Predictable cash flow supports operator financing and site expansion decisions.
- Pay-as-you-go:Usage-based billing without commitment. Appeals to project-based teams and seasonal staffing fluctuations in consulting and media sectors.
- Hybrid Solutions:Blended structures combining baseline membership with variable add-on credits. Corporate procurement teams favor these for budget flexibility across quarterly planning cycles.
- Custom Packages:Negotiated terms for large-scale deployments with branding, security, and IT integration requirements. Framework agreements spanning multiple cities characterize enterprise adoption.
Membership plans retain volume leadership; custom packages hold the steepest expansion curve as procurement centralization accelerates.
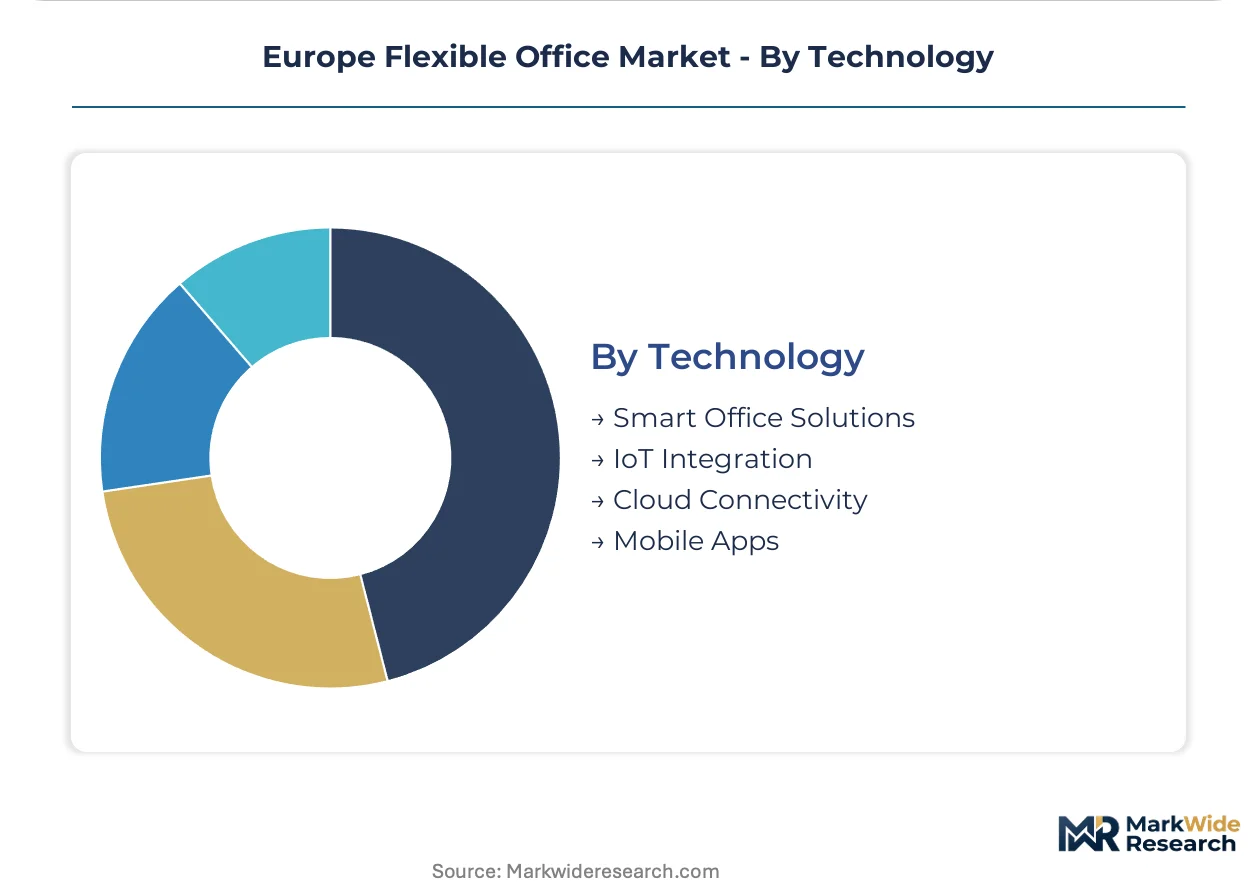
Technology:
Margin differentiation increasingly depends on infrastructure sophistication as ESG verification and operational efficiency become procurement gatekeepers.
- Smart Office Solutions:Occupancy sensors, air quality monitoring, and automated climate control systems. CSRD-mandated corporate tenants in Germany and France require verified environmental data for supplier qualification.
- IoT Integration:Connected devices enabling predictive maintenance and space utilization analytics. Facility management teams leverage these for portfolio optimization across distributed locations.
- Cloud Connectivity:Enterprise-grade network infrastructure with redundancy and security protocols. Financial services and healthcare-adjacent tenants demand compliance-grade connectivity.
- Mobile Apps:Booking platforms, access control, and community engagement tools. User experience quality directly influences retention in competitive urban markets.
Smart office solutions retain volume leadership; IoT integration holds the steepest expansion curve as building efficiency mandates tighten across EU member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flexible office inventory clusters in capital cities and financial centers where enterprise demand concentrates. Germany, the United Kingdom, and France absorb the majority of transaction volume. Secondary cities in Poland and Portugal exhibit supply gaps relative to employment growth.
Germany
Enterprise procurement teams in Frankfurt and Berlin drive demand for CSRD-compliant workspace with verified energy performance. The national transposition of the Energy Performance of Buildings Directive accelerates retrofit timelines for existing commercial stock. Munich and Hamburg operators are converting obsolete office buildings to flexible use under efficiency code incentives.
United Kingdom
London's legal and consulting sectors sustain premium pricing for serviced offices with confidentiality infrastructure. Facilities management teams integrate flexible office spend into portfolio optimization under tightening ESG disclosure requirements. The West End and City of London submarkets show the highest density of tech-enabled operators.
France
Paris-based multinationals require satellite locations for hybrid work mandates across Île-de-France. The EU Green Deal shapes refurbishment investment decisions for operators seeking corporate tenant qualification. Lyon and Marseille are attracting suburban penetration strategies as commute tolerance declines.
Poland
Warsaw and Krakow employment growth outpaces flexible office supply development. National building efficiency standards create conversion opportunities for obsolete commercial assets. Enterprise tenants from shared services and technology sectors are driving demand in emerging business districts.
Netherlands
Amsterdam's startup ecosystem sustains co-working velocity while enterprise demand shifts toward professionalized flexible solutions. CSRD reporting obligations compel verification of building sustainability credentials from workspace providers. Rotterdam and Utrecht are gaining traction for distributed satellite locations.
Europe Flexible Office Market Competitive Landscape
Concentration sits with established multi-brand operators holding leasehold portfolios across European capitals. The market structure tiers between global footprint holders, design-led premium specialists, and national partnership-based entrants. Strategic archetypes include scale-driven network builders, experience-differentiated boutique operators, and captive-development joint ventures. Dominant competitive moves involve portfolio consolidation through lease assignment and technology integration partnerships with building systems providers.
Within the scale-driven tier, International Workplace Group anchors physical presence through its Regus and Spaces brands across London, Paris, and Frankfurt. Mindspace exemplifies the design-led archetype with premium positioning in tier-one cities. Wojo occupies a partnership-based position through its captive access to new commercial developments. These operators represent divergent paths to tenant acquisition amid enterprise procurement centralization.
| Leading Market Players |
|---|
| Mindspace |
| International Workplace Group (IWG) |
| Regus Group Companies |
| Talent Garden |
| KNOTEL |
| WeWork |
| Wojo |
| Huckletree |
| The Office Group |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day fit-out cycles from lease signature to occupancy create working capital intensity that shapes operator pricing power and landlord concession negotiations across European flexible office markets. This lead-time band concentrates risk with development-stage operators while rewarding established players holding pre-negotiated leasehold pipelines in Germany, the United Kingdom, and France.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across European flexible office markets, separating CSRD-certified premium stock from uncertified commodity space. Three-tier pricing structure across premium, standard, and economy levels reflects building efficiency grades, with BREEAM Outstanding and LEED Platinum assets commanding substantial uplifts in London and Paris. Cost compression in standard-tier inventory is intensifying because energy cost volatility compresses margins on utility-inclusive contracts. Freelancers and early-stage ventures exhibit highest price sensitivity, while enterprise procurement teams prioritize sustainability verification over per-desk economics.
Supply Chain Analysis
Grade-A commercial asset availability in London, Paris, and Frankfurt acts as a chokepoint constraining operator expansion velocity and elevating leasehold acquisition costs. Supply concentration rests on these three core markets, with secondary cities in Poland and Portugal exhibiting structural undersupply relative to employment growth. Raw material dependencies include sustainable timber for biophilic fit-outs, low-carbon concrete for structural retrofits, and IoT sensor networks for smart building integration. Single-source vulnerability sits with specialized sustainability consultants required for CSRD compliance documentation. Distribution runs through landlord-operator direct lease negotiations, with limited secondary market for lease assignment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's flexible office market operates as a defensive-moat business where regulatory entrenchment through CSRD compliance creates switching costs that cement incumbent positions. Network effects from multi-location framework agreements compound this structural advantage.
For Market Incumbents: Secure leasehold pipelines in Warsaw and Lisbon before efficiency code renovations accelerate asset competition. Consolidate smaller operators in Berlin and Amsterdam through lease assignment to capture enterprise procurement centralization. Vertical integration into smart building technology partnerships defends margin position against undifferentiated commodity providers.
For New Entrants and Emerging Players: Lead with suburban satellite locations in Lyon and Manchester where enterprise hybrid work mandates outpace supply response. Target remote team segments requiring distributed collaboration points outside prime CBD rents. White-label CSRD compliance services to landlords as a go-to-market angle, converting property owners into captive development partners.
For Investors and Strategic Acquirers: Carve-out targets emerge from real estate private equity portfolios holding obsolete commercial stock in Germany and France. Long-term viability hinges on operators demonstrating enterprise client retention through renewal cycles and technology integration depth. Watch enterprise procurement team consolidation velocity as the inflection indicator for sector maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| CSRD Compliance Certification | Enterprise tenants under EU regulation mandate verified sustainability credentials for supplier qualification. |
| Smart Building Technology Integration | Occupancy analytics and climate control systems enable yield optimization and premium positioning in tier-one cities. |
| Suburban Location Expansion | Hybrid work normalization drives satellite demand beyond central business districts in secondary metropolitan areas. |
| Leasehold Portfolio Consolidation | Acquisition of distressed operators captures enterprise framework agreements and accelerates network density. |
| Landlord Partnership Structuring | Captive development agreements with Bouygues Immobilier-type partners secure pipeline access without capital deployment. |
Research Methodology
A standing panel of flexible office operators, corporate real estate directors, landlord asset managers, and sustainability consultants provided ongoing calibration across the study period. Primary interviews with facilities management teams at legal and consulting firms in London, Frankfurt, and Paris were cross-referenced against secondary validation from EU building efficiency directive transposition documents, national energy performance databases, and operator lease disclosure filings. Bottom-up location-level supply inventory was triangulated with top-down enterprise spending estimates across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs before finalization. Segmentation modeling incorporated product type, end user scale, service contract structure, and technology integration level across the projection horizon. CAGRs were derived from fitted trend extrapolation moderated by regulatory implementation timelines and employment growth forecasts. Industry-specific inputs included CSRD adoption curves by sector and national building code refurbishment schedules.
Forecasts assume regulatory continuity in EU Green Deal implementation and national Energy Performance of Buildings Directive transpositions; material policy shifts would require re-modeling. Energy cost volatility, interest rate trajectory, and enterprise return-to-office mandates constitute primary revision triggers. Revision becomes warranted when enterprise procurement centralization velocity crosses thresholds indicating sector consolidation acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
United States Office Real Estate Market
Office Real Estate
South Korea Office Real Estate Market
Office Real Estate
China Flexible Office Space Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
Saudi Arabia Flexible Office Space Market
Office Real Estate
Australia Co-Working Office Spaces Market
Office Real Estate
France Office Real Estate Market
Office Real Estate
Japan Office Real Estate Market
Office Real Estate
Asia Pacific Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Market
Office Real Estate
Canada Office Real Estate Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
China Office Real Estate Market
Office Real Estate
Qatar Co-Working Office Spaces Market
Office Real Estate
India Flexible Office Space Market