
 India Office Real Estate Market | 2026-2036
India Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
India Office Real Estate Market Foresight
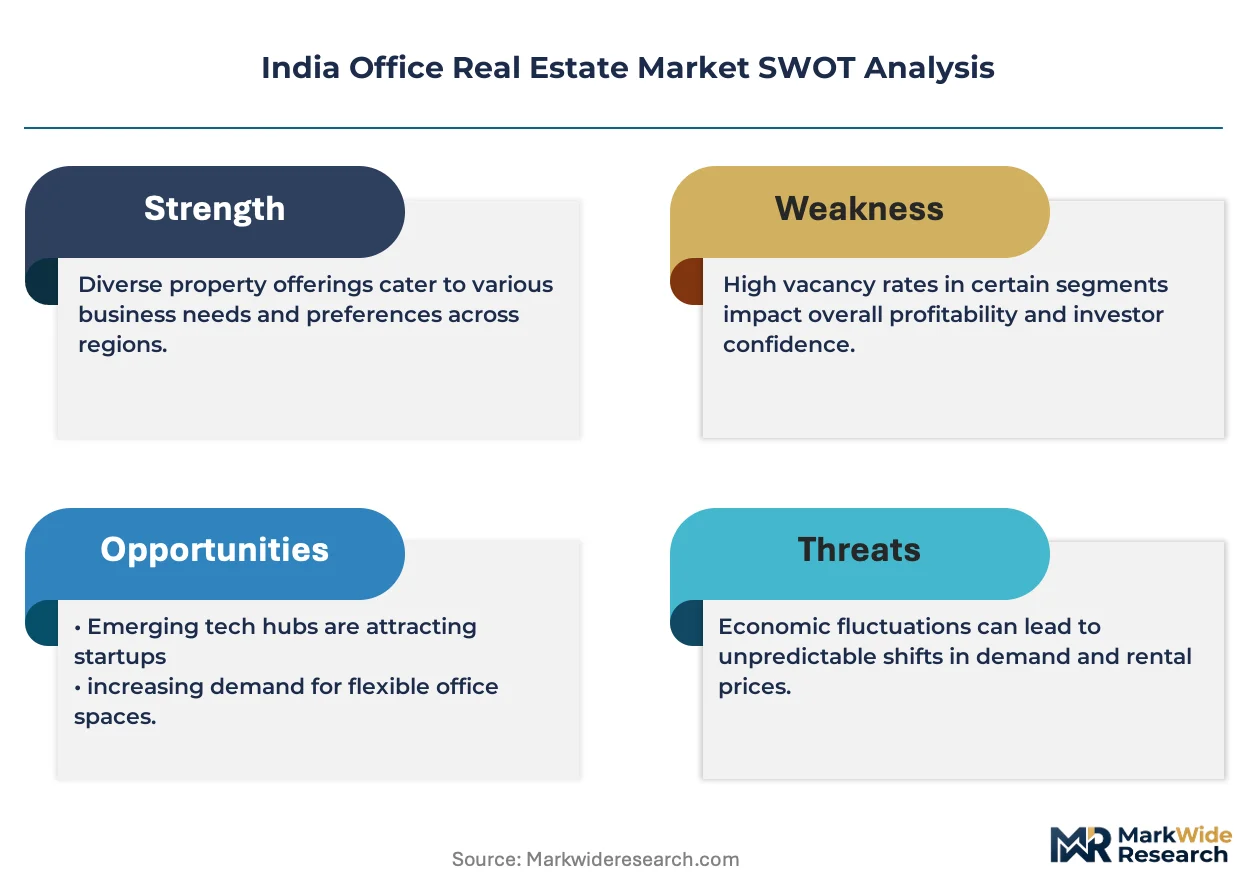
Flexible workspace seekers are reorganizing demand patterns across Indian metros, pulling lease volumes away from conventional long-term occupiers toward enterprise clients seeking agility. Embassy Office Parks REIT anchors premium Grade A supply across Bengaluru and Pune with institutional-quality assets. DLF Limited dominates the National Capital Region through integrated commercial developments with captive amenities. Mindspace Business Parks REIT sustains rental resilience via diversified tenant mixes weighted toward technology and banking clients.
India office real estate comprises purpose-built commercial structures designed for administrative, professional, and technology operations, typically engineered to specifications spanning floor loading capacity of 500-750 kg per square meter, power redundancy of 100 percent, and air handling systems delivering 12-15 air changes per hour to support dense workstation configurations. IT Parks command the deepest development pipelines as export-oriented technology services firms expand captive and third-party delivery centers, while Co-working Spaces attract the fastest absorption velocity among mid-market enterprises shedding fixed-cost liabilities. Traditional Offices retain the largest existing stock base but face structural vacancy pressure where aging infrastructure lacks modern specifications.
The Real Estate (Regulation and Development) Act mandates project registration, escrow account management, and timeline accountability, compressing delivery risk premiums and redirecting institutional capital toward compliant developers. State RERA authorities in Maharashtra, Karnataka, and Telangana enforce graded penalties for disclosure lapses, tightening market access for speculative or undercapitalized sponsors. BIS standards for structural safety and fire suppression systems shape construction specifications and retrofit obligations across existing inventory. Stakeholders must monitor evolving municipal development plan amendments and transit-oriented zoning incentives that will redistribute absorption potential across emerging micro-markets.
Market Dynamics
Flexible workspace arrangements are restructuring tenant-landlord power dynamics across Indian metros, compressing average lease tenures and forcing asset owners to reconfigure operating models around enterprise-grade service delivery.
Growth Catalysts
- PLI scheme incentives:Electronics and IT hardware manufacturers are expanding captive office footprints in Chennai and Hyderabad to access production-linked subsidies.
- SEBI REIT regulations:Institutional capital deployment into income-yielding commercial assets accelerates as regulatory frameworks mature for public-market vehicles.
- Technology sector leasing:Global capability centers and GCCs drive absorption of Grade A stock with specialized infrastructure requirements for 24/7 operations.
Market Restraints
- Land aggregation friction:Fragmented land titles and litigation risk in Maharashtra and Karnataka extend pre-construction timelines.
- Construction input volatility:Steel and cement price fluctuations compress development margins on speculative office projects.
- Secondary stock obsolescence:Aging buildings lacking modern power redundancy face structural vacancy pressure against new Grade A supply.
Strategic Opportunities
- Tier-II city expansion:Kochi, Indore, and Chandigarh present underpenetrated demand from IT services firms seeking cost arbitrage.
- Transit-oriented development:Metro rail extensions in Bengaluru and Hyderabad unlock micro-market premiums around station catchments.
- Green building mandates:BIS energy efficiency standards and state-level environmental clearances create differentiation for certified assets.
Industry Challenges
- Specialized asset management talent:REIT-grade property management and investor relations capabilities remain scarce outside Mumbai and Delhi NCR.
- Legacy system integration:Older buildings require capital-intensive retrofitting to meet contemporary air handling and fiber connectivity specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Office Real Estate Market |
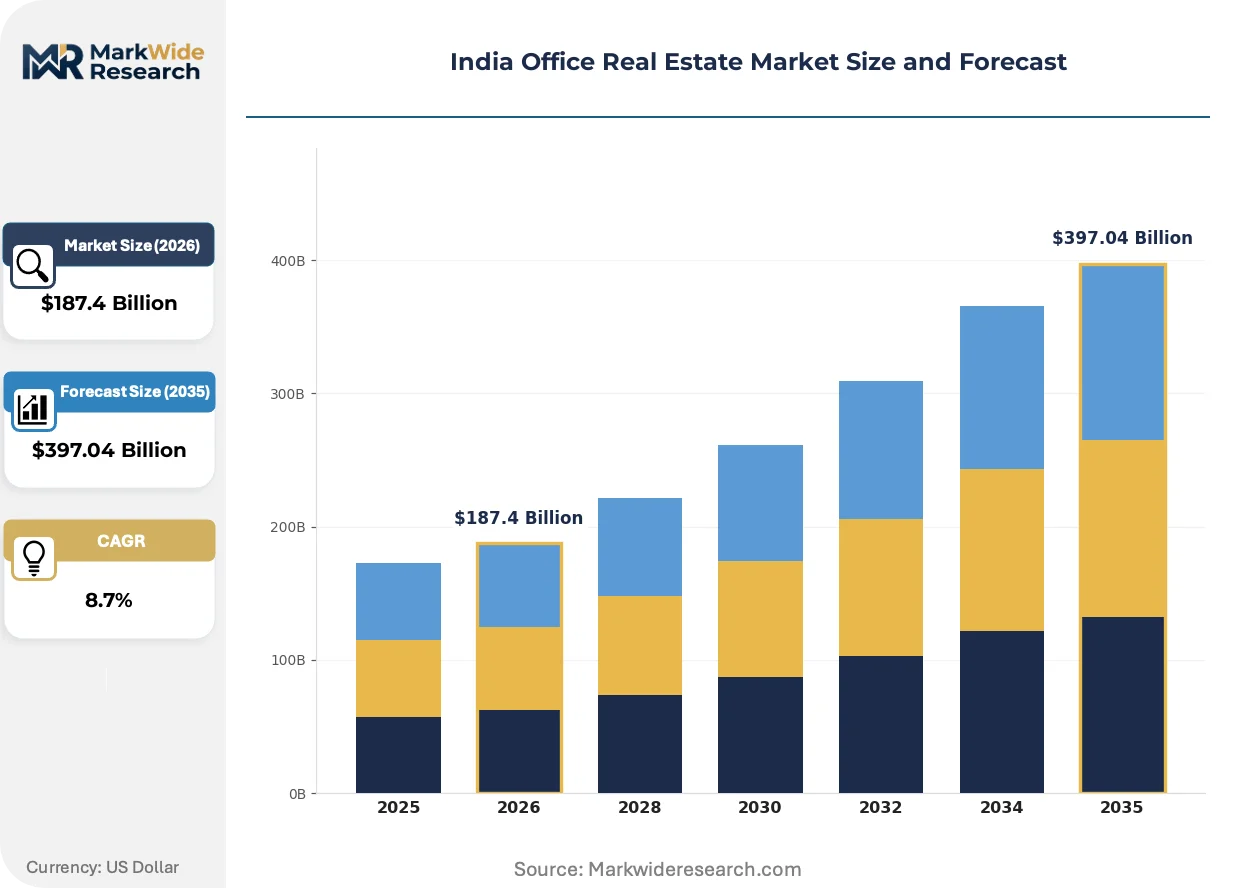
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Co-working Spaces, IT Parks, Business Centers, Traditional Offices End User: Corporates, Startups, Freelancers, Government Agencies Lease Type: Long-term Lease, Short-term Lease, Rental Agreements, Flexible Leasing Floor Space: Small Offices, Medium Offices, Large Offices, Enterprise Suites |
| Companies Covered | Mindspace Business Parks REIT, RMZ Corp, DLF Limited, Brigade Group, Godrej Properties, Embassy Office Parks REIT, Prestige Estates Projects, Panchshil Realty, Brookfield India REIT, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Office Real Estate Market Shifts & Advancements
Technology-enabled space utilization and regulatory pressure on energy performance are converging to redefine how office assets are designed, operated, and monetized across Indian commercial corridors.
Smart building management systems are decomposing traditional facilities management contracts by enabling real-time monitoring of occupancy patterns, HVAC efficiency, and predictive maintenance. Large enterprise occupiers in Bengaluru and Hyderabad are mandating these platforms in new leases. The technology is compressing operating cost structures and shifting landlord value propositions from rent per square foot to service-level guarantees.
RERA mandates across Maharashtra, Karnataka, and Telangana now require project registration, escrow account segregation, and timeline accountability before marketing launch. Developers face graded penalties for disclosure lapses, tightening market access for undercapitalized sponsors. Institutional capital is redirecting toward compliant sponsors with established track records in transparent delivery.
Occupiers are consolidating vendor relationships through integrated facility service contracts that bundle property management, IT infrastructure, and flexible space provisioning. Traditional single-service providers face displacement by platforms offering enterprise-grade agility. This pattern is most visible among technology and financial services firms in the Mumbai Metropolitan Region.
India Office Real Estate Market Segmentation
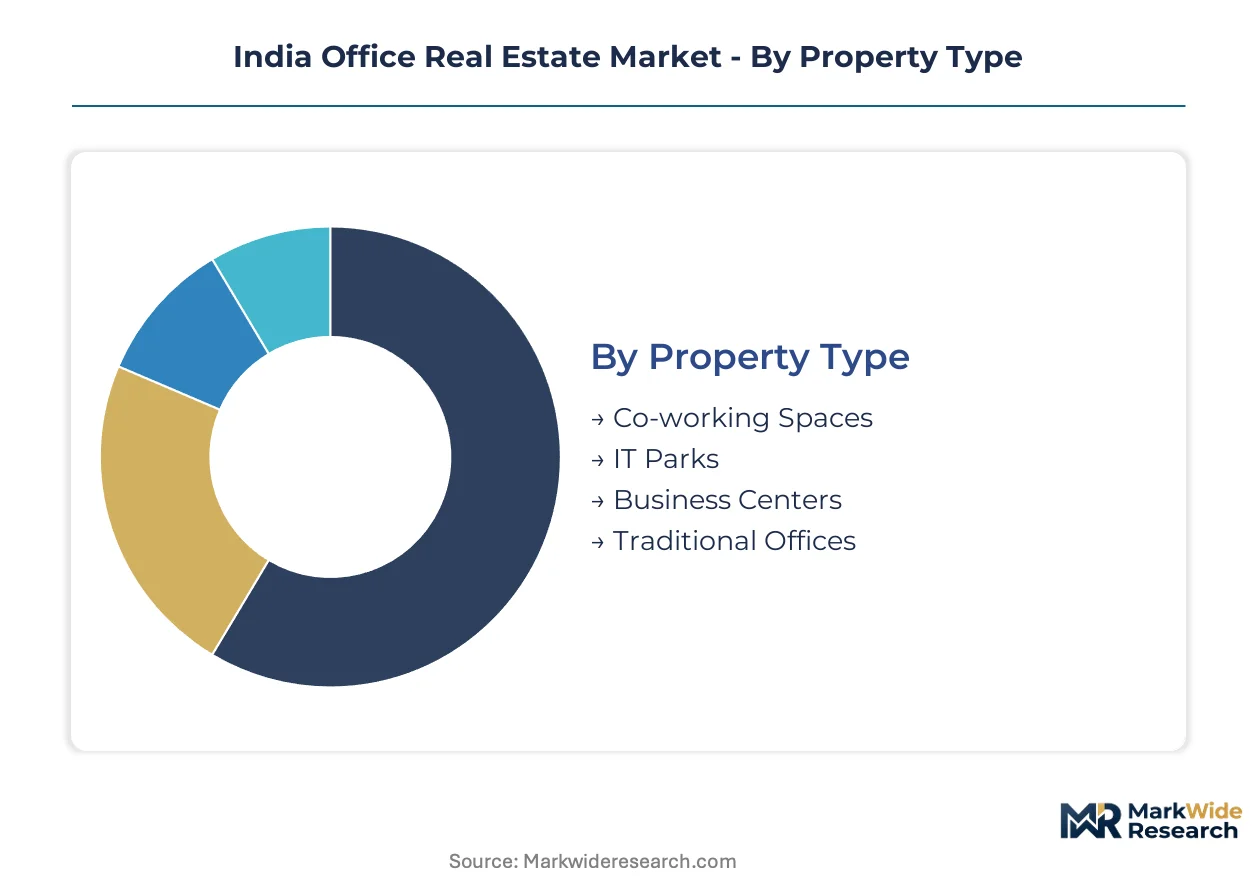
Segmentation in Indian office real estate reveals divergent capital intensity, lease economics, and regulatory exposure across property configurations. Understanding these divisions enables stakeholders to match development strategies with specific demand pockets and tenant risk profiles.
Property Type:
IT Parks anchor export-led absorption from technology services firms, while Co-working Spaces and Traditional Offices serve predominantly domestic occupiers with varying cost sensitivities.
- IT Parks:Purpose-built campuses with 100 percent power redundancy and 12-15 air changes per hour serve global capability centers in Bengaluru and Hyderabad. PLI scheme incentives for electronics manufacturing are expanding captive footprints in Chennai.
- Co-working Spaces:Flexible-fit environments with shared amenities attract mid-market enterprises shedding fixed-cost liabilities. Enterprise clients in Mumbai Metropolitan Region now drive absorption velocity ahead of individual freelancers.
- Business Centers:Serviced environments with bundled reception and IT support target professional services firms requiring immediate occupancy without capital expenditure.
- Traditional Offices:Conventional long-lease structures with dedicated facilities dominate legacy stock but face structural vacancy pressure where aging infrastructure lacks modern specifications.
Traditional Offices command the established base. The steepest expansion runs through Co-working Spaces.
End User:
Corporates concentrate demand in Grade A developments with institutional capital backing, whereas Startups and Freelancers fragment across flexible and secondary stock with shorter commitment horizons.
- Corporates:Multinational technology and financial services firms mandate smart building systems and enterprise-grade service levels in Bengaluru and Hyderabad leases. Embassy Office Parks REIT and Mindspace Business Parks REIT anchor this tenant class.
- Startups:Venture-backed enterprises prioritize agility over prestige, absorbing fitted space in emerging micro-markets around metro rail extensions. Cost arbitrage drives interest toward Tier-II cities.
- Freelancers:Individual professionals generate spot demand for hot-desking arrangements, though enterprise clients increasingly displace this segment in co-working operator revenue mixes.
- Government Agencies:Public sector tenants occupy dedicated administrative buildings with BIS compliance requirements, typically through long-term rental agreements with state-level authorities.
Corporates dominate value-weighted absorption. Startups are gaining share fastest among emerging supply.
Lease Type:
Long-term structures align with institutional asset management models, while Flexible Leasing and Short-term arrangements respond to occupier demands for balance sheet agility.
- Flexible Leasing:Enterprise-grade contracts with 3-12 month terms and expansion options enable technology firms to scale headcount without capital commitment. SEBI REIT regulations favor landlords with diversified lease maturity profiles.
- Long-term Lease:5-9 year commitments with structured escalations anchor income stability for REIT-grade assets. DLF Limited leverages this structure across National Capital Region integrated developments.
- Short-term Lease:Interim arrangements bridge project timelines or transitional requirements, commanding rental premiums that reflect higher vacancy risk and turnover costs.
- Rental Agreements:Conventional monthly or annual structures persist in secondary stock and government-occupied premises with limited institutional ownership.
Long-term Lease structures anchor the revenue base. Flexible Leasing shows the steepest trajectory as enterprise adoption accelerates.
Floor Space:
Large Offices and Enterprise Suites concentrate in prime micro-markets with transit access, while Small Offices distribute across peripheral locations with lower rental thresholds.
- Enterprise Suites:Integrated floorplates exceeding 100,000 square feet accommodate global capability centers with 24/7 operations and dense workstation configurations. Demand clusters in Hyderabad's HITEC City and Bengaluru's Outer Ring Road corridor.
- Large Offices:50,000-100,000 square foot configurations serve established technology services firms with moderate expansion requirements. RERA-compliant developers capture this segment through pre-commitment strategies.
- Medium Offices:10,000-50,000 square foot spaces attract domestic corporates and professional services firms with stable headcount projections.
- Small Offices:Sub-10,000 square foot configurations serve regional headquarters, consulting practices, and back-office functions in Tier-II cities including Indore and Chandigarh.
Large Offices represent the volume core. Enterprise Suites are climbing the fastest as GCC expansion concentrates demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grade A supply concentrates in southern and western corridors where technology services firms anchor absorption. State-level infrastructure investments and RERA compliance frameworks redistribute competitive advantage across metropolitan clusters.
Maharashtra
Financial services and fintech occupiers drive demand in Mumbai Metropolitan Region. The Maharashtra RERA enforces graded disclosure penalties, compressing delivery timelines for compliant developers. Navi Mumbai and Thane corridor capture overflow demand as transit infrastructure expands.
Karnataka
Global capability centers from technology and banking sectors absorb premium stock in Bengaluru. BIS energy efficiency standards mandate retrofit specifications for existing inventory. Whitefield and Outer Ring Road micro-markets sustain pre-commitment velocity ahead of construction completion.
Telangana
Export-oriented IT services and electronics manufacturing firms expand captive footprints in Hyderabad. PLI scheme incentives for IT hardware accelerate land aggregation in HITEC City and Gachibowli. Telangana RERA registration requirements redirect institutional capital toward established sponsors.
Tamil Nadu
Automotive and electronics manufacturing spillover generates administrative office demand in Chennai. State-level environmental clearances shape green building mandates for new Grade A developments. OMR and Guindy industrial corridors attract technology services firms seeking cost arbitrage against Bengaluru.
Delhi-NCR
Government agencies and professional services firms occupy dedicated administrative buildings across the National Capital Region. RERA-compliant developers capture corporate demand through integrated commercial developments with captive amenities. Gurugram and Noida expressway corridors concentrate new supply absorption.
India Office Real Estate Market Competitive Landscape
Concentration sits with institutional-grade REITs and integrated developers controlling prime Grade A inventory. Three archetypes dominate: REIT-grade platform operators with diversified tenant mixes, diversified real estate conglomerates with captive land banks, and specialized office developers with technology sector relationships. Competitive dynamics center on portfolio diversification into Tier-II cities and backward integration into facility management capabilities.
Among REIT-structured operators, Embassy Office Parks REIT and Mindspace Business Parks REIT exemplify the institutional platform archetype with Bengaluru and Hyderabad concentration. DLF Limited anchors the integrated developer tier through National Capital Region commercial developments. Brigade Group and Prestige Estates Projects represent southern India specialists with Karnataka and Tamil Nadu footprint density. RMZ Corp occupies a position among private office-focused developers with technology sector tenant relationships.
| Leading Market Players |
|---|
| Mindspace Business Parks REIT |
| RMZ Corp |
| DLF Limited |
| Brigade Group |
| Godrej Properties |
| Embassy Office Parks REIT |
| Prestige Estates Projects |
| Panchshil Realty |
| Brookfield India REIT |
| Others |
Supply & Pricing Matrix
Long-term lease commitments with structured escalation clauses lock in rental visibility for Grade A landlords while securing supply access for technology and financial services occupiers across Bengaluru, Hyderabad, and Mumbai Metropolitan Region. These contract structures compress tenant bargaining power during absorption cycles and anchor institutional capital deployment into income-yielding commercial assets.
Pricing Analysis
Volume-discount tiering structures separate Enterprise Suites exceeding 100,000 square feet from Medium Offices and Small Offices through rental escalations and fit-out contribution schedules. Price differentiation hinges on BIS energy efficiency certification levels and captive amenity bundling including power redundancy and fiber connectivity specifications. Cost compression in secondary stock intensifies as aging buildings lacking modern air handling systems face structural vacancy pressure against new Grade A supply. Startups and venture-backed enterprises exhibit highest price sensitivity, while multinational corporates with global capability center mandates accept premium positioning for operational continuity guarantees.
Supply Chain Analysis
Inbound logistics costs from steel and cement supply volatility through Jawaharlal Nehru Port and Chennai Port congestion compress development margins on speculative office projects in Maharashtra and Karnataka. Construction material supply concentrates in China, India, and Southeast Asian manufacturing hubs, with finished glass curtain wall systems and HVAC equipment drawing from specialized fabrication centers. Steel reinforcement bars, cement, and aluminum composite panels constitute critical input dependencies. Single-source vulnerability from concentrated HVAC equipment suppliers elevates project delay risk. Distribution runs through RERA-registered developers with established track records in transparent delivery, redirecting institutional capital away from speculative sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated facility service contracts represent a service-attach opportunity expanding faster than base rental income, as occupiers consolidate vendor relationships around enterprise-grade agility spanning property management, IT infrastructure, and flexible space provisioning.
For Market Incumbents: Fortify portfolio resilience through backward integration into captive facility management capabilities and diversified lease maturity profiles under SEBI REIT regulations. Co-working operators with enterprise client concentration threaten traditional landlord pricing power. Capacity addition in Tier-II cities including Kochi, Indore, and Chandigarh captures cost-arbitrage demand from technology services firms.
For New Entrants and Emerging Players: Differentiate on transit-oriented micro-market positioning around metro rail extensions in Bengaluru and Hyderabad station catchments. Underpenetrated demand from IT services firms in Chandigarh and Indore presents accessible white-space. Green building certification under BIS energy efficiency standards offers a go-to-market angle for institutional capital attraction.
For Investors and Strategic Acquirers: Specialized office developers with technology sector tenant relationships and RERA-compliant delivery track records offer acquisition exposure to income-yielding commercial assets. Long-term viability rests on portfolio diversification into Tier-II cities and backward integration into facility management capabilities. Watch PLI scheme incentive disbursement velocity for electronics and IT hardware manufacturing as an inflection indicator for Chennai and Hyderabad captive office footprint expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| REIT Platform Expansion | SEBI regulatory maturation accelerates institutional capital deployment into income-yielding commercial assets. |
| Green Certification Program | BIS energy efficiency standards create rental differentiation for compliant Grade A developments. |
| Transit-Oriented Development | Metro rail extensions in Bengaluru and Hyderabad unlock micro-market premiums around station catchments. |
| Integrated Facility Services | Enterprise occupiers consolidate vendor relationships around bundled property management and IT infrastructure contracts. |
| Tier-II City Geographic Expansion | Technology services firms seeking cost arbitrage drive absorption velocity in Kochi, Indore, and Chandigarh. |
Research Methodology
Operator-level perspectives from asset managers at REIT-grade platforms, leasing directors at integrated developers, tenant representation brokers, and facilities management executives anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from SEBI REIT disclosure filings, state RERA authority registration databases, municipal development plan amendments, and BIS construction standard documentation. Bottom-up project pipeline assessments and top-down macroeconomic absorption modeling provided triangulation across data sources.
Sensitivity analysis around PLI scheme incentive disbursement schedules, construction input price volatility scenarios, and lease tenure compression patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled include property type, end user category, lease structure, and floor space configuration alongside regional regulatory cluster differentiation. CAGRs derived from absorption velocity trends, pre-commitment ratios, and rental escalation schedules. Forecast inputs incorporated technology sector headcount expansion plans and GCC establishment timelines.
The analysis sits within stated boundaries; outcomes outside sustained institutional capital inflows, RERA compliance enforcement continuity, or technology services export demand stability would require recalibration. Forecasts reflect documented assumptions regarding infrastructure completion schedules and regulatory implementation timelines. Specific risk factors include land aggregation litigation delays, steel and cement price volatility, and secondary stock obsolescence acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
United States Office Real Estate Market
Office Real Estate
United Kingdom Co-Working Office Spaces Market
Office Real Estate
Bahrain Flexible Office Space Market
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
South Korea Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
Europe Flexible Office Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Brokerage Market
Office Real Estate
Asia Pacific Flexible Office Market
Office Real Estate
Italy Office Real Estate Market
Office Real Estate
North America Flexible Office Market
Office Real Estate
China Co Working Office Space Market